
 Survival Tools Market | 2026-2036
Survival Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Survival Tools Market Outlook
Aftermarket blade sharpening and component refurbishment is rewriting margin capture across the survival tools value chain. Leatherman Tool Group, Inc. anchors North American distribution through its direct-to-consumer platform and authorized service center network. SOG Specialty Knives & Tools, Inc. competes in military and law enforcement channels with fixed-blade specialization and government contract eligibility. Fenix Outdoors International AG extends European retail reach through its portfolio of outdoor brands and multi-channel merchandising.
Survival tools encompass handheld instruments engineered for emergency sustenance, shelter construction, and self-rescue operations, typically manufactured from hardened stainless steel with Rockwell hardness ratings between 54 and 58 HRC for edge retention under field stress. Multi-tools command the largest product-type revenue pool due to their functional density and civilian portability, while first aid kits represent the fastest-growing segment as households and municipalities expand emergency stockpiles. Water purification tools carry premium pricing in the emergency preparedness application channel, where certification against EPA standards determines procurement eligibility.
FDA regulations govern antimicrobial claims on first aid components, while FCC standards apply to electronic signaling devices such as emergency beacons and two-way radios integrated into survival kits. The Consumer Product Safety Commission enforces blade-locking mechanism requirements to prevent accidental closure injuries. Stakeholders must monitor evolving state-level emergency preparedness mandates and federal disaster-response funding allocations that directly shape institutional purchasing volumes.
Market Dynamics
Military procurement standardization across NATO member states is compressing supplier qualification timelines while civilian preparedness mandates from FEMA reshape institutional purchasing specifications. This dual-channel pressure favors manufacturers with dual-use certification capabilities.
Growth Catalysts
- NATO Standardization Agreement 4370:Common technical specifications for tactical multi-tools accelerate cross-border military procurement and reduce supplier requalification costs for certified vendors.
- FEMA Community Preparedness Grants:Federal funding streams to municipal emergency management agencies institutionalize survival tool stockpiling requirements for disaster response units.
- Sheffield Stainless Innovation Corridor:Concentrated metallurgy R&D in South Yorkshire advances powder metallurgy blade steels with superior edge retention under field stress conditions.
Market Restraints
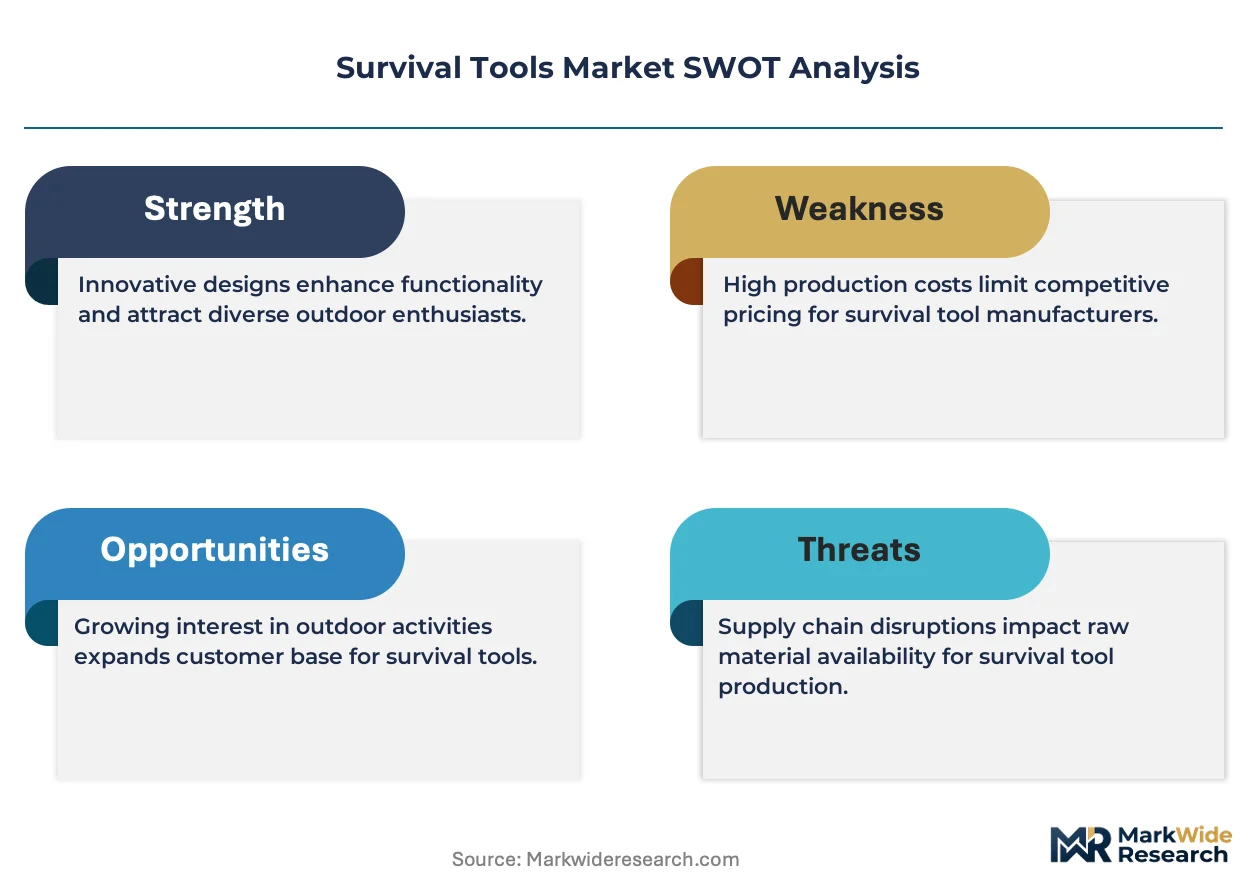
- Nickel Price Volatility:Austenitic stainless steel formulations depend on nickel alloying, exposing manufacturers to London Metal Exchange price swings that compress margin predictability.
- Solingen Blade Cluster Dependency:Premium fixed-blade production concentrates in a single German city, creating geographic supply risk without qualified secondary forging capacity.
- FCC Equipment Authorization Delays:Emergency beacon integration into survival kits faces 12-18 month certification timelines that stall product launch cycles.
Strategic Opportunities
- Underpenetrated Nordic Municipalities:Sweden and Finland maintain limited civilian emergency stockpiling compared to US preparedness culture, presenting whitespace for institutional sales development.
- EU Critical Raw Materials Act:Strategic autonomy mandates incentivize domestic European production of hardened tool steels previously sourced from third-country suppliers.
- Direct-to-Consumer Service Integration:Blade refurbishment subscriptions and component upgrade programs capture recurring revenue from existing installed base without new customer acquisition cost.
Industry Challenges
- Rockwell Hardness Calibration Expertise:Qualified metallurgists capable of certifying 54-58 HRC blade specifications remain scarce in North American manufacturing regions outside traditional cutlery centers.
- Multi-Regulatory Convergence:Survival kits containing first aid, electronics, and edged tools simultaneously trigger FDA, FCC, and CPSC jurisdiction, multiplying compliance documentation requirements.
- Legacy Distribution Inventory Reconfiguration:Big-box outdoor retailers carry obsolete SKUs requiring markdown clearance before shelf reset for modular, upgradeable tool systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Survival Tools Market |
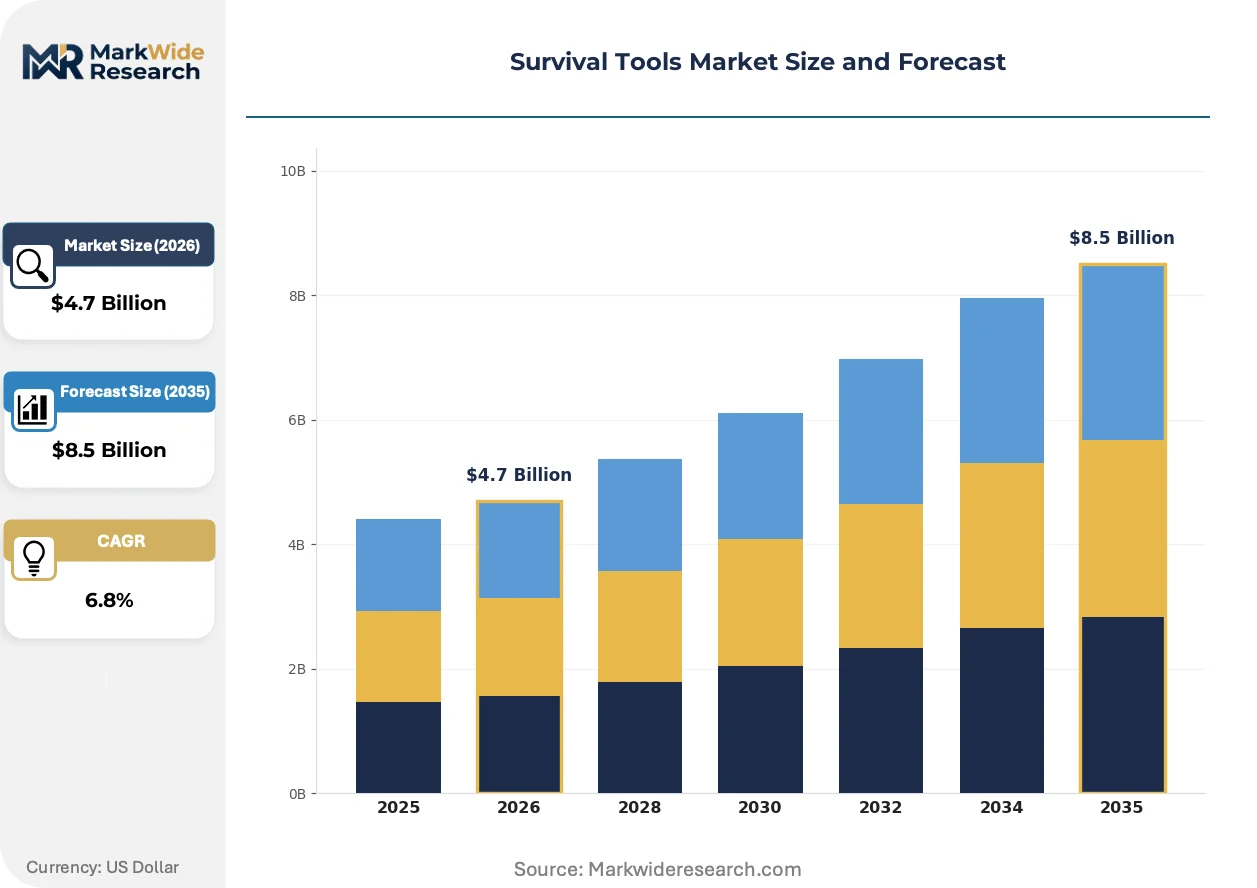
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-tools, Fire Starters, First Aid Kits, Water Purification Application: Outdoor Activities, Emergency Preparedness, Camping, Hunting End User: Individuals, Military Personnel, Outdoor Enthusiasts, Emergency Services Material: Stainless Steel, Aluminum, Plastic, Fabric |
| Companies Covered | Leatherman Tool Group, Inc., SOG Specialty Knives & Tools, Inc., The Coleman Company, Inc., Fiskars Group, Tender Corporation, UST Brands, Surefire, LLC, Exxel Outdoors, LLC, Fenix Outdoors International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Survival Tools Market Strategic Shifts
Digital integration is penetrating mechanical tool categories, compressing the traditional separation between analog reliability and connected functionality. Three distinct vectors now reshape product architecture and go-to-market approaches.
Modular blade architecture with standardized attachment interfaces is virtualizing the traditional fixed-blade versus folding-blade dichotomy. Special operations units now deploy mission-configurable cutting systems with swappable blade profiles. This platform approach reduces inventory burden while enabling rapid field adaptation without complete tool replacement.
REACH Annex XVII restrictions on chromium(VI) compounds in surface treatment processes force manufacturers to adopt trivalent chromium or plasma electrolytic oxidation finishes. European producers in Solingen and Sheffield face 2026 compliance deadlines for existing product lines. The transition elevates capital requirements for smaller forges while creating specification divergence between EU and non-EU product variants.
Subscription-based preparedness provisioning is displacing one-time retail purchases among affluent coastal households. Curated quarterly kits with rotating water purification, signaling, and shelter components build recurring revenue relationships. This model concentrates in California and Washington state municipalities with active earthquake preparedness programming.
Survival Tools Market Segmentation
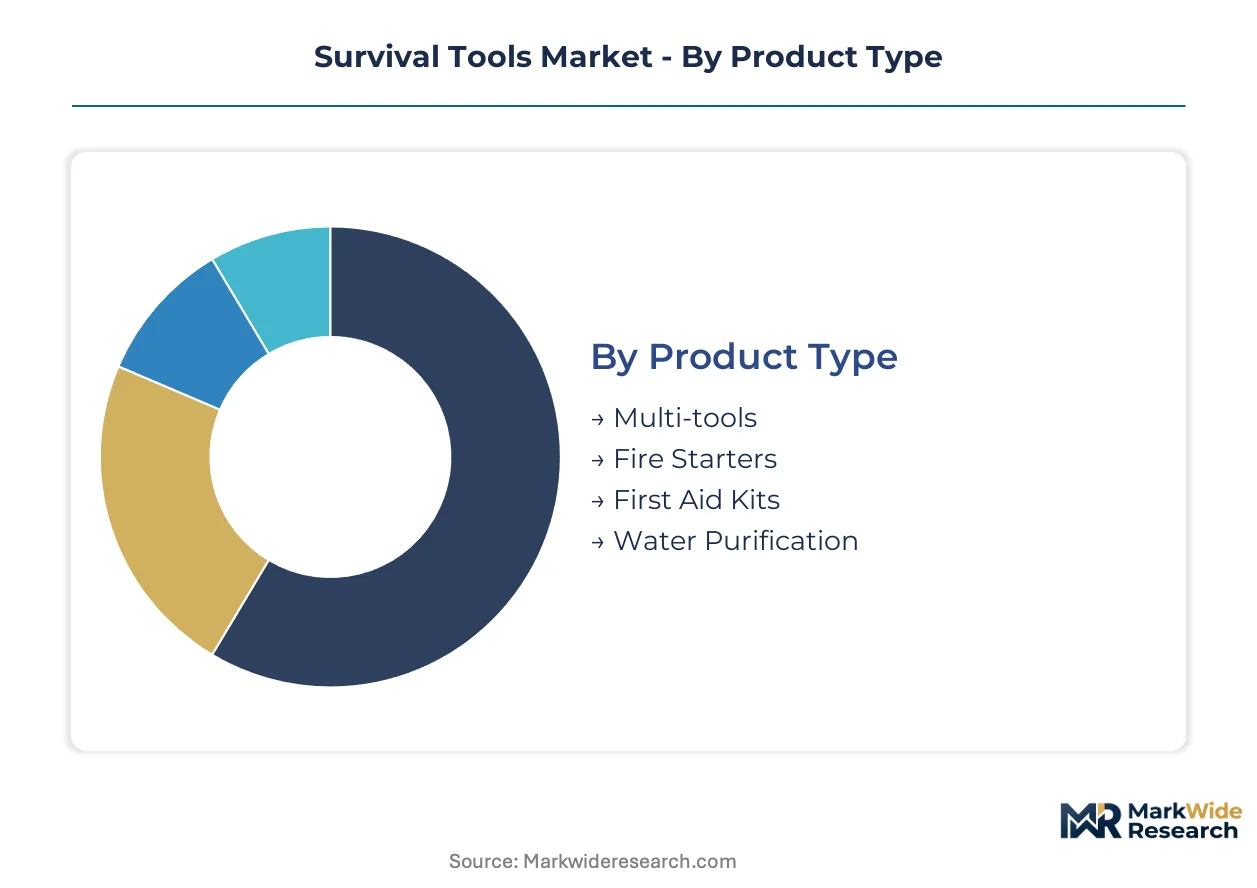
Survival tools manufacturers configure production lines around distinct performance specifications and procurement channels. Segmentation reveals where military-grade metallurgy diverges from consumer-grade portability, and where institutional purchasing concentrates versus dispersed retail demand.
Product Type:
Cost tier determines manufacturing complexity and margin structure across the four product categories.
- Multi-tools:Functional density drives premium positioning through integrated pliers, blades, and drivers in hardened stainless steel housings. NATO standardization agreements and FEMA municipal grants concentrate institutional procurement in the United States Pacific Northwest and across German federal states.
- First Aid Kits:FDA antimicrobial claims compliance elevates component costs while EPA certification requirements for water purification add-ons expand kit complexity. Household emergency stockpiling in California and Washington municipalities accelerates segment expansion.
- Fire Starters:Ferrocerium rod and magnesium block configurations serve military field-ready specifications.
- Water Purification:Ceramic filter and UV-C systems carry certification-dependent pricing in emergency preparedness channels.
Multi-tools holds installed capacity. First Aid Kits is rotating up the share rankings.
Application:
End-use context shapes durability requirements and regulatory exposure for each application channel.
- Emergency Preparedness:Federal disaster-response funding allocations and FEMA Community Preparedness Grants institutionalize municipal stockpiling requirements. Certification against multiple standards—FDA for medical components, FCC for signaling devices, CPSC for blade-locking mechanisms—multiplies compliance documentation.
- Outdoor Activities:Recreational portability demands balance weight constraints against Rockwell hardness ratings between 54 and 58 HRC. Sheffield stainless innovations and Solingen forging traditions anchor supply for serious enthusiasts.
- Camping:Weekend-use durability tolerates lower-specification alloys and polymer handles.
- Hunting:Fixed-blade field dressing tools require blood-groove engineering and corrosion-resistant finishes.
Emergency Preparedness captures institutional volume. Outdoor Activities maintains the broadest geographic footprint.
End User:
Customer type governs procurement volume scale and contract structure variability.
- Military Personnel:NATO Standardization Agreement 4370 compresses supplier qualification timelines for tactical multi-tools and fire starters. Dual-use certification capabilities favor manufacturers with existing government contract eligibility.
- Emergency Services:Municipal and county-level disaster response units standardize on modular, upgradeable tool systems with component refurbishment protocols.
- Individuals:Subscription-based preparedness provisioning displaces one-time retail purchases among affluent coastal households in earthquake-prone municipalities.
- Outdoor Enthusiasts:Direct-to-consumer platforms and authorized service center networks capture aftermarket blade sharpening revenue.
Military Personnel commands the largest contract values. Emergency Services is gaining share fastest through federal funding channelization.
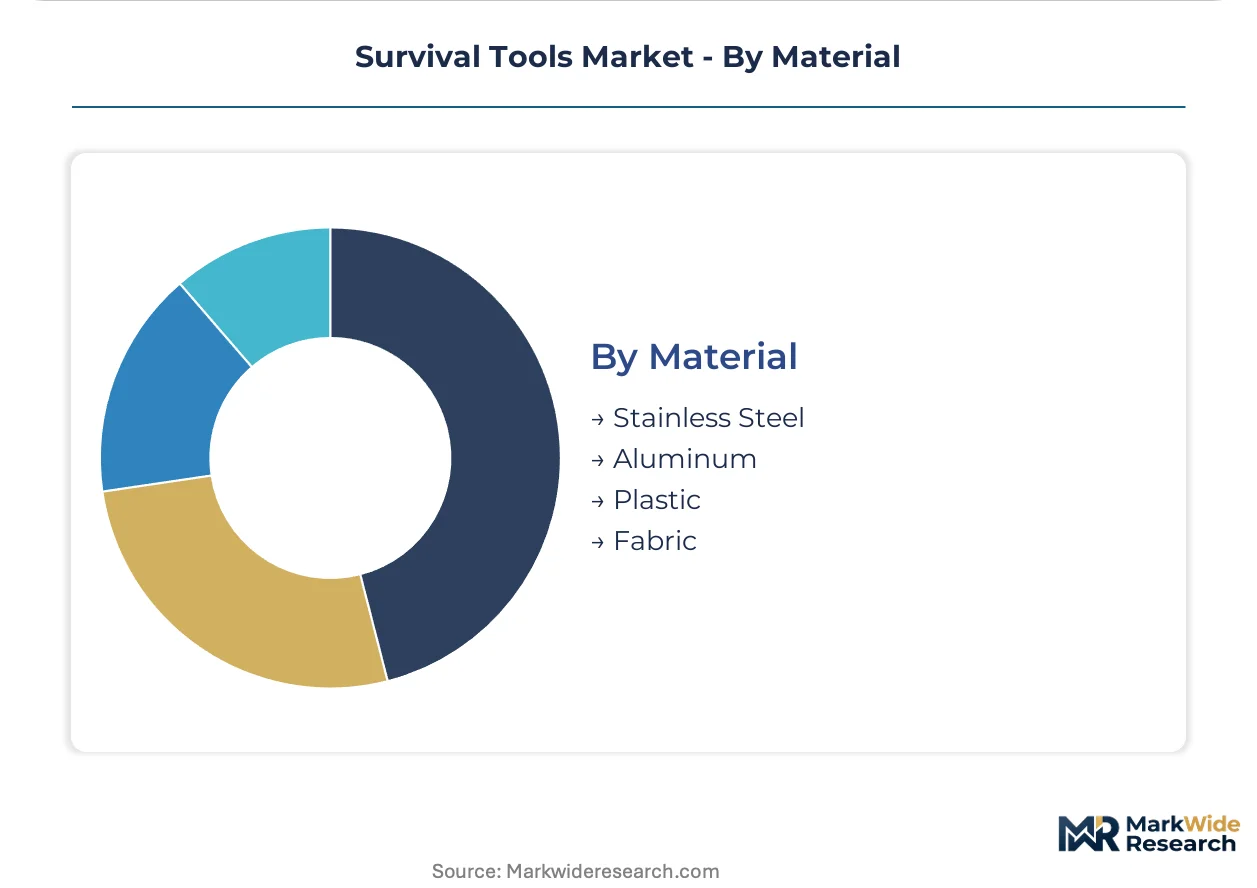
Material:
Supply concentration and regulatory exposure differentiate material selection across price-performance tiers.
- Stainless Steel:Austenitic formulations with nickel alloying dominate blade production despite London Metal Exchange price volatility. REACH Annex XVII chromium(VI) restrictions force trivalent chromium or plasma electrolytic oxidation finish transitions for European producers.
- Aluminum:Lightweight handle and housing applications serve portability-focused consumer segments.
- Plastic:Polymer components reduce unit costs in entry-level multi-tools and first aid kit casings.
- Fabric:Cordura and ballistic nylon construct sheath and carrying systems with MOLLE compatibility for tactical mounting.
Stainless Steel holds installed capacity. Fabric is rotating up the share rankings through modular platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Municipal procurement in the United States Pacific Northwest absorbs premium multi-tool pricing through FEMA grant channelization. German military buyers prioritize Rockwell hardness certification over unit cost. Nordic civilian markets remain underpenetrated with household preparedness rates below North American benchmarks.
United States
FEMA Community Preparedness Grants institutionalize municipal stockpiling requirements across Oregon and Washington state disaster response units. The Consumer Product Safety Commission enforces blade-locking mechanism standards that filter import eligibility. Sheffield stainless innovations from UK suppliers penetrate Pacific Northwest distribution through Portland-based outdoor retail networks.
Germany
NATO Standardization Agreement 4370 compresses supplier qualification timelines for tactical multi-tools across Bundeswehr procurement channels. REACH Annex XVII chromium(VI) restrictions force Solingen forges toward trivalent chromium finishes by 2026 compliance deadlines. The Solingen blade cluster maintains premium fixed-blade production concentration without qualified secondary forging capacity elsewhere in Europe.
United Kingdom
Sheffield's powder metallurgy R&D corridor advances austenitic stainless formulations with superior edge retention for military field stress conditions. British Ministry of Defence procurement aligns with NATO technical specifications for tactical cutting systems. South Yorkshire metallurgy centers export blade steel innovations to North American and European OEMs under dual-use certification protocols.
Sweden
Limited civilian emergency stockpiling culture creates whitespace for institutional sales development compared to US preparedness benchmarks. EU Critical Raw Materials Act strategic autonomy mandates incentivize domestic hardened tool steel production previously sourced from third-country suppliers. Stockholm and Gothenburg municipalities pilot subscription-based preparedness provisioning models adapted from California earthquake programming.
Canada
Provincial emergency management agencies standardize on modular, upgradeable tool systems with component refurbishment protocols. Health Canada regulates antimicrobial claims on first aid kit components parallel to FDA jurisdiction in adjacent US markets. British Columbia's outdoor retail density mirrors Pacific Northwest civilian preparedness culture with federal emergency management directive alignment.
Survival Tools Market Competitive Environment
Capability concentration sits with metallurgy-certified forges; scale advantage sits with multi-channel distributors with direct-to-consumer platforms. The vendor base stratifies across three tiers: NATO-certified military suppliers, FEMA-eligible institutional vendors, and recreational retail brands. Two strategic archetypes dominate: dual-use manufacturers with government contract eligibility and subscription-based preparedness provisioning services. Competitive moves concentrate on authorized service center network expansion and blade refurbishment subscription capture.
Among North American tool manufacturers, Leatherman Tool Group, Inc. and SOG Specialty Knives & Tools, Inc. exemplify the dual-use certification archetype. Fenix Outdoors International AG represents European multi-channel distribution scale. These three occupy positions spanning military procurement eligibility, municipal institutional sales, and direct-to-consumer aftermarket service integration.
| Leading Market Players |
|---|
| Leatherman Tool Group, Inc. |
| SOG Specialty Knives & Tools, Inc. |
| The Coleman Company, Inc. |
| Fiskars Group |
| Tender Corporation |
| UST Brands |
| Surefire, LLC |
| Exxel Outdoors, LLC |
| Fenix Outdoors International AG |
| Others |
Value Chain & Pricing Dynamics
Sheffield's powder metallurgy corridor and Solingen's forging cluster concentrate premium blade steel supply, anchoring margin capture in aftermarket refurbishment services rather than transactional tool sales. Nickel price volatility on the London Metal Exchange feeds directly into austenitic stainless steel input costs, compressing predictability for manufacturers without long-term offtake agreements with South Yorkshire or German metallurgy centers.
Pricing Analysis
Aftermarket blade sharpening subscriptions and component upgrade programs drive lifetime value across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified tactical specifications from recreational portability grades and entry-level polymer-handle alternatives. Cost compression in the mid-tier consumer segment is intensifying because big-box retailers require markdown clearance of obsolete SKUs before shelf resets. Municipal emergency services demonstrate the lowest price sensitivity due to FEMA grant channelization, while weekend campers exhibit highest elasticity to unit cost fluctuations.
Supply Chain Analysis
Feedstock dependency on nickel-alloyed austenitic stainless formulations draws from concentrated metallurgy R&D in the United Kingdom, Germany, and emerging powder metallurgy capacity in Sweden. Solingen maintains single-source vulnerability for premium fixed-blade forging without qualified secondary capacity elsewhere in Europe. Distribution runs through direct-to-consumer platforms and authorized service center networks that capture recurring refurbishment revenue alongside initial tool transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a procurement cyclical trough as NATO Standardization Agreement 4370 accelerates cross-border military requalification timelines and FEMA Community Preparedness Grants institutionalize municipal stockpiling mandates.
For Market Incumbents: Entrench dual-use certification capabilities by deepening government contract eligibility across both military and emergency services channels. Expand authorized service center networks in the Pacific Northwest and German federal states to capture blade refurbishment subscriptions before competitors establish footprint. Counter emerging subscription-based preparedness provisioning services by modularizing product architectures for upgradeable field adaptation without complete replacement cycles. For New Entrants and Emerging Players: Build out municipal sales development in underpenetrated Nordic civilian markets where household preparedness rates trail North American benchmarks. Target Sweden and Finland institutional procurement channels with adapted subscription models from California earthquake programming. Establish go-to-market presence through EU Critical Raw Materials Act strategic autonomy incentives for domestic hardened tool steel production. For Investors and Strategic Acquirers: Capital is best deployed toward metallurgy-certified forges with REACH Annex XVII compliance capabilities and existing NATO supplier qualification status. Long-term viability over the projection horizon favors manufacturers with backward integration into powder metallurgy R&D rather than pure distribution scale. Monitor FCC Equipment Authorization timelines for emergency beacon integration as inflection indicator for product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Blade Refurbishment Subscription Launch | Captures recurring revenue from Leatherman and SOG installed base without customer acquisition cost. |
| NATO Dual-Use Certification Investment | Compresses supplier requalification timelines for Bundeswehr and British Ministry of Defence procurement. |
| REACH Annex XVII Compliance Transition | Forces Solingen and Sheffield forges toward trivalent chromium finishes ahead of 2026 deadlines. |
| Direct-to-Consumer Platform Expansion | Bypasses big-box retail inventory reconfiguration delays for modular tool system launches. |
| Nordic Municipal Sales Development | Exploits whitespace in Sweden and Finland emergency stockpiling below US preparedness benchmarks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of NATO procurement databases, FEMA grant allocation records, and London Metal Exchange nickel pricing series through bottom-up and top-down triangulation. Primary interviews engaged product managers at tactical multi-tool manufacturers, municipal emergency management procurement officers, metallurgy R&D directors in South Yorkshire, and outdoor retail category buyers. Secondary validation incorporated Bundeswehr technical specifications, British Ministry of Defence standardization agreements, EPA water purification certification registries, and FCC equipment authorization filings.
Forecast inputs span product type segmentation across multi-tools, first aid kits, fire starters, and water purification systems; application channels including emergency preparedness, outdoor activities, camping, and hunting; and end user categories from military personnel through individual consumers. CAGRs derive from installed capacity utilization rates, federal funding allocation trajectories, and subscription provisioning adoption curves across the analysis window. Industry-specific inputs include Rockwell hardness certification timelines, REACH compliance transition schedules, and FCC authorization backlog durations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by emerging powder metallurgy specialists or accelerated Nordic municipal procurement standardization would shift outcomes. Cross-checking against NATO Standardization Agreement implementation progress and FEMA Community Preparedness Grant renewal authorizations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Emergency Escape Breathing Device Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Global Emergency Notification Software Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market