
 Emergency Location Transmitter Market | 2026-2036
Emergency Location Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Location Transmitter Market Analysis
Defense procurement channels is reshaping how emergency location transmitters reach end users, with prime contractors bundling ELTs into platform-level avionics packages. Honeywell International Inc. leverages its integrated flight deck portfolio to embed distress signaling within broader cockpit electronics. Orolia Holding SAS anchors its position through sovereign supply agreements with European military operators. Astronics Corporation competes via specialized crash-hardened transmitter designs for rotorcraft applications.
An emergency location transmitter is a self-contained radio beacon device that automatically activates upon impact or manual initiation, transmitting distress signals on 406 MHz via Cospas-Sarsat satellite infrastructure to enable rapid search and rescue coordination. These units incorporate solid-state accelerometers, lithium battery packs rated for multi-year standby, and GPS receivers to encode position data within digital burst transmissions. Emergency Position Indicating Radio Beacons dominate maritime and aviation installations due to mandatory carriage requirements under SOLAS and ICAO annexes. Personal Locator Beacons represent the fastest-expanding category as backcountry recreation participation rises and unit costs decline. GPS-enabled technology segments command premium positioning where precise coordinate encoding reduces search radius from kilometers to meters.
FAA regulations under 14 CFR 91.207 mandate ELT carriage for most US-registered aircraft, while EASA enforces equivalent requirements through Commission Regulation (EU) No 965/2012, with both agencies driving 406 MHz migration. The EU AI Act and emerging cybersecurity frameworks are beginning to shape software verification protocols for next-generation connected beacons. Stakeholders must monitor spectrum reallocation debates and dual-frequency interoperability standards as satellite constellations evolve.
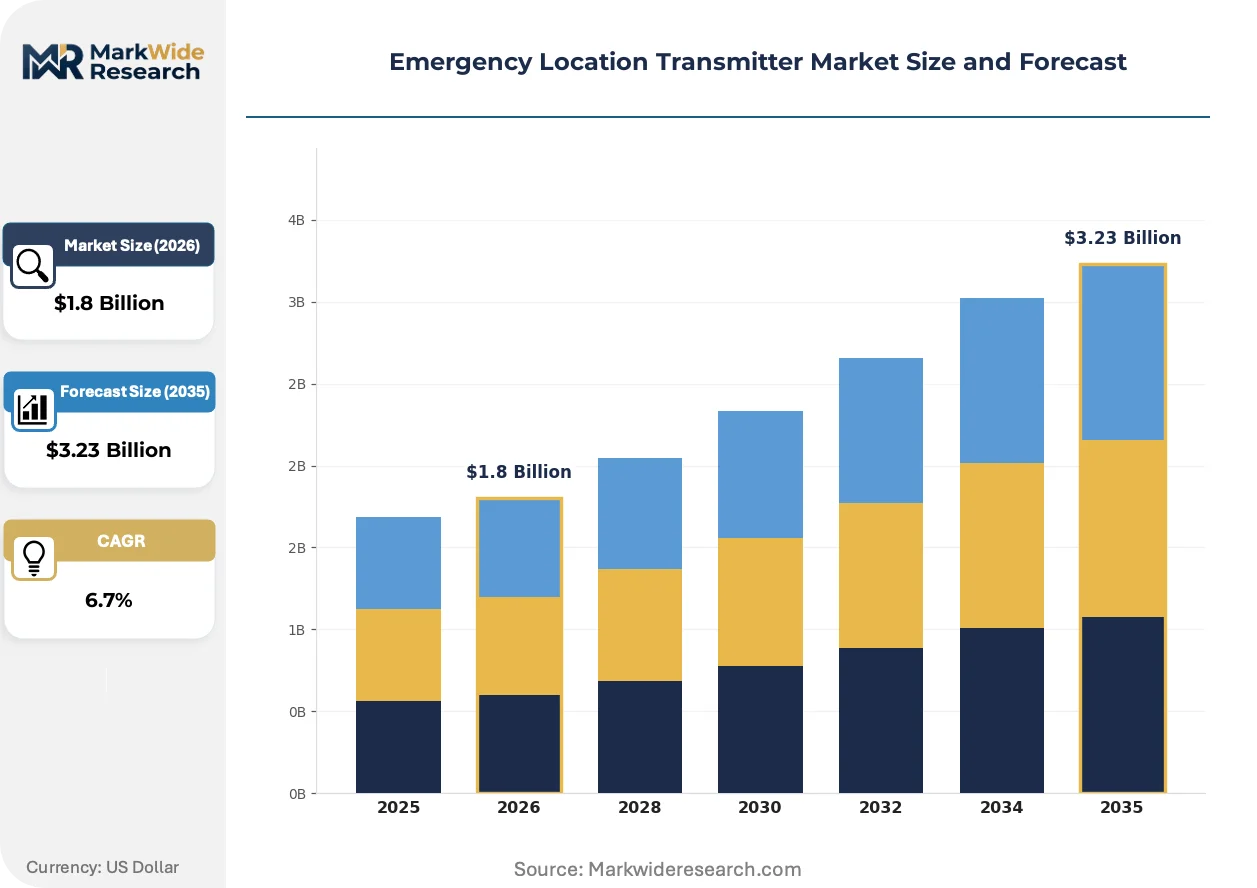
Market Dynamics
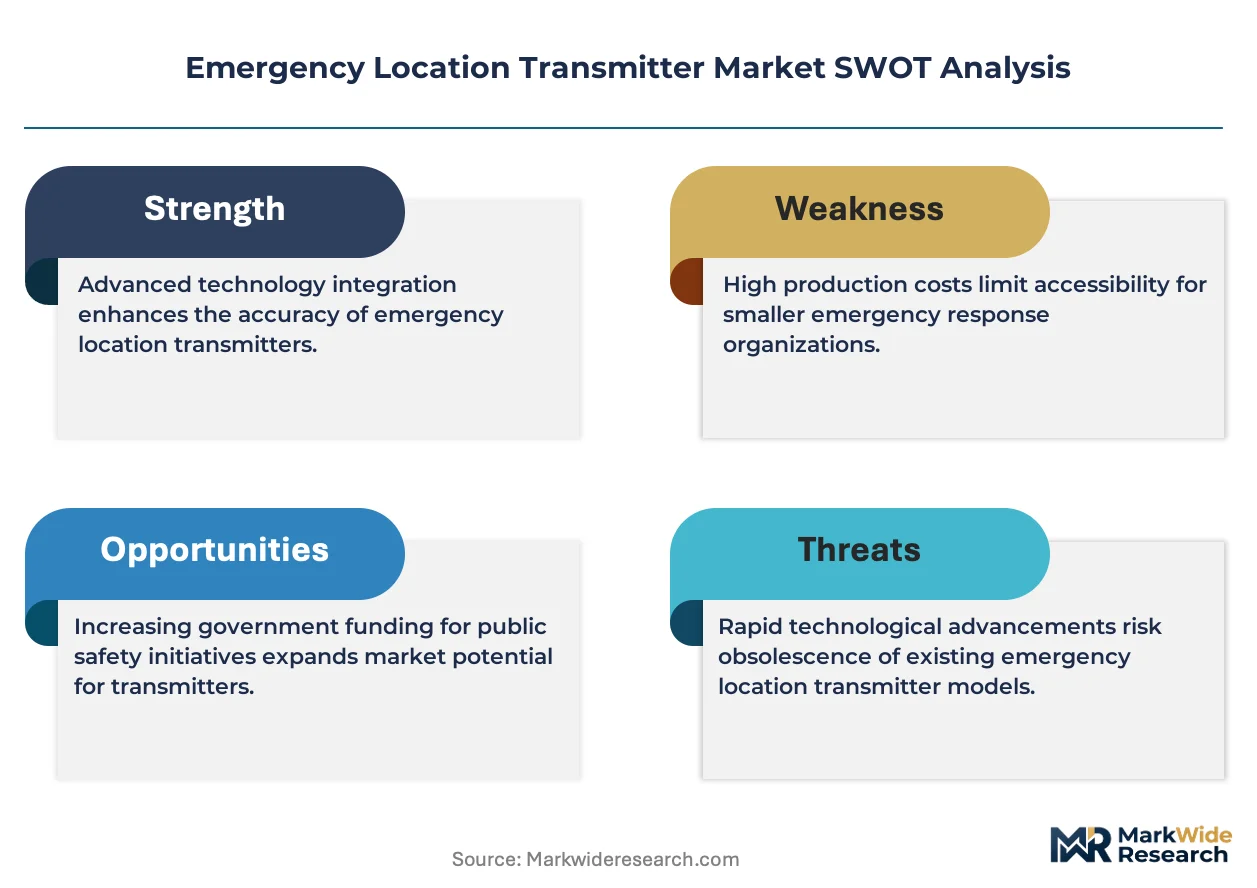
Defense procurement bundling and sovereign supply mandates are concentrating channel power among integrated avionics primes, squeezing standalone ELT specialists into niche crash-hardened and rotorcraft segments.
Growth Catalysts
- FAA 14 CFR 91.207 mandates:US-registered aircraft must carry automatic-activation ELTs, forcing fleet-wide retrofits as 121.5 MHz phase-out deadlines tighten.
- Cospas-Sarsat 406 MHz infrastructure:Satellite constellation upgrades enable meter-precision geolocation, reducing search radii and driving replacement demand across maritime and aviation fleets.
- Commercial aviation fleet expansion:Narrow-body and wide-body production backlogs at Boeing and Airbus embed ELTs into original equipment specifications.
Market Restraints
- Lithium battery supply concentration:Cell production clusters in East Asia create single-source vulnerability for multi-year standby power requirements.
- Accelerometer calibration complexity:Solid-state impact sensors require temperature-compensated testing protocols that extend production cycles.
- Dual-frequency interoperability delays:Debates over 406 MHz and emerging satellite bands fragment R&D budgets across incompatible hardware paths.
Strategic Opportunities
- Personal Locator Beacon recreation demand:Backcountry participation growth in the United States and Canada expands addressable market beyond regulated carriage requirements.
- EU AI Act software verification:Connected beacon cybersecurity protocols create first-mover advantage for vendors with embedded encryption stacks.
- Coast Guard maritime safety directives:Legacy unit replacement cycles accelerate in coastal enforcement and commercial fishing fleets.
Industry Challenges
- Crash-hardening certification timelines:RTCA DO-160 environmental testing for rotorcraft applications extends qualification periods beyond commercial aviation standards.
- Legacy 121.5 MHz inventory stranding:Obsolescence risk concentrates in general aviation segments with deferred upgrade schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Location Transmitter Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Locator Beacons, Satellite Emergency Radios, GPS Trackers, Emergency Position Indicating Radio Beacons Technology: GPS, GSM, RFID, Beacons Application: Maritime, Aviation, Outdoor Recreation, Search & Rescue End User: Government Agencies, Military, Outdoor Enthusiasts, Commercial Shipping |
| Companies Covered | Honeywell International Inc., Orolia Holding SAS, Astronics Corporation, ECA Group, Ack Avionics Technologies Inc., McMurdo Group, ACR Electronics, Cobham, HR Smith Group of Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Location Transmitter Market Emerging Trajectories
Beacon technology is converging with satellite IoT architectures and AI-enabled signal processing, compressing the gap between distress detection and rescue dispatch while raising new cybersecurity verification burdens.
GPS-enabled coordinate encoding is migrating from aviation-grade ELTs into lower-cost Personal Locator Beacon units. Recreational buyers in North America and Europe now expect meter-level precision previously reserved for commercial installations. This capability compression is collapsing the price-performance gap between regulated and voluntary beacon categories.
EASA Commission Regulation (EU) No 965/2012 enforcement is tightening 406 MHz carriage requirements across European-registered aircraft. National aviation authorities in Germany, France, and the United Kingdom are aligning inspection protocols with automatic activation testing. Commercial operators face compressed compliance windows as grandfather clauses expire.
After-sales service unbundling is fragmenting traditional distributor relationships in the general aviation segment. Maintenance repair organizations now source ELT batteries and replacement units directly from manufacturers, bypassing avionics dealers. This channel disintermediation is most pronounced in the United States where Part 145 repair stations consolidate purchasing power.
Emergency Location Transmitter Market Segmentation
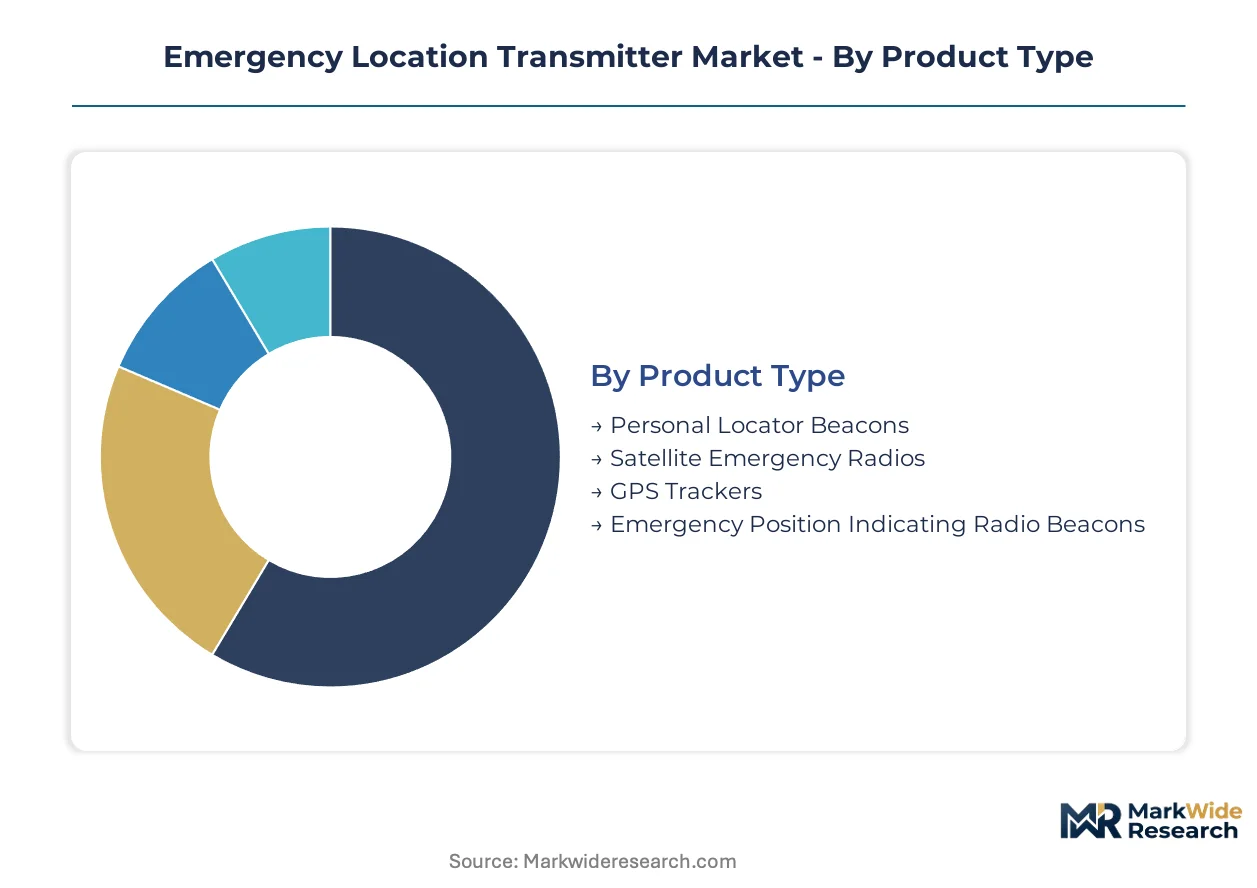
Emergency location transmitter procurement patterns diverge sharply across use-case scenarios, from mandatory aviation carriage to voluntary outdoor recreation purchases. Understanding these segment boundaries clarifies why technology specifications, pricing tiers, and distribution channels cluster into distinct commercial ecosystems.
Product Type:
Use-case spectrum spans regulated commercial mandates to discretionary consumer adoption, with each product category optimized for specific activation triggers and environmental hardening requirements.
- Emergency Position Indicating Radio Beacons:These marine-grade units transmit on 406 MHz with integrated GPS encoding and strobe lighting for nighttime visibility. SOLAS-mandated carriage on commercial vessels and ICAO-compliant aviation installations drive concentrated demand in United States and European coastal enforcement fleets. Battery replacement cycles and RTCA DO-160 certification requirements sustain aftermarket revenue streams.
- Personal Locator Beacons:Compact, manually-activated devices with 406 MHz burst transmission and 121.5 MHz homing signal backup. Backcountry recreation participation in United States national parks and Canadian wilderness areas accelerates unit sales as unit costs decline below $300 retail.
- Satellite Emergency Radios:Two-way voice and messaging capability via Iridium or Globalstar constellations, enabling interactive rescue coordination beyond simple distress alerting.
- GPS Trackers:Continuous position reporting devices primarily for asset monitoring and non-emergency fleet management, with secondary distress functionality in select models.
The dominant share belongs to Emergency Position Indicating Radio Beacons, while Personal Locator Beacons are closing the gap fastest.
Technology:
Cost tier stratification separates precision-positioning premiums from basic broadcast functionality, with hybrid architectures commanding intermediate pricing.
- GPS:Satellite-derived coordinate encoding reduces search radius from kilometers to meters, enabling precise rescue dispatch. Aviation-grade installations and premium maritime units incorporate multi-constellation receivers for Cospas-Sarsat compatibility.
- GSM:Cellular network dependency limits coverage to terrestrial infrastructure footprints, constraining adoption to near-shore maritime and domestic aviation routes.
- RFID:Proximity-based identification without autonomous distress transmission, deployed primarily for inventory tracking and crew accountability systems.
- Beacons:Legacy broadcast-only architectures on 121.5 MHz face obsolescence as Cospas-Sarsat satellite processing terminates analog signal support.
GPS-enabled units capture the premium tier, while GSM-based alternatives serve cost-constrained near-shore applications.
Application:
Customer type determines regulatory exposure and procurement channel, with mandated segments exhibiting price-inelastic demand and voluntary categories showing high price sensitivity.
- Aviation:FAA 14 CFR 91.207 and EASA Commission Regulation (EU) No 965/2012 mandate automatic-activation ELT carriage, embedding units into airframe certification pathways.
- Maritime:SOLAS Chapter IV requirements enforce Emergency Position Indicating Radio Beacon carriage on commercial vessels, with national coast guards conducting compliance inspections.
- Outdoor Recreation:Voluntary purchase decisions driven by insurance discounts and wilderness permit requirements in United States national forest jurisdictions.
- Search & Rescue:Professional responder units require hardened specifications and interoperability with military coordination networks.
Aviation maintains the largest installed base, though Outdoor Recreation demonstrates the steepest expansion trajectory.
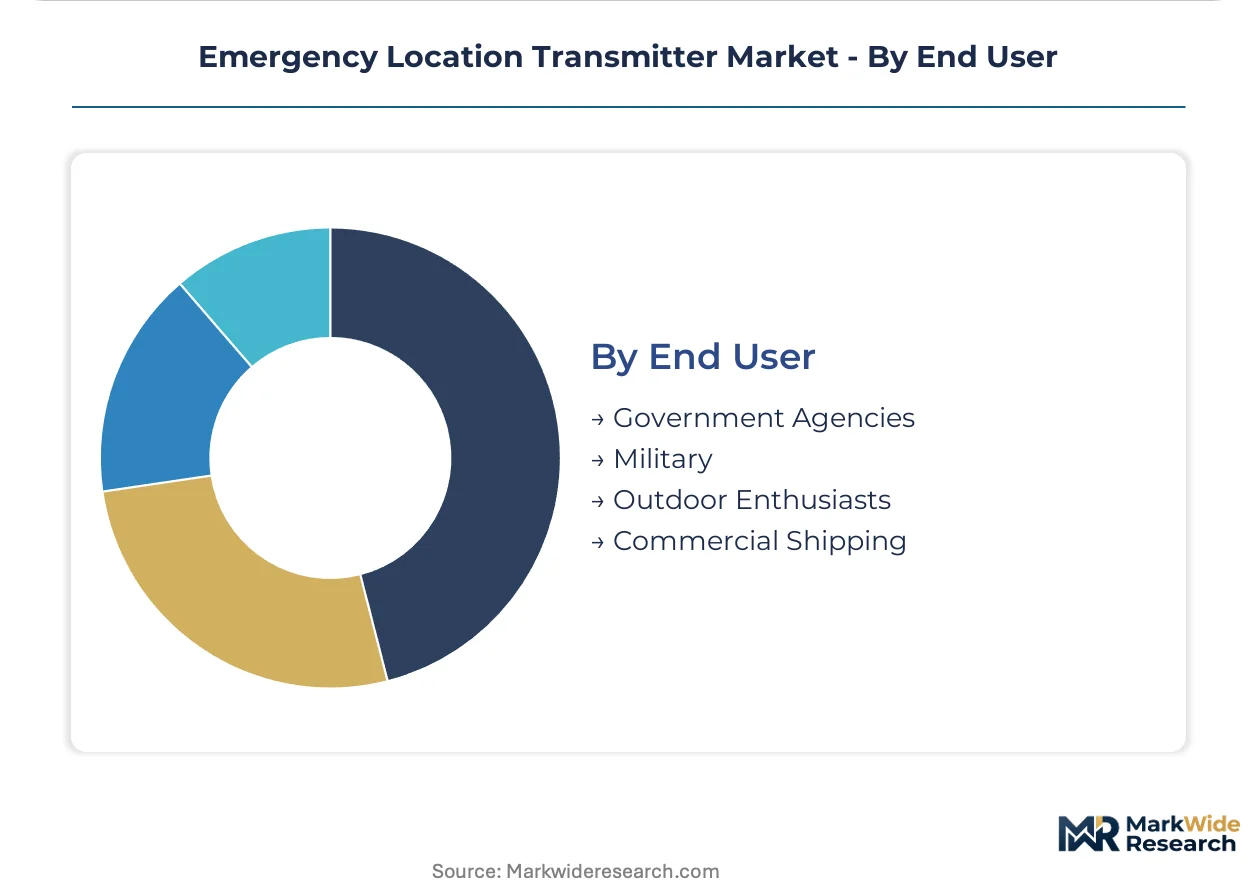
End User:
Volume concentration varies dramatically, with military and commercial shipping procurement consolidating purchasing power while outdoor enthusiasts fragment demand across retail channels.
- Military:Sovereign supply agreements and platform-level avionics integration prioritize crash-hardening and anti-tamper specifications over unit cost.
- Government Agencies:Coast Guard and national park service fleets combine regulated carriage with public-safety mission requirements.
- Commercial Shipping:Container fleet operators and fishing vessel owners face Port State Control inspections verifying 406 MHz beacon registration.
- Outdoor Enthusiasts:Individual purchasers through outdoor retail and direct-to-consumer channels, with seasonal demand spikes aligned to hiking and hunting calendars.
Military procurement anchors volume for hardened specifications, while Outdoor Enthusiasts represent the fastest-climbing demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aviation operators command premium pricing leverage against European maritime buyers due to FAA mandate timing and NextGen airspace investment cycles. German industrial clusters absorb cost premiums for sovereign-certified hardware that Asian shipyards reject. Japanese precision manufacturers extract value from dual-use defense contracts that commercial aviation channels cannot match.
United States
Commercial aviation fleet expansion and Coast Guard maritime safety directives drive concentrated demand for 406 MHz replacement units. FAA 14 CFR 91.207 enforcement tightens compliance windows for legacy 121.5 MHz phase-out. Dallas-Fort Worth avionics maintenance hubs cluster Part 145 repair station activity, consolidating aftermarket purchasing power away from traditional distributors.
Germany
EASA Commission Regulation (EU) No 965/2012 alignment forces accelerated retrofit schedules across Lufthansa Group narrow-body fleets. The country's national aviation regulator enforces automatic-activation testing protocols that exceed baseline EU requirements. Hamburg aerospace manufacturing corridors integrate ELT sourcing into platform-level avionics packages for Airbus final assembly lines.
Japan
Dual-use defense procurement channels prioritize crash-hardened specifications for Maritime Self-Defense Force rotary-wing platforms. METI industrial standards shape domestic supplier qualification requirements that foreign vendors struggle to satisfy. Nagoya aerospace supplier networks embed distress signaling modules into integrated flight deck systems for regional jet programs.
United Kingdom
Coast Guard search and rescue fleet modernization accelerates EPIRB replacement cycles in North Sea oil platform servicing routes. Civil Aviation Authority inspection protocols align with ICAO annex amendments for 406 MHz carriage verification. Southampton maritime technology clusters concentrate battery replacement and recertification services for commercial fishing vessel operators.
Australia
Remote aviation routes and offshore resource extraction drive mandatory ELT carriage across thinly populated continental interiors. The country's national maritime safety authority enforces SOLAS Chapter IV compliance with Port State Control inspection intensity matching European standards. Perth defense technology corridors channel sovereign supply agreements for military-specification beacon procurement.
Emergency Location Transmitter Market Vendor Landscape
Integrated avionics primes and specialized crash-hardening specialists split the market into non-overlapping procurement channels. Defense bundling concentrates volume among platform-level suppliers, while standalone retrofit demand fragments across maintenance repair organizations. Two strategic archetypes dominate: diversified aerospace conglomerates embedding ELTs within cockpit electronics suites, and focused beacon manufacturers defending niche rotorcraft and maritime applications. Competitive moves center on sovereign supply agreement capture and aftermarket service network unbundling.
Within the diversified aerospace tier, Honeywell International Inc. and Orolia Holding SAS exemplify contrasting geographic anchoring strategies. Honeywell occupies a position reflecting North American avionics integration heritage, while Orolia sits within European sovereign supply frameworks. Astronics Corporation represents the specialized crash-hardening archetype, with its corporate designation signaling focused manufacturing structure rather than conglomerate diversification.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Orolia Holding SAS |
| Astronics Corporation |
| ECA Group |
| Ack Avionics Technologies Inc. |
| McMurdo Group |
| ACR Electronics |
| Cobham |
| HR Smith Group of Co. |
| Others |
Supply Flow & Price Mechanics
Shanghai-Nagoya maritime corridors absorb lithium cell freight premiums that cascade into configured-to-order aviation units, concentrating margin pressure on crash-hardened specialists while standard maritime beacons compete on volume scale. Supply concentration in East Asian battery manufacturing feeds downstream price differentiation between GPS-enabled precision tiers and basic 406 MHz broadcast architectures.
Pricing Analysis
Configured-to-order aviation installations command spreads exceeding standard maritime units by certification grade and GPS constellation integration. Three-tier pricing structure across aviation-grade, commercial maritime, and recreational personal locator levels segments buyer sensitivity, with outdoor enthusiasts exhibiting highest price elasticity. Cost compression in recreational tiers intensifies as unit manufacturing scales, while military-specification crash-hardening retains pricing power through RTCA DO-160 qualification barriers. Fleet operators with Part 145 repair station networks leverage consolidated purchasing volume against distributor markups.
Supply Chain Analysis
Extended payment terms from Japanese precision manufacturers to tier-one avionics primes stabilize lithium primary cell flows through supply-chain finance facilities. Component sourcing draws from China, South Korea, and Japan for solid-state accelerometers, GPS receivers, and battery packs. Single-source vulnerability concentrates in lithium manganese dioxide cell production clusters. Distribution runs through sovereign defense procurement channels for military applications and avionics maintenance hubs for commercial retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crash-hardening engineering talent scarcity constrains rotorcraft specialist expansion, privileging incumbents with existing RTCA qualification infrastructure and squeezing aspirants into lower-margin recreational segments.
For Market Incumbents: Harden sovereign supply agreement positions through embedded flight deck integration, defending against standalone beacon commoditization by capturing platform-level avionics bundling. Prioritize backward integration into lithium cell qualification to mitigate East Asian supply concentration. Channel control through direct Part 145 repair station relationships bypasses distributor disintermediation threats. For New Entrants and Emerging Players: Pursue personal locator beacon white space in Canadian wilderness jurisdictions and United States national forest permit systems, where regulatory nudges and insurance discount programs accelerate voluntary adoption. Target direct-to-consumer outdoor retail channels with sub-$300 GPS-enabled units. Position through wilderness safety education partnerships rather than competing for aviation certification timelines. For Investors and Strategic Acquirers: Specialized crash-hardening boutiques with existing military platform qualifications present consolidation targets as defense procurement bundling concentrates channel power. Long-term viability hinges on dual-use technology transfer between commercial aviation and rotorcraft specifications. Monitor Cospas-Sarsat constellation upgrade schedules as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Supply Agreement Capture | Platform-level avionics bundling with Honeywell and Orolia locks out standalone competitors from defense procurement channels. |
| Aftermarket Service Network Unbundling | Direct Part 145 repair station relationships consolidate purchasing power and bypass traditional distributor margins. |
| Crash-Hardening Certification Investment | RTCA DO-160 qualification barriers protect rotorcraft specialists from recreational-tier price erosion. |
| Dual-Frequency Interoperability R&D | 406 MHz and emerging satellite band compatibility hedges against spectrum reallocation regulatory shifts. |
| Cybersecurity Protocol Stack Integration | EU AI Act software verification requirements create first-mover advantage for connected beacon encryption capabilities. |
Methodological Framework
Operator-level perspectives from avionics procurement officers, Part 145 repair station managers, Coast Guard compliance inspectors, and outdoor retail category buyers anchored the qualitative base. Secondary validation drew from FAA 14 CFR filings, EASA Commission Regulation submissions, Cospas-Sarsat system status documents, and customs trade records for lithium cell movements. Bottom-up unit shipment estimates triangulated against top-down fleet size and mandate compliance models.
Scenario-bracketing around Cospas-Sarsat constellation upgrade timing and 121.5 MHz phase-out deadlines shaped the analytical framework across the analysis window. Segmentation dimensions spanned product type, technology tier, application mandate status, and end-user procurement channel. CAGRs derived from fitted adoption curves against regulatory compliance windows, with aviation fleet production backlogs and maritime Port State Control inspection intensity as primary forecast inputs.
Sensitivities concentrate around lithium supply chain disruptions, dual-frequency standardization delays, and defense procurement budget reallocations. Forecasts reflect documented assumptions on mandate enforcement timing and satellite infrastructure deployment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Escape Breathing Device Market
Emergency and Disaster Management
Global Emergency Notification Software Market