
 Smart Home Safety Market | 2026-2036
Smart Home Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Safety Market Outlook
The EU Green Deal is realigning material sourcing and energy-efficiency mandates for connected safety hardware across European supply chains. ADT leverages its professional installation network to sustain recurring revenue density in North American suburbs. Ring anchors the DIY segment through deep e-commerce channel control and video-first product architecture.
Smart home safety encompasses networked intrusion detection, environmental hazard monitoring, and access control systems operating through wireless protocols with typical latency thresholds below 200 milliseconds for real-time alert transmission. These installations serve residential and commercial property stakeholders by reducing insurance liabilities and enabling remote occupancy verification. Security cameras and smart locks capture the dominant share of hardware value, while Z-Wave and Zigbee protocols are displacing Wi-Fi in whole-home integrated deployments where mesh reliability and battery longevity determine system performance. The professional installation category retains premium pricing power, though DIY systems are compressing entry-level margins and expanding the renter addressable base.
FCC certification governs radio-frequency emissions for devices sold in the United States, while CE marking and the EU AI Act impose algorithmic transparency and data governance obligations on European deployments. The EU F-Gas Regulation indirectly shapes demand by restricting refrigerants in climate-controlled server infrastructure that supports cloud-based monitoring platforms. Stakeholders must weigh protocol standardization bets against regulator-driven interoperability mandates before committing to multi-year hardware roadmaps.
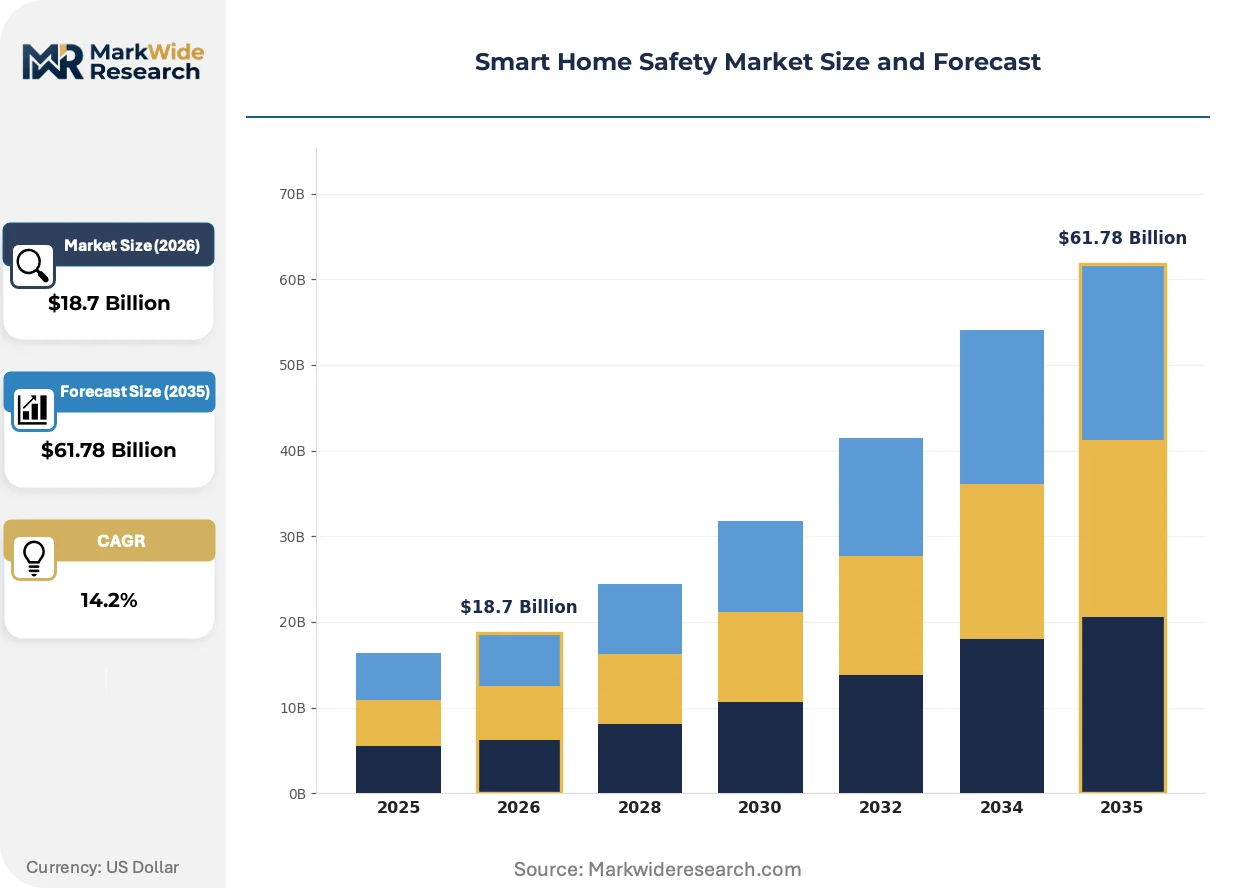
Market Dynamics
Protocol standardization bets now dominate vendor capital allocation as Z-Wave Long Range and Matter compete for whole-home integration dominance, while the EU AI Act forces algorithmic transparency redesigns across European product lines.
Growth Catalysts
- Insurance premium incentives:US property insurers now discount premiums by fixed percentages for verified smart alarm installations, accelerating homeowner conversion from traditional monitored systems.
- GDPR certification requirements:European data governance mandates are creating competitive moats for vendors with pre-certified privacy architectures, filtering out smaller hardware entrants.
- Smart city integration:Municipal governments in the United States are embedding residential safety data into emergency response dispatch systems, expanding the addressable base for connected devices.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for wireless chipsets remains concentrated in East Asian foundries, exposing hardware vendors to geopolitical disruption risk and extended lead times.
- Wi-Fi congestion thresholds:Dense urban deployments face interference limitations that degrade real-time alert reliability below the 200-millisecond threshold required for intrusion detection.
- CE marking complexity:The EU AI Act's algorithmic transparency requirements are extending product certification timelines by six to nine months for computer-vision-enabled cameras.
Strategic Opportunities
- Renter addressable expansion:Battery-powered, peel-and-stick sensor kits are unlocking the previously inaccessible rental housing segment across Germany and France where permanent installation is prohibited.
- Environmental hazard convergence:Integration of smoke, carbon monoxide, and water leak detection into unified sensor platforms is creating upsell opportunities beyond pure security applications.
- F-Gas Regulation tailwinds:Restrictions on refrigerants in climate-controlled server infrastructure are accelerating edge-computing migration for local video processing, reducing cloud dependency.
Industry Challenges
- RF engineering talent scarcity:Mesh network optimization and sub-gigahertz protocol design require specialized wireless engineering skills that remain concentrated in a small pool of semiconductor veterans.
- Legacy system interoperability:Hardwired alarm infrastructure from the 1990s and 2000s persists in suburban US housing stock, forcing retrofit complexity or parallel system operation.
- FCC certification bottlenecks:Radio-frequency emission testing backlogs at accredited laboratories are delaying product launches by four to six months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Safety Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Alarms, Security Cameras, Smart Locks, Motion Sensors Technology: Wi-Fi, Bluetooth, Z-Wave, Zigbee End User: Residential, Renters, Homeowners, Property Managers Installation: DIY, Professional, Remote Monitoring, Integrated Systems |
| Companies Covered | Ring, Cove Security, ADT, Brinks Home Security, Alder Security, SimpliSafe, Frontpoint, Deep Sentinel, Vivint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Safety Market Strategic Shifts
Three simultaneous shifts are restructuring competitive advantage: protocol convergence is collapsing hardware fragmentation, regulatory transparency mandates are elevating software architecture importance, and channel control is migrating from installers to platform operators.
Thread and Matter protocols are overtaking proprietary Zigbee and Z-Wave stacks in new construction deployments. Homebuilders in the United States now specify Matter-certified devices to ensure tenant interoperability across brands. This standardization is compressing margins for hardware vendors while elevating platform and software service revenue.
The EU AI Act's risk classification framework is forcing algorithmic disclosure for facial recognition and behavioral analytics in security cameras. European deployments must now document training data provenance and decision logic for market surveillance authorities. Vendors are responding by segregating AI-enabled features into region-specific firmware builds.
Channel control is migrating from professional installers to e-commerce platforms with embedded installation marketplaces. US homeowners increasingly purchase hardware through Amazon and Home Depot digital channels, then book third-party installation as an add-on service. This disintermediation is eroding ADT's suburban installation network advantage while expanding Ring's direct-to-consumer capture rate.
Smart Home Safety Market Segmentation
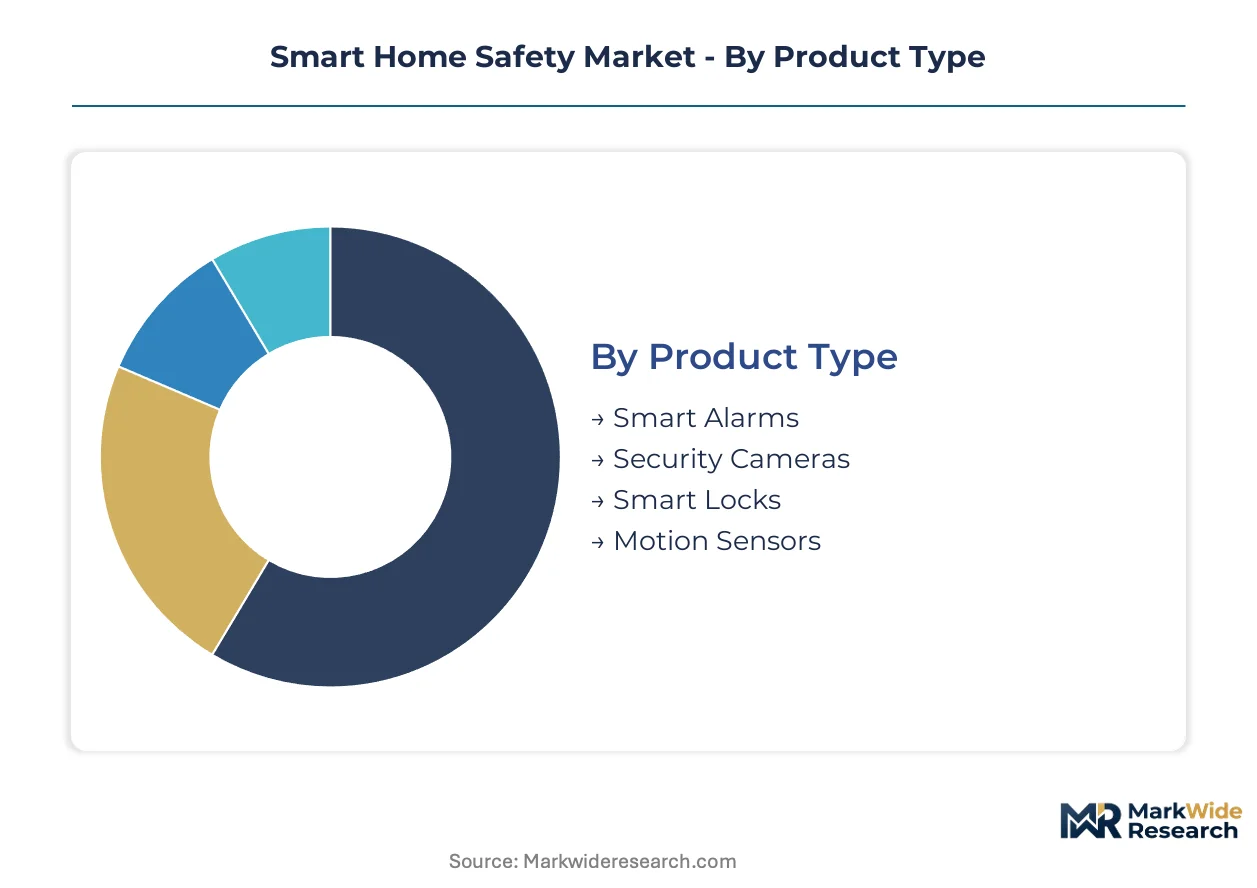
Segment boundaries in smart home safety reflect divergent certification burdens and channel economics. Hardware vendors must align product architectures with specific compliance pathways and buyer procurement patterns to avoid margin erosion from misaligned inventory.
Product Type:
Security cameras face the heaviest regulatory load under the EU AI Act's algorithmic transparency mandates, while smart alarms navigate FCC Part 15 emissions testing and UL 827 monitoring center standards.
- Smart Alarms:Hub-based intrusion detection systems with cellular and IP dual-path communication. Demand concentrates in US suburban owner-occupied housing where insurers offer premium discounts for UL-certified installations. FCC Part 15 Subpart B and UL 985/1632 govern hardware certification timelines.
- Security Cameras:Video capture devices with edge or cloud-based analytics. European deployments require GDPR data governance documentation and EU AI Act risk classification for facial recognition features, extending certification by six to nine months.
- Smart Locks:Keyless entry systems with biometric or keypad authentication. ANSI/BHMA grading and CE marking for electromagnetic compatibility shape vendor go-to-market sequencing.
- Motion Sensors:Passive infrared and microwave detection devices with pet-immunity algorithms. Battery longevity and sub-gigahertz protocol compatibility determine placement in whole-home architectures.
Security cameras sit at the top of the volume ranking, with smart locks climbing the fastest.
Technology:
Protocol selection locks vendors into multi-year hardware roadmaps with divergent power budgets and interoperability profiles.
- Wi-Fi:IP-based connectivity leveraging existing residential broadband infrastructure. Dense urban deployments in New York and Los Angeles encounter congestion thresholds that degrade real-time alert reliability below 200-millisecond requirements.
- Bluetooth:Short-range pairing for device commissioning and mobile proximity unlocking. Low energy consumption suits battery-powered door sensors and temporary rental installations.
- Z-Wave:Sub-gigahertz mesh protocol with 100-meter range and 10-year battery life. Silicon Labs certification and regional frequency band compliance (908.42 MHz US, 868.42 MHz EU) fragment firmware development.
- Zigbee:IEEE 802.15.4-based mesh networking with 2.4 GHz global deployment. Thread protocol convergence is displacing proprietary Zigbee stacks in new construction specifications.
Z-Wave holds the largest installed base, though Matter-certified Thread implementations are gaining share fastest.
End User:
Buyer type determines pricing tolerance, installation channel preference, and recurring revenue potential.
- Residential:Owner-occupied single-family and multifamily dwellings. Insurance premium incentives and municipal smart city integrations in Austin and Phoenix accelerate system adoption.
- Renters:Lease-constrained occupants requiring non-permanent installations. Peel-and-stick sensor kits with cellular backup unlock demand in German and French rental markets where drilling is prohibited.
- Homeowners:Permanent residents with equity stakes driving premium system investment. Professional installation preference sustains higher average revenue per user.
- Property Managers:Multi-unit portfolio operators seeking centralized monitoring and tenant turnover flexibility. Master key override and remote access provisioning shape procurement criteria.
Homeowners generate the highest revenue per account, with renters expanding the addressable base most quickly.
Installation:
Channel structure determines margin capture between hardware vendors, service providers, and end customers.
- DIY:Self-installed systems purchased through e-commerce channels with embedded configuration apps. Amazon and Home Depot digital marketplaces disintermediate traditional installer networks.
- Professional:Technician-deployed systems with hardwired power and monitored alarm response. Suburban US markets retain premium pricing power through recurring monthly revenue contracts.
- Remote Monitoring:Central station oversight of self-installed hardware with optional video verification. UL 827 certification requirements filter vendor participation.
- Integrated Systems:Whole-home automation combining safety, climate, and lighting control. Matter protocol certification ensures cross-brand interoperability in new construction.
Professional installation retains the highest lifetime value, with DIY systems capturing volume growth fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart home safety industry traces its commercial origins to suburban United States markets in the 1990s, where hardwired alarm systems first achieved scale through professional installer networks. This foundation established certification protocols and recurring revenue models that now propagate across regulatory jurisdictions.
United States
Insurance premium discounts from State Farm and Allstate accelerate homeowner conversion to monitored systems. FCC Part 15 certification governs radio-frequency emissions for wireless devices. The Dallas-Fort Worth metroplex hosts multiple central station monitoring facilities serving national subscriber bases.
Germany
Rental housing restrictions on permanent installations drive demand for peel-and-stick cellular sensors. GDPR and the EU AI Act impose algorithmic transparency mandates on computer-vision devices. Berlin's startup ecosystem incubates privacy-first hardware architectures targeting EU compliance.
United Kingdom
Smart meter rollout programs create infrastructure for whole-home safety integration. BS EN 50131 standards for intruder alarm systems shape product certification pathways. London's insurance district influences underwriting models that reward verified alarm installations.
France
CNIL enforcement actions elevate data governance as a procurement criterion for security cameras. The EU Green Deal redirects material sourcing toward recycled plastics and reduced packaging. Lyon hosts semiconductor design clusters specializing in low-power wireless chipsets.
Japan
Aging demographics expand demand for remote occupancy verification systems. METI promotes interoperability standards through the Connected Consumer Devices Consortium. Osaka's electronics manufacturing corridor supplies precision sensors for regional safety hardware.
Smart Home Safety Market Competitive Environment
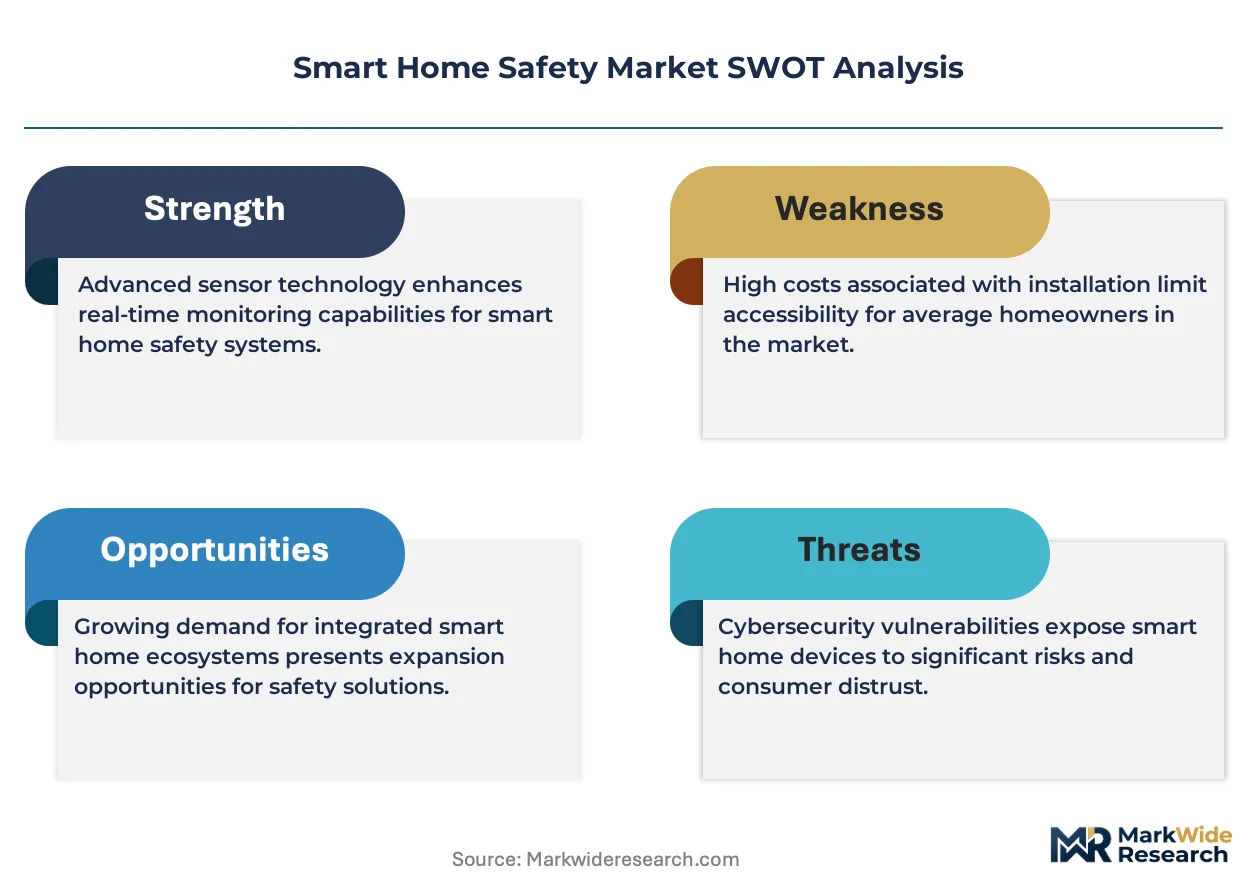
Capital-heavy producers compete with asset-light designers across divergent margin structures. The market exhibits tiered consolidation, with national installation networks defending recurring revenue density against direct-to-consumer platforms compressing entry-level pricing. Three archetypes dominate: professional monitoring incumbents with technician fleets, e-commerce-native hardware brands, and hybrid remote-monitoring services. Competitive moves concentrate on channel disintermediation and protocol certification races for Matter compliance.
Within the professional monitoring tier, ADT and Vivint anchor positions through suburban installation density and long-term service contracts. Ring exemplifies the e-commerce-native archetype, leveraging Amazon's fulfillment infrastructure to capture DIY market expansion. Cove Security and SimpliSafe occupy intermediate positions, blending self-install hardware with optional central station oversight.
| Leading Market Players |
|---|
| Ring |
| Cove Security |
| ADT |
| Brinks Home Security |
| Alder Security |
| SimpliSafe |
| Frontpoint |
| Deep Sentinel |
| Vivint |
| Others |
Value Chain & Pricing Dynamics
Professional-monitored and DIY self-install tiers diverge sharply across hardware bundling, recurring service attach rates, and certification depth, with that bifurcation driving parallel supply chain configurations: premium vendors source UL-certified cellular modules and encrypted edge processors through contracted semiconductor distributors, while entry-level brands tap generic Wi-Fi chipsets via Shenzhen trading houses to preserve margin on sub-$200 system bundles.
Pricing Analysis
Subscription-tethered hardware pricing dominates the revenue architecture, with three-tier pricing structure across premium, standard, and economy levels anchored by UL 827 certification grade and installation channel. Price differentiation separates professional-monitored systems with cellular backup from Wi-Fi-dependent DIY kits. Cost compression in the DIY tier intensifies because Amazon and Home Depot marketplace sellers undercut direct-brand pricing. Renters exhibit highest price sensitivity, while suburban homeowners with insurance premium incentives show lowest.
Supply Chain Analysis
EU Green Deal domestic-content mandates and US CHIPS Act incentives are reshaping sourcing decisions for European and North American deployments. Semiconductor fabrication for wireless chipsets concentrates in Taiwan, South Korea, and China. Battery cells, plastic enclosures, and printed circuit boards draw from Vietnamese and Malaysian contract manufacturers. Single-source vulnerability in 868 MHz and 908 MHz sub-gigahertz radio modules creates exposure. Distribution runs through Amazon fulfillment centers and professional installer procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act functions as a regulatory compounder, mandating algorithmic transparency documentation that extends certification timelines and elevates compliance spending into a competitive moat for prepared vendors.
For Market Incumbents: Deploy certification depth as the primary defensive lever. Accelerate EU AI Act pre-certification for computer-vision product lines before smaller competitors exhaust capital on extended approval cycles. Capture Matter protocol certification early to lock homebuilder specification channels against Zigbee and Z-Wave holdouts. Channel control erosion from e-commerce platforms threatens suburban installer network density.
For New Entrants and Emerging Players: Begin with peel-and-stick cellular sensor kits targeting German and French rental housing where permanent installation prohibitions exclude legacy vendors. Environmental hazard convergence—smoke, carbon monoxide, and water leak unification—offers white-space penetration with lower AI Act exposure than facial recognition cameras. Direct-to-consumer subscription bundling bypasses installer channel gatekeeping.
For Investors and Strategic Acquirers: Consolidation pressure builds where FCC certification backlogs and EU AI Act compliance costs exceed $2 million annual burn for pre-revenue hardware startups. Five-to-ten-year viability favors vendors with pre-certified privacy architectures and existing Matter interoperability. Acquisition target archetype: remote-monitoring services with UL 827 certification and cellular carrier partnerships. Watch silicon supply lead time normalization as inflection signal for hardware margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Homebuilder specification mandates in Austin and Phoenix require cross-brand interoperability. |
| EU AI Act Pre-Certification | Berlin and Paris deployments demand algorithmic transparency documentation for facial recognition. |
| Cellular Backup Integration | Insurance premium discounts from State Farm require dual-path communication redundancy. |
| Edge Computing Migration | F-Gas Regulation restrictions accelerate local video processing away from cloud-dependent infrastructure. |
| Renter-Addressable SKU Development | Peel-and-stick German rental market expansion unlocks previously inaccessible tenant segments. |
Study Parameters
Bottom-up homeowner and renter demand modeling reconciled against top-down semiconductor supply tracking forms the analytical core. Primary interviews with smart home platform engineers, UL certification consultants, central station monitoring operators, and insurance underwriting specialists combined with secondary validation from FCC equipment authorization databases, ETSI harmonized standards filings, and Amazon marketplace sales rank data. Triangulation across installation channel surveys and cellular carrier IoT connectivity disclosures verified demand assumptions.
Historical trendline analysis of protocol adoption curves and certification timeline expansion informed projection parameters across the analysis window. Segmentation dimensions modeled include installation type, end-user tenure status, wireless protocol architecture, and regional regulatory cluster. CAGRs derived from fitted adoption curves weighted by insurance incentive penetration and smart city integration milestones. Edge computing migration rates and silicon supply lead time volatility served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwan semiconductor fabrication, sudden EU AI Act enforcement escalation, and municipal smart city budget freezes. Forecasts reflect documented assumptions about insurance premium incentive persistence and Matter protocol adoption velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Child Safety Seat Market
Personal Safety
Pepper Sprays Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Global Fall Protection Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Fall Detection System Market
Personal Safety
Child Leash Market
Personal Safety
Road Safety Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Asia-Pacific People Screening Market