
 Active Seat Belt System Market | 2026-2036
Active Seat Belt System Market Size, Share, and Industry Trends Forecast 2026-2036
Active Seat Belt System Market Intelligence
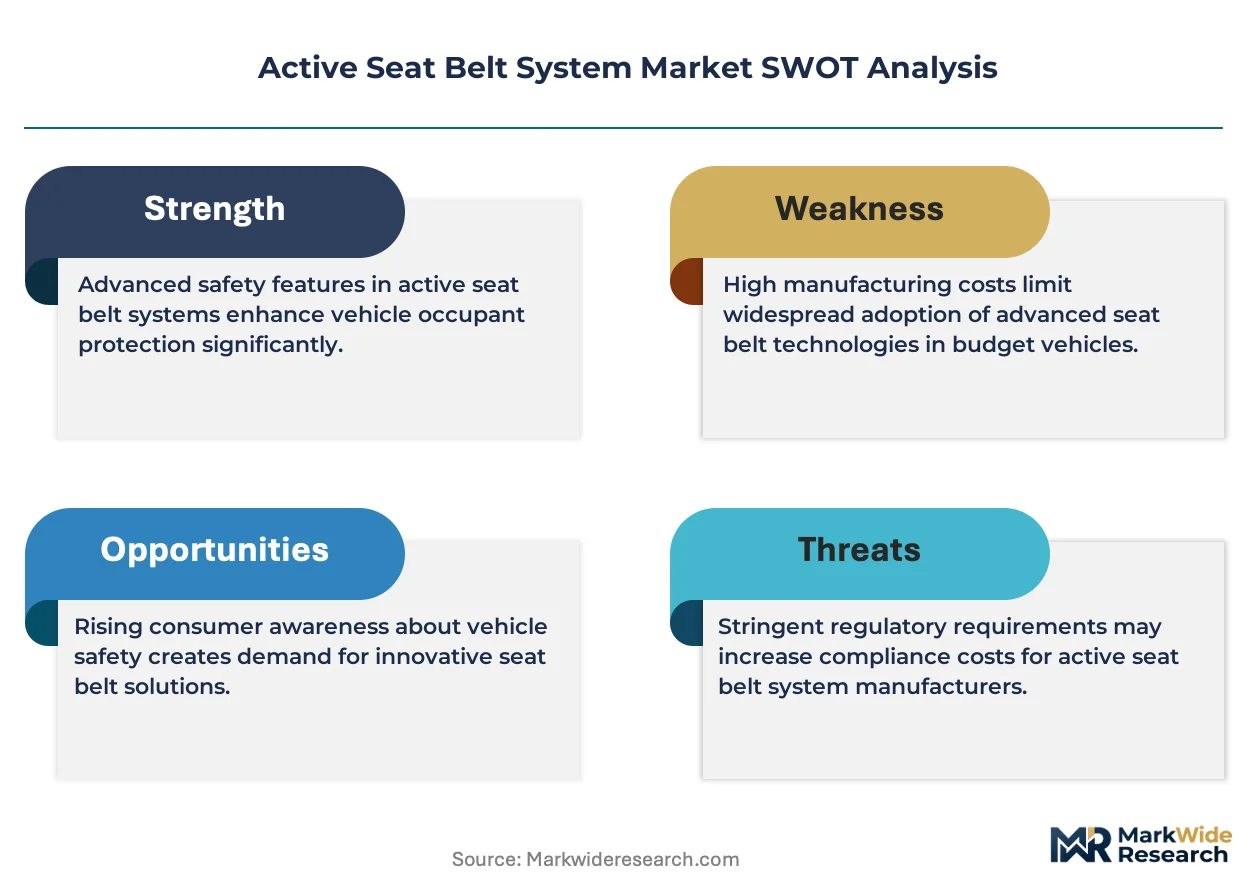
Mechatronics engineering talent is rotating toward automotive safety electronics, tightening labor availability for legacy mechanical belt suppliers while unlocking electromechanical innovation. Autoliv Inc. leverages its vertically integrated sensor-to-retractor pipeline to dominate crash-responsive pretensioner supply. Continental AG anchors European OEM relationships through localized R&D centers in Germany. ZF Friedrichshafen AG sustains manufacturing scale across multiple assembly corridors.
An active seat belt system is an electromechanically controlled occupant restraint that uses motor-driven spools, pyrotechnic pretensioners, or reactive force limiters to adjust webbing tension in real time before and during collision events, typically operating within 10-20 milliseconds of sensor trigger. The system serves the primary commercial purpose of reducing occupant chest deflection and submarining risk across frontal and offset crash modes. Electromechanical technology leads value generation due to its reversible operation and integration with advanced driver-assistance architectures, while pneumatic systems retain niche presence in heavy-duty commercial cabins. Factory-installed deployment controls margin pools given OEM liability frameworks and calibration complexity, whereas aftermarket channels face certification barriers that constrain price realization.
NHTSA FMVSS 209 and 302 govern webbing material flammability and tensile integrity in the United States, while ECE R16 mandates anchor strength and retractor durability across European type approvals. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces offset crash testing that effectively requires active pretensioner inclusion in domestic-market vehicles. Stakeholders must monitor divergence between UN R16 harmonization efforts and NHTSA's distinct sled-test protocols when planning platform-standardization strategies.
Market Dynamics
The active seat belt system market is being reshaped by NHTSA's tightening force-limiter requirements under updated Federal Motor Vehicle Safety Standards, which mandate faster pretensioner response times and stricter chest-deflection limits for frontal crash protection.
Growth Catalysts
- Electromechanical retractor integration:Motor-driven spools enable reversible tension adjustment and seamless connectivity with advanced driver-assistance architectures, creating upgrade pathways for premium vehicle platforms.
- ECE R16 harmonization:Anchor strength and retractor durability mandates across European type approvals are standardizing component specifications, reducing engineering fragmentation for multinational OEMs.
- Japan's offset crash testing:Ministry of Land, Infrastructure, Transport and Tourism enforcement effectively requires active pretensioner inclusion in domestic-market vehicles, locking in baseline demand.
Market Restraints
- Pyrotechnic material cost volatility:Gas generant and initiator compounds face supply concentration in specialized chemical processors, compressing margin pools for mechanical belt suppliers.
- Calibration complexity barriers:OEM liability frameworks restrict aftermarket channel participation, as sensor-to-retractor synchronization requires factory-authorized diagnostic equipment.
- UN R16 and NHTSA protocol divergence:Sled-test methodology differences between UN harmonization efforts and US-specific requirements force dual validation tracks, extending development timelines.
Strategic Opportunities
- Heavy-duty commercial cabin penetration:Pneumatic active belt systems retain niche presence in truck and bus segments, offering retrofit potential as fleet operators upgrade occupant protection.
- ADAS convergence:Integration of seat belt controllers with autonomous emergency braking and lane-keeping systems enables predictive pretensioning before collision events.
- German R&D localization:Continental AG's anchored European OEM relationships through Germany-based development centers demonstrate the value of proximity engineering for platform-specific customization.
Industry Challenges
- Mechatronics talent migration:Engineering labor is rotating toward automotive safety electronics, tightening availability for legacy mechanical belt suppliers and inflating recruitment costs.
- Sensor-to-retractor integration complexity:Multi-domain calibration across crash sensors, occupant classification systems, and retractor motors requires cross-functional teams that remain scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Seat Belt System Market |
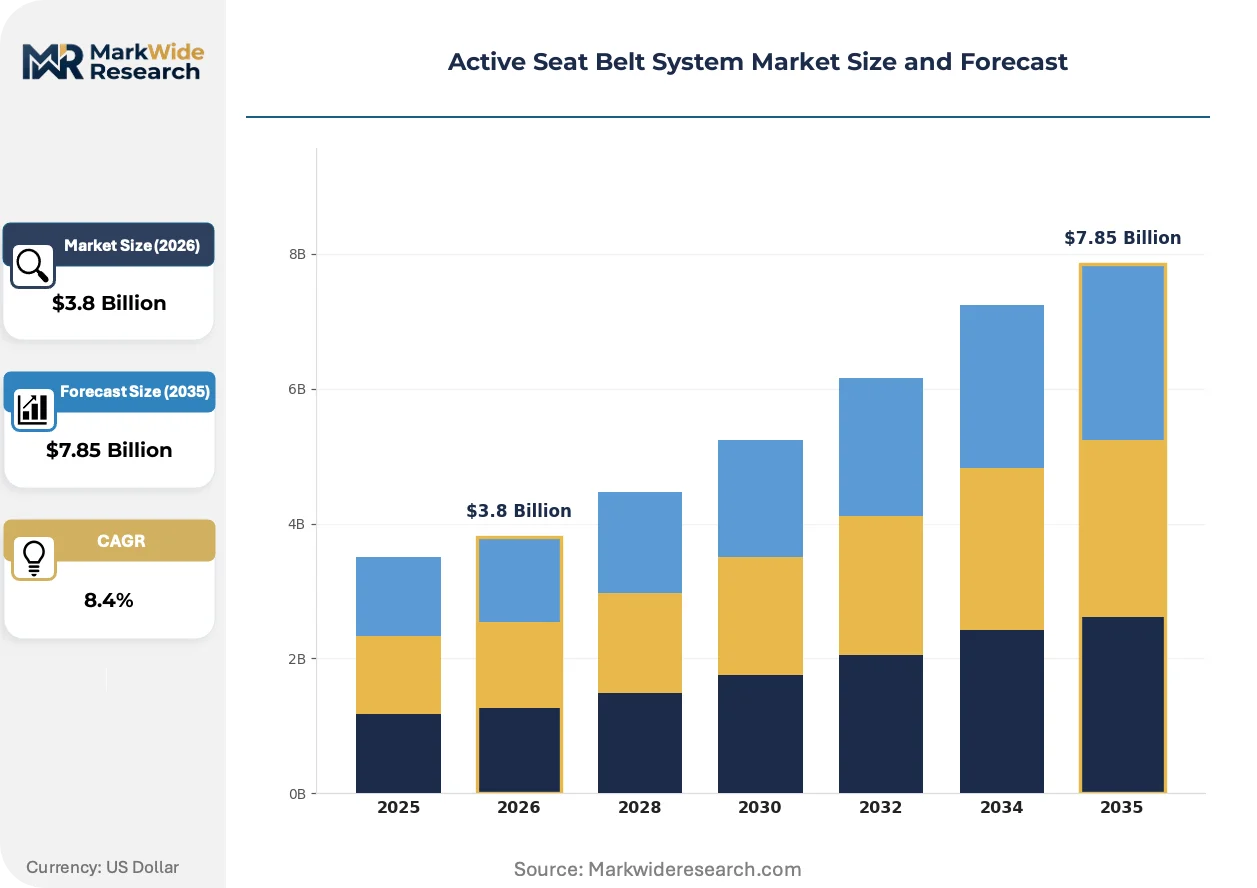
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Integrated, Retractable Technology: Electromechanical, Pneumatic, Hydraulic, Reactive End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Factory-installed, Retrofit, Customized, Standard |
| Companies Covered | Autoliv Inc., Continental AG, DENSO Corporation, ZF Friedrichshafen AG, Hyundai Mobis, Joyson Group, Tokai Rika Co. Ltd., GWR Safety Systems, Far Europe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Seat Belt System Market Strategic Shifts & Innovations
Electromechanical architectures are displacing pyrotechnic pretensioners across premium vehicle segments, while regulatory divergence between US and European test protocols is fragmenting platform standardization strategies.
Reactive force limiter technology is decomposing the traditional trade-off between occupant retention and chest deflection mitigation. Luxury OEMs in Germany and Japan are adopting load-limited retractors that modulate webbing payout based on real-time crash severity estimation. This capability is compressing the competitive window for single-stage pyrotechnic systems that cannot adjust post-trigger.
NHTSA's updated FMVSS 209 and 302 standards are tightening webbing material flammability and tensile integrity requirements, forcing suppliers to validate new polymer formulations. The industrial consequence is extended qualification timelines for Asian textile producers seeking US market entry. Component manufacturers are responding by consolidating testing partnerships with NHTSA-registered laboratories to accelerate certification throughput.
Fleet procurement patterns are compressing switching cycles for active seat belt retrofits in commercial vehicle segments. Direct sourcing from tier-one safety suppliers is displacing aftermarket distributors in North American heavy-truck channels. This shift is most visible in long-haul freight operations where insurance underwriters now mandate active restraint inclusion for preferred risk rating.
Active Seat Belt System Market Segmentation
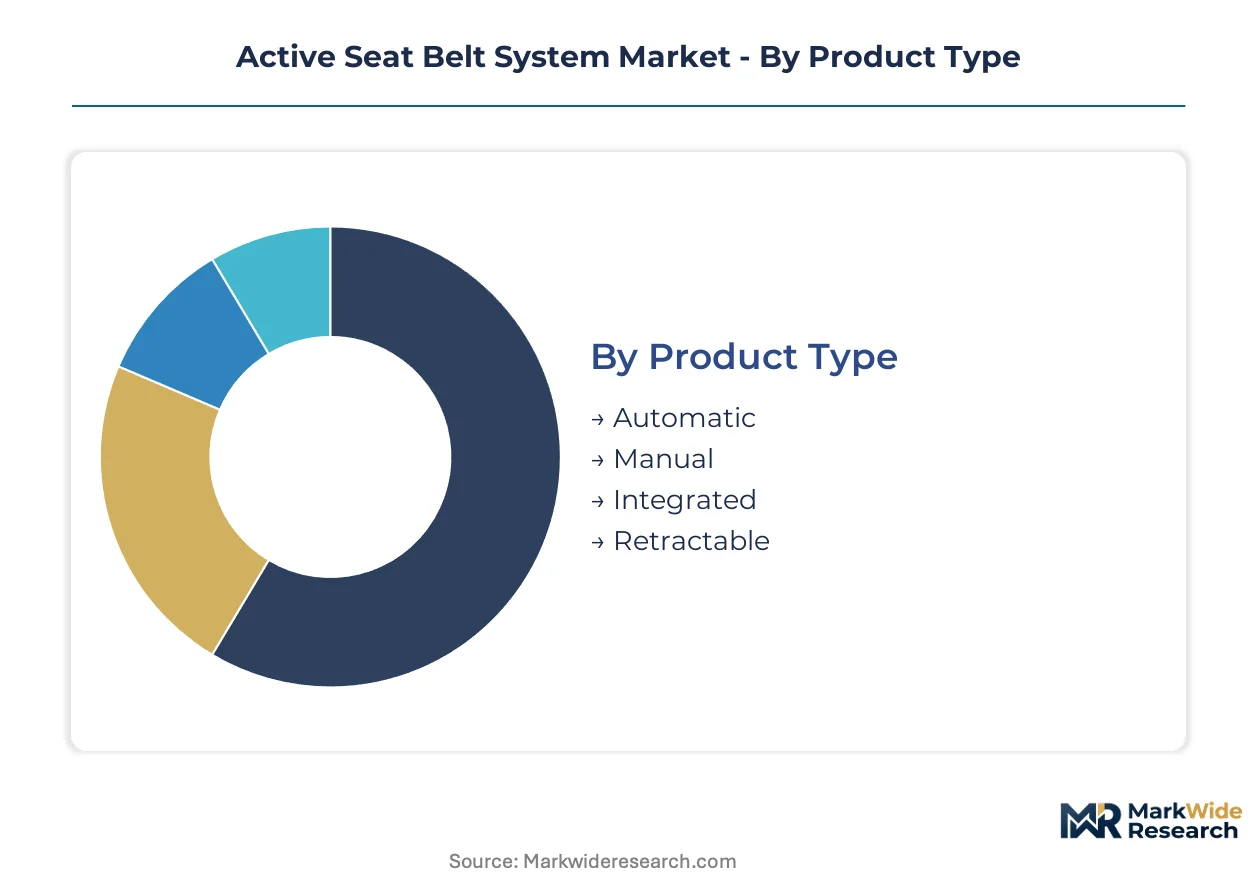
Active seat belt system segmentation reveals distinct substitution pressures across product architectures, with reversible electromechanical designs displacing single-use pyrotechnic units in premium platforms while pneumatic systems defend niche commercial applications. Technology and installation type categories determine margin stratification, as factory-integrated electromechanical retractors command pricing premiums against retrofit mechanical alternatives.
Product Type:
Automatic configurations face intensifying displacement risk from integrated smart-retractor platforms that bundle pretensioning with occupant sensing.
- Automatic:Motor-driven spools adjust webbing tension without driver intervention, typically deploying within 10-20 milliseconds of collision detection. Demand concentrates in German and Japanese luxury OEM platforms where NHTSA's tightening chest-deflection limits favor predictive restraint activation.
- Integrated:Combines retractor mechanisms with seat position sensors and occupant classification modules in unified housings. Japanese vehicle assemblers favor this architecture for offset crash compliance, locking in specification requirements through Ministry of Land, Infrastructure, Transport and Tourism testing protocols.
- Manual:Driver-activated tension adjustment retains presence in economy vehicle segments where electromechanical cost premiums exceed platform budgets.
- Retractable:Spring-loaded spool designs with automatic locking functions serve as baseline configurations in emerging market vehicle platforms.
Automatic configurations retain volume leadership; integrated systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates reversible electromechanical platforms from single-cycle pneumatic and hydraulic alternatives.
- Electromechanical:DC motor-driven spools enable pre-crash tensioning and post-event relaxation, supporting ADAS integration with autonomous emergency braking architectures. German OEMs specify these systems for predictive pretensioning capabilities that reduce occupant submarining risk.
- Reactive:Load-limited retractors modulate webbing payout based on real-time crash severity estimation through deformation-sensitive torsion bars. United States assembly plants are adopting this technology to meet NHTSA's updated FMVSS 209 force-limiter requirements without full electromechanical cost burdens.
- Pneumatic:Compressed-air pretensioners serve heavy-duty commercial cabins where electrical system complexity poses reliability risks.
- Hydraulic:Fluid-pressure systems retain limited presence in specialized industrial vehicle applications requiring extreme force density.
Electromechanical platforms dominate value capture; reactive technology is climbing the fastest.
End User:
Customer type determines specification authority, with OEMs holding design control while Tier-1 suppliers manage manufacturing scale.
- OEMs:Original equipment manufacturers define active seat belt calibration protocols and sensor-to-retractor synchronization requirements, locking in supplier relationships through platform-specific validation programs. German and Japanese OEMs maintain captive engineering teams for pretensioner integration with proprietary vehicle architectures.
- Tier-1 Suppliers:Autoliv and Continental manufacture retractor assemblies to OEM specifications, managing electromechanical component supply chains and NHTSA-registered testing partnerships. These suppliers concentrate production in Germany, Japan, and United States assembly corridors.
- Vehicle Assemblers:Contract manufacturers integrate complete active restraint modules during final assembly, dependent on Tier-1 supply schedules.
- Aftermarket Providers:Channel participants face certification barriers as OEM liability frameworks restrict sensor calibration access to factory-authorized diagnostic equipment.
OEMs retain specification control; Tier-1 suppliers hold manufacturing concentration.
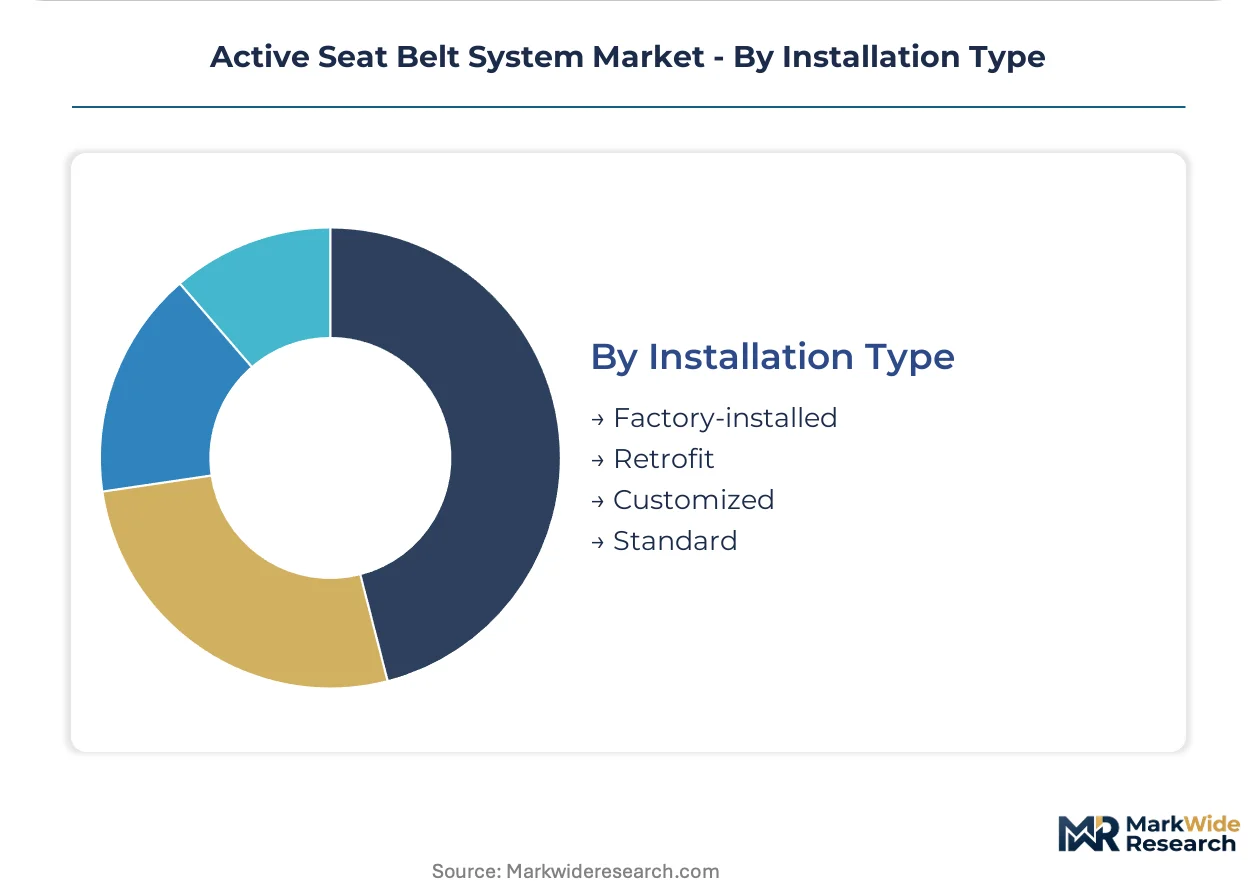
Installation Type:
Application maturity separates factory-integrated platforms with full sensor fusion from retrofit channels constrained by diagnostic access limitations.
- Factory-installed:Complete sensor-to-retractor calibration occurs during vehicle assembly, with electromechanical systems integrated into ADAS controller area networks. United States and German assembly plants mandate this installation mode for premium platforms.
- Retrofit:Post-assembly installation of pneumatic active belt systems serves North American heavy-truck fleet operators where insurance underwriters mandate active restraint inclusion. Calibration complexity restricts this channel to mechanical-only configurations.
- Customized:Specialized pretensioner tuning for motorsport and limited-production vehicles requires manual calibration protocols.
- Standard:Baseline mechanical retractor installations without active pretensioning serve economy vehicle segments.
Factory-installed deployment dominates value pools; retrofit channels face steepest access barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, Japan, and the United States consume active seat belt systems through divergent pathways: German OEMs prioritize predictive pretensioning for luxury platforms, Japanese assemblers enforce offset-crash compliance through regulatory mandate, and US manufacturers respond to NHTSA force-limiter tightening with reactive load-limiting technology.
United States
NHTSA's updated FMVSS 209 standards mandate faster pretensioner response times and stricter chest-deflection limits for frontal crash protection. Assembly plants in Michigan and Ohio integrate electromechanical retractors at scale for premium truck and SUV platforms. Insurance underwriters now mandate active restraint inclusion for preferred risk ratings in long-haul freight operations.
Germany
Luxury OEMs in Bavaria and Baden-Württemberg specify predictive pretensioning capabilities that reduce occupant submarining risk through ADAS convergence. ECE R16 harmonization across European type approvals standardizes anchor strength and retractor durability specifications. Continental AG anchors European OEM relationships through localized R&D centers in Stuttgart and Ingolstadt.
Japan
The Ministry of Land, Infrastructure, Transport and Tourism enforces offset crash testing that effectively requires active pretensioner inclusion in domestic-market vehicles. Vehicle assemblers in Aichi Prefecture and the Kanto region favor integrated architectures combining retractor mechanisms with seat position sensors. Tokai Rika Co. Ltd. occupies a position within the supplier tier serving these platform requirements.
South Korea
Hyundai Mobis exemplifies the scale-driven archetype among domestic safety component manufacturers serving Hyundai-Kia Automotive Group platforms. The Seoul Capital Area concentrates electromechanical retractor production for export-bound vehicles. Korean OEMs are adopting reactive force limiter technology to meet diverging US and European regulatory requirements without full electromechanical cost burdens.
China
Domestic OEMs in the Yangtze River Delta and Pearl River Delta are expanding electromechanical retractor adoption as ADAS penetration deepens across premium vehicle segments. Joyson Group represents the integrated supplier archetype within this market, though specific platform relationships remain proprietary. Local assembly plants face extended qualification timelines for polymer webbing formulations meeting NHTSA flammability standards.
Active Seat Belt System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding sensor-to-retractor calibration relationships and the lower tier competing on mechanical component supply. The market structure concentrates around vertically integrated safety electronics pipelines, electromechanical component specialists, and legacy mechanical belt fabricators facing talent migration pressures. Three archetypes dominate: integrated sensor-retractor pipeline operators, regional R&D-anchored platform partners, and scale-manufacturing conglomerates serving multiple OEMs. Competitive moves center on backward integration into sensor supply and geographic co-location with major assembly corridors.
Within the integrated pipeline tier, Autoliv Inc. and ZF Friedrichshafen AG exemplify the vertically consolidated archetype controlling electromechanical component supply chains. Continental AG occupies a position as the R&D-anchored partner for European OEM relationships. Among Asia-Pacific suppliers, DENSO Corporation represents the scale-manufacturing conglomerate archetype with multi-domain safety system exposure. These three companies sit within distinct strategic positions: Autoliv and ZF emphasize upstream control over sensor-to-retractor synchronization, while Continental leverages proximity engineering for platform-specific customization in Germany.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Continental AG |
| DENSO Corporation |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Joyson Group |
| Tokai Rika Co. Ltd. |
| GWR Safety Systems |
| Far Europe Inc. |
| Others |
Cost & Logistics Intelligence
Electromechanical retractor displacement of pyrotechnic pretensioners simultaneously shifts supply geography toward German and Japanese motor manufacturing clusters while compressing pricing premiums for single-cycle mechanical alternatives. This substitution dynamic concentrates component sourcing in electromechanical supply corridors and fragments legacy belt fabricators into price-competitive tiers.
Pricing Analysis
Long-term offtake agreements dominate procurement between OEMs and Tier-1 suppliers, locking in electromechanical retractor volumes across multi-year platform cycles. Price differentiation separates factory-integrated ADAS-convergent systems from retrofit pneumatic configurations, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from pyrotechnic material cost volatility in specialized chemical processors, compressing margin pools for mechanical belt suppliers. Aftermarket providers exhibit highest price sensitivity due to diagnostic equipment barriers, while luxury OEMs absorb premium electromechanical costs for predictive pretensioning capabilities.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific textile producers face extended qualification timelines at NHTSA-registered laboratories, creating bottlenecks for polymer webbing formulations seeking US market entry. Supply concentrates in Germany, Japan, and the United States, with electromechanical component production anchored in Stuttgart, Aichi Prefecture, and Michigan assembly corridors. Raw material dependencies include gas generant compounds, DC motor assemblies, and deformation-sensitive torsion bars. Single-source vulnerability concentrates in specialized chemical processors for initiator compounds. Distribution runs through OEM platform engineering teams and Tier-1 supplier manufacturing scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The active seat belt system market sits at a high-growth disruption driven by NHTSA's force-limiter tightening and electromechanical-ADAS convergence, creating asymmetric opportunity for integrated sensor-retractor pipeline operators over legacy mechanical fabricators.
For Market Incumbents: Secure backward integration into sensor supply and crash algorithm development to defend against electromechanical specialist entrants. Anchor manufacturing scale in Germany, Japan, and US assembly corridors where OEM platform relationships concentrate. Prioritize NHTSA-registered testing partnerships to accelerate certification throughput for polymer webbing formulations. For New Entrants and Emerging Players: Aftermarket diagnostic service gaps where OEM liability frameworks restrict sensor calibration access offer white-space penetration. Target North American heavy-truck fleet operators where insurance underwriters mandate active restraint inclusion. Pursue pneumatic system retrofit partnerships with commercial vehicle distributors lacking factory-authorized equipment. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated electromechanical pipeline operators over legacy mechanical belt fabricators facing mechatronics talent migration. Long-term viability favors sensor-to-retractor synchronization capabilities and ADAS controller integration. Watch for divergence resolution between UN R16 harmonization and NHTSA sled-test protocols as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Retractor Platform Standardization | Enables ADAS convergence with autonomous emergency braking architectures across German and Japanese OEM platforms. |
| Backward Integration into Crash Sensor Supply | Captures sensor-to-retractor synchronization value pools currently concentrated at Autoliv and ZF Friedrichshafen. |
| NHTSA-Registered Laboratory Partnership | Accelerates polymer webbing qualification timelines for Asian textile producers seeking US market entry. |
| Heavy-Duty Commercial Fleet Retrofit Program | Addresses insurance underwriter mandates for active restraint inclusion in North American long-haul freight operations. |
| Localized R&D Center Establishment | Replicates Continental's Stuttgart proximity engineering model for platform-specific OEM customization in Germany. |
Research Approach
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, NHTSA regulatory affairs specialists, and aftermarket distribution operators provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from FMVSS filing databases, ECE R16 type approval records, vehicle production registries, and electromechanical component trade data. Bottom-up retractor shipment analysis and top-down OEM platform content modeling were triangulated for consistency.
Consistency checks validated volume and value outputs against external benchmarks including IHS Markit vehicle registration data and supplier SEC disclosure patterns. The analytical framework modeled segmentation across technology type, installation mode, vehicle class, and regional production cluster throughout the projection horizon. CAGRs were derived from electromechanical content-per-vehicle trajectories and regulatory mandate phase-in schedules across the analysis window.
Underlying assumptions cover NHTSA force-limiter enforcement timelines, ECE R16 harmonization progress, and electromechanical cost curve trajectories, with deviation risk concentrated in pyrotechnic material supply disruptions and UN-NHTSA protocol divergence persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Portable Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market