
 Asia-Pacific Process Safety Services Market | 2026-2036
Asia-Pacific Process Safety Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Process Safety Services Market Outlook
Asset-light service contracting and performance-based leasing arrangements is rewriting competitive entry barriers across the Asia-Pacific process safety landscape. Bureau Veritas leverages its marine-certification heritage to anchor offshore oil and gas safety contracts across Southeast Asian waters. Schneider Electric competes through integrated power-and-safety automation bundles that reduce client capital outlay. Emerson Electric Co. sustains technology leadership in safety instrumented systems diagnostics for high-risk chemical processes.
Process safety services encompass engineered consulting, workforce training, systematic auditing, and regulatory compliance verification designed to prevent catastrophic releases, fires, and explosions in hazardous industrial operations; practitioners apply quantitative risk analysis methodologies such as layers of protection analysis and safety integrity level calculations to establish tolerable failure frequencies, typically targeting risk reduction factors from ten to ten-thousand depending on process severity. Consulting and auditing services command the deepest margin pools where specialist engineering hours carry premium pricing, while training services face commoditization from digital module proliferation. Safety instrumented systems technology dominates capital-linked revenue streams as plants retrofit aging distributed control architectures with independent shutdown logic.
Australia's Work Health and Safety Act, China's GB standards administered by SAMR, and India's CEA electrical safety directives collectively mandate systematic hazard identification and documented risk reduction across process industries, creating compliance-driven demand that resists discretionary budget cuts. Japan's METI has tightened high-pressure gas safety regulations, forcing refinery and petrochemical operators to expand third-party inspection frequency. Stakeholders must monitor how national carbon-neutrality timelines reshape capital allocation between brownfield safety upgrades and new greenfield process designs.
Market Dynamics
Asset-light service contracting and performance-based leasing arrangements are rewriting competitive entry barriers across the Asia-Pacific process safety landscape, as refinery operators and chemical manufacturers seek to convert fixed safety compliance costs into variable operational expenditures.
Growth Catalysts
- Regulatory tightening:Japan's METI has expanded third-party inspection mandates for high-pressure gas facilities, forcing refinery and petrochemical operators to increase external safety audit frequency.
- Industrial corridor concentration:China's chemical manufacturing corridor around the Yangtze River Delta is generating concentrated demand for third-party safety auditing and compliance verification services.
- Digital safety instrumentation:Safety instrumented systems diagnostics technology is driving retrofit demand as aging distributed control architectures require independent shutdown logic upgrades.
Market Restraints
- Specialist engineering scarcity:Consulting and auditing services depend on premium-priced specialist engineering hours that face supply constraints across Southeast Asian markets.
- Training commoditization:Digital module proliferation is compressing margins in workforce training services, eroding pricing power for traditional instructor-led programs.
- Capital intensity of retrofits:Safety instrumented systems technology deployment requires substantial capital outlay that discretionary budgets resist during energy price volatility.
Strategic Opportunities
- Integrated automation bundles:Power-and-safety automation convergence creates openings for vendors to reduce client capital outlay through unified platform offerings.
- Offshore oil and gas expansion:Southeast Asian waters present underpenetrated demand for marine-certification-anchored safety services in offshore extraction operations.
- Carbon-neutrality capital reallocation:National net-zero timelines in China, Japan, and South Korea are redirecting investment toward greenfield process designs with embedded safety systems.
Industry Challenges
- Quantitative risk analysis talent gap:Practitioners skilled in layers of protection analysis and safety integrity level calculations remain scarce relative to compliance audit demand.
- Legacy system integration friction:Retrofitting independent shutdown logic into aging distributed control architectures creates technical complexity and operational disruption risks.
- Multi-jurisdiction certification timelines:Australia's Work Health and Safety Act, China's GB standards, and India's CEA directives impose overlapping compliance requirements that extend project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Process Safety Services Market |
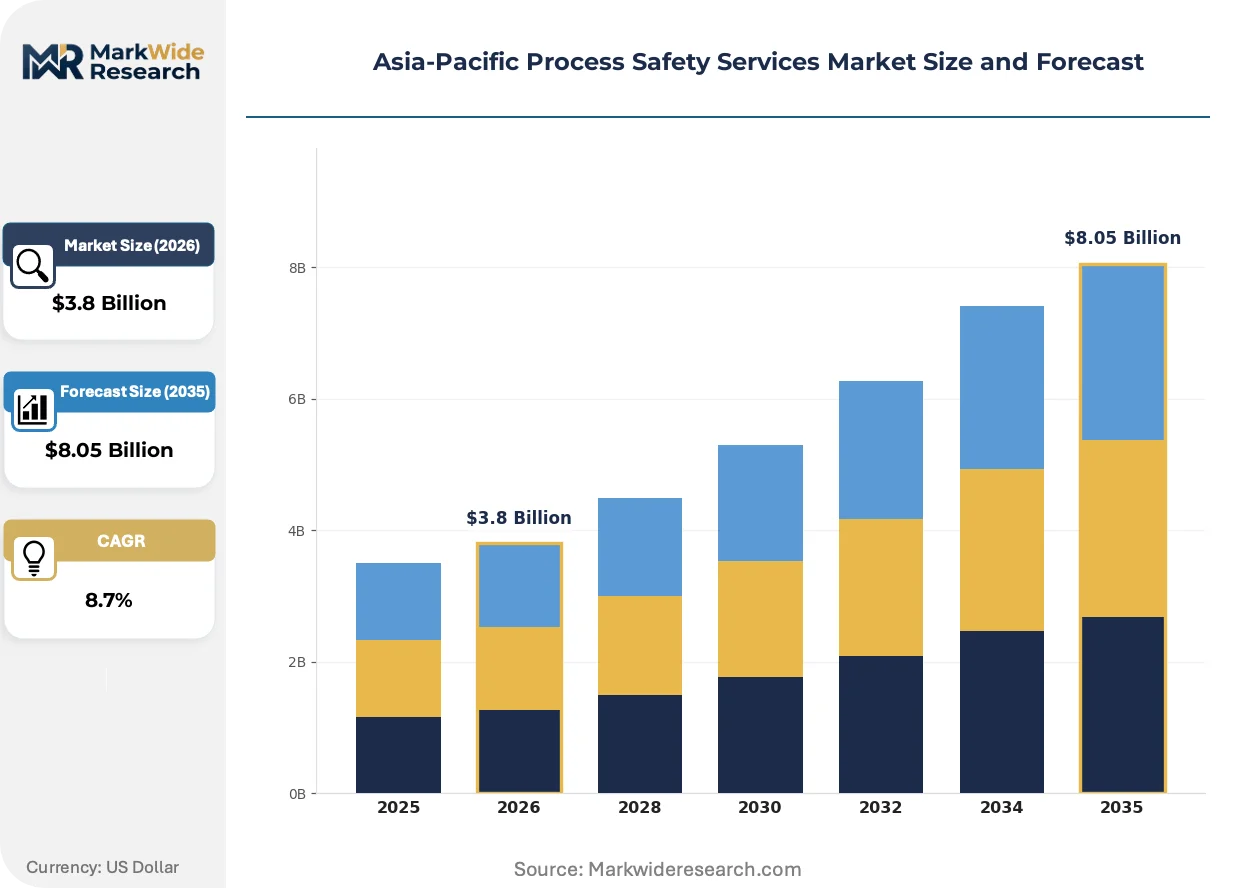
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Training, Auditing, Compliance Technology: Risk Analysis, Safety Instrumented Systems, Emergency Response, Incident Investigation End User: Chemical Manufacturing, Oil & Gas, Pharmaceuticals, Food Processing Application: Hazard Identification, Safety Management, Regulatory Compliance, Process Optimization |
| Companies Covered | Emerson Electric Co., Rockwell Automation, Siemens, ABB, Bureau Veritas, Honeywell International Inc., Schneider Electric, Intertek Group plc, Johnson Controls, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Process Safety Services Market Strategic Shifts
Digital twin technology and remote monitoring platforms are actively restructuring how process safety services are delivered, compressing the need for physical site presence while elevating real-time diagnostic capabilities.
Cloud-based safety training platforms are virtualizing workforce certification programs that previously required dedicated instructor-led sessions. Chemical manufacturers in South Korea and Singapore are adopting these modules at accelerated pace to meet recurring competency requirements. This virtualization is compressing training delivery costs while expanding addressable markets for safety education providers.
China's GB standards administered by SAMR are mandating documented risk reduction methodologies across process industries, with specific requirements for quantitative hazard identification. The industrial consequence is elevated demand for third-party engineering consultancies capable of certifying compliance documentation. High-risk chemical processes in the Yangtze River Delta are most affected, with operators expanding procurement of external auditing services.
Refinery operators across Southeast Asia are unbundling after-sales service contracts from original equipment manufacturer supply agreements. Third-party safety service providers are capturing maintenance and diagnostic work that incumbents previously monopolized. This pattern is most visible in Thailand and Indonesia, where national oil companies have centralized procurement functions seeking specialist independence from vendor-tied service arrangements.
Asia-Pacific Process Safety Services Market Segmentation
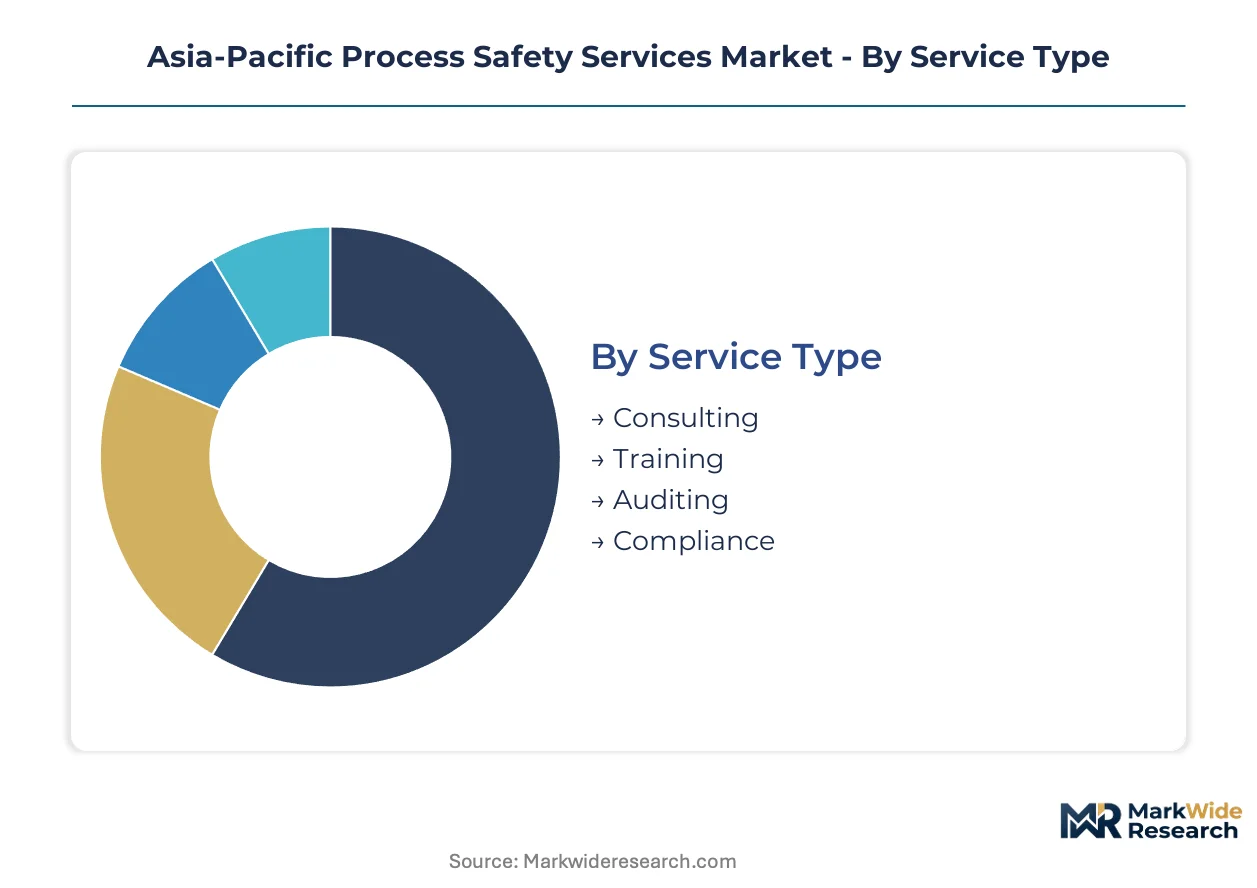
Process safety services fragment across four dimensions that reshape procurement patterns and margin structures. Service type determines whether providers capture recurring revenue or project-based fees. Technology segmentation separates capital-intensive hardware deployment from advisory consulting. End-user concentration in chemical corridors and oil basins dictates geographic service density.
Service Type:
Cost tier separates premium specialist hours from commoditized digital delivery.
- Consulting:Quantitative risk analysis and layers of protection analysis require certified functional safety engineers. Yangtze River Delta chemical manufacturers procure external engineering consultancies to certify compliance documentation under SAMR's GB standards. Specialist scarcity sustains premium pricing.
- Training:Workforce certification programs face compression from cloud-based module proliferation. South Korean and Singaporean chemical manufacturers adopt virtualized training to meet recurring competency requirements. Digital delivery erodes margins for instructor-led programs.
- Auditing:Third-party inspection mandates from Japan's METI expand external audit frequency for high-pressure gas facilities.
- Compliance:Documentation verification services concentrate where multi-jurisdiction certification timelines overlap.
Consulting holds installed capacity. Training is rotating up the share rankings through digital scale.
Technology:
Application maturity separates legacy retrofit demand from embedded greenfield design.
- Risk Analysis:Layers of protection analysis and safety integrity level calculations establish tolerable failure frequencies. Practitioners target risk reduction factors from ten to ten-thousand depending on process severity. Talent scarcity constrains audit throughput.
- Safety Instrumented Systems:Independent shutdown logic retrofits aging distributed control architectures. Capital intensity resists discretionary budgets during energy price volatility. Diagnostics technology sustains recurring service attachments.
- Emergency Response:Real-time monitoring platforms compress physical site presence requirements.
- Incident Investigation:Root cause analysis services activate post-event, creating lumpy revenue patterns.
Safety instrumented systems dominate capital-linked revenue. Risk analysis commands the steepest expansion trajectory in headcount-constrained markets.
End User:
Volume concentration tracks hazardous process intensity and regulatory enforcement stringency.
- Chemical Manufacturing:High-risk processes around the Yangtze River Delta generate concentrated demand for third-party safety auditing. China's dual carbon goals redirect investment toward greenfield designs with embedded safety systems.
- Oil & Gas:Offshore extraction operations in Southeast Asian waters present underpenetrated demand for marine-certification-anchored services. Thailand and Indonesia national oil companies unbundle after-sales contracts from OEM supply agreements.
- Pharmaceuticals:Batch process safety requirements drive specialized containment verification services.
- Food Processing:Combustible dust hazard controls expand auditing demand in grain handling and spray drying operations.
Chemical manufacturing anchors regional procurement volume. Oil and gas is gaining share fastest through offshore contract unbundling.
Application:
Customer type separates compliance-driven mandatory spend from discretionary optimization projects.
- Hazard Identification:Systematic hazard identification mandates under Australia's Work Health and Safety Act create baseline demand. Documented risk reduction requirements resist budget cuts.
- Safety Management:Integrated power-and-safety automation bundles reduce client capital outlay. Unified platform offerings capture procurement from fragmented legacy architectures.
- Regulatory Compliance:Multi-jurisdiction certification across Australia's WHS Act, China's GB standards, and India's CEA directives extends project timelines.
- Process Optimization:Discretionary efficiency projects face deferral risk when capital allocation shifts to carbon-neutrality timelines.
Hazard identification holds regulatory-mandated baseline volume. Safety management is climbing the fastest through automation convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's high-pressure gas inspection market while Vietnam and Indonesia compete on cost for offshore safety contracting. Australia's Work Health and Safety Act enforcement creates premium audit demand. China's Yangtze River Delta corridor generates the deepest volume pools for third-party engineering consultancies.
China
Chemical manufacturers around the Yangtze River Delta procure external engineering consultancies to certify compliance documentation under SAMR's GB standards. The country's dual carbon goals redirect investment toward greenfield process designs with embedded safety systems. High-risk chemical processes in Shanghai and Jiangsu province are expanding procurement of external auditing services.
Japan
Refinery and petrochemical operators face expanded third-party inspection mandates from METI for high-pressure gas facilities. The Kansai industrial corridor around Osaka generates concentrated demand for safety instrumented systems diagnostics. Japanese operators are increasing external safety audit frequency to meet tightened regulatory timelines.
Australia
The Work Health and Safety Act mandates systematic hazard identification across process industries, creating compliance-driven demand that resists discretionary budget cuts. Mining operations in Western Australia and Queensland procure specialized containment verification services. Documented risk reduction requirements sustain premium pricing for specialist engineering hours.
South Korea
Chemical manufacturers in the Ulsan and Yeosu industrial complexes adopt cloud-based safety training platforms at accelerated pace to meet recurring competency requirements. MFDS pharmaceutical batch process safety requirements drive specialized containment verification services. Virtualized training delivery is compressing costs while expanding addressable markets.
Indonesia
National oil company Pertamina has centralized procurement functions seeking specialist independence from vendor-tied service arrangements. Offshore extraction operations in the Java Sea present underpenetrated demand for marine-certification-anchored safety services. Third-party providers are capturing maintenance and diagnostic work previously monopolized by original equipment manufacturers.
Asia-Pacific Process Safety Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in diagnostics and verification niches. The vendor base separates into consolidated automation conglomerates, diversified testing-and-inspection networks, and specialist engineering boutiques. Three archetypes dominate: integrated power-safety bundlers, marine-certification-anchored offshore contractors, and independent shutdown logic retrofitters. Competitive moves concentrate on unbundling after-sales service contracts from OEM supply agreements and converging power-and-safety automation into unified platform offerings.
Among diversified testing-and-inspection networks, Bureau Veritas occupies a position exemplifying marine-certification heritage applied to offshore oil and gas safety contracts. Schneider Electric represents the integrated power-safety automation bundler archetype, while Emerson Electric Co. anchors the independent shutdown logic retrofitter tier. These three names illustrate how competitive positioning fragments across service delivery models rather than consolidating around single-technology dominance.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Rockwell Automation |
| Siemens |
| ABB |
| Bureau Veritas |
| Honeywell International Inc. |
| Schneider Electric |
| Intertek Group plc |
| Johnson Controls |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in specialist engineering talent across Southeast Asian markets is compressing margins for training services while inflating premium rates for quantitative risk analysis consulting. This utilization imbalance forces service providers to segment delivery models aggressively, pushing commoditized offerings toward digital platforms while reserving high-value engineering hours for compliance-critical audits.
Pricing Analysis
The customization-premium spread separates configured-to-order safety instrumented systems diagnostics from standardized cloud-based training modules. Project-based consulting fees for layers of protection analysis command substantial premiums over subscription-tier digital certification programs. Price differentiation hinges on certification grade under SAMR's GB standards and the geographic delivery cost of deploying functional safety engineers to offshore extraction sites. Pricing pressure stems from digital module proliferation eroding instructor-led program margins. Chemical manufacturers in South Korea and Singapore exhibit lowest price sensitivity for compliance-critical auditing, while grain handling operations in food processing show highest sensitivity to training cost compression.
Supply Chain Analysis
Tariff exposure between China and key component source markets in Germany and Japan elevates input costs for safety instrumented systems hardware. Geographic supply concentration centers on China for distributed control architecture components, Japan for high-reliability instrumentation, and South Korea for integrated automation platforms. Raw material dependencies include specialized semiconductors for shutdown logic controllers, corrosion-resistant alloys for offshore environments, and engineered polymers for containment systems. Single-source vulnerability persists in advanced diagnostics chipsets. Distribution runs through direct OEM service networks in legacy installations and emerging third-party specialist channels in unbundled procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital training platforms threaten incumbent consulting margins by substituting virtualized competency certification for premium engineering hours. Incumbents must architect defensive positioning that preserves high-value audit relationships against this automation pressure.
For Market Incumbents: Build regulatory certification moats by deepening SAMR GB standards compliance verification capabilities in the Yangtze River Delta. Anchor client relationships through multi-year performance-based leasing arrangements that convert capital expenditure into operational expenditure. Vertical integration into cloud-based diagnostics platforms captures recurring revenue streams threatened by pure-play software entrants. Defend specialist engineering capacity through apprenticeship pipelines targeting quantitative risk analysis talent scarcity.
For New Entrants and Emerging Players: Pursue offshore oil and gas safety contracting in Indonesia's Java Sea and Thailand's Gulf waters where marine-certification heritage creates entry barriers for land-focused competitors. Target unbundled after-sales service contracts at Pertamina and other national oil companies seeking vendor independence. White-space exists in integrated power-and-safety automation bundles for greenfield chemical processes under China's dual carbon goals. Go-to-market leverage rests on partnerships with established marine surveyors possessing existing offshore operator relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because national carbon-neutrality timelines in China, Japan, and South Korea mandate sustained capital allocation toward process safety infrastructure. Acquisition targets should emphasize specialist engineering boutiques with certified functional safety engineers and established SAMR documentation relationships. Watch for inflection in METI inspection mandate expansion beyond high-pressure gas into adjacent petrochemical processes as the signal for audit volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Leasing Arrangements | Converts fixed safety compliance costs into variable operational expenditure for refinery operators. |
| Integrated Power-Safety Automation Bundles | Schneider Electric's unified platform reduces client capital outlay against fragmented legacy architectures. |
| Marine-Certification Service Expansion | Bureau Veritas leverages offshore heritage to capture underpenetrated Southeast Asian extraction demand. |
| Digital Training Platform Virtualization | Cloud-based modules compress delivery costs while expanding addressable markets for safety education. |
| Third-Party Audit Unbundling | Specialist independents capture maintenance work previously monopolized by original equipment manufacturers. |
Study Parameters
A spread of perspectives from plant safety managers at Yangtze River Delta chemical facilities, procurement leads at Indonesian national oil companies, functional safety engineers at certification bodies, and aftermarket service heads at automation OEMs converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SAMR GB standards documentation, METI regulatory filings, Australia's Work Health and Safety Act enforcement records, and customs data tracking safety instrumentation trade flows. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions included service type, technology application, end-user industry concentration, and regional regulatory enforcement stringency. CAGRs derived from weighted scenario analysis incorporating capital expenditure cycles, inspection mandate expansion timelines, and digital substitution elasticities. Industry-specific inputs encompassed refinery turnaround schedules, offshore licensing rounds, and carbon-neutrality capital reallocation patterns.
Sensitivities concentrate around METI mandate expansion velocity, digital training platform adoption curves, and specialist engineering graduation rates. Forecasts embed assumptions regarding sustained regulatory enforcement and continued unbundling of OEM service contracts. Macroeconomic deviation, regulatory enforcement relaxation, or breakthrough automation in quantitative risk analysis would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market