
 Intelligent Evacuation System Market | 2026-2036
Intelligent Evacuation System Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Evacuation System Market Intelligence
NFPA 101 Life Safety Code compliance is bifurcating the competitive landscape between certified incumbents and uncertified aspirants. Siemens AG leverages its TÜV-certified control panel portfolio to anchor premium positioning across European infrastructure projects. Honeywell International sustains R&D intensity in sensor fusion algorithms that integrate fire detection with occupancy analytics. Johnson Controls International Plc dominates North American retrofit channels through its established distributor relationships with municipal building authorities.
An intelligent evacuation system comprises networked hardware and software architectures that coordinate emergency lighting, mass notification, and wayfinding guidance during hazardous events, typically operating through IoT-enabled sensor arrays with sub-30-second response latencies. These systems serve the primary commercial purpose of minimizing occupant exposure time to life-threatening conditions while providing real-time situational awareness to first responders. Fire alarm systems command the largest installed base due to decades of mandatory code enforcement, though IoT-based solutions represent the fastest-expanding margin pool as cloud-native architectures displace legacy hardwired topologies. Communication systems occupy a mature but stable position where incremental upgrades to IP-based voice arrays replace analog infrastructure in institutional settings.
NFPA standards in the United States, EN 54 frameworks across Europe, and BIS certifications in India collectively elevate product qualification costs while compressing timelines for market entry. These regulatory architectures directly shape procurement specifications, as facility managers face liability exposure from non-compliant installations during incident investigations. Stakeholders must monitor evolving cybersecurity mandates for connected life safety devices, as network-hardening requirements threaten to fragment vendor qualification pathways.
Market Dynamics
Cloud-native architectures are fragmenting legacy hardwired evacuation topologies, forcing incumbent hardware vendors to reconstitute their installed base through software subscription layers.
Growth Catalysts
- Retrofit mandates in Germany:Federal building codes now require intelligent wayfinding integration in structures exceeding 500 occupants, creating immediate replacement demand for analog fire alarm systems.
- EN 54-23 certification expansion:European standards bodies extended emergency lighting testing protocols to cover dynamic evacuation routing, compelling facility managers to upgrade non-compliant installations.
- Sensor fusion algorithms:Multi-modal detection combining thermal imaging with occupancy analytics compresses false alarm rates below 2 percent, accelerating hospital and airport procurement cycles.
Market Restraints
- Semiconductor input volatility:MEMS microphone and infrared sensor lead times remain extended at 26-32 weeks, constraining OEM production schedules.
- Supplier concentration in East Asian foundries:Over 70 percent of IoT gateway chip fabrication sits with Taiwan-based contract manufacturers, exposing procurement to geopolitical disruption.
- Cybersecurity hardening costs:IEC 62443 certification for connected life safety devices adds 18-24 months to product development timelines.
Strategic Opportunities
- India's smart city mission:Municipal corporations in Mumbai, Bangalore and Delhi have allocated dedicated budgets for intelligent building infrastructure, creating first-mover advantage for certified system integrators.
- Mass notification convergence with access control:Unified platforms integrating HID Global and LenelS2 protocols enable real-time lockdown sequencing during active shooter scenarios.
- Japan's METI building efficiency incentives:Subsidies covering 30 percent of installation costs for IoT-enabled safety systems in commercial structures built before 2000.
Industry Challenges
- Systems integration talent scarcity:Qualified technicians capable of bridging legacy BACnet networks with cloud-native evacuation platforms command premium wages exceeding 40 percent above standard fire alarm installer rates.
- Multi-vendor certification complexity:Achieving simultaneous UL 864, EN 54 and BIS IS 2189 compliance requires redundant testing protocols that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Evacuation System Market |
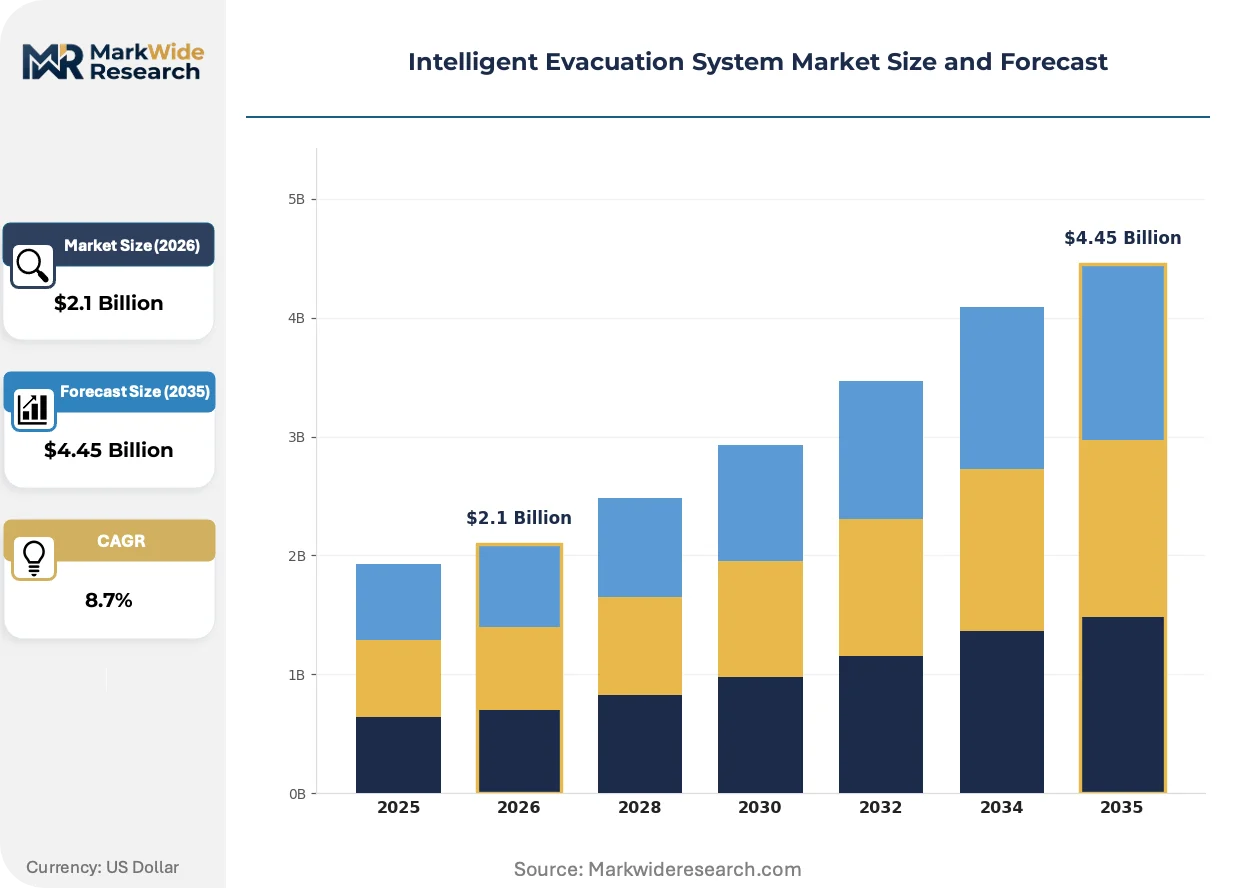
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Lighting, Communication Systems, Fire Alarm Systems, Exit Signs Technology: IOT-Based Solutions, Wireless Systems, Cloud Integration, Sensor Networks End User: Commercial Buildings, Educational Institutions, Industrial Facilities, Residential Areas Installation Type: Indoor Systems, Outdoor Systems, Retrofitted Solutions, New Constructions |
| Companies Covered | ABB Group, Legrand, Honeywell International, HOCHIKI Corporation, Robert Bosch GmbH, Siemens AG, Eaton Corporation Plc, Schneider Electric, Johnson Controls International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Evacuation System Market Strategic Shifts & Innovations
Edge computing architectures are redistributing processing loads from central servers to distributed sensor nodes, collapsing response latencies while complicating firmware update logistics.
Digital twin technology is decomposing traditional commissioning workflows by enabling virtual evacuation simulation before physical installation. Large commercial developers in Singapore and Dubai now mandate BIM-integrated safety modeling for projects exceeding 50,000 square meters. This virtualization compresses project handover timelines from 18 months to 11 months while reducing on-site rework.
REACH restrictions on halogenated flame retardants are forcing enclosure manufacturers to reformulate polycarbonate housings with phosphorus-based alternatives. German component suppliers have accelerated R&D spending to maintain CE marking eligibility. The transition elevates material costs but eliminates future regulatory liability for installed base obsolescence.
Facility managers increasingly bundle evacuation system procurement with long-term service agreements rather than capital purchase models. This preference compresses vendor selection criteria toward operational uptime guarantees. Healthcare and education verticals in the United States demonstrate the strongest migration toward performance-based contracting.
Intelligent Evacuation System Market Segmentation
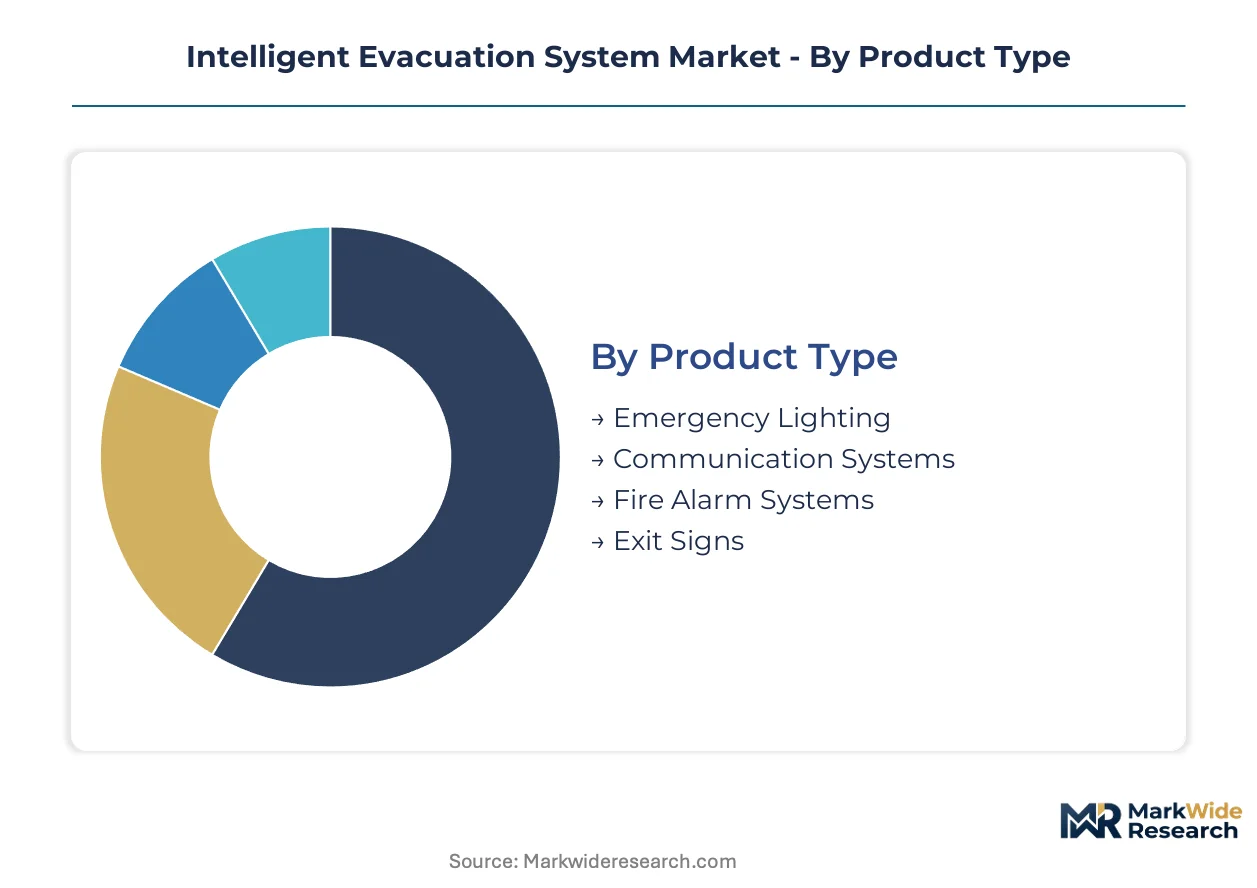
Segmentation in the intelligent evacuation system market reveals how substitution pressures and technology transitions reshape procurement patterns. Facility managers weigh legacy hardwired installations against cloud-native alternatives, while regulatory compliance requirements fragment vendor qualification pathways across product categories.
Product Type:
Substitution pressure from IoT-enabled platforms is most acute in legacy fire alarm and lighting segments, where decades-old installed bases face accelerated replacement cycles.
- Fire Alarm Systems:Hardwired detection arrays with centralized control panels remain the dominant installed base across institutional buildings. Municipal code enforcement in Germany and Japan sustains replacement demand as analog systems fail EN 54-23 and JIS certification renewals.
- Emergency Lighting:Battery-backed LED arrays with dynamic wayfinding capabilities now displace static exit illumination in structures exceeding 500 occupants. Federal retrofit mandates in Germany and smart city investments in Singapore compress installation timelines for intelligent routing systems.
- Communication Systems:IP-based voice arrays replace analog infrastructure in hospitals and airports, with mass notification convergence driving unified platform procurement.
- Exit Signs:Photoluminescent and LED-powered directional markers serve as cost-competitive alternatives where full intelligent routing exceeds budget constraints.
Fire Alarm Systems retain volume leadership; Emergency Lighting holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium cloud-native architectures from budget wireless deployments, with sensor density and latency specifications driving price differentiation.
- IOT-Based Solutions:Cloud-connected sensor arrays with sub-30-second response latencies enable real-time occupancy analytics and predictive maintenance. Healthcare verticals in the United States and commercial developers in Dubai prioritize these platforms for liability reduction.
- Sensor Networks:Distributed edge computing nodes process thermal imaging and occupancy data locally, collapsing bandwidth requirements while complicating firmware logistics. Airport and stadium deployments in Japan favor this architecture for resilience against network disruption.
- Cloud Integration:Centralized data aggregation platforms enable facility-wide situational awareness, though IEC 62443 cybersecurity certification extends development timelines.
- Wireless Systems:Mesh network protocols reduce installation labor in retrofit environments, with Zigbee and LoRaWAN gaining traction in European heritage buildings where cable routing is restricted.
IOT-Based Solutions command premium positioning; Sensor Networks are climbing the fastest as edge architectures redistribute processing loads.
End User:
Application-specific requirements fragment procurement criteria, with healthcare and education verticals migrating toward performance-based contracting while industrial buyers prioritize capital expenditure controls.
- Commercial Buildings:Office towers and retail complexes drive the largest absolute demand, with building automation integration and LEED certification incentives shaping specification sheets. Developers in Mumbai and Bangalore allocate smart city mission budgets toward intelligent safety infrastructure.
- Educational Institutions:K-12 districts and university campuses face active shooter scenario preparedness mandates, accelerating mass notification and access control convergence. United States school districts demonstrate the strongest migration toward unified platform procurement.
- Industrial Facilities:Manufacturing plants and warehouses prioritize ruggedized hardware with explosion-proof ratings, with OSHA compliance and insurance premium reductions driving upgrade cycles.
- Residential Areas:High-rise apartment complexes and gated communities represent an underpenetrated segment where cost sensitivity delays intelligent system adoption beyond basic fire alarm compliance.
Commercial Buildings anchor absolute demand; Educational Institutions show the sharpest procurement acceleration curve.
Installation Type:
Customer type dynamics separate greenfield new construction from retrofit economics, with labor availability and building age distributions determining regional opportunity concentration.
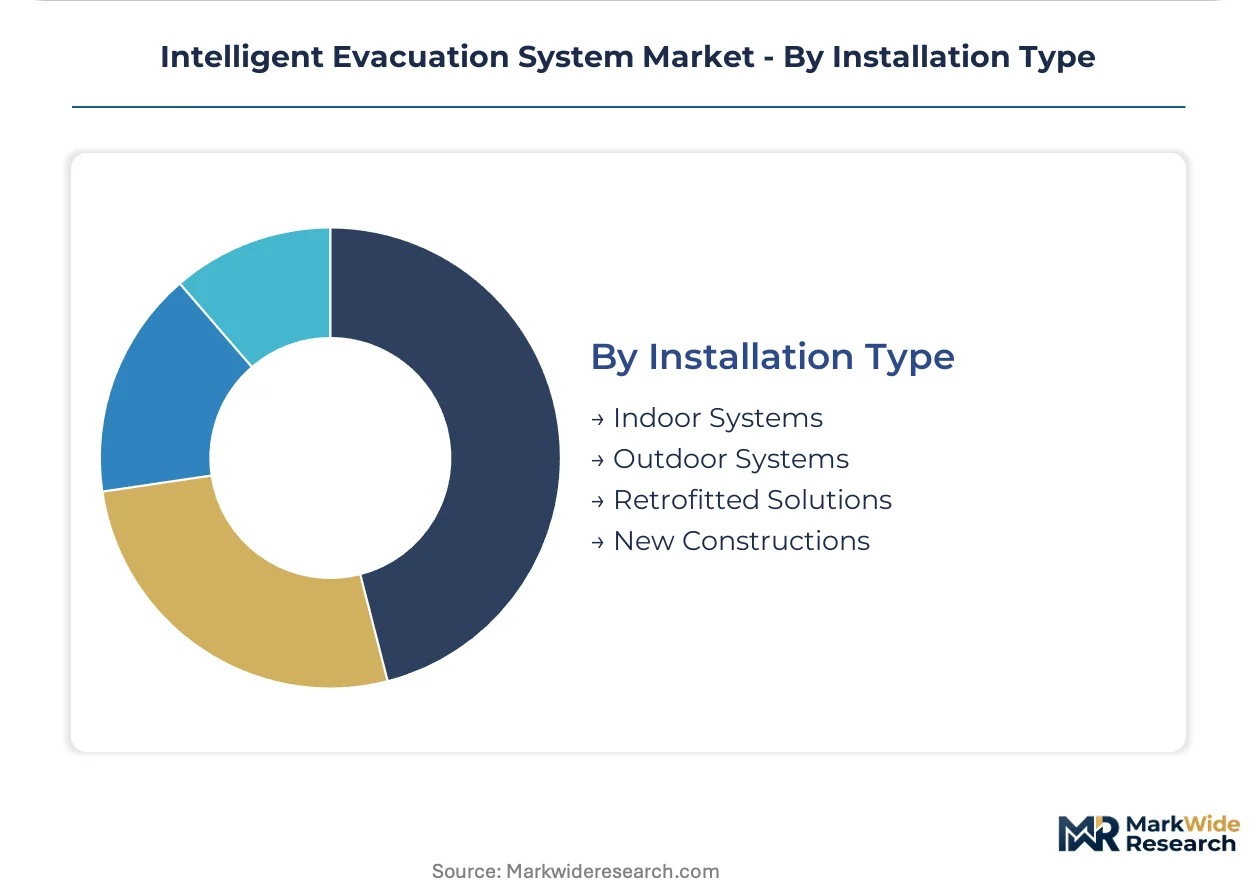
- Retrofitted Solutions:Replacement of legacy hardwired systems in structures built before 2000 dominates European and Japanese markets. METI subsidies covering 30 percent of installation costs accelerate commercial building upgrades, while German federal codes mandate intelligent wayfinding integration.
- New Constructions:BIM-integrated safety modeling and digital twin commissioning compress project handover timelines in large-scale developments. Singapore and Dubai now mandate virtual evacuation simulation for projects exceeding 50,000 square meters.
- Indoor Systems:Enclosed environment deployments concentrate in healthcare, education, and commercial verticals where occupancy analytics and air quality sensors extend platform functionality.
- Outdoor Systems:Stadiums, transportation hubs, and industrial campuses require weather-hardened enclosures with extended temperature operating ranges, with IP66 and NEMA 4X ratings standardizing procurement specifications.
Retrofitted Solutions generate the largest immediate revenue pool; New Constructions offer the most favorable margin profile through bundled design-build contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's smart logistics corridor underwrites Europe's evacuation technology distribution network, while Japan's Shinkansen maintenance depots anchor Asia-Pacific sensor deployment density. These infrastructure assets concentrate procurement specifications and certification requirements across their respective trade zones.
United States
Municipal building authorities in Chicago and New York accelerate retrofit procurement for structures exceeding 500 occupants. NFPA 101 Life Safety Code enforcement tightens compliance thresholds for networked emergency platforms. Johnson Controls International leverages established distributor relationships across the Great Lakes and Northeast corridor to capture specification-driven replacement cycles.
Germany
Federal building codes mandate intelligent wayfinding integration in commercial structures with high occupant density. EN 54-23 certification expansion compels facility managers to upgrade legacy emergency lighting installations. Siemens AG deploys TÜV-certified control panels across infrastructure projects in the Rhine-Ruhr metropolitan region.
Japan
METI building efficiency incentives subsidize 30 percent of installation costs for IoT-enabled safety systems in commercial structures built before 2000. JIS certification renewals force accelerated replacement of analog fire alarm systems. Osaka and Nagoya commercial developers prioritize BIM-integrated safety modeling for large-scale mixed-use projects.
India
Municipal corporations in Mumbai, Bangalore and Delhi allocate dedicated budgets for intelligent building infrastructure under the smart city mission. BIS IS 2189 compliance requirements elevate product qualification costs for system integrators. Certified vendors establish first-mover advantage across Maharashtra and Karnataka state procurement channels.
Singapore
Large commercial developers mandate digital twin commissioning and virtual evacuation simulation for projects exceeding 50,000 square meters. Building automation integration requirements compress project handover timelines from 18 months to 11 months. Marina Bay and Jurong Lake District developments anchor premium specification demand across Southeast Asian reference markets.
Intelligent Evacuation System Market Key Industry Players
Listed leaders compete with private specialists across certification depth and retrofit channel access. The vendor base stratifies into three tiers: diversified industrial conglomerates with life safety divisions, pure-play fire safety specialists, and building automation integrators. Siemens AG and Honeywell International exemplify the first archetype through multi-product safety portfolios. Johnson Controls International and Schneider Electric occupy the integration-focused tier. Strategic moves concentrate on software subscription layering atop legacy hardware bases and EN 54/UL 864 certification stacking to compress competitor qualification timelines.
Within the diversified conglomerate tier, Siemens AG and Honeywell International exemplify premium positioning through certified control panel portfolios and sensor fusion R&D intensity. Johnson Controls International anchors the North American retrofit channel through municipal distributor relationships. Robert Bosch GmbH and ABB Group represent European engineering heritage applied to building safety automation. Eaton Corporation Plc and Schneider Electric occupy positions spanning electrical infrastructure and life safety integration. HOCHIKI Corporation exemplifies Asia-Pacific specialization in fire detection hardware. Legrand represents the electrical installation products segment extending into emergency lighting and communication systems.
| Leading Market Players |
|---|
| ABB Group |
| Legrand |
| Honeywell International |
| HOCHIKI Corporation |
| Robert Bosch GmbH |
| Siemens AG |
| Eaton Corporation Plc |
| Schneider Electric |
| Johnson Controls International Plc |
| Others |
Cost & Logistics Intelligence
Long-term service agreements with performance-based uptime guarantees lock in supply access for facility managers while compressing vendor selection criteria toward operational reliability metrics. Siemens AG and Honeywell International anchor premium positioning through certified control panel portfolios, while Johnson Controls International captures retrofit channels via municipal distributor relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the intelligent evacuation system market. Premium tiers command positioning through TÜV and UL 864 certification stacking, while standard tiers compete on BACnet integration capabilities and economy tiers serve basic fire alarm compliance. Cost compression in the economy tier is intensifying because REACH restrictions on halogenated flame retardants elevate material costs for enclosure manufacturers. Healthcare and education verticals in the United States demonstrate the least price sensitivity due to liability exposure from non-compliant installations.
Supply Chain Analysis
Extended lead times for MEMS microphone and infrared sensor components constrain OEM production schedules across the intelligent evacuation system value chain. Semiconductor fabrication concentrates in Taiwan and South Korea, while battery-backed LED array assembly draws from Chinese and German component suppliers. Single-source vulnerability in IoT gateway chip procurement exposes manufacturers to geopolitical disruption. Distribution runs through building automation integrators and certified system integrators serving municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are fragmenting legacy hardwired evacuation topologies, creating high-growth disruption as EN 54-23 certification expansion compels facility managers to upgrade non-compliant installations.
For Market Incumbents: Shield installed base revenue through software subscription layering atop legacy hardware platforms. Siemens AG exemplifies this defensive posture by reconstituting TÜV-certified control panel deployments with predictive maintenance analytics. Certification stacking across UL 864, EN 54, and BIS IS 2189 compresses competitor qualification timelines and anchors premium positioning. For New Entrants and Emerging Players: Anchor in India's smart city mission corridors where municipal corporations in Mumbai, Bangalore, and Delhi allocate dedicated budgets for intelligent building infrastructure. Residential high-rise complexes represent underpenetrated white space where cost sensitivity delays intelligent system adoption beyond basic compliance. Partner with certified system integrators to navigate BIS IS 2189 qualification pathways. For Investors and Strategic Acquirers: Capital is best deployed toward sensor fusion algorithm specialists with hospital and airport reference deployments. Long-term viability across the projection horizon rests on multi-modal detection capabilities combining thermal imaging with occupancy analytics. Watch for IEC 62443 cybersecurity certification completion as an inflection indicator for cloud-native platform readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Stacking Investment | Simultaneous UL 864, EN 54, and BIS compliance compresses competitor time-to-market. |
| Sensor Fusion Algorithm Development | Multi-modal detection integrating thermal imaging with occupancy analytics reduces false alarm rates below 2 percent. |
| Software Subscription Layering | Cloud-native architectures enable recurring revenue streams atop legacy hardware installed bases. |
| Digital Twin Commissioning Capability | BIM-integrated safety modeling compresses project handover timelines from 18 months to 11 months. |
| Cybersecurity Hardening Certification | IEC 62443 compliance addresses network-hardening requirements for connected life safety devices. |
Research Approach
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Facility managers, fire safety engineers, municipal building authority procurement officers, and certified system integrators provided operational perspectives. Secondary validation drew from NFPA code documentation, EN 54 testing protocols, BIS certification records, and SEC filings from listed building automation conglomerates. Bottom-up demand modeling triangulates against top-down market sizing across the projection horizon.
Sensitivity analysis across technology adoption curves, regulatory enforcement intensity, and semiconductor supply availability shapes the forecast framework. Segmentation dimensions include product type, technology architecture, end-user vertical, and installation context. CAGRs derive from substitution elasticity modeling between legacy hardwired and cloud-native platforms. METI subsidy uptake rates and German federal retrofit mandate compliance timelines serve as country-specific forecast inputs.
Material uncertainties — semiconductor input volatility, cybersecurity mandate evolution, and geopolitical disruption to East Asian foundry output — sit outside the modeled envelope. Forecasts reflect assumptions regarding EN 54-23 certification expansion pacing and smart city mission budget continuity. Revision becomes warranted when MEMS sensor lead times exceed 40 weeks or IEC 62443 compliance timelines compress competitor entry pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market