
 North America Emergency Shower and Eye Wash Station Market | 2026-2036
North America Emergency Shower and Eye Wash Station Market Size, Share, and Industry Trends Forecast 2026-2036
North America Emergency Shower and Eye Wash Station Market Analysis
Aftermarket service revenue is reshaping margin distribution across the North America emergency shower and eye wash station landscape. Haws Corporation leverages its century-long installed base to capture recurring calibration and inspection contracts. Honeywell International Inc. anchors its position through integrated safety system bundling that extends beyond standalone units. Bradley Corporation specializes in stainless-steel fabrication for corrosive environments, competing on material durability rather than price alone.
Emergency showers and eye wash stations are plumbed safety fixtures designed to deliver tepid potable water at minimum flow rates of 20 gallons per minute for showers and 0.4 gallons per minute for eye washes over sustained durations, primarily to dilute and flush hazardous chemical exposures from workers' eyes and skin. Combination units integrating shower, eye wash, and drench hose functions command the largest product-type volume pool due to consolidated installation economics in space-constrained facilities. Wall-mounted installations dominate retrofit activity in existing chemical processing plants where floor space remains at a premium, while portable eye wash units represent the fastest-expanding segment driven by temporary construction site mandates.
OSHA workplace safety standards and ANSI Z358.1 equipment specifications shape product design thresholds and inspection frequency requirements across U.S. industrial facilities. Canadian provincial regulators under the Canadian Centre for Occupational Health and Safety framework enforce parallel compliance timelines, creating synchronized replacement cycles for cross-border operators. Stakeholders must monitor evolving tepid water definitions and emerging self-contained heated unit standards that could trigger wholesale infrastructure upgrades before current equipment reaches end-of-life.
Market Dynamics
OSHA's intensified ANSI Z358.1 enforcement is compressing replacement cycles across Gulf Coast petrochemical facilities, forcing capital allocation toward tepid water infrastructure before equipment reaches natural end-of-life.
Growth Catalysts
- ANSI Z358.1 tepid water mandates:The standard's 60-100°F requirement is triggering wholesale plumbing upgrades in legacy Texas and Louisiana plants.
- Petrochemical capacity expansion:Gulf Coast ethane cracker construction is embedding safety infrastructure into greenfield specifications.
- Self-contained heated units:Battery-powered tempering technology is opening retrofit pathways in facilities lacking central hot water distribution.
Market Restraints
- Stainless steel price volatility:316L alloy input costs swing with nickel futures, compressing margin on corrosion-resistant fabrications.
- Contractor concentration:Licensed industrial plumbing labor pools concentrate in Houston and Baton Rouge, creating installation bottlenecks.
- Legacy copper piping incompatibility:Tepid water recirculation systems degrade existing copper infrastructure, forcing parallel replacement.
Strategic Opportunities
- Canadian oil sands remediation:Alberta's aging SAGD facilities face synchronized ANSI compliance deadlines with U.S. counterparts.
- Mobile construction site mandates:OSHA's temporary workplace standard is creating pull-through demand for cart-mounted eye wash stations.
- IIoT-enabled predictive maintenance:Flow sensor integration with facility management software is unbundling inspection revenue from hardware sales.
Industry Challenges
- Certified plumber scarcity:Cross-connection control assembly installation requires licensed backflow certification that outstrips Gulf Coast labor supply.
- Legacy system integration:Tepid water blending valves must interface with 1970s-era plant steam distribution without triggering pressure cascade failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Emergency Shower and Eye Wash Station Market |
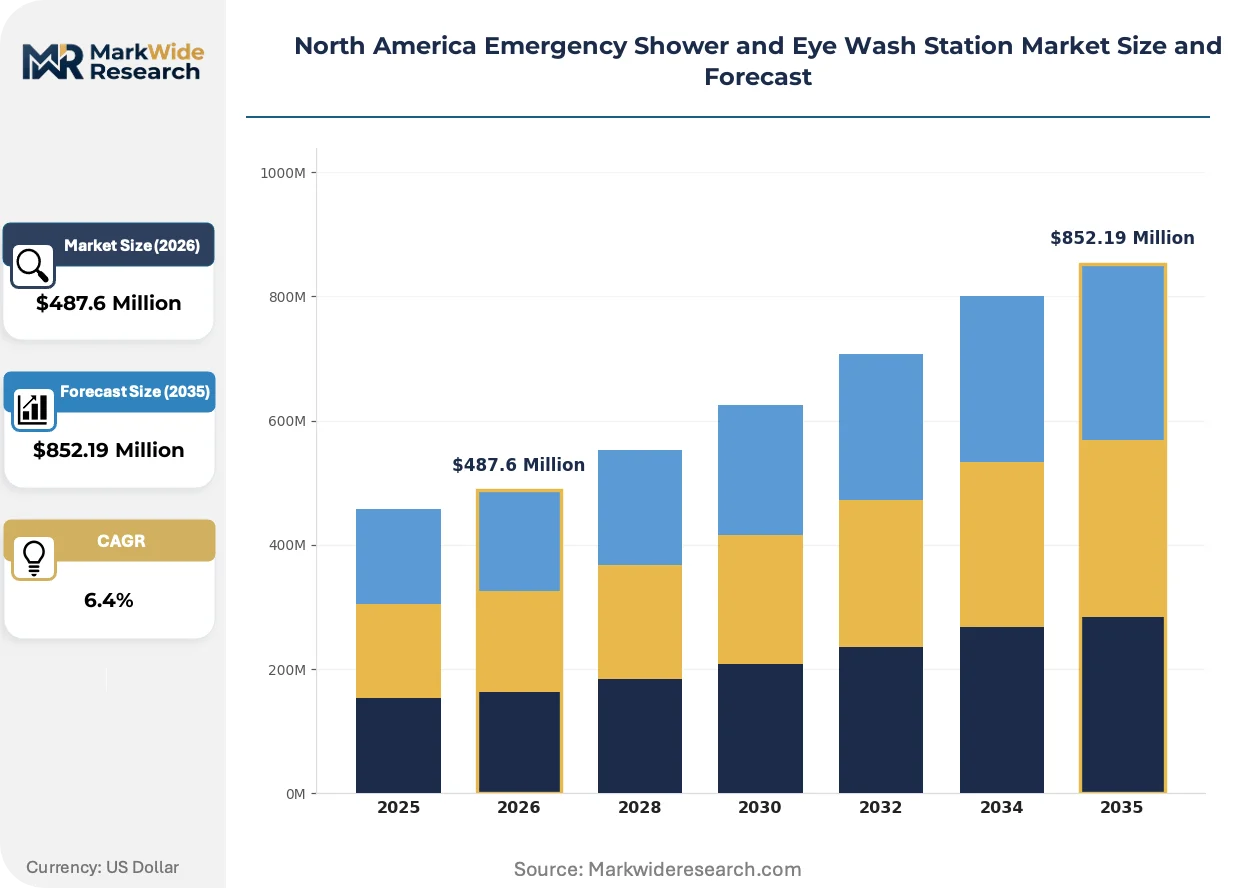
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $852.19 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Shower, Portable Eye Wash, Combination Unit, Drench Hose, Face Wash Fountain Installation Type: Wall Mounted, Floor Mounted, Pedestal Mounted, Ceiling Mounted, Independent Stand Application: Chemical Processing Plants, Manufacturing Facilities, Laboratories, Construction Sites, Food Processing End User: Pharmaceutical Manufacturers, Educational Institutions, Research Organizations, Government Facilities |
| Companies Covered | Haws Corporation, Honeywell International Inc., Bradley Corporation, Guardian Equipment, Hughes Safety Showers, Encon Safety Products, Speakman, Uline, Grainger, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Emergency Shower and Eye Wash Station Market Emerging Trajectories
Digital instrumentation is penetrating safety fixture infrastructure, transforming passive hardware into monitored nodes within facility-wide compliance systems.
Smart flow monitoring technology is virtualizing inspection workflows across Texas and Louisiana petrochemical complexes. Facilities are retrofitting ultrasonic sensors to existing shower heads, transmitting usage data to centralized maintenance dashboards. This architecture is virtualizing the traditional weekly manual activation logs that ANSI Z358.1 mandates, compressing labor allocation while improving audit trail integrity.
OSHA's 2023 emphasis on documented tepid water verification is accelerating heated blending valve adoption in unconditioned storage areas. The enforcement posture is forcing facilities to abandon ambient-temperature tank sourcing in favor of active temperature control. Gulf Coast chemical processors are responding by specifying thermostatically controlled mixing valves with digital temperature logging.
Maintenance departments are consolidating safety equipment procurement under integrated facility service contracts rather than discrete capital budgets. Third-party inspection providers are capturing recurring revenue streams that hardware manufacturers previously left on the table. This reconfiguration is most visible in cross-border operators running synchronized U.S.-Canadian facilities under unified vendor management.
North America Emergency Shower and Eye Wash Station Market Segmentation
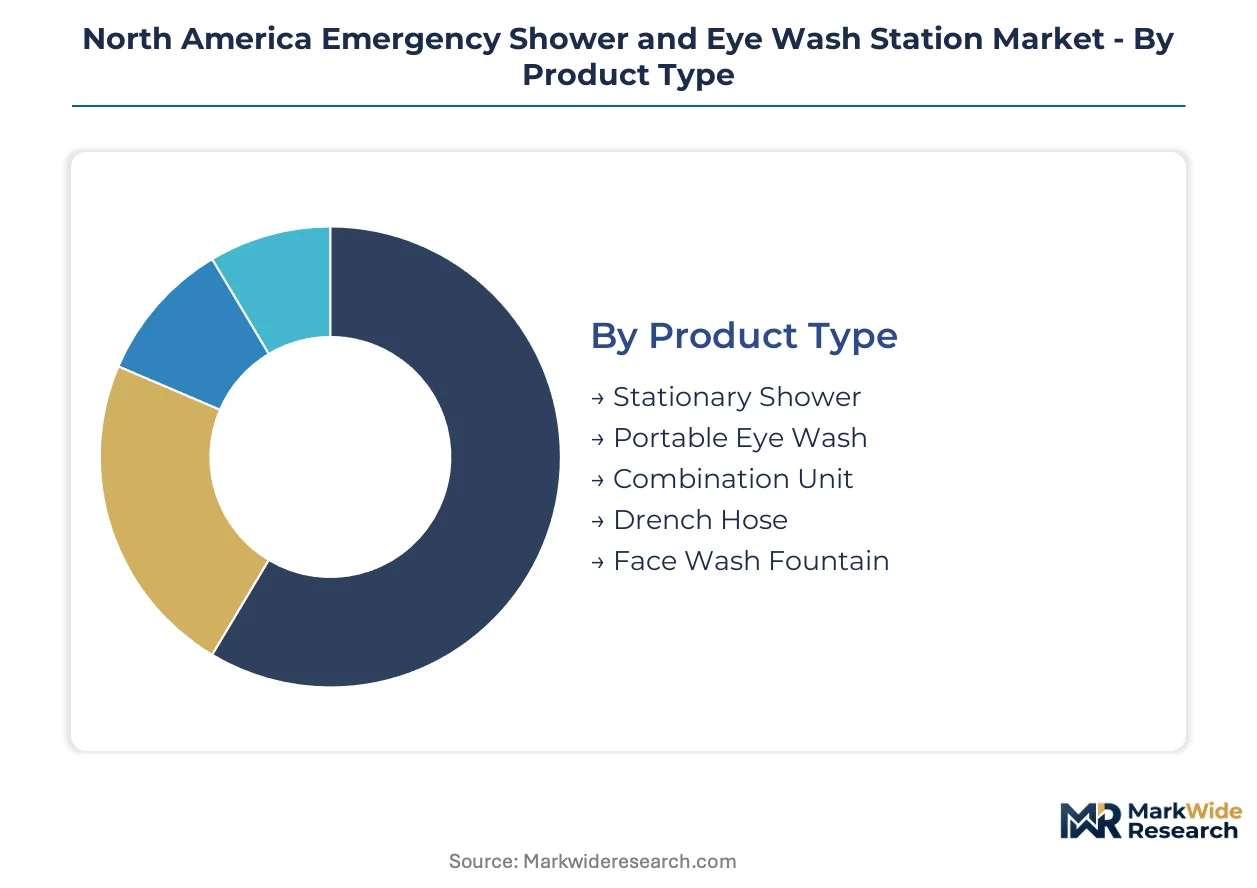
Product architecture in emergency safety fixtures diverges sharply between permanent infrastructure and temporary deployment scenarios. Installation constraints and regulatory exposure levels determine which segment configurations capture capital allocation across Gulf Coast petrochemical corridors and Canadian oil sands operations.
Product Type:
Cost tier stratification separates integrated multi-function systems from single-purpose emergency fixtures, with price points scaling from basic portable units to tepid water-enabled combination systems.
- Stationary Shower:Plumbed permanent fixtures delivering 20 gallons per minute minimum flow for full-body chemical decontamination. Demand concentrates in Texas and Louisiana ethane cracker complexes where OSHA mandates full shower coverage within 10 seconds of hazard exposure.
- Combination Unit:Integrated shower, eye wash, and drench hose assemblies consolidating three functions into single plumbing connections. Wall-mounted configurations dominate retrofit activity in space-constrained chemical processing plants across the Gulf Coast corridor.
- Portable Eye Wash:Self-contained gravity-fed or pressurized units for temporary construction sites. OSHA temporary workplace standards are accelerating cart-mounted deployment.
- Drench Hose:Handheld supplemental flushing devices for targeted chemical spot removal. Laboratories specify these for benchtop acid handling stations.
- Face Wash Fountain:Dedicated eye and face wash basins with aerated spray heads. Food processing facilities favor these for caustic cleaning agent exposure scenarios.
Combination units hold installed capacity. Portable eye wash is rotating up the share rankings.
Installation Type:
Application environment dictates mounting geometry, with floor space availability and existing infrastructure compatibility driving specification decisions across legacy and greenfield facilities.
- Wall Mounted:Bracket-fixed units conserving floor space in congested process areas. Retrofit dominance in 1970s-era Texas and Louisiana plants where structural steel limits floor penetration.
- Floor Mounted:Free-standing units with integrated drain pans for high-volume shower applications. Greenfield petrochemical construction embeds these into concrete safety islands.
- Pedestal Mounted:Elevated eye wash basins at standardized 33-45 inch heights for seated or standing access. Laboratories and pharmaceutical cleanrooms specify these for ergonomic compliance.
- Ceiling Mounted:Overhead shower heads with pull-rod activation for unobstructed coverage. Corrosive chemical storage warehouses deploy these to eliminate floor obstruction.
- Independent Stand:Self-supporting frames with integrated water supply for locations lacking permanent plumbing. Mobile construction sites and remote Alberta oil sands facilities drive demand.
Wall mounted configurations anchor replacement cycles. Independent stand units are climbing the fastest among installation categories.
Application:
End-use hazard profiles determine flow rate requirements, material specifications, and inspection frequency, with chemical exposure severity creating tiered product performance thresholds.
- Chemical Processing Plants:High-volume shower systems with 316L stainless steel construction resisting sulfuric acid and caustic soda exposure. Gulf Coast ethane cracker expansions embed ANSI Z358.1 compliance into capital budgets.
- Manufacturing Facilities:Mixed metalworking coolant and solvent exposure scenarios requiring combination eye wash and shower coverage. Midwest automotive and aerospace clusters standardize on thermostatically controlled tempering.
- Laboratories:Compact eye wash stations for fume hood and benchtop chemical handling. Educational and pharmaceutical research facilities drive specification for drench hose accessories.
- Construction Sites:Portable and heated self-contained units for temporary concrete admixture and epoxy exposure. OSHA mobile workplace mandates are accelerating cart-mounted procurement.
- Food Processing:Stainless steel face wash fountains for caustic cleaning agent and sanitizer exposure. USDA-inspected facilities in California and Wisconsin centralize specification authority.
Chemical processing plants dominate capital deployment. Construction sites are gaining share fastest among application categories.
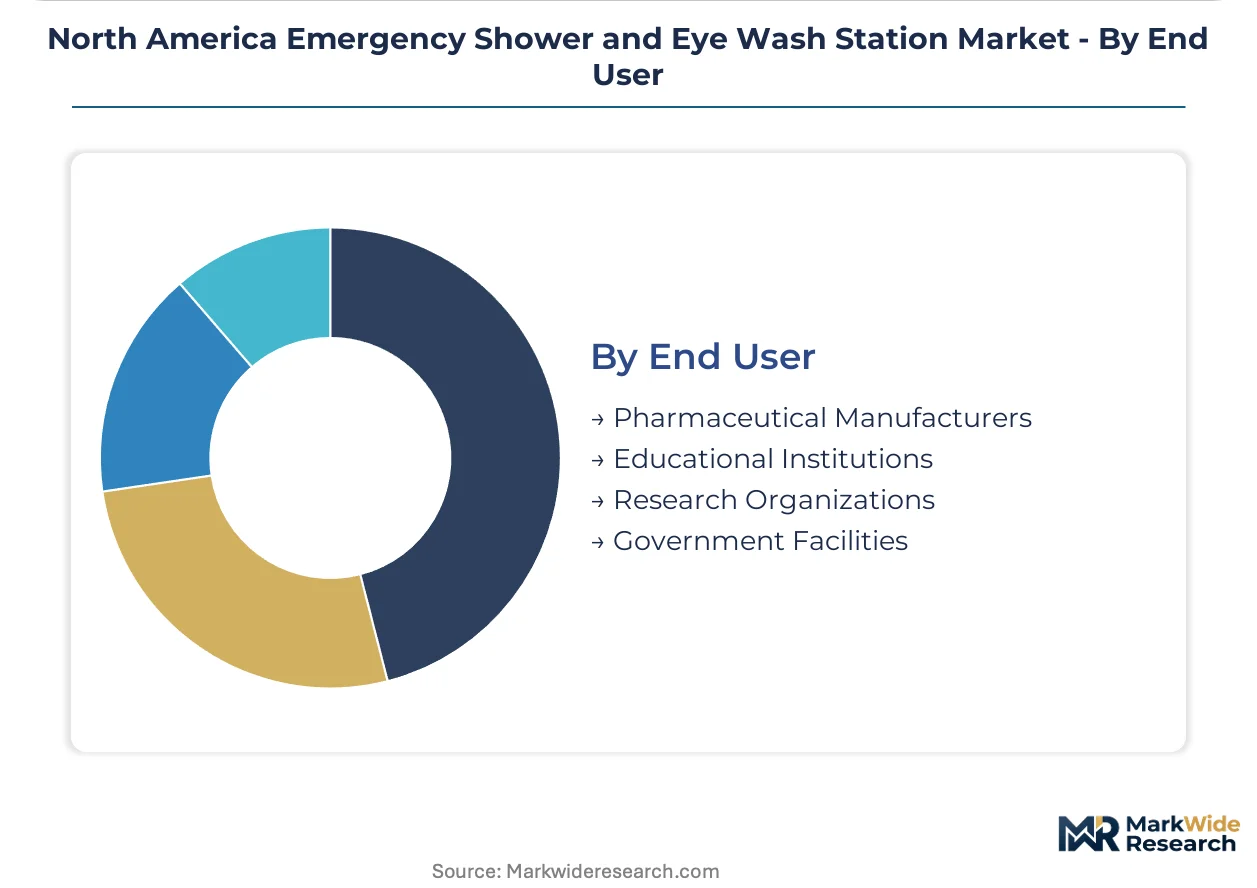
End User:
Customer procurement sophistication varies from centralized corporate safety standards to decentralized facility-level decision-making, influencing contract structure and service bundling economics.
- Pharmaceutical Manufacturers:FDA-regulated facilities with validated cleaning protocols and stringent documentation requirements. New Jersey and Massachusetts biotech clusters specify integrated IIoT monitoring for audit trail automation.
- Educational Institutions:University chemistry departments and vocational training centers with mixed legacy and modern infrastructure. State procurement contracts consolidate purchasing across multi-campus systems.
- Research Organizations:National laboratories and private R&D facilities handling exotic materials. Department of Energy sites drive specification for specialized drench systems.
- Government Facilities:Military maintenance depots and civilian agency operations with standardized federal supply schedule purchasing. Defense Logistics Agency contracts anchor volume pricing.
Pharmaceutical manufacturers hold installed capacity. Educational institutions are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed industrial plumbing labor concentrates in Houston and Baton Rouge, creating installation bottlenecks that compress project timelines across Gulf Coast petrochemical corridors. Canadian provincial regulators under CCOHS enforce parallel ANSI Z358.1 compliance timelines, synchronizing replacement cycles for cross-border operators. Mexican maquiladora safety standards are tightening as nearshoring accelerates chemical processing investment.
United States
Texas and Louisiana ethane cracker expansions embed tepid water infrastructure into greenfield capital budgets. OSHA's intensified ANSI Z358.1 enforcement compresses replacement cycles before equipment reaches natural end-of-life. Gulf Coast chemical processors specify thermostatically controlled mixing valves with digital temperature logging.
Canada
Alberta's aging SAGD facilities face synchronized compliance deadlines with U.S. counterparts under CCOHS provincial frameworks. Health Canada workplace safety guidelines align with ANSI tepid water mandates. Edmonton and Calgary industrial clusters drive specification for self-contained heated units in remote oil sands locations.
Mexico
Nuevo León petrochemical complexes expand safety infrastructure as nearshoring investment accelerates. Mexican federal labor law amendments tighten occupational exposure protocols for chemical processing. Monterrey industrial corridors specify combination units consolidating shower, eye wash, and drench hose functions.
North America Emergency Shower and Eye Wash Station Market Vendor Landscape
Century-long installed base operators and integrated safety system bundlers split the market between recurring service revenue and capital equipment consolidation. The vendor structure concentrates around three strategic archetypes: legacy manufacturers leveraging historical installation footprints, diversified conglomerates cross-selling safety portfolios, and specialized fabricators competing on material durability. Dominant competitive moves include aftermarket service contract capture and IIoT-enabled predictive maintenance integration.
Within the legacy manufacturer tier, Haws Corporation and Bradley Corporation exemplify installed-base monetization through recurring calibration contracts. Honeywell International Inc. anchors the diversified conglomerate position, bundling emergency fixtures within broader industrial safety system offerings. These three entities represent the principal competitive anchors shaping procurement consolidation patterns.
| Leading Market Players |
|---|
| Haws Corporation |
| Honeywell International Inc. |
| Bradley Corporation |
| Guardian Equipment |
| Hughes Safety Showers |
| Encon Safety Products |
| Speakman |
| Uline |
| Grainger |
| Others |
Supply Flow & Price Mechanics
316L stainless steel feedstock concentration in Chinese and Indonesian nickel smelting corridors anchors cost volatility for corrosion-resistant fabrications, concentrating margin pressure on Gulf Coast petrochemical procurement teams specifying acid-resistant shower assemblies. ANSI Z358.1 tepid water mandates are compressing price elasticity as facilities absorb mandatory plumbing upgrades regardless of budget cycles.
Pricing Analysis
OSHA's ANSI Z358.1 enforcement dictates the pricing tier structure across emergency safety fixtures, separating thermostatically controlled combination units from basic ambient-temperature models. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and IIoT monitoring integration. Cost compression in mid-tier stainless fabrications is intensifying because nickel futures volatility feeds directly into 316L alloy input costs. Educational institutions exhibit highest price sensitivity due to state procurement contract constraints, while pharmaceutical manufacturers prioritize validated audit trail capabilities over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for distributor financing of tepid water blending valve assemblies, stretching working capital across the industrial plumbing channel. Manufacturing concentrates in the United States, China, and Mexico, with brass valve castings and thermostatic mixing cartridges drawing from specialized foundry clusters. Single-source vulnerability concentrates in ceramic disc cartridge suppliers serving thermostatic valve producers. Distribution runs through authorized industrial safety distributors and integrated facility service contractors rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-contained battery-powered tempering units threaten traditional plumbed infrastructure by enabling retrofit deployment without central hot water distribution, forcing incumbents to defend installed base relationships through service contract capture.
For Market Incumbents: Build switching-cost moats through IIoT-enabled predictive maintenance platforms that virtualize ANSI-mandated inspection workflows. Capture recurring calibration revenue streams that emerging competitors cannot match without century-long installed base footprints. Deepen backward integration into thermostatic valve cartridge production to offset brass casting cost volatility. For New Entrants and Emerging Players: Pursue mobile construction site mandates as the most penetrable white-space target, where OSHA temporary workplace standards create procurement urgency without entrenched vendor relationships. Target Alberta oil sands remediation clusters facing synchronized CCOHS compliance deadlines with limited local service infrastructure. Lead with cart-mounted heated eye wash stations bundled with third-party inspection partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward aftermarket service specialists with established ANSI calibration certification networks rather than pure hardware manufacturers. Long-term viability hinges on recurring revenue attachment rates exceeding discrete equipment replacement cycles. Watch for IIoT platform adoption inflection as the signal separating sustainable competitive position from commodity hardware exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermostatic Valve Manufacturing | Captive supply of mixing cartridges insulates margin from nickel-driven brass casting volatility. |
| IIoT Predictive Maintenance Platform Launch | Ultrasonic flow sensor integration virtualizes OSHA-mandated weekly activation logs for audit automation. |
| Long-term Inspection Service Contract | Recurring calibration revenue capture extends customer lifetime value beyond initial hardware procurement. |
| Geographic Expansion into Canadian Oil Sands | Alberta SAGD facility aging creates synchronized replacement demand under CCOHS tepid water alignment. |
| Joint Venture with Certified Plumbing Contractor Networks | Houston and Baton Rouge labor scarcity makes licensed installation capacity a strategic chokepoint control. |
Methodological Framework
Initial hypotheses were tested against primary input from plant safety managers, industrial procurement leads, certified plumbing contractors, and aftermarket service technicians and refined through secondary validation. Primary fieldwork drew from OSHA compliance officers in Texas and Louisiana petrochemical corridors and CCOHS provincial regulators in Alberta. Secondary sources included ANSI Z358.1 technical committee documentation, SEC 10-K filings from diversified safety equipment manufacturers, and customs trade data for 316L stainless steel import flows. Bottom-up facility inventory estimates were triangulated against top-down capital expenditure projections from ethane cracker expansion announcements.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning product architecture, installation geometry, end-use hazard severity, and procurement centralization level. CAGRs were derived from replacement cycle compression analysis under intensified enforcement postures and greenfield capital budget embedding rates. Industry-specific inputs included tepid water infrastructure retrofit cost curves and certified plumber wage inflation trajectories in Gulf Coast labor markets.
Sensitivities concentrate around OSHA enforcement intensity variations, nickel futures volatility transmission to stainless fabrication costs, and IIoT platform adoption pace across legacy facility operators. Forecasts reflect assumptions about regulatory timeline synchronization between U.S. and Canadian jurisdictions and labor pool expansion in industrial plumbing certification programs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Emergency Escape Breathing Device Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market