
 Hazard Control Market | 2026-2036
Hazard Control Market Size, Share, and Industry Trends Forecast 2026-2036
Hazard Control Market Intelligence
A scarcity of technicians skilled in integrating IoT-enabled safety systems is redrawing the competitive landscape for hazard control solutions. Schneider Electric leverages its extensive digital automation portfolio to offer integrated safety and process control platforms. Siemens AG competes through its comprehensive industrial software and hardware, targeting complex manufacturing environments. Emerson Electric Co. differentiates with its focus on process industries and specialized sensor technologies for applications like gas detection.
Hazard control encompasses the engineering and equipment used to detect, contain, and neutralize industrial risks before they escalate into catastrophic events. These systems often incorporate sensors with high sensitivity, such as electrochemical detectors capable of identifying toxic gases in parts-per-million concentrations, to trigger automated responses. Fire suppression systems constitute a mature, high-value product segment driven by building codes and insurance mandates. The market for gas detection sensors, particularly those using infrared detection technology, is expanding due to reliability in harsh oil refinery applications.
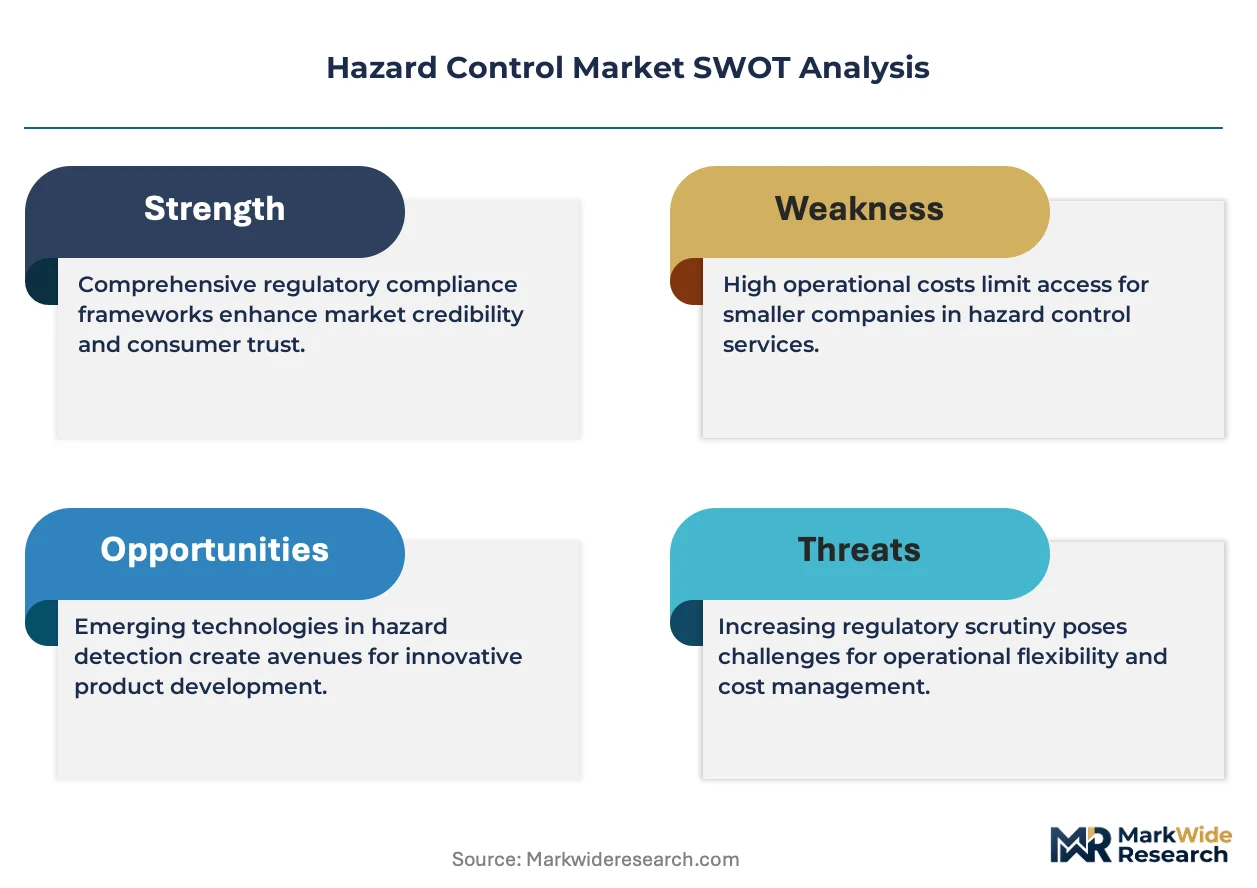
Regulatory frameworks from bodies like the US Occupational Safety and Health Administration (OSHA) and compliance with Europe's REACH directive are primary demand drivers. These regulations mandate specific performance standards for equipment, directly influencing product design. Adherence to ISO 45001 for occupational health and safety management further shapes procurement. Stakeholders must now decide how to balance investments between basic compliance systems and advanced predictive analytics platforms.
Market Dynamics
The convergence of stringent occupational safety regulations and the digitalization of industrial processes defines the hazard control market. This creates a primary tension between the need for basic regulatory compliance and the strategic advantage offered by advanced, data-driven predictive safety systems.
Growth Catalysts
- Regulatory Enforcement:Stricter mandates, including the EU's REACH directive for chemical substances and OSHA standards in the US, compel ongoing investment in compliant detection and suppression systems across processing industries.
- Industrial Expansion:Rapid industrialization in hubs across India and China generates new, greenfield demand for hazard control infrastructure, particularly in the chemical, power generation, and metals sectors.
- Sensor Technology Advancement:The development of more sensitive and reliable sensors, such as infrared detectors for hydrocarbon gas detection in harsh oil refinery environments, expands application viability and drives upgrades from older technologies.
Market Restraints
- High Capital Costs:The significant upfront investment required for installing or retrofitting integrated, automated hazard control systems can be prohibitive for small and medium-sized enterprises, slowing widespread adoption.
- Integration with Legacy Systems:A primary technical barrier is the complexity and cost associated with integrating modern IoT-enabled safety devices with older, proprietary industrial control systems still prevalent in many facilities.
- Procedural Control Reliance:In some industries and regions with lax enforcement, companies may opt for cheaper, less reliable administrative and procedural safety controls over investing in capital-intensive engineering solutions.
Strategic Opportunities
- Predictive Analytics Services:A significant opportunity exists in developing AI-powered software platforms that analyze sensor data to predict equipment failures or process deviations before they become hazardous incidents.
- Drone-Based Inspection:Integrating gas sensors and thermal cameras with unmanned aerial vehicles (UAVs) creates new service models for inspecting large, inaccessible, or hazardous areas like storage tanks and pipelines.
- Mid-Market Penetration:Targeting mid-sized manufacturing plants in Southeast Asian and Latin American economies with scalable, modular hazard control solutions represents a key growth vector as their regulatory environments mature.
Industry Challenges
- Specialized Skills Shortage:A critical lack of technicians and engineers skilled in both industrial safety protocols and modern IT/OT convergence, including cybersecurity for control systems, hampers implementation.
- Certification Bottlenecks:The long and expensive process of obtaining intrinsic safety certifications, such as ATEX in Europe or IECEx globally, for new electronic equipment intended for explosive atmospheres can delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazard Control Market |
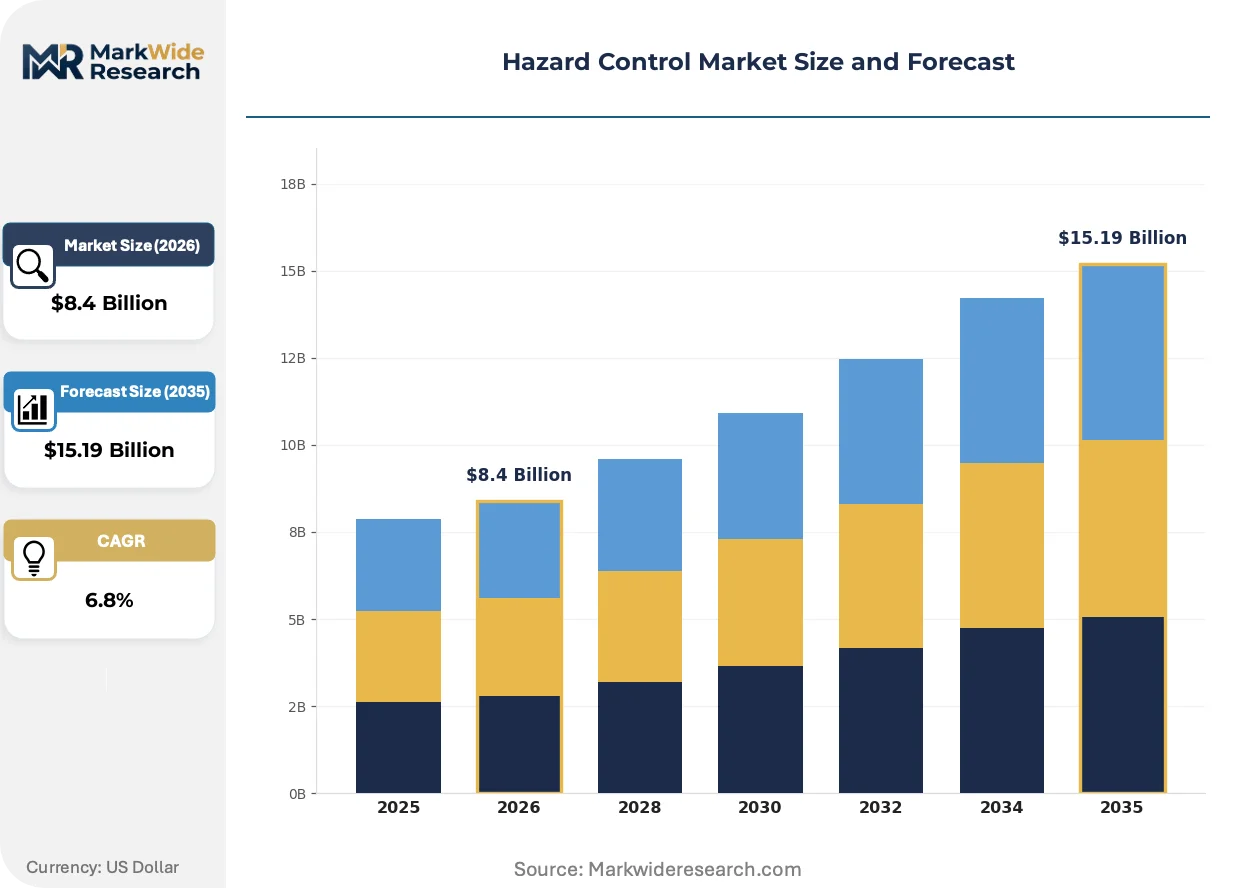
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Suppression Systems, Gas Detection Sensors, Spill Containment Solutions, Personal Protective Equipment, Emergency Shower Stations Technology: Infrared Detection, Ultrasonic Sensors, Electrochemical Detectors, Flame Detectors, Mechanical Barriers Application: Chemical Processing, Construction Sites, Mining Operations, Waste Management, Transportation Facilities End User: Manufacturing Units, Research Laboratories, Oil Refineries, Utilities Providers, Food Processing Plants |
| Companies Covered | Schneider Electric, Siemens AG, Emerson Electric Co., ABB Ltd., Rockwell Automation, Inc., Eaton, Mitsubishi Electric, Bosch Rexroth AG, BARTEC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazard Control Market Strategic Shifts & Innovations
The evolution from reactive, alarm-based systems to proactive, data-centric safety networks is the market's core technological trajectory. This shift is driven by advancements in connectivity, software, and a changing regulatory landscape that demands more sophisticated risk management capabilities.
Wireless sensor networks enable flexible and scalable deployment of monitoring points without the cost and rigidity of traditional hardwired infrastructure. These systems are being adopted in complex environments like chemical processing plants and remote oil and gas sites for temporary or gap-filling coverage. The proliferation of competing communication standards like WirelessHART and ISA100.11a is fragmenting the technology landscape away from a single dominant protocol.
Europe's F-Gas Regulation, which aims to phase down the use of hydrofluorocarbons, directly impacts fire suppression systems. The regulation forces a transition away from HFC-based agents toward alternatives with lower global warming potential, such as inert gases or advanced water mist systems. This shift affects product development and certification priorities for fire suppression equipment manufacturers supplying the European market.
A transition from one-time equipment purchases to service-oriented contracts is altering buyer behavior. End-users are increasingly seeking "Safety-as-a-Service" models that bundle hardware, remote monitoring, and maintenance into a recurring subscription fee, reducing initial capital outlay. This model is most prominent in high-value manufacturing sectors in North America where maximizing uptime and ensuring continuous compliance are business imperatives.
Hazard Control Market Segmentation
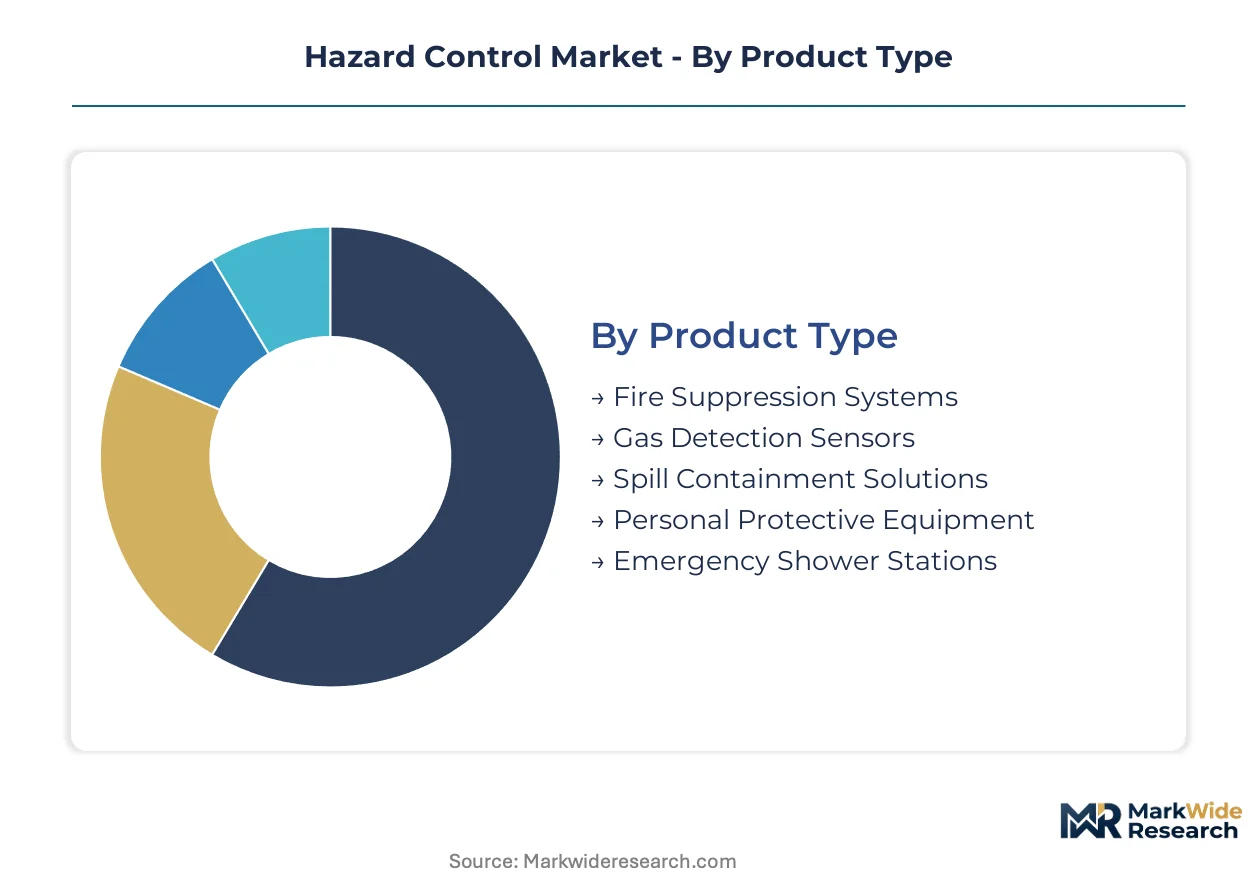
Segmentation within the hazard control market provides a granular view of where specific risks emerge and how specialized solutions address them. This detailed breakdown highlights varying compliance requirements and technological preferences across diverse industrial landscapes.
Product Type:
Margin pools in this product category are concentrated around specialized engineering solutions and recurring service contracts.
- Fire Suppression Systems:These systems deploy agents like inert gases or water mist to extinguish fires in industrial settings. Building codes and insurance mandates drive procurement in industrial and commercial structures across Europe.
- Gas Detection Sensors:These devices identify specific gases, often using electrochemical or infrared principles, to alert personnel to hazardous conditions. Oil refineries in China require these sensors for volatile hydrocarbon detection.
- Spill Containment Solutions:These products manage leaks of hazardous materials, critical for chemical storage and transportation.
- Personal Protective Equipment:This includes safety gear like respirators and gloves, essential for worker protection in hazardous environments.
- Emergency Shower Stations:These units provide immediate decontamination for chemical exposures in various industrial settings.
The dominant share belongs to Fire Suppression Systems, while Gas Detection Sensors is closing the gap fastest.
Technology:
Cost tiers within hazard control technology reflect the precision and environmental resilience required for deployment.
- Infrared Detection:This technology identifies hydrocarbon gases by measuring their absorption of infrared light, offering high reliability. Harsh oil refinery applications in India rely on this for its stability and resistance to poisoning.
- Electrochemical Detectors:These sensors react to specific toxic gases, generating an electrical current proportional to gas concentration. Chemical processing facilities in the US utilize these for precise parts-per-million detection.
- Ultrasonic Sensors:These detect gas leaks by identifying the sound of escaping pressurized gas, suitable for outdoor and noisy environments.
- Flame Detectors:These devices identify the presence of flames through optical sensing, triggering alarms in combustible areas.
- Mechanical Barriers:These physical structures prevent the spread of hazards, like blast walls or safety interlocks in manufacturing plants.
Infrared Detection commands significant volume, driven by reliability in challenging environments, while Electrochemical Detectors show steepest expansion trajectory.
Application:
Volume concentration for hazard control solutions is highest in sectors with inherent process risks and large-scale operations.
- Chemical Processing:This application involves managing highly reactive and toxic substances, requiring sophisticated detection and suppression systems. Facilities across Germany implement advanced systems due to stringent REACH regulations.
- Mining Operations:This environment presents risks from explosive gases and dust, demanding robust ventilation and monitoring technologies. Safety protocols in Australian mines drive demand for specialized gas detection and suppression.
- Construction Sites:These sites require temporary and portable hazard controls for worker safety and environmental protection.
- Waste Management:This application focuses on containing biological and chemical hazards from waste streams in municipal and industrial facilities.
- Transportation Facilities:These locations require systems for managing fuel spills and fire risks in logistics hubs and ports.
Demand concentration remains high in Chemical Processing, with Mining Operations showing consistent expansion.
End User:
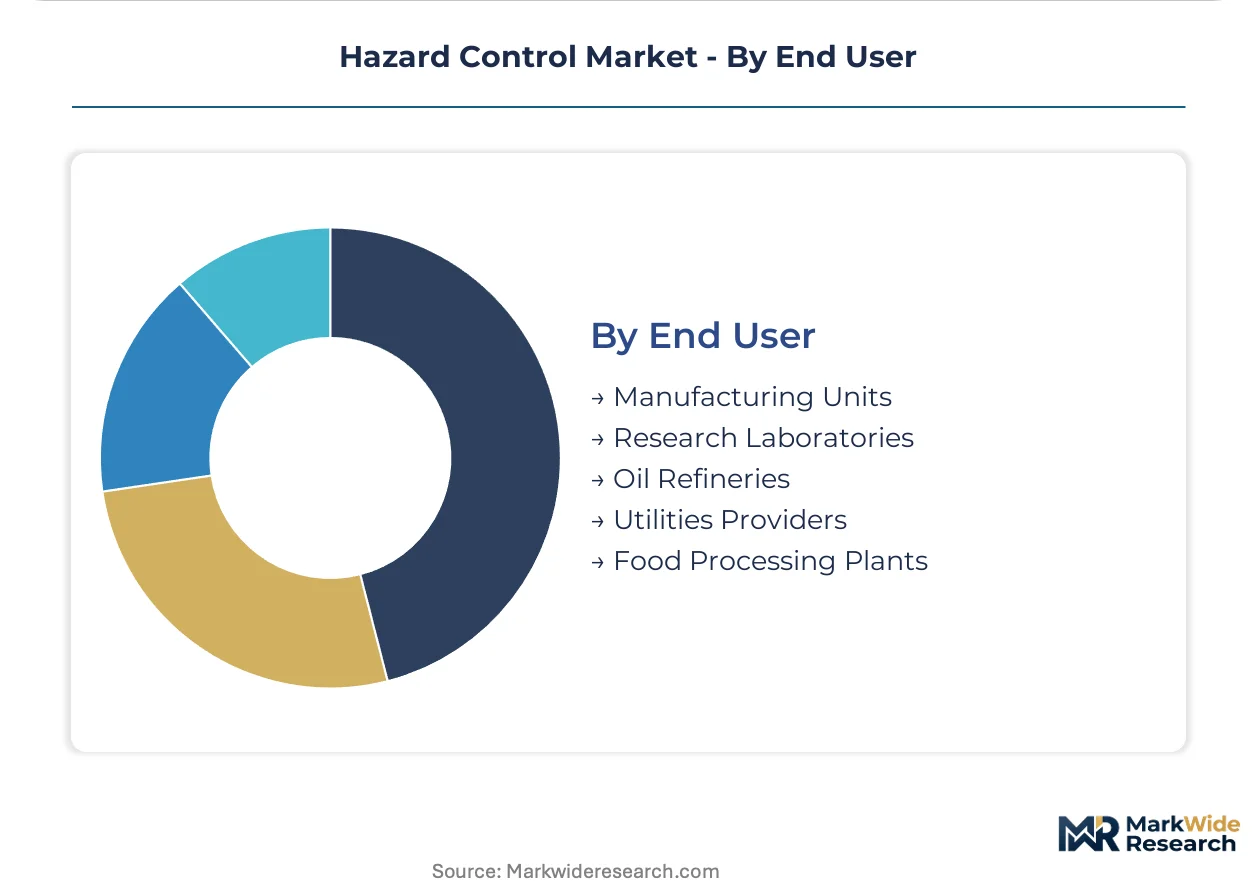
Regulatory drivers significantly influence procurement patterns across different end-user segments for hazard control solutions.
- Oil Refineries:These facilities handle highly flammable hydrocarbons, necessitating advanced gas detection and fire suppression systems. US EPA mandates and OSHA standards compel continuous investment in these complex environments.
- Manufacturing Units:This segment includes diverse industries requiring general safety systems for machinery and processes. ISO 45001 compliance drives investment in occupational health and safety across European factories.
- Research Laboratories:These facilities require precise controls for handling hazardous chemicals and biological agents.
- Utilities Providers:This segment uses hazard control for power generation and water treatment facilities, addressing electrical and chemical risks.
- Food Processing Plants:These plants require specialized safety measures to prevent contamination and ensure worker safety in hygienic environments.
Large-scale procurement from Oil Refineries stabilizes demand, as Manufacturing Units present new growth vectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Occupational Safety and Health Administration (OSHA) standards compel continuous investment in hazard control systems across North American industrial sectors. This regulatory pressure, combined with rapid industrialization in emerging economies, drives diverse regional demand for safety solutions. The market exhibits significant growth in areas with extensive chemical processing, oil and gas operations, and a maturing regulatory landscape.
United States
OSHA standards compel continuous investment in hazard control for oil refineries and manufacturing units across the United States. EPA mandates also drive demand for advanced systems in chemical processing facilities. Texas and Louisiana host significant petrochemical complexes requiring sophisticated gas detection and fire suppression technologies.
Germany
Stringent REACH regulations in Germany necessitate advanced hazard control systems for chemical processing facilities. ISO 45001 compliance also shapes procurement across manufacturing units. The Rhine-Ruhr region, a major industrial hub, implements sophisticated detection and suppression technologies for complex industrial operations.
China
Rapid industrialization in China generates new demand for hazard control infrastructure, particularly in chemical and power generation sectors. Regulatory enforcement by the Ministry of Ecology and Environment (MEE) drives investment in compliant detection systems. Industrial hubs like the Yangtze River Delta require extensive safety solutions for expanding manufacturing capabilities.
India
Harsh oil refinery applications in India rely on infrared detection for stability and resistance to poisoning. Production Linked Incentive (PLI) schemes encourage manufacturing expansion, increasing demand for safety systems. Gujarat's chemical industry and energy sector drive significant procurement of advanced hazard control equipment.
Australia
Mining operations in Australia present risks from explosive gases and dust, demanding robust ventilation and monitoring technologies. Safety protocols enforced by state regulatory bodies drive demand for specialized gas detection and suppression solutions. Western Australia's mining sector continuously invests in advanced hazard control measures to protect personnel and assets.
Hazard Control Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the hazard control market structure. This tiered landscape includes providers of comprehensive digital automation platforms, alongside niche manufacturers of specialized sensor technologies. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and solution offerings.
Integrated solution providers such as Schneider Electric and Siemens AG exemplify the trend towards comprehensive industrial software and hardware integration. Emerson Electric Co. occupies a strong position with its focus on process industries and specialized sensor technologies. These companies anchor the market by offering broad platforms that address complex manufacturing environments and critical infrastructure safety requirements.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| Emerson Electric Co. |
| ABB Ltd. |
| Rockwell Automation, Inc. |
| Eaton |
| Mitsubishi Electric |
| Bosch Rexroth AG |
| BARTEC Group |
| Others |
Cost & Logistics Intelligence
Project-based contracts for integrated hazard control systems lock in both supply access for complex installations and price visibility for end-users. These agreements mitigate cost fluctuations for large-scale deployments in oil refineries and chemical processing plants.
Pricing Analysis
Geographic price spreads for hazard control solutions are pronounced, with higher costs in Germany and the US driven by stringent regulations compared to volume-driven markets in China. Project-based and "Safety-as-a-Service" models dominate, bundling hardware, software, and maintenance. Price differentiation stems from specialized certifications like ATEX and the level of integrated automation, while pricing softness emerges from the high capital costs for small and medium-sized enterprises. Oil refineries and chemical processing facilities exhibit lower price sensitivity due to critical safety mandates.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized electronic components from Asian manufacturing hubs, influence the hazard control supply chain. Supply concentration for advanced sensors and automation platforms centers in Germany, the US, and Japan. This market relies on critical electronic components and specialized chemicals for sensor manufacturing, where single-source vulnerability for highly sensitive detectors presents a structural risk. Downstream distribution primarily occurs through direct sales channels for integrated systems and via specialized industrial distributors for individual sensors and PPE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hazard control market is experiencing a buyer-power shift as large industrial conglomerates consolidate procurement of integrated safety systems. This trend allows major end-users like oil refineries to demand more comprehensive and cost-effective solutions.
For Market Incumbents: Consolidate digital automation portfolios to offer truly integrated safety and process control platforms. Incumbents must invest in R&D for predictive analytics to counter the threat of reactive alarm-based systems. Expand "Safety-as-a-Service" models to reduce customer capital outlay and ensure recurring revenue. This strategy helps mitigate the impact of the specialized skills shortage on implementation.
For New Entrants and Emerging Players: Anchor in niche opportunities like AI-powered predictive analytics platforms for existing sensor infrastructure. Target mid-sized manufacturing plants in Southeast Asian economies with scalable, modular hazard control solutions. Offer drone-based inspection services for inaccessible or hazardous areas such as storage tanks, leveraging advanced sensor integration. A subscription-based "Safety-as-a-Service" model provides a strong go-to-market angle for these underpenetrated segments.
For Investors and Strategic Acquirers: AI-powered predictive analytics firms represent a compelling acquisition target archetype for long-term viability, given the market's shift towards data-driven safety. Strategic acquirers should prioritize companies with strong intellectual property in specialized sensor technologies or industrial cybersecurity. The convergence of IT/OT systems drives continuous investment interest. Watch for the accelerating adoption of IoT-enabled safety systems in manufacturing units as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand "Safety-as-a-Service" Models | Reduces upfront capital costs for end-users, particularly benefiting manufacturing units and SMEs. |
| Invest in Predictive Analytics R&D | Develops AI-powered software platforms that analyze sensor data to prevent hazardous incidents in chemical processing. |
| Acquire Niche Sensor Technology Firms | Integrates specialized gas detection capabilities, enhancing offerings for harsh oil refinery applications. |
| Pursue ATEX/IECEx Certification for New Products | Ensures compliance for electronic equipment intended for explosive atmospheres, particularly in European markets. |
| Develop Modular IoT Hazard Control Solutions | Caters to mid-sized manufacturing plants in Southeast Asia, addressing their evolving regulatory environments. |
Research Approach
Desk research of regulatory documents, industrial safety standards, and company annual reports preceded structured interviews with plant managers, safety engineers, and procurement leads. This approach integrated primary insights with secondary validation. Bottom-up data collection from facility-level deployments was triangulated with top-down market sizing estimates. This ensured a comprehensive view of the hazard control landscape.
Variance decomposition across the analysis window identified key growth drivers and restraints impacting hazard control solutions. The analytical framework modeled market dynamics by product type, technology, application, and end-user segments. Compound annual growth rates were derived from historical trends and projected regulatory enforcement. Industrialization rates in China and India, alongside EU F-Gas Regulation impacts, served as critical forecast inputs.
Material uncertainties—including geopolitical events and unforeseen technological breakthroughs—sit outside the modeled envelope. Forecasts reflect current assumptions regarding regulatory enforcement and industrial investment. Practitioners should keep alternative scenarios live as global economic stability and the pace of IoT adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Emergency Escape Breathing Device Market