
 China Surveillance Camera Market | 2026-2036
China Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
China Surveillance Camera Market Insights
4K resolution and AI-integrated specification tiers is collapsing into mainstream procurement as municipal buyers replace legacy analog systems. Hikvision leverages its captive semiconductor supply chain to control component costs across dome and bullet camera lines. Dahua Technology anchors its position through deep R&D investment in low-light imaging and edge-computing chipsets. Uniview differentiates by specializing in fisheye panoramic systems for commercial indoor installations.
China surveillance cameras are electro-optical devices capturing video data through CMOS or CCD sensors, transmitting signals via coaxial, Ethernet, or wireless protocols for security monitoring and automated analytics. Dome cameras lead indoor commercial deployments due to vandal-resistant housings and 360-degree coverage, while bullet cameras dominate outdoor wall-mounted applications across transportation corridors. IP technology is displacing analog infrastructure as the fastest-growing segment, though wireless installations remain limited by MIIT spectrum allocation constraints. PTZ units command premium positioning in industrial and critical infrastructure settings where remote directional control delivers operational value.
MIIT enforces GB/T cybersecurity standards and network access licenses that determine which camera models qualify for government and state-owned enterprise procurement. SAMR administers product quality certification under CCC marking rules that gate domestic market entry for both local manufacturers and imported equipment. Stakeholders must monitor evolving MEE data localization requirements that increasingly restrict cross-border transmission of video feeds from cameras deployed in sensitive facilities.
Market Dynamics
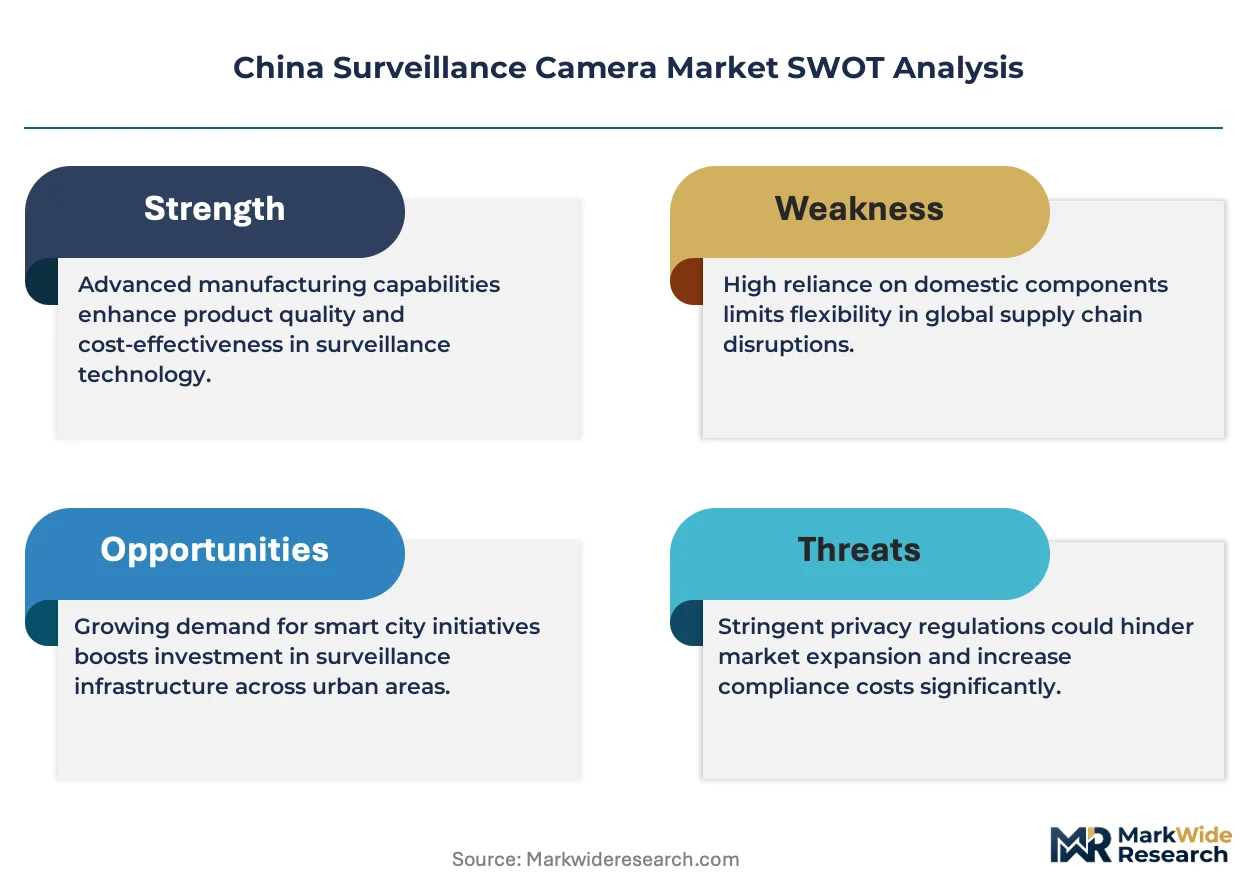
MIIT's GB/T cybersecurity certification framework is forcing manufacturers to redesign hardware architectures and firmware stacks before products qualify for government procurement, compressing development cycles while raising compliance barriers for smaller suppliers.
Growth Catalysts
- Smart city infrastructure mandates:Hangzhou, Shenzhen, and Chengdu municipal authorities are deploying AI-enabled video analytics networks for traffic management and public safety monitoring.
- MIIT network access licensing:Mandatory certification for network-connected cameras is standardizing procurement requirements across state-owned enterprises and creating predictable demand pipelines.
- Transportation sector digitization:Railway and highway authorities are replacing analog systems with high-definition IP camera networks for real-time corridor surveillance.
Market Restraints
- Semiconductor supply concentration:Domestic CMOS sensor production remains concentrated among a limited set of foundry partners, exposing camera assemblers to input volatility.
- Wireless spectrum constraints:MIIT's conservative allocation of unlicensed bands restricts deployment flexibility for cellular and Wi-Fi-enabled surveillance units.
- Data localization compliance costs:MEE requirements for video feed storage within national boundaries force infrastructure investments that inflate total cost of ownership.
Strategic Opportunities
- Edge AI convergence:On-device inference chipsets combined with low-light imaging sensors are opening premium positioning in industrial PTZ applications.
- Western region penetration:Chengdu and Xi'an municipal budgets for safe-city programs remain under-deployed relative to coastal counterparts.
- Commercial indoor specialization:Fisheye panoramic systems for retail and logistics facilities represent a whitespace segment distinct from saturated government verticals.
Industry Challenges
- Firmware security engineering talent:GB/T compliance requires specialized embedded systems expertise that remains scarce in domestic labor markets.
- Legacy analog integration friction:Hybrid deployments combining existing coaxial infrastructure with IP backbones create commissioning complexity and service margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Surveillance Camera Market |
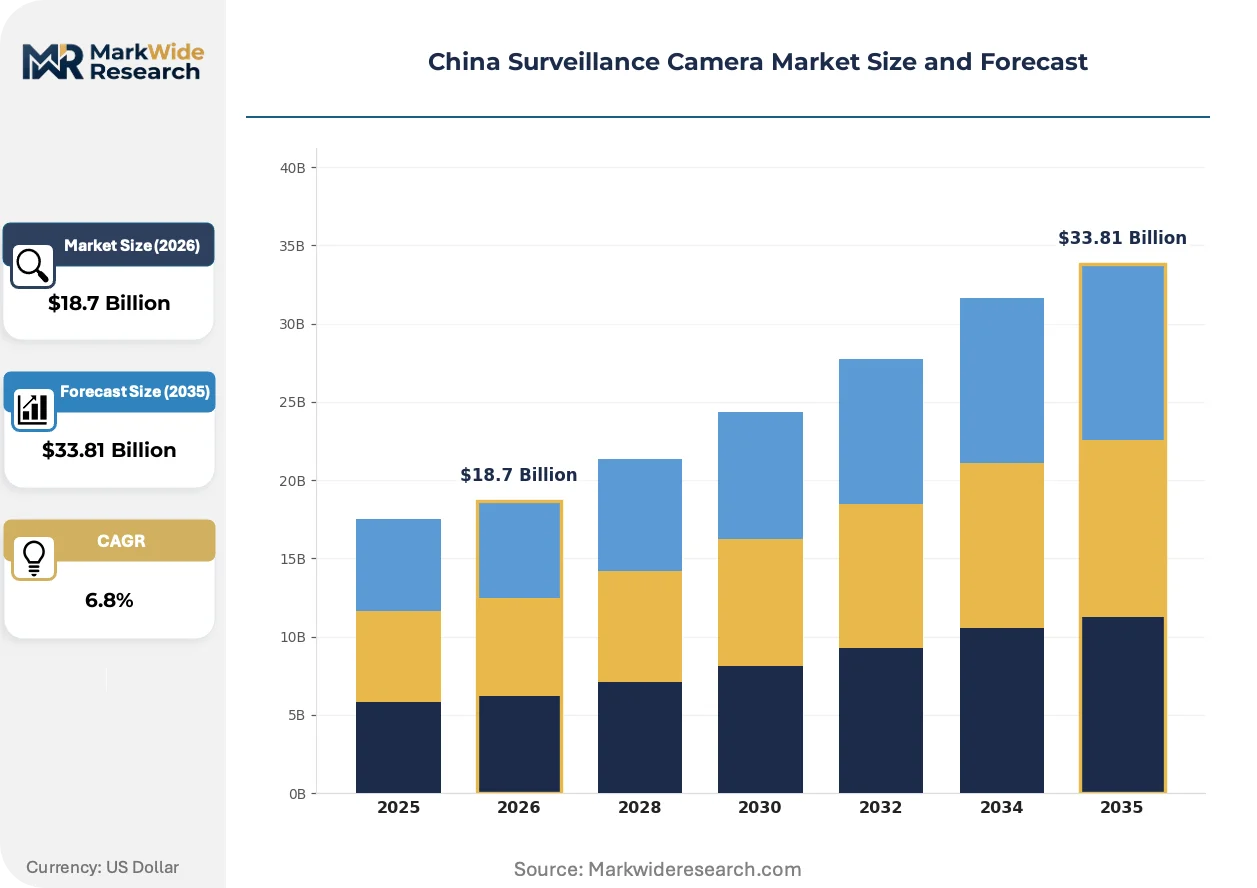
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, PTZ, Bullet, Fisheye Technology: Analog, IP, Wireless, IP67 End User: Commercial, Residential, Transportation, Industrial Installation Type: Indoor, Outdoor, Wall-mounted, Ceiling-mounted |
| Companies Covered | Hikvision, Dahua Technology, Uniview, Tiandy Technologies, Milesight Technology, LS VISION, ZKTeco, Shenzhen JER Technology, Enster Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Surveillance Camera Market Trends and Innovations
Specification tiers across resolution and AI integration are collapsing into unified procurement standards as municipal buyers consolidate vendor lists and demand interoperable platforms.
Edge-computing chipsets with on-device video analytics are bifurcating the product landscape. These processors execute facial recognition and behavior detection without cloud dependency. Railway authorities and critical infrastructure operators are adopting them for latency-sensitive applications. The technology is bifurcating procurement into cloud-dependent economy tiers versus autonomous premium systems with diverging margin structures.
MIIT's GB/T cybersecurity standards are tightening firmware authentication and encryption requirements for all network-connected cameras. Manufacturers must submit source code audits and obtain network access licenses before commercial distribution. Government and state-owned enterprise procurement channels are responding by disqualifying uncertified models, compressing the qualified supplier base.
Municipal buyers are consolidating vendor relationships and demanding multi-year maintenance contracts bundled with hardware procurement. System integrators and value-added distributors are displacing pure equipment resellers in major metropolitan tenders. This concentration is most visible in Hangzhou and Shenzhen smart city programs where single-source awards are replacing fragmented multi-vendor deployments.
China Surveillance Camera Market Segmentation
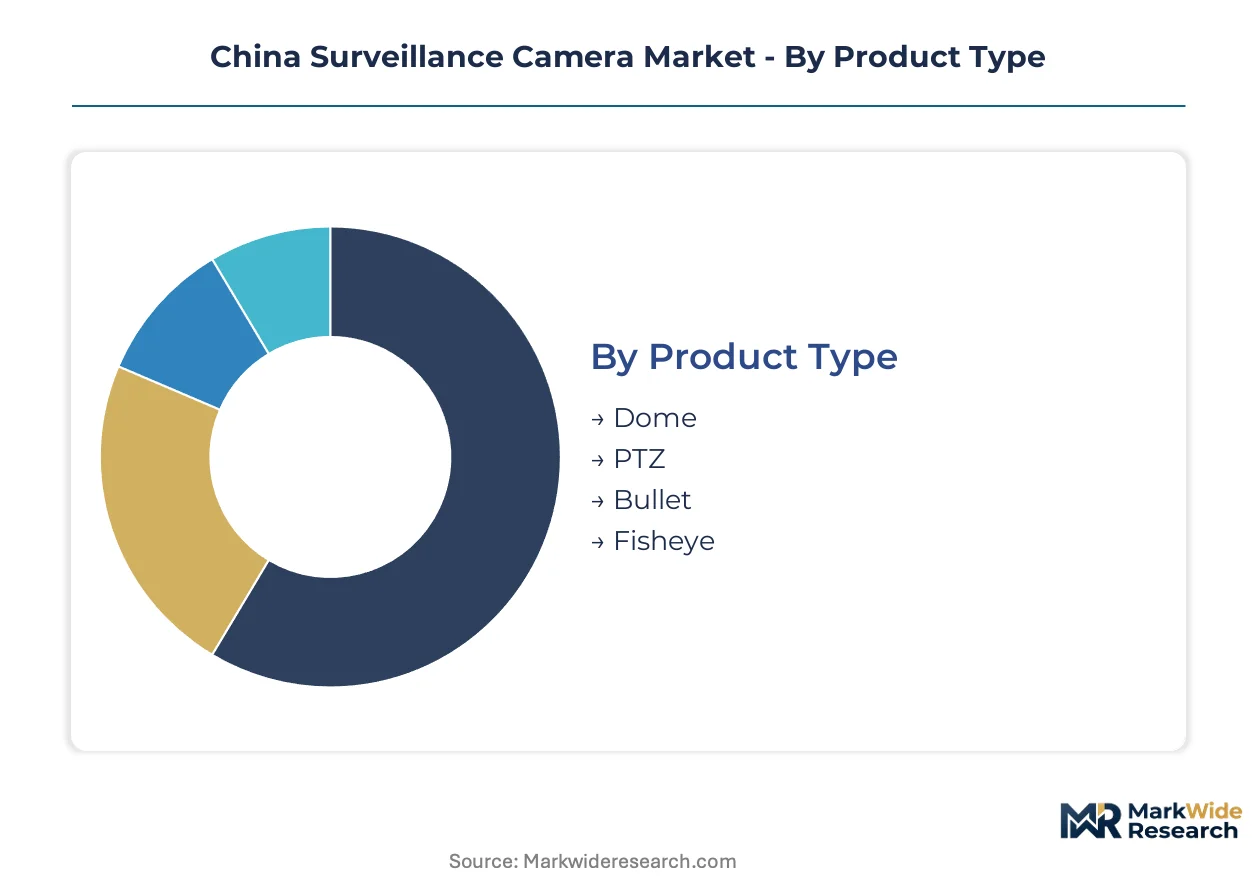
Product differentiation across China's surveillance camera market determines procurement eligibility for municipal tenders and enterprise contracts. Specification tiers increasingly collapse as MIIT certification requirements standardize minimum performance thresholds across all segments.
Product Type:
Margin pools concentrate in PTZ and specialized dome configurations where remote control capabilities and vandal-resistant engineering justify premium positioning.
- Dome:Vandal-resistant housings enclose 360-degree coverage mechanisms for indoor commercial deployments. Hangzhou municipal authorities specify dome cameras for subway station platforms and retail corridor monitoring under smart city procurement frameworks.
- PTZ:Pan-tilt-zoom actuators enable remote directional control through motorized lens assemblies. Railway authorities deploy PTZ units along high-speed corridors where real-time operator intervention replaces fixed-view limitations.
- Bullet:Cylindrical weather-sealed housings mount on exterior walls across transportation infrastructure. Bullet cameras dominate highway authority specifications for license plate recognition at toll plazas.
- Fisheye:Ultra-wide-angle optics capture panoramic single-sensor coverage for indoor logistics facilities. Uniview specializes in this whitespace segment distinct from saturated government verticals.
The dominant share belongs to Dome, while Fisheye is closing the gap fastest.
Technology:
Application requirements drive divergence between legacy infrastructure preservation and IP-native deployment patterns.
- IP:Ethernet-transmitted digital video streams support 4K resolution and embedded analytics through ONVIF-compliant protocols. Transportation sector digitization mandates from railway and highway authorities are accelerating displacement of coaxial infrastructure.
- Analog:Coaxial-cable signal transmission persists in budget-constrained retrofit scenarios. Legacy analog integration friction creates commissioning complexity where hybrid backbones combine existing wiring with IP headends.
- Wireless:Cellular and Wi-Fi protocols enable rapid deployment without structured cabling. MIIT spectrum allocation constraints restrict deployment flexibility for cellular-enabled surveillance units in unlicensed bands.
- IP67:Ingress protection ratings certify dust-tight housing and water immersion resistance for harsh environments. Industrial facilities and coastal transportation corridors specify IP67-rated enclosures for corrosion protection.
IP commands the installed base majority, with Wireless gaining share fastest where cabling costs dominate project economics.
End User:
Customer procurement sophistication varies sharply between state-mandated technical standards and commercial flexibility.
- Transportation:Railway and highway authorities deploy high-definition networks for real-time corridor surveillance. MIIT network access licensing creates predictable demand pipelines through mandatory certification requirements.
- Commercial:Retail and logistics facilities prioritize fisheye panoramic systems for inventory monitoring. System integrators displace pure equipment resellers as municipal buyers consolidate vendor relationships.
- Industrial:Critical infrastructure operators specify edge-computing chipsets for latency-sensitive applications. Edge AI convergence opens premium positioning through on-device inference without cloud dependency.
- Residential:Consumer-grade specifications emphasize mobile app integration and cloud storage subscriptions. Data localization compliance costs from MEE requirements inflate total cost of ownership for connected home systems.
Transportation holds the dominant procurement volume, while Industrial is expanding most quickly through edge-computing adoption.
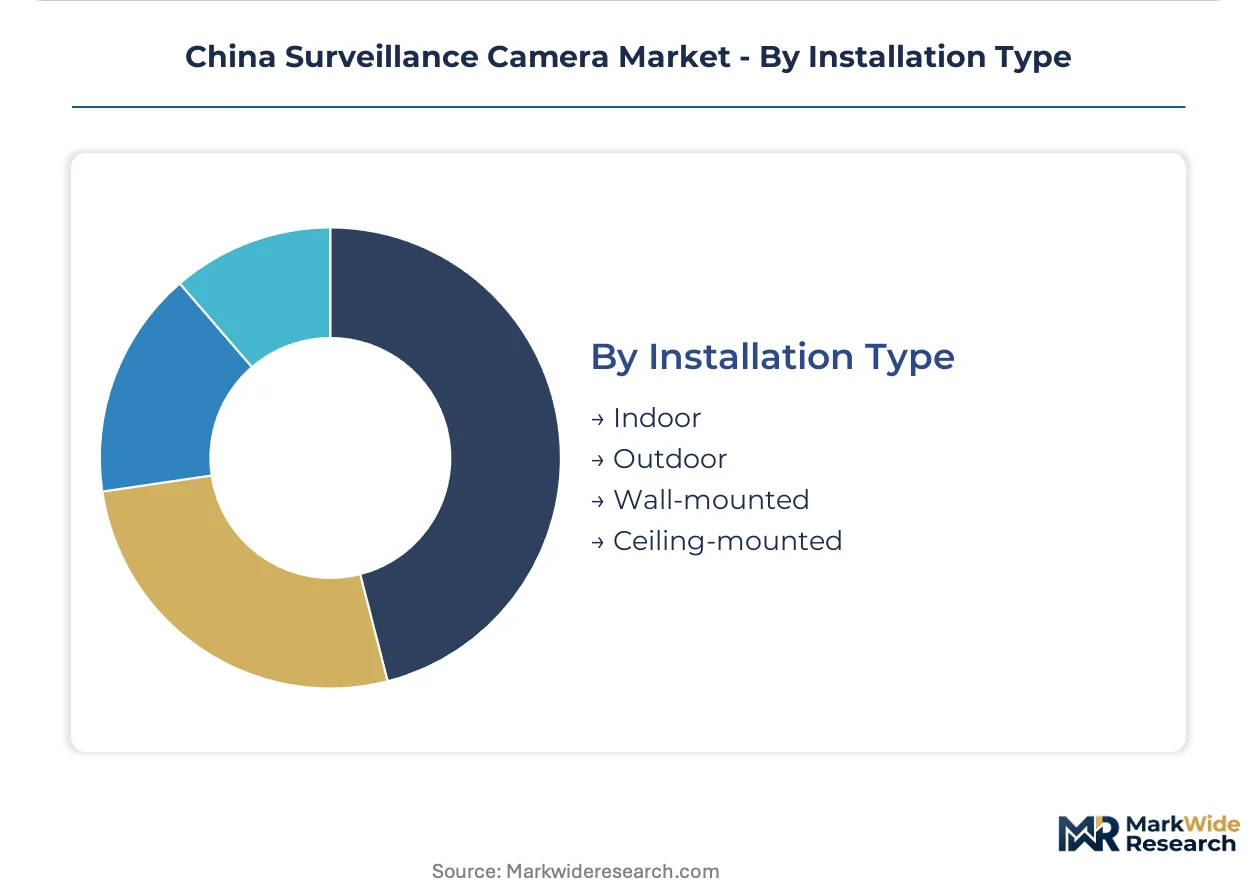
Installation Type:
Physical mounting constraints determine housing specifications and field service requirements across deployment scenarios.
- Outdoor:Weather-sealed enclosures with heater-blower modules sustain temperature extremes. Wall-mounted bullet configurations dominate transportation corridor deployments.
- Indoor:Aesthetic housing designs blend with commercial interior finishes. Ceiling-mounted dome units provide 360-degree coverage for lobby and corridor monitoring.
- Wall-mounted:Cantilever brackets position lenses for optimal sightlines across perimeters. Highway authority specifications standardize wall-mounted bullet cameras at toll plaza approaches.
- Ceiling-mounted:Recessed and surface-mount options accommodate structural constraints in transit facilities. Subway station platforms specify ceiling-mounted dome cameras for passenger flow analytics.
Outdoor installations constitute the primary deployment mode, with Ceiling-mounted climbing fastest through transit infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's surveillance camera production capacity substantially exceeds domestic absorption, positioning the country as a net exporter of finished equipment and imaging components to Southeast Asian and Middle Eastern markets. Import flows concentrate on specialized CMOS sensors and precision optical assemblies from Japanese and South Korean suppliers. Regional demand patterns diverge sharply between coastal megacities with mature smart city deployments and interior provinces still building foundational video infrastructure.
Guangdong Province
Shenzhen municipal authorities command the nation's densest concentration of AI-enabled video analytics procurement, driven by integrated safe-city and transportation digitization mandates. SAMR's CCC marking enforcement creates compliance bottlenecks that filter qualified suppliers for state-owned enterprise tenders. The Pearl River Delta manufacturing cluster anchors dome and bullet camera assembly lines serving both domestic deployment and export markets.
Zhejiang Province
Hangzhou's smart city infrastructure program generates sustained demand for subway platform monitoring and retail corridor surveillance systems. MIIT network access licensing requirements standardize procurement specifications across municipal departments. The Yangtze River Delta technology corridor concentrates edge-computing chipset development for latency-sensitive industrial applications.
Sichuan Province
Chengdu municipal budgets for safe-city programs remain under-deployed relative to coastal counterparts, creating procurement acceleration potential. MEE data localization requirements force video feed storage infrastructure investments that inflate total cost of ownership. The Sichuan-Chongqing economic zone represents a whitespace frontier for fisheye panoramic systems in logistics facilities.
Beijing-Tianjin-Hebei
Railway authority digitization mandates drive high-definition IP camera network deployment along high-speed corridors connecting the capital region. GB/T cybersecurity certification frameworks compress development cycles while raising compliance barriers for smaller suppliers. The Beijing technology hub concentrates firmware security engineering talent scarce in broader domestic labor markets.
Shandong Province
Highway authority specifications for license plate recognition at toll plazas sustain bullet camera demand across transportation infrastructure. Industrial facility operators specify IP67-rated enclosures for corrosion protection in coastal deployment environments. The Shandong Peninsula manufacturing base supports weather-sealed housing production for harsh-environment outdoor installations.
China Surveillance Camera Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and captive supply chain control. The supplier base concentrates around three domestic conglomerates with integrated semiconductor capabilities, while mid-tier assemblers compete on price for commercial verticals. Strategic archetypes include vertically integrated platform providers, component-specialized fabricators, and regional system integrators. Competitive moves center on MIIT certification pre-qualification and multi-year maintenance contract bundling.
Within the platform-provider tier, Hikvision and Dahua Technology exemplify integrated supply chain control through in-house semiconductor production. Uniview occupies a distinct position specializing in fisheye panoramic configurations for commercial indoor deployments. These three anchors represent divergent strategic bets on scale economies versus segment specialization.
| Leading Market Players |
|---|
| Hikvision |
| Dahua Technology |
| Uniview |
| Tiandy Technologies |
| Milesight Technology |
| LS VISION |
| ZKTeco |
| Shenzhen JER Technology |
| Enster Electronics |
| Others |
Pricing and Supply Chain Analysis
Ninety-day semiconductor inventory cycles at CMOS sensor foundries concentrate pricing power among three domestic conglomerates while compressing margin buffers for mid-tier assemblers competing on commercial tenders. MIIT certification delays extending procurement timelines by six to eight weeks reinforce captive supply advantages for vertically integrated platform providers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with MIIT GB/T certification tier and volume scale as primary differentiation drivers. Cost compression in economy segments is intensifying because municipal buyers bundle multi-year maintenance contracts with hardware procurement, shifting margin capture toward service attach. Transportation authorities exhibit lowest price sensitivity due to mandated network access licensing requirements, while residential consumer segments face highest elasticity as MEE data localization compliance inflates total cost of ownership.
Supply Chain Analysis
Container availability constraints along the Yangtze River Delta to Pearl River Delta trade lane expose inbound logistics volatility for Japanese and South Korean CMOS sensor shipments. Domestic production draws from Taiwan wafer foundries, South Korean memory suppliers, and local precision optical assembly clusters, with single-source vulnerability concentrated in advanced image signal processor design. Distribution runs through state-owned enterprise procurement channels and municipal system integrators displacing pure equipment resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-year maintenance contract bundling now expands faster than hardware unit shipments as municipal buyers consolidate vendor relationships and demand predictive analytics subscriptions. This service-attach dynamic repositions margin pools toward recurring revenue streams.
For Market Incumbents: Shield certification-compliant product lines against firmware security engineering talent scarcity by deepening in-house embedded systems capabilities before GB/T standards tighten further. Prioritize backward integration into edge-computing chipsets to capture premium positioning in industrial PTZ applications where latency-sensitive deployments command pricing power. For New Entrants and Emerging Players: Anchor in Chengdu and Xi'an municipal safe-city programs where procurement acceleration potential exceeds coastal saturation levels. Target fisheye panoramic systems for logistics facilities as a whitespace segment distinct from government verticals dominated by established platform providers. Pursue system integrator partnerships rather than direct OEM channel competition. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-premium play because MIIT network access licensing creates predictable demand pipelines while compressing the qualified supplier base. Acquisition targets should display pre-certified hardware architectures and captive maintenance contract portfolios. Watch for GB/T standard revision announcements as inflection indicators for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Pre-Qualification | GB/T compliance gates government procurement and compresses qualified supplier lists. |
| Edge AI Chipset Integration | On-device inference opens premium positioning in railway and critical infrastructure deployments. |
| Multi-Year Maintenance Contract Bundling | Municipal buyers in Hangzhou and Shenzhen consolidate vendors through service attach requirements. |
| Western Region Channel Expansion | Chengdu and Xi'an safe-city budgets remain under-deployed relative to coastal counterparts. |
| Fisheye Panoramic Specialization | Uniview's segment focus demonstrates whitespace viability in commercial indoor logistics facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT network access license databases, SAMR CCC marking registries, and municipal procurement disclosure records. Discussions with system integration engineers, state-owned enterprise procurement officers, firmware security architects, and edge-computing chipset designers informed demand-side validation. Bottom-up unit shipment estimates triangulate against top-down infrastructure budget allocations across provincial safe-city programs.
Segmentation dimensions modeled include product type, technology protocol, end-user vertical, installation environment, and regional municipal budget deployment stage across the analysis window. CAGRs derive from infrastructure investment trajectories, replacement cycle assumptions for legacy analog systems, and certification timeline impacts on qualified supplier capacity. Railway authority digitization mandates and MEE data localization enforcement serve as key demand and cost-side forecast inputs.
Underlying assumptions cover sustained MIIT certification enforcement, stable semiconductor input availability, and continued municipal smart city budget prioritization, with deviation risk concentrated in wireless spectrum allocation policy shifts and export control expansions affecting CMOS sensor supply. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Japan Surveillance Camera Market