
 Europe Process Safety Services Market | 2026-2036
Europe Process Safety Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Process Safety Services Market Foresight
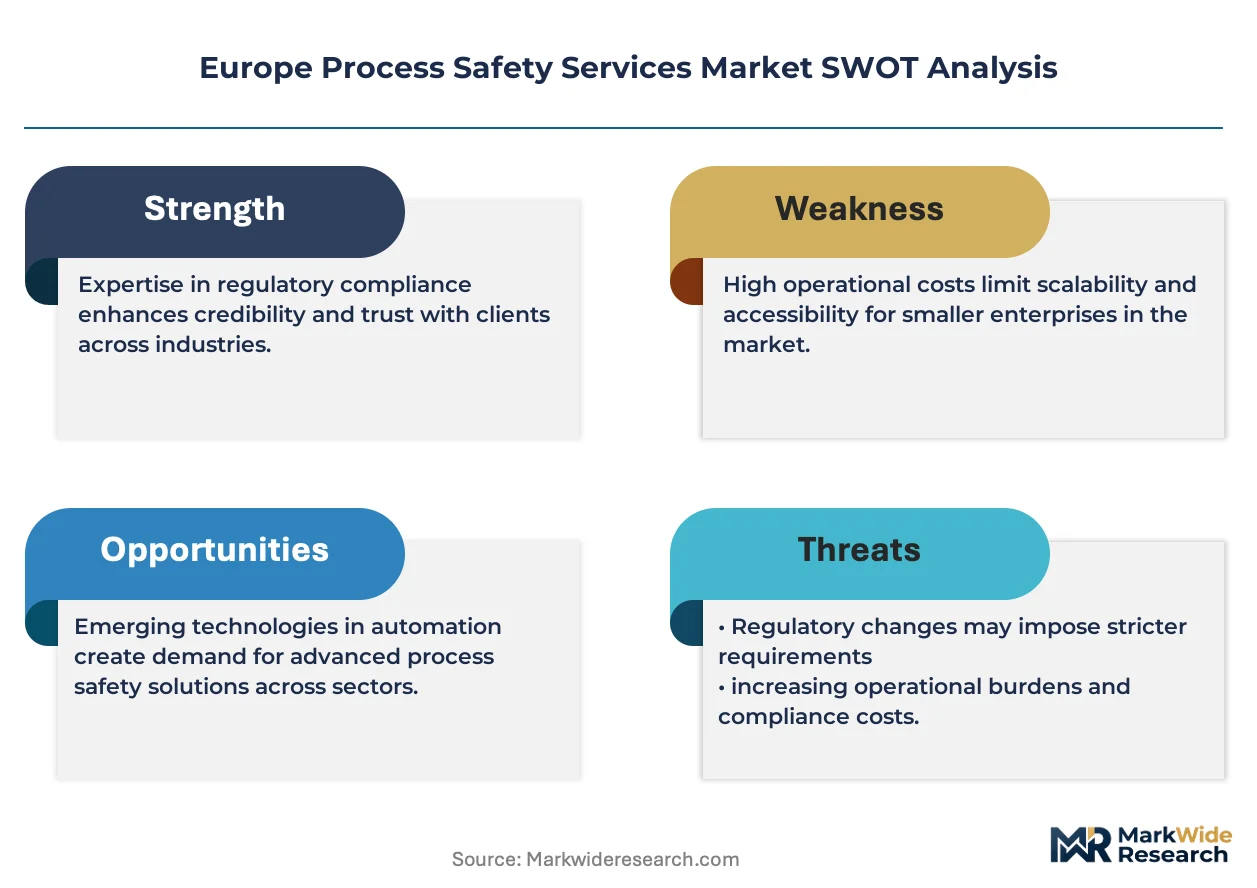
Germany's Rhine-Ruhr industrial corridor is fragmenting as new safety consultancies enter alongside established engineering firms. Emerson Electric Co. leverages its automation heritage to anchor integrated safety-instrumented system offerings. Bureau Veritas competes through its TIC network, while TÜV SÜD sustains credibility via German-accredited testing authority status.
Europe Process Safety Services encompass engineered consulting, training, auditing, and hazard analysis delivered to process industries managing toxic, flammable, or explosive materials. Functional safety lifecycle management under IEC 61511 standards governs SIL verification, proof testing intervals, and safety requirement specifications for chemical, pharmaceutical, and hydrocarbon facilities. Consulting and assessment services dominate revenue pools due to recurring regulatory mandates, while remote delivery models grow fastest as digital twin deployments enable virtual hazard and operability studies. The oil and gas vertical maintains mature spend levels, though pharmaceutical safety services capture expanding margins from ATEX and containment validation demands.
EU Seveso III Directive, REACH, and ATEX Directive 2014/34/EU collectively mandate systematic safety management systems, driving recurring third-party assessment demand across member states. ECHA substance restrictions and national competent authority enforcement create compliance deadlines that manufacturers cannot defer without operational shutdown risk. Stakeholders must monitor how the EU Green Deal's chemical sustainability transitions reshape process hazard profiles and corresponding service specifications.
Market Dynamics
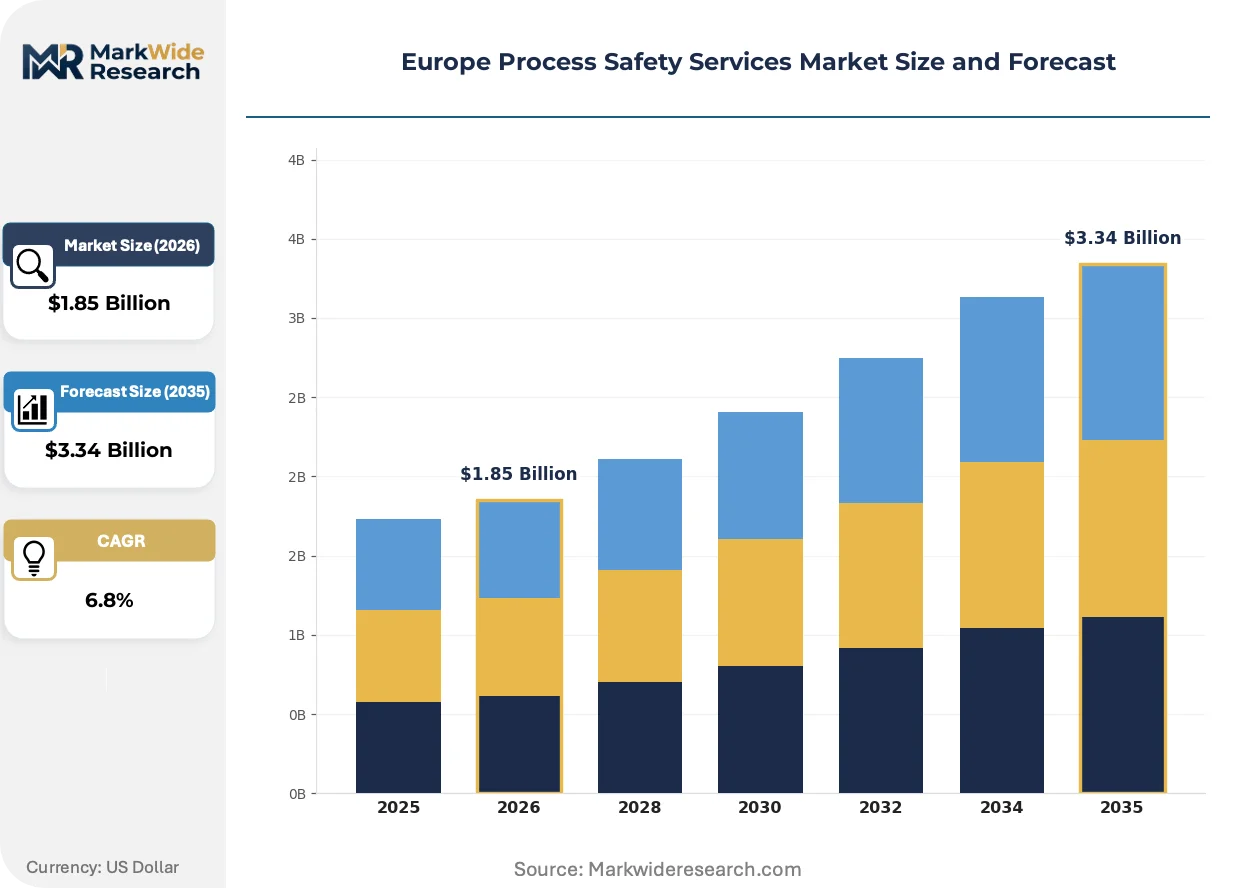
EU Seveso III Directive amendments are forcing chemical manufacturers across member states to escalate third-party safety assessment frequency, converting episodic consulting engagements into recurring revenue streams for specialized service providers.
Growth Catalysts
- Seveso III Directive enforcement:Competent authorities in Germany, France, and the Netherlands mandate systematic safety management systems for upper-tier establishments, creating non-discretionary spend on external verification.
- Digital twin adoption:Chemical and pharmaceutical facilities deploy virtual plant models to conduct remote hazard and operability studies, expanding addressable service volume beyond physical site visits.
- ATEX compliance expansion:Explosive atmosphere directives now cover pharmaceutical containment validation and battery manufacturing, opening adjacent verticals to established process safety consultancies.
Market Restraints
- Qualified engineer scarcity:Functional safety certification under IEC 61511 requires specialized competence that universities and vocational programs cannot replenish at market demand rates.
- Client procurement consolidation:Large chemical multinationals centralize safety service buying through preferred vendor frameworks, squeezing mid-tier consultancies on margin and access.
- Remote delivery limitations:Regulatory bodies in several member states still mandate physical presence for certain audit types, capping efficiency gains from virtual service models.
Strategic Opportunities
- Poland and Czech Republic industrial corridors:Greenfield chemical investments in Central Europe lack established local safety consultancy infrastructure, creating first-mover positioning for expanding German and French providers.
- EU Green Deal chemical transitions:Substance substitution mandates and sustainable process redesigns alter hazard profiles, requiring updated safety requirement specifications and SIL verification.
- Cross-functional integration:Convergence of process safety with cybersecurity for industrial control systems enables bundled service offerings at premium pricing.
Industry Challenges
- Legacy system integration:Safety instrumented system upgrades in brownfield facilities must interface with decades-old distributed control architectures, complicating verification and validation protocols.
- Talent retention pressure:Experienced hazard analysts face poaching from equipment vendors offering equity participation, destabilizing consultancy technical depth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Process Safety Services Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Training, Assessment, Auditing Industry Vertical: Pharmaceutical, Oil & Gas, Chemicals, Food & Beverage Application: Hazard Analysis, Risk Assessment, Compliance Management, Incident Investigation Delivery Model: On-site, Remote, Hybrid, Custom |
| Companies Covered | Emerson Electric Co., Rockwell Automation, Inc., Honeywell International Inc., Intertek Group plc, Bureau Veritas, ABB Ltd., Siemens AG, TÜV SÜD, Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Process Safety Services Market Shifts & Advancements
Digital instrumentation and connected plant architectures are compressing proof testing intervals while enabling predictive safety performance monitoring. Service providers must reconfigure delivery models around continuous rather than periodic engagement.
Machine learning algorithms applied to historical incident databases and real-time sensor feeds are digitizing hazard identification workflows. Major chemical manufacturers in the Rhine-Ruhr corridor pilot these tools for predictive risk scoring. The technology is digitizing how safety requirement specifications get generated, compressing front-end engineering design cycles from months to weeks.
ECHA substance restriction proposals under REACH are forcing reformulation safety assessments for thousands of chemical registrations. Industrial consequence includes mandatory re-evaluation of process hazard analyses when feedstock compositions change. Specialty chemical segments in Belgium and northern Italy face the densest compliance deadlines, driving emergency consulting engagements.
Buyer procurement patterns are fragmenting as mid-sized chemical manufacturers bypass traditional engineering procurement and construction contractors to contract safety consultancies directly. This disintermediation is most visible in pharmaceutical manufacturing clusters around Basel and Cork, where facility owners seek specialized ATEX and containment expertise unavailable through generalist construction managers.
Europe Process Safety Services Market Segmentation
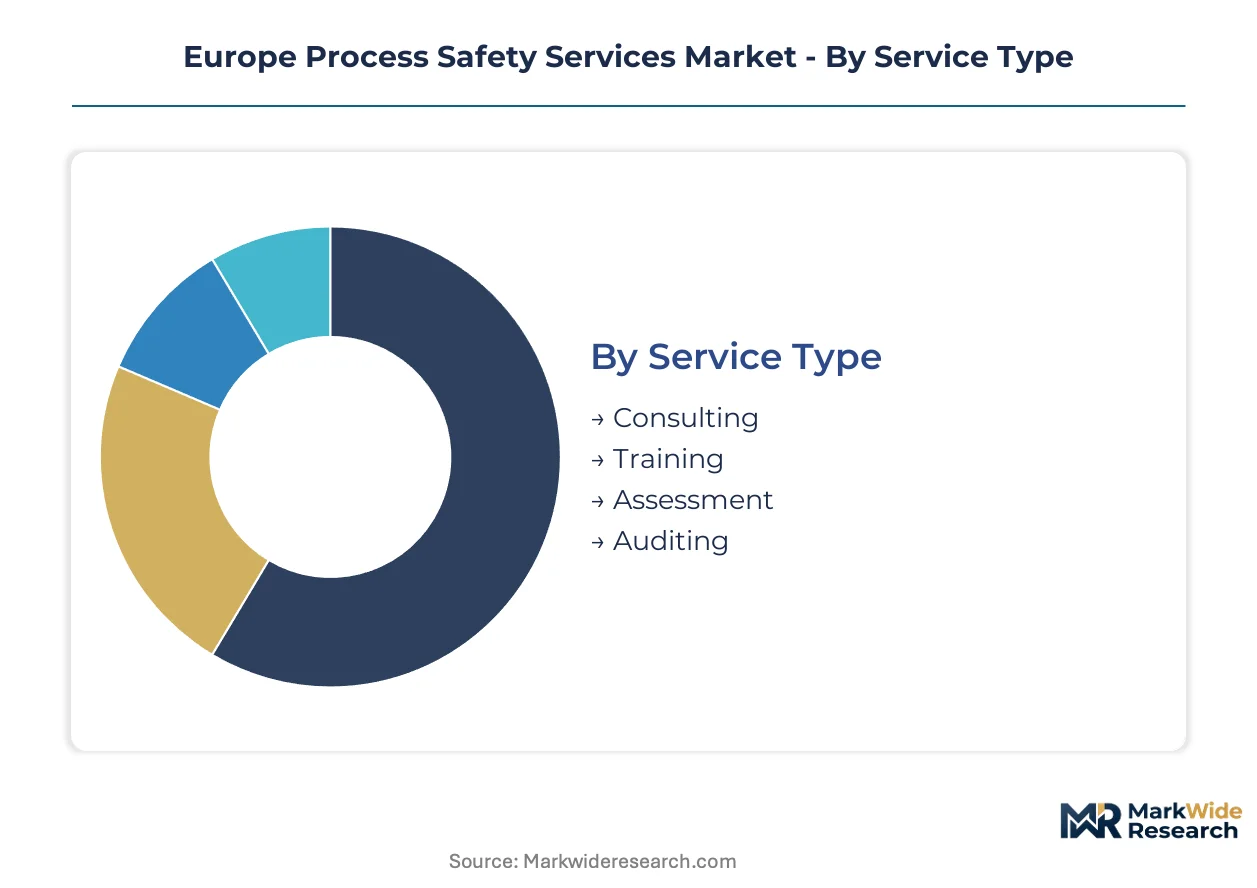
Process safety services in Europe fragment across service archetypes, industrial end-uses, and delivery modalities that dictate contract structures and margin profiles. Regulatory mandates under Seveso III and REACH create divergent service intensity across verticals, while digital instrumentation is compressing traditional site-visit economics.
Service Type:
Cost tier structures the procurement landscape, with premium advisory commanding multiples over commoditized training modules.
- Consulting:Front-end engineering design support, SIL verification, and safety requirement specification development for hazardous facility upgrades. Rhine-Ruhr chemical manufacturers concentrate spend here as Seveso III mandates escalate external verification frequency.
- Assessment:Systematic safety management system audits, process hazard analysis revalidation, and compliance gap analysis against IEC 61511 standards. Dutch and Belgian competent authorities drive non-discretionary demand through enforcement deadlines.
- Training:Functional safety certification programs and competent person qualification under national implementing regulations.
- Auditing:Third-party verification of safety instrumented system performance and proof testing interval compliance.
Consulting holds installed capacity. Assessment is rotating up the share rankings.
Industry Vertical:
Application context determines hazard profile complexity and corresponding service specification depth.
- Chemicals:Continuous and batch process safety lifecycle management for toxic, flammable, and explosive material handling. Upper-tier Seveso establishments in Germany and France sustain the deepest recurring consulting relationships due to mandatory external verification cycles.
- Pharmaceutical:ATEX compliance for solvent handling, containment validation for potent compound manufacturing, and cleanroom safety system design. Basel and Cork manufacturing clusters generate specialized demand exceeding generalist contractor capabilities.
- Oil & Gas:Mature safety management system maintenance for upstream and downstream hydrocarbon facilities.
- Food & Beverage:Dust explosion protection and thermal process safety for spray drying and solvent extraction operations.
Chemicals holds installed capacity. Pharmaceutical is rotating up the share rankings.
Application:
Volume concentration tracks regulatory enforcement intensity and facility modification cycles.
- Hazard Analysis:HAZOP, LOPA, and bow-tie methodology execution for process design modifications and substance substitution projects. ECHA restriction proposals under REACH force reformulation safety reassessments across Belgian and northern Italian specialty chemical segments.
- Compliance Management:Safety management system documentation, regulatory submission preparation, and competent authority liaison. Upper-tier Seveso establishments in the Netherlands face compressed deadlines driving emergency consulting engagements.
- Risk Assessment:Quantitative consequence modeling and frequency analysis for insurance and regulatory purposes.
- Incident Investigation:Root cause analysis and safety requirement specification updates following process safety events.
Hazard Analysis holds installed capacity. Compliance Management is rotating up the share rankings.
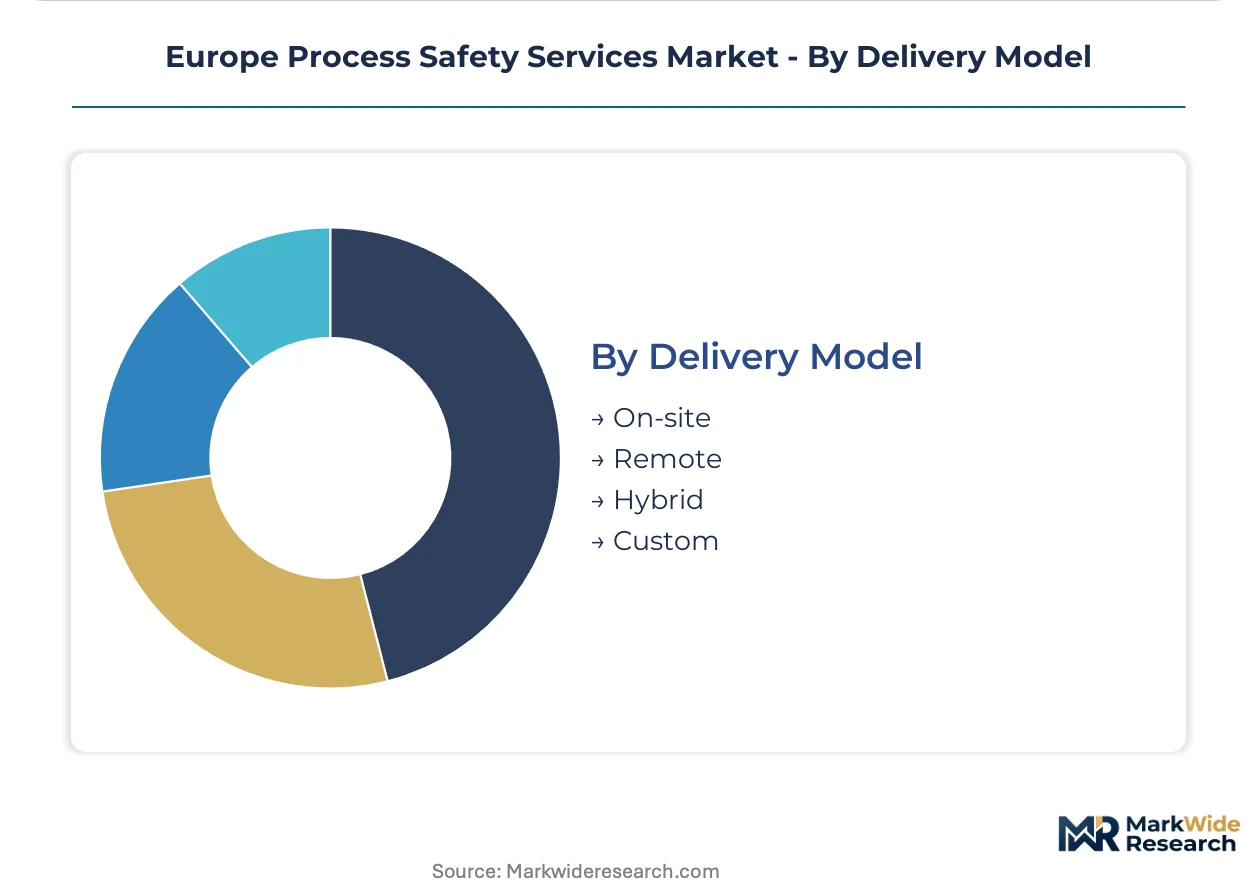
Delivery Model:
Customer type preferences are fragmenting as mid-sized manufacturers bypass traditional engineering procurement channels.
- Hybrid:Blended remote and physical presence models optimizing cost and regulatory acceptability. German and French providers pilot this structure for Central European greenfield investments lacking established local consultancy infrastructure.
- Remote:Virtual hazard and operability studies enabled by digital twin deployments and connected plant architectures. Several member states still mandate physical presence for certain audit types, capping addressable volume.
- On-site:Traditional facility-based service delivery for brownfield verification and regulatory body inspections.
- Custom:Embedded safety engineering teams and long-term outsourcing arrangements for major chemical multinationals.
On-site holds installed capacity. Hybrid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider capacity concentrates in Germany's industrial heartland, where Seveso III enforcement generates sustained demand for external verification. Competent authorities in France and the Netherlands compress compliance deadlines, while Central European chemical investments outpace local safety consultancy infrastructure.
Germany
The Rhine-Ruhr corridor hosts Europe's densest cluster of upper-tier Seveso establishments, driving non-discretionary spend on third-party safety management system audits. Federal Environment Agency enforcement of amended Seveso III provisions mandates systematic external verification cycles that manufacturers cannot defer. Ludwigshafen and Leverkusen chemical complexes sustain recurring consulting relationships for SIL verification and process hazard analysis revalidation.
France
Seine Valley petrochemical facilities and Normandy refineries generate mature demand for functional safety lifecycle management under IEC 61511 standards. Bureaucratic reinforcement of Seveso III through the Ministry of Ecological Transition accelerates compliance gap analysis engagements. Lyon and Grenoble pharmaceutical manufacturing clusters require specialized ATEX compliance services for solvent handling operations.
Netherlands
Rotterdam port industrial complex and Chemelot chemical cluster face compressed competent authority deadlines for safety instrumented system performance verification. Dutch Environment and Transport Inspectorate mandates physical presence for certain audit types, capping remote delivery adoption. Antwerp-Rotterdam-Rhine-Ruhr pipeline corridor sustains cross-border service provider mobility.
Belgium
Antwerp petrochemical hub and Ghent pharmaceutical manufacturing generate emergency consulting engagements from ECHA substance restriction proposals under REACH. Federal Public Service Environment enforces reformulation safety reassessments across specialty chemical segments. Flanders industrial corridor experiences densest compliance deadline clustering in northern Europe.
Poland
Upper Silesian and Płock industrial corridors attract greenfield chemical investments lacking established local safety consultancy infrastructure. Polish Inspectorate of Environmental Protection transposes Seveso III requirements with implementation lags creating first-mover positioning for expanding German providers. Warsaw and Kraków emerging as secondary demand nodes for pharmaceutical safety services.
Europe Process Safety Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in verification and testing niches. The vendor base stratifies across automation heritage conglomerates, accredited testing authorities, and specialized consultancies. Engineering procurement contractors and independent safety consultancies represent distinct strategic archetypes. Competitive moves concentrate on geographic expansion into Central European greenfield corridors and cross-functional integration with cybersecurity offerings.
Within the automation-heritage tier, Emerson Electric Co., Rockwell Automation, Inc., and Siemens AG anchor integrated safety-instrumented system offerings that bundle hardware with lifecycle consulting. These entities occupy positions where functional safety verification intersects with distributed control architecture deployment. TÜV SÜD exemplifies the accredited testing authority archetype, leveraging German regulatory credibility for third-party assessment mandates. Bureau Veritas and Intertek Group plc represent transnational TIC network competitors competing through geographic coverage density rather than vertical technology integration.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Rockwell Automation, Inc. |
| Honeywell International Inc. |
| Intertek Group plc |
| Bureau Veritas |
| ABB Ltd. |
| Siemens AG |
| TÜV SÜD |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr corridor concentrates accredited safety consultancy capacity, creating pricing power for German providers serving Seveso III verification mandates across Benelux and Central European markets. This geographic clustering allows established firms to command premium rates for IEC 61511 functional safety certification while mid-tier competitors face margin compression from client procurement consolidation.
Pricing Analysis
EU Seveso III Directive dictates the pricing tier structure across the European process safety services landscape. Three-tier pricing structure across premium, standard, and economy levels separates German-accredited testing authorities from regional generalists and commodity training providers. Price differentiation centers on certification grade under IEC 61511 standards and after-sales service bundling with safety instrumented system lifecycle management. Cost compression in the standard tier is intensifying because large chemical multinationals centralize buying through preferred vendor frameworks. Mid-sized pharmaceutical manufacturers in Basel and Cork demonstrate highest price sensitivity, while upper-tier Seveso establishments show lowest sensitivity due to non-discretionary compliance deadlines.
Supply Chain Analysis
Engineering procurement contractors in Germany, France, and the Netherlands hold dominant contract-manufacturing concentration for integrated safety service delivery. Raw material inputs draw from specialized functional safety engineers, digital twin software licenses, and regulatory documentation systems. Supply chain risk centers on single-source vulnerability for IEC 61511-certified hazard analysts, as universities cannot replenish technical talent at market demand rates. Distribution runs through direct enterprise sales teams for major automation conglomerates and specialized consultancy networks for compliance-focused assessments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European process safety services represent an early-cycle expansion story. Digital twin adoption for remote hazard and operability studies accelerates service volume beyond physical site visit constraints, creating new addressable market layers.
For Market Incumbents: Insulate technical depth by embedding equity participation for senior hazard analysts, countering poaching from equipment vendors. Deepen backward integration into proprietary digital twin platforms to differentiate from TIC network competitors. Prioritize certification investment in ATEX compliance for pharmaceutical containment validation, capturing margin expansion from Basel and Cork manufacturing clusters. For New Entrants and Emerging Players: Pursue white-space positioning in Poland and Czech Republic industrial corridors, where greenfield chemical investments lack established local safety consultancy infrastructure. Target hybrid delivery models for Central European facilities, combining remote digital twin capabilities with periodic physical presence. Anchor go-to-market strategy through partnerships with German engineering procurement contractors seeking geographic extension. For Investors and Strategic Acquirers: Carve-out targets emerge from automation conglomerates divesting non-core safety consulting divisions to focus on hardware margins. Long-term viability over a 5-10 year window rests on regulatory enforcement durability under EU Green Deal chemical sustainability transitions. Monitor ECHA substance restriction proposal velocity as the inflection signal for emergency consulting demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion into Central Europe | Polish and Czech greenfield chemical investments lack local safety consultancy infrastructure. |
| Digital Twin Platform Integration | Virtual HAZOP studies enabled by connected plant architectures compress proof testing intervals. |
| Cross-Functional Cybersecurity Bundling | Convergence with industrial control system security enables premium-priced service offerings. |
| ATEX Compliance Specialization | Pharmaceutical containment validation in Basel and Cork captures expanding service margins. |
| Accredited Testing Authority Acquisition | German regulatory credibility under TÜV SÜD model creates defensive moats for third-party verification. |
Research Methodology
A standing panel of plant safety managers, regulatory affairs leads at chemical manufacturers, EPC procurement officers, and competent authority inspectors provided ongoing calibration for demand assumptions. Primary interviews with these stakeholders combined with secondary validation from ECHA restriction proposals, Seveso III implementation reports, IEC 61511 certification databases, and customs trade data. Bottom-up service provider capacity estimates triangulated against top-down regulatory mandate intensity across member states.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning service archetype, industry vertical, delivery modality, and regional enforcement cluster. CAGRs derived from regulatory deadline clustering analysis and facility modification cycle timing. Forecast inputs incorporated digital twin deployment rates and ECHA substance restriction pipeline velocity as industry-specific demand drivers.
Sensitivities concentrate around EU Green Deal implementation pace and Central European greenfield investment flows. Forecasts reflect assumptions on regulatory enforcement continuity and qualified engineer supply elasticity. Quarterly review of ECHA restriction proposal announcements and competent authority inspection frequency data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Noise Control System Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Industrial Noise Control Market