
 Advanced Disaster Management Simulator Market | 2026-2036
Advanced Disaster Management Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Disaster Management Simulator Market Outlook
The EU AI Act is hardening compliance requirements for autonomous decision-support modules embedded in disaster simulation platforms. Schneider Electric leverages its building-management software heritage to anchor integrated command-and-control environments. ETC Simulation specializes in high-fidelity wildfire and flood scenario engines for public-sector trainers. NEC Corporation extends its public safety communications infrastructure into simulation backbones across East Asian markets.
Advanced Disaster Management Simulators are computational training environments that replicate natural and anthropogenic hazards through physics-based modeling, real-time geospatial data ingestion, and multi-agent behavioral algorithms, typically rendering scenarios at 90 frames per second for virtual reality immersion. Their primary purpose is to accelerate decision-cycle proficiency among emergency coordinators without exposing personnel to live-risk conditions. Cloud-Based Solutions represent the fastest-expanding technology segment as agencies prioritize distributed access and reduced capital outlay, while On-Premises deployments retain dominance in defense and intelligence contexts where air-gapped security is non-negotiable. Incident Response applications command the deepest budget allocations among Government Agencies, whereas Educational Institutions are driving uptake of SaaS delivery models for curriculum integration.
The European Commission's CSRD mandates climate-risk disclosure protocols that directly stimulate corporate investment in scenario-planning tools. In the United States, FEMA's National Incident Management System certification standards shape procurement specifications for federally funded training programs. Japan's METI has issued resilience-technology roadmaps that channel subsidies toward earthquake-tsunami simulation platforms. Stakeholders must weigh interoperability commitments against the fragmentation risk posed by divergent national certification regimes.
Market Dynamics
Cloud migration is compressing capital barriers for municipal agencies while tightening cybersecurity requirements reshape procurement specifications across defense and civilian sectors simultaneously.
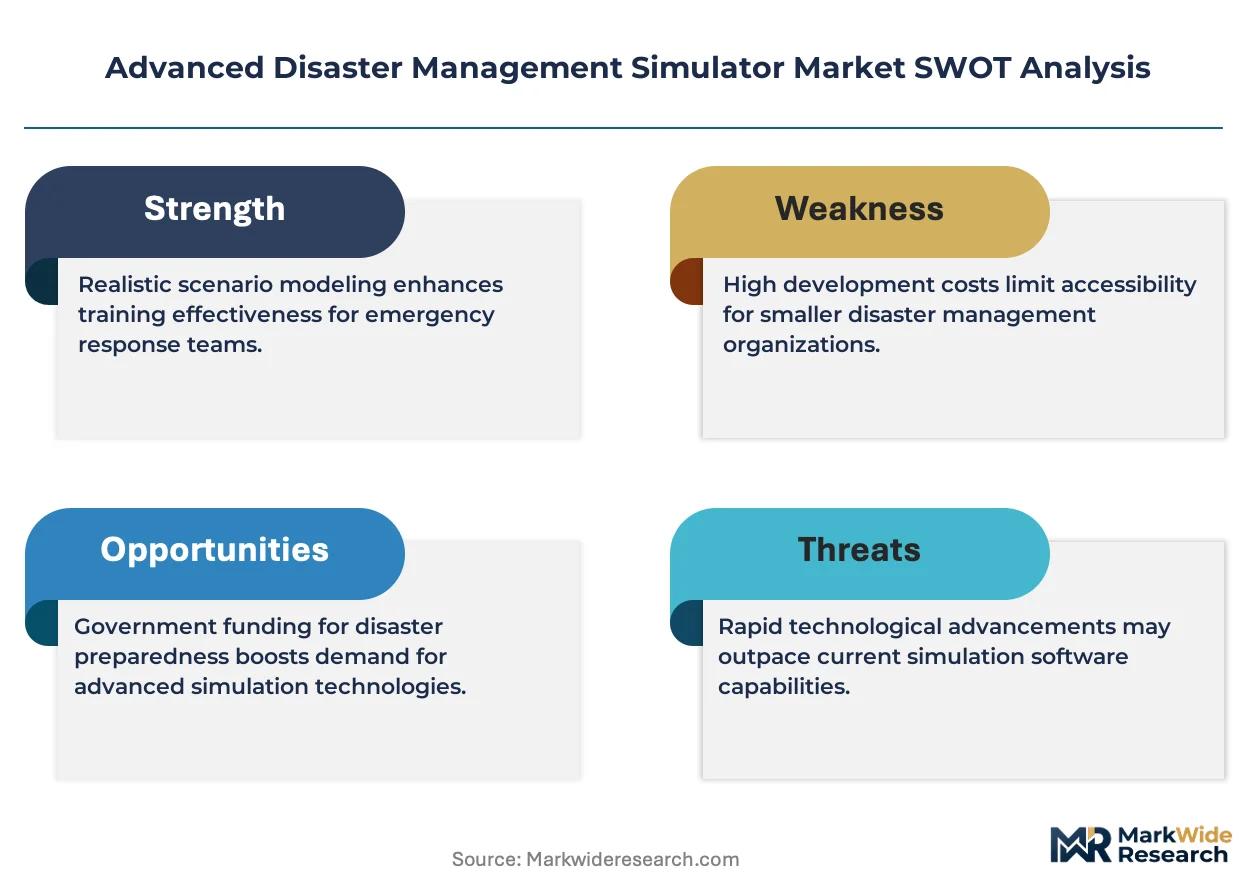
Growth Catalysts
- FEMA Certification Mandates:The National Incident Management System certification standards require simulation-based training for federally funded emergency response programs, forcing procurement upgrades across US fire departments and state agencies.
- EU AI Act Compliance:Autonomous decision-support modules in disaster platforms face hardened algorithmic transparency requirements, driving replacement cycles for legacy systems lacking audit trails.
- Earthquake-Tsunami Subsidies:Japan's METI resilience-technology roadmaps channel direct government funding toward multi-hazard simulation platforms, accelerating deployment timelines for coastal prefectures.
Market Restraints
- GPU Supply Concentration:Rendering engines demanding 90 frames per second for VR immersion depend on NVIDIA and AMD chip architectures, creating vulnerability to semiconductor export controls and foundry bottlenecks.
- Air-Gapped Security Premium:Defense and intelligence agencies require on-premises deployments with physical network isolation, imposing 40-60% cost premiums versus cloud alternatives and limiting vendor pool.
- Interoperability Fragmentation:Divergent national certification regimes across Germany, Japan, and the United States prevent scenario library portability, forcing redundant content development.
Strategic Opportunities
- CSRD Climate Disclosure:The European Commission's Corporate Sustainability Reporting Directive mandates scenario-planning for climate risk, opening enterprise sales channels beyond traditional government buyers.
- SaaS Curriculum Integration:Educational institutions seek subscription-based delivery models for emergency management degree programs, creating recurring revenue streams with lower sales friction.
- Geospatial-Twin Convergence:Real-time satellite data ingestion combined with physics-based hazard modeling enables live-event rehearsal capabilities that static scenario libraries cannot match.
Industry Challenges
- Multi-Agent Behavioral Modeling Talent:Simulators require expertise in crowd psychology and evacuation dynamics that sits at the intersection of computer science and social science, with limited specialized labor pools.
- Legacy SCADA Integration:Industrial control systems in critical infrastructure operators use proprietary protocols that resist standardized API connections, complicating realistic scenario construction.
- Cross-Border Data Sovereignty:Cloud-based training platforms storing geospatial vulnerability data face conflicting national security classifications that fragment deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Disaster Management Simulator Market |
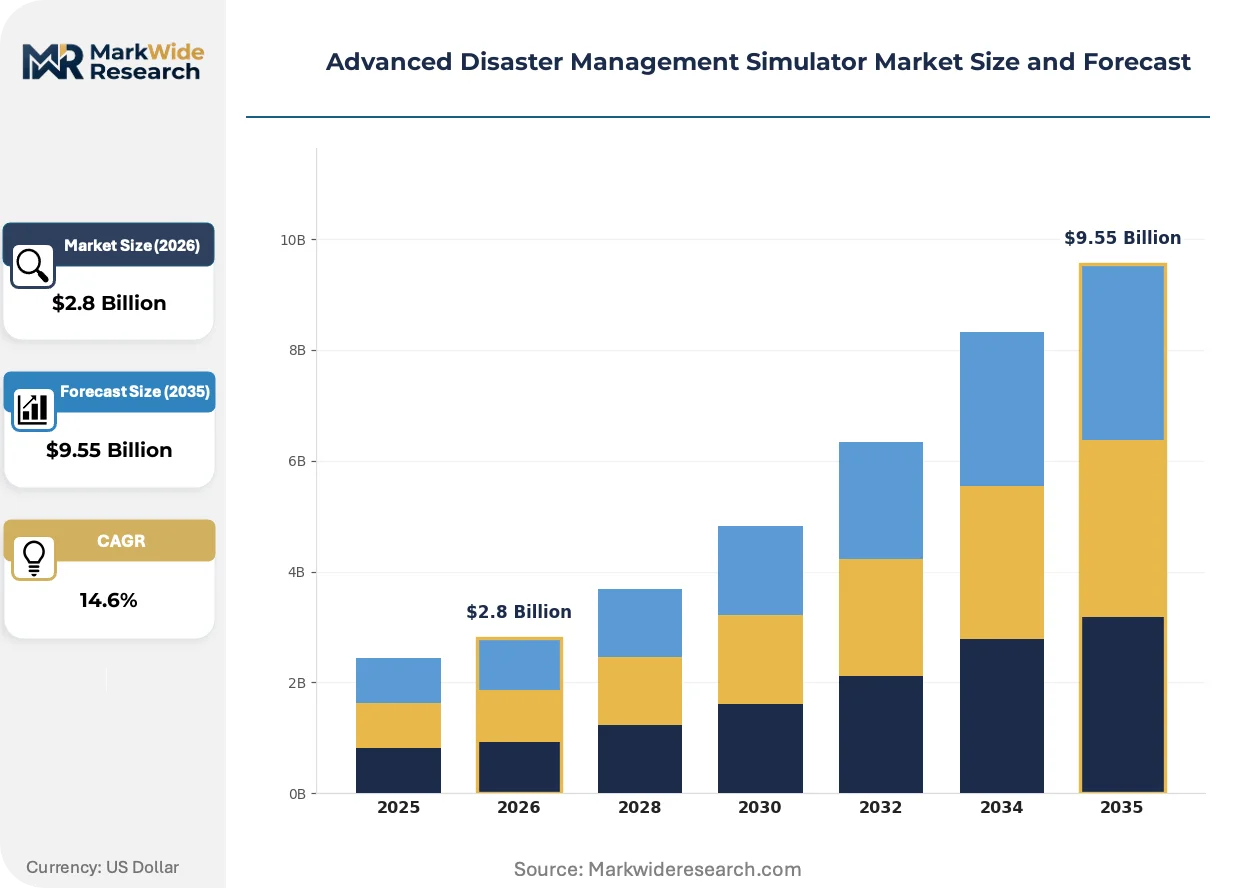
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Emergency Training, Incident Response, Risk Assessment, Resource Allocation Technology: Virtual Reality, Augmented Reality, Cloud-Based Solutions, Scenario Planning End User: Government Agencies, NGOs, Educational Institutions, Corporations Deployment: On-Premises, SaaS, Mobile Applications, Hybrid Models |
| Companies Covered | Schneider Electric, 3D Systems Corporation, ETC Simulation, Esri, Simtable, ForgeFX Simulations, IBM Corporation, The AnyLogic Company, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Disaster Management Simulator Market Strategic Shifts
Immersive rendering capabilities are advancing faster than organizational readiness to absorb them, creating capability gaps between technology availability and training program redesign.
Digital twin architectures are expanding into disaster management platforms by ingesting live sensor feeds from flood gauges, seismic monitors, and weather satellites to generate dynamic scenario branches. Municipal emergency managers in the Netherlands and New Zealand are piloting these systems for real-time levee-breach rehearsal. The technology is expanding into predictive decision-support by compressing the gap between simulation output and operational deployment.
The EU AI Act's risk-classification framework is reclassifying autonomous recommendation engines in command-and-control simulators as high-risk AI systems, imposing conformity assessment burdens on vendors. German federal civil protection agencies now require documented human-in-the-loop protocols for any automated resource allocation suggestions. Platform developers are responding by architecting explicit override mechanisms and audit logging as standard features rather than optional modules.
Subscription licensing is displacing perpetual purchase models among educational institutions and mid-sized municipal departments seeking to avoid capital appropriation cycles. SaaS delivery enables curriculum designers to update scenario content continuously rather than awaiting versioned software releases. This shift is most visible in US community college emergency management programs and Australian state fire service training academies, where annual operating budgets replace multi-year capital planning horizons.
Advanced Disaster Management Simulator Market Segmentation
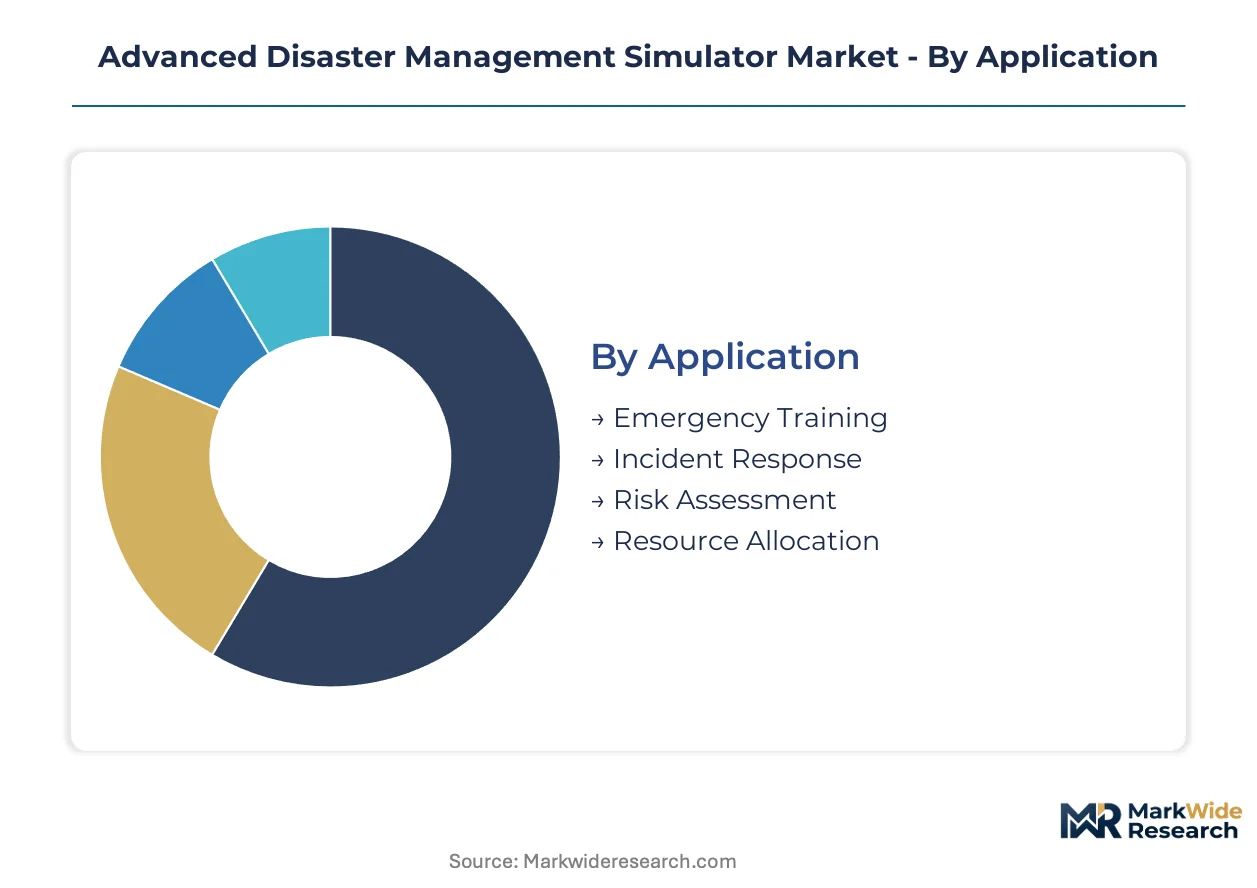
Segmentation in the Advanced Disaster Management Simulator Market reveals distinct procurement patterns across application types and deployment architectures. Each category carries unique capital requirements and compliance obligations that shape vendor positioning.
Application:
Emergency Training and Incident Response command the heaviest upfront infrastructure investment due to VR rendering requirements and scenario library development.
- Emergency Training:Physics-based hazard modeling at 90 frames per second for VR immersion demands dedicated GPU clusters and motion-capture stages. Fire departments in Germany and municipal agencies across the United States concentrate procurement here, driven by FEMA certification mandates for federally funded programs.
- Incident Response:Real-time multi-agent behavioral algorithms simulate crowd psychology and evacuation dynamics. Government agencies in Japan allocate the deepest budget pools, channeled by METI earthquake-tsunami resilience roadmaps.
- Risk Assessment:Climate-risk scenario engines for CSRD compliance reporting.
- Resource Allocation:Autonomous decision-support modules facing EU AI Act algorithmic transparency requirements.
Most installed capacity flows through Emergency Training. Expansion is steepest in Incident Response.
Technology:
Cloud-Based Solutions and Virtual Reality dominate volume, though capital deployment differs sharply between subscription software and immersive hardware.
- Cloud-Based Solutions:Distributed access architectures reduce municipal capital outlay while enabling continuous content updates. Educational institutions in Australia and US community colleges drive SaaS uptake, replacing multi-year capital planning with annual operating budgets.
- Virtual Reality:Head-mounted displays and haptic feedback systems require dedicated training facilities. Netherlands and New Zealand emergency managers pilot live sensor-fed digital twins for levee-breach rehearsal.
- Augmented Reality:Overlay visualization for field commander tablet deployment.
- Scenario Planning:Static library-based engines for tabletop exercise facilitation.
Cloud-Based Solutions capture the majority of new procurement cycles. Virtual Reality claims the highest per-seat revenue.
End User:
Government Agencies and Educational Institutions represent opposing procurement logics: capital appropriation versus operating expenditure.
- Government Agencies:Federal civil protection bodies in Germany and coastal prefectures in Japan mandate high-fidelity multi-hazard platforms. Tightening FAA emergency response certification timelines for US airport operators accelerate replacement cycles.
- Educational Institutions:Emergency management degree programs seek curriculum-integrated SaaS with continuous scenario refresh. Australian state fire service training academies lead subscription licensing adoption.
- NGOs:Humanitarian logistics simulation for cross-border coordination.
- Corporations:CSRD-mandated climate-risk disclosure tooling for enterprise resilience planning.
Government Agencies anchor current installed base. Educational Institutions are climbing the fastest.
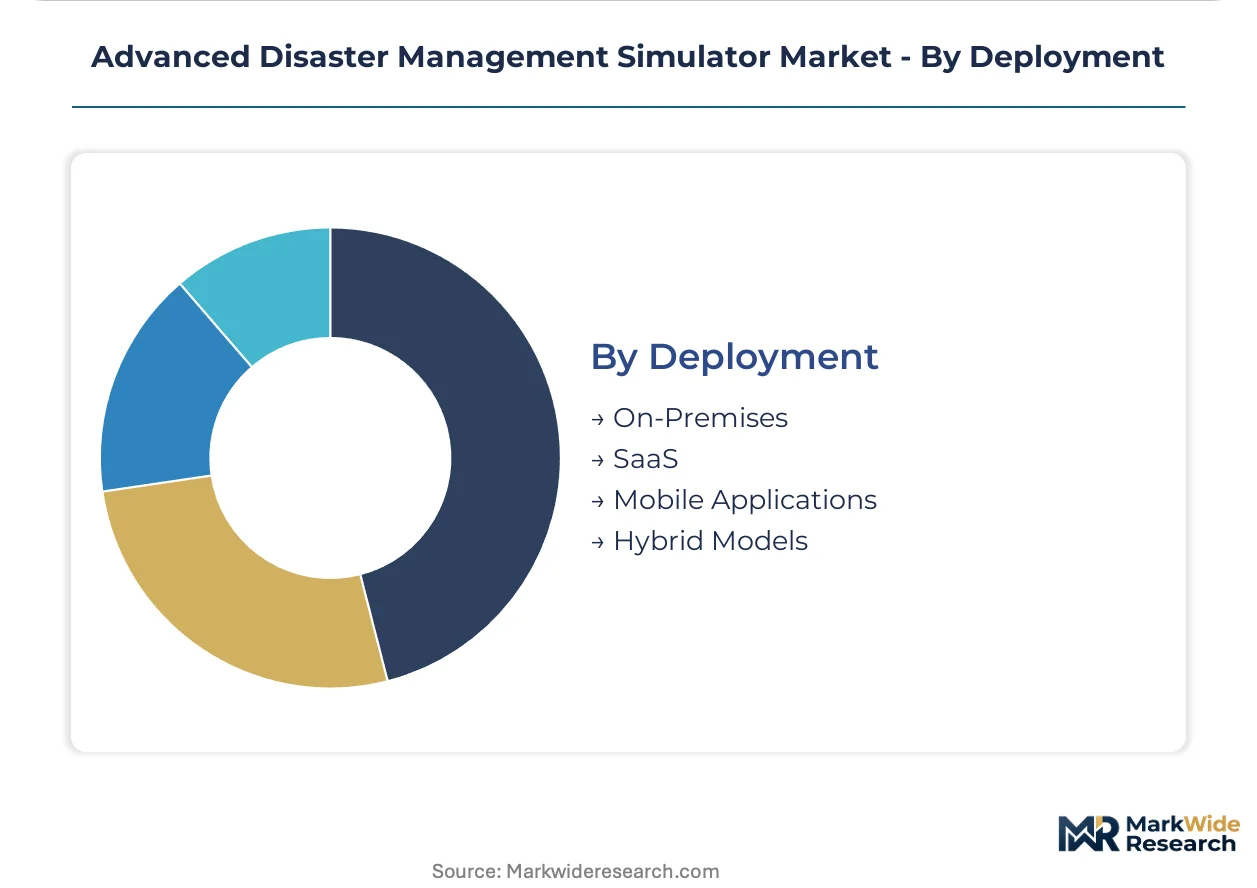
Deployment:
On-Premises deployments impose 40-60% cost premiums over cloud alternatives, concentrating among defense and intelligence end users.
- On-Premises:Air-gapped physical network isolation for classified geospatial vulnerability data. Defense contexts across multiple national security classifications fragment deployment architectures.
- SaaS:Browser-based access eliminating capital appropriation friction for mid-sized municipal departments.
- Mobile Applications:Field commander tablets for augmented reality overlay in live events.
- Hybrid Models:Sensitive scenario libraries on-premises with collaborative tools cloud-hosted.
On-Premises retains dominance where security is non-negotiable. SaaS is expanding most quickly among civilian agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Disaster simulation technology first achieved operational scale in the United States through defense-funded research programs during the 1990s. Federal procurement standards subsequently diffused these platforms to allied governments and municipal agencies worldwide.
United States
FEMA's National Incident Management System certification mandates drive municipal fire department procurement of immersive training systems. The FAA has tightened emergency response certification timelines for airport operators, compressing replacement cycles for legacy platforms. Greater Boston and the Pacific Northwest host concentrated clusters of simulation software developers serving defense and civilian agencies.
Germany
Federal civil protection agencies are modernizing coordination protocols through high-fidelity multi-hazard simulation platforms. The EU AI Act imposes algorithmic transparency requirements on autonomous decision-support modules, forcing documented human-in-the-loop protocols. Bavaria and North Rhine-Westphalia anchor procurement concentration for wildfire and flood scenario engines.
Japan
METI resilience-technology roadmaps channel direct subsidies toward earthquake-tsunami simulation platforms for coastal prefectures. National security classifications fragment cloud deployment architectures for geospatial vulnerability data. The Kanto region around Tokyo concentrates platform integration expertise for public safety communications infrastructure.
Australia
State fire service training academies lead adoption of subscription licensing models for emergency management curriculum integration. Continuous scenario refresh capabilities replace multi-year capital planning with annual operating budgets. New South Wales and Victoria pilot live sensor-fed digital twins for real-time levee-breach rehearsal.
Netherlands
Municipal emergency managers deploy physics-based flood modeling systems ingesting live data from national water management sensor networks. Cross-border data sovereignty requirements complicate collaborative training with neighboring Belgian and German agencies. The Randstad metropolitan cluster concentrates pilot programs for predictive decision-support platforms.
Advanced Disaster Management Simulator Market Competitive Environment
The competitive structure tilts toward diversified technology conglomerates with existing public sector relationships. Mid-sized specialists retain pockets of advantage in high-fidelity scenario engines and vertical application depth. Three archetypes dominate: building-management software heritage companies extending into command-and-control environments, geospatial analytics platforms leveraging satellite data ingestion, and dedicated simulation houses with physics-based hazard modeling expertise. Strategic moves concentrate on interoperability certifications for national procurement standards and SaaS transitions to capture educational institution budgets.
Among building-management heritage players, Schneider Electric anchors integrated environment offerings. ETC Simulation occupies a specialist position exemplifying high-fidelity wildfire and flood scenario development. NEC Corporation represents the public safety communications infrastructure extension archetype across East Asian markets.
| Leading Market Players |
|---|
| Schneider Electric |
| 3D Systems Corporation |
| ETC Simulation |
| Esri |
| Simtable |
| ForgeFX Simulations |
| IBM Corporation |
| The AnyLogic Company |
| NEC Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive GPU cluster deployment in United States and German training facilities anchors both supply security and pricing power for high-fidelity VR rendering systems, insulating premium-tier vendors from cloud cost volatility while forcing mid-market competitors into subscription dependency. This integration choice separates defense-grade on-premises deployments from municipal SaaS procurement, with the former commanding substantial cost premiums and the latter facing compressed margins through annual operating budget constraints.
Pricing Analysis
Bundled hardware-software packages dominate defense and intelligence agency procurement, while unbundled SaaS tiers capture educational and mid-sized municipal buyers. Three-tier pricing structure across premium, standard, and economy levels separates air-gapped on-premises systems from cloud-based collaborative platforms and basic scenario libraries. Cost compression in the standard tier is intensifying because GPU supply concentration limits vendor negotiation leverage with NVIDIA and AMD. Educational institutions exhibit the highest price sensitivity due to annual operating budget ceilings, whereas defense agencies prioritize security compliance over unit economics.
Supply Chain Analysis
Specialized multi-agent behavioral modeling talent shortages in United States, German, and Japanese development centers constrain scenario engine production capacity and extend delivery timelines for custom hazard simulations. GPU semiconductor fabrication draws from Taiwan and South Korea foundries, physics-based rendering software rests on California and Bavaria engineering clusters, and haptic hardware assembly sources from Chinese component suppliers. Single-source vulnerability in NVIDIA chip architecture creates exposure to export control disruptions. Distribution runs through direct public sector procurement channels with extended certification cycles rather than commercial reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory certification mandates across FEMA, EU AI Act, and METI frameworks institutionalize recurring replacement cycles rather than discretionary upgrade decisions.
For Market Incumbents: Anchor defensive positioning through interoperability certification investments for divergent national standards, preventing scenario library portability that would commoditize content assets. Deepen vertical integration into GPU cluster provisioning to offset semiconductor supply concentration risk. The threat of SaaS-native entrants with continuous deployment capabilities demands accelerated cloud transition timelines for legacy on-premises architectures. For New Entrants and Emerging Players: Mid-sized municipal fire departments in Australia and Netherlands represent an underserved buyer archetype with unmet needs for subscription-based wildfire and flood scenario engines without capital appropriation friction. White-space concentration appears in CSRD-mandated climate-risk disclosure tooling for European corporate resilience planners and humanitarian logistics simulation for cross-border NGO coordination. A curriculum-integrated SaaS go-to-market approach through community college emergency management programs offers lowest customer acquisition cost. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented national certification regimes prevent scenario portability and force redundant content development across jurisdictions. Long-term viability favors vendors with documented human-in-the-loop protocol architectures compliant with EU AI Act high-risk AI system classifications. Acquisition targets should demonstrate physics-based hazard modeling expertise at the intersection of computer science and social science. The signal to watch is METI subsidy expansion or contraction for coastal prefecture deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | Enables scenario library portability across FEMA, EU AI Act, and METI procurement standards. |
| Cloud Platform Migration | Captures educational institution budgets through SaaS delivery replacing capital appropriation cycles. |
| Geospatial-Twin Integration | Combines live satellite data ingestion with physics-based modeling for Netherlands and New Zealand pilots. |
| Human-in-the-Loop Protocol Development | Satisfies EU AI Act high-risk AI system requirements for German federal civil protection agencies. |
| GPU Supply Diversification | Reduces vulnerability to NVIDIA and AMD semiconductor export controls and foundry bottlenecks. |
Study Parameters
Multiple input streams — primary interviews with emergency management trainers, simulation platform engineers, and public sector procurement officers; secondary validation through FEMA certification documentation, EU AI Act regulatory filings, and METI resilience-technology roadmap disclosures; plus customs data on GPU and haptic hardware trade flows — were reconciled through bottom-up scenario library deployment tracking and top-down federal budget appropriation analysis.
Historical deployment trajectories across United States fire departments, German federal civil protection agencies, and Japanese coastal prefectures were cross-referenced against panel input from platform developers and training academy directors throughout the forecast period. Segmentation dimensions modeled include deployment architecture, application type, end-user category, and national regulatory compliance tier. CAGRs were derived from installation base growth rates adjusted for replacement cycle compression under tightening certification timelines, with specific inputs from FAA emergency response mandate acceleration and CSRD climate disclosure mandate expansion.
Underlying measurement precision varies by segment; cloud-based SaaS deployments carry tighter precision than classified on-premises defense installations where disclosure constraints limit visibility. Forecasts reflect assumptions regarding subsidy continuity, semiconductor supply stability, and regulatory enforcement intensity. Material deviation in METI funding allocations, EU AI Act conformity assessment timelines, or NVIDIA export control designations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market