
 Global Embedded FPGA Market | 2026-2036
Global Embedded FPGA Market Size, Share, and Industry Trends Forecast 2026-2036
Global Embedded FPGA Market Intelligence
The shift from discrete FPGAs to licensable embedded FPGA (eFPGA) intellectual property (IP) cores is fragmenting the traditional semiconductor design flow. Achronix Semiconductor Corporation specializes in high-performance eFPGA IP and custom chiplet solutions for data center acceleration. QuickLogic Corporation leverages its ultra-low-power technology for mobile, AI, and IoT endpoints. Meanwhile, Intel Corporation integrates its own FPGA technology within complex processor architectures, creating a distinct competitive dynamic.
Embedded FPGA (eFPGA) is an intellectual property core of programmable logic that is integrated directly onto a System-on-Chip (SoC) or Application-Specific Integrated Circuit (ASIC). This architecture provides post-silicon reconfigurability, allowing hardware-level updates to address bugs or adapt to changing protocols without a full chip redesign. SRAM-based technology dominates due to its compatibility with standard CMOS logic processes. High-density eFPGA configurations are gaining traction in applications like aerospace & defense and data centers, where complex, adaptable algorithms are essential.
Compliance with standards like the US International Traffic in Arms Regulations (ITAR) is critical for eFPGAs used in military and aerospace applications. In consumer and industrial sectors, adherence to CE marking requirements in Europe and MIIT specifications for telecommunications equipment in China governs market access. Vendor selection increasingly depends on the quality of the IP integration toolchain and the proven reliability of the logic fabric in advanced process nodes.
Market Dynamics
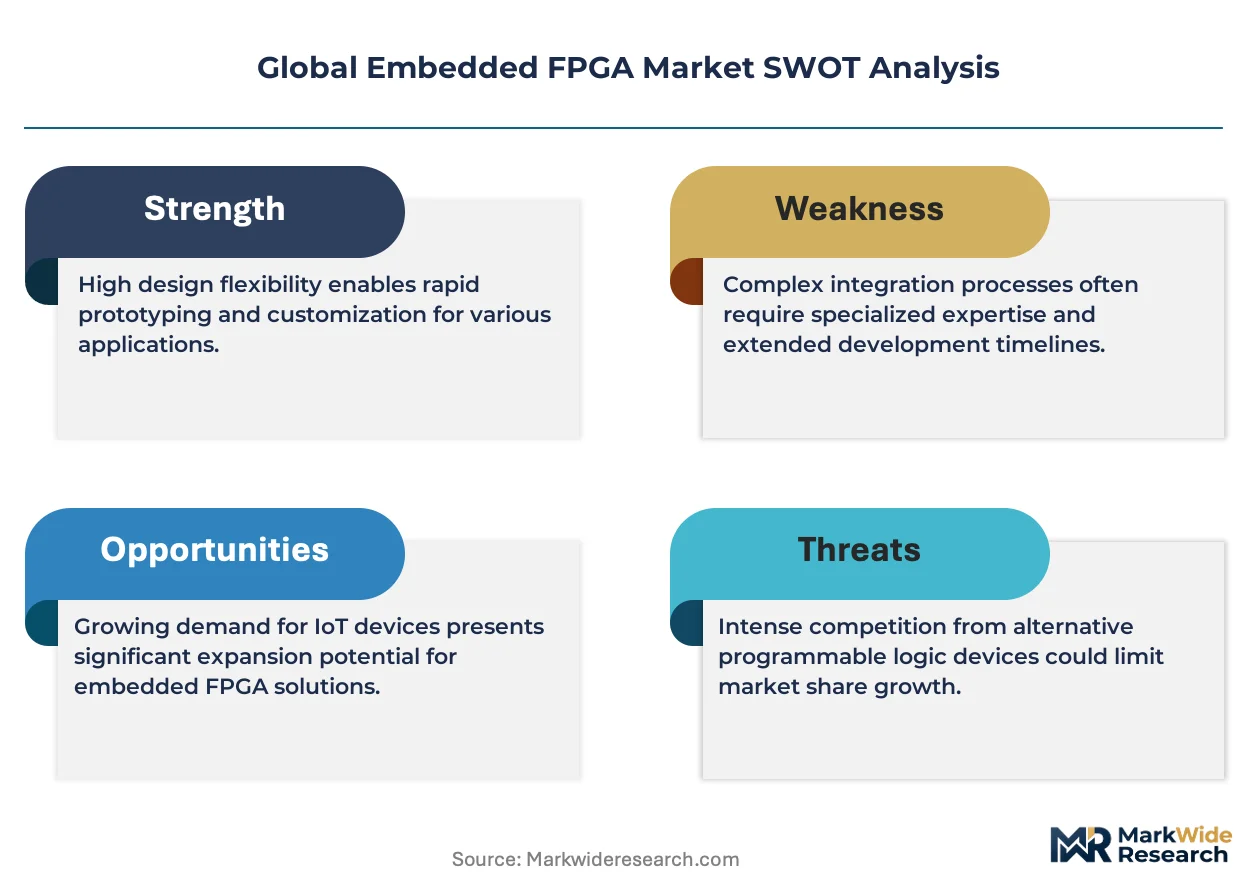
The central force shaping the embedded FPGA market is the architectural shift toward licensable IP cores. This move enables post-silicon adaptability, allowing hardware functions to be modified after chip manufacturing to extend product lifecycles and address evolving standards.
Growth Catalysts
- AI Acceleration:The proliferation of artificial intelligence workloads in data centers and at the edge drives demand for reconfigurable hardware.
- Chinese 5G Infrastructure:National initiatives in China, governed by MIIT specifications, mandate rapid deployment of adaptable 5G base stations.
- Automotive Electronics:The increasing complexity of ADAS requires hardware that can be updated in the field for new algorithms.
Market Restraints
- High IP Licensing Cost:The significant upfront cost for high-performance eFPGA IP cores is a barrier for smaller design teams and startups.
- Performance Trade-offs:Compared to fixed-function ASICs, eFPGAs can have lower logic density and higher power consumption, limiting use in certain applications.
- Design Complexity:Integrating eFPGA IP into an SoC requires specialized expertise in both hardware and software, increasing development time and risk.
Strategic Opportunities
- Industrial IoT:Expanding use of eFPGAs in industrial automation for smart factories provides a significant growth avenue, particularly in Europe.
- Medical Imaging:Adaptable image processing pipelines in advanced medical devices like MRI scanners create an opportunity for specialized eFPGA IP.
- Open-Source Toolchains:The development of open-source tools could lower the barrier to entry and expand the user base.
Industry Challenges
- Talent Scarcity:A shortage of engineers with the dual expertise in SoC architecture and FPGA design constrains project execution.
- IP Verification:Ensuring the reliability of third-party eFPGA IP across different semiconductor process nodes is a significant technical hurdle.
- Standardization Gaps:The lack of universal standards for eFPGA integration and toolchain interoperability complicates design flows for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embedded FPGA Market |
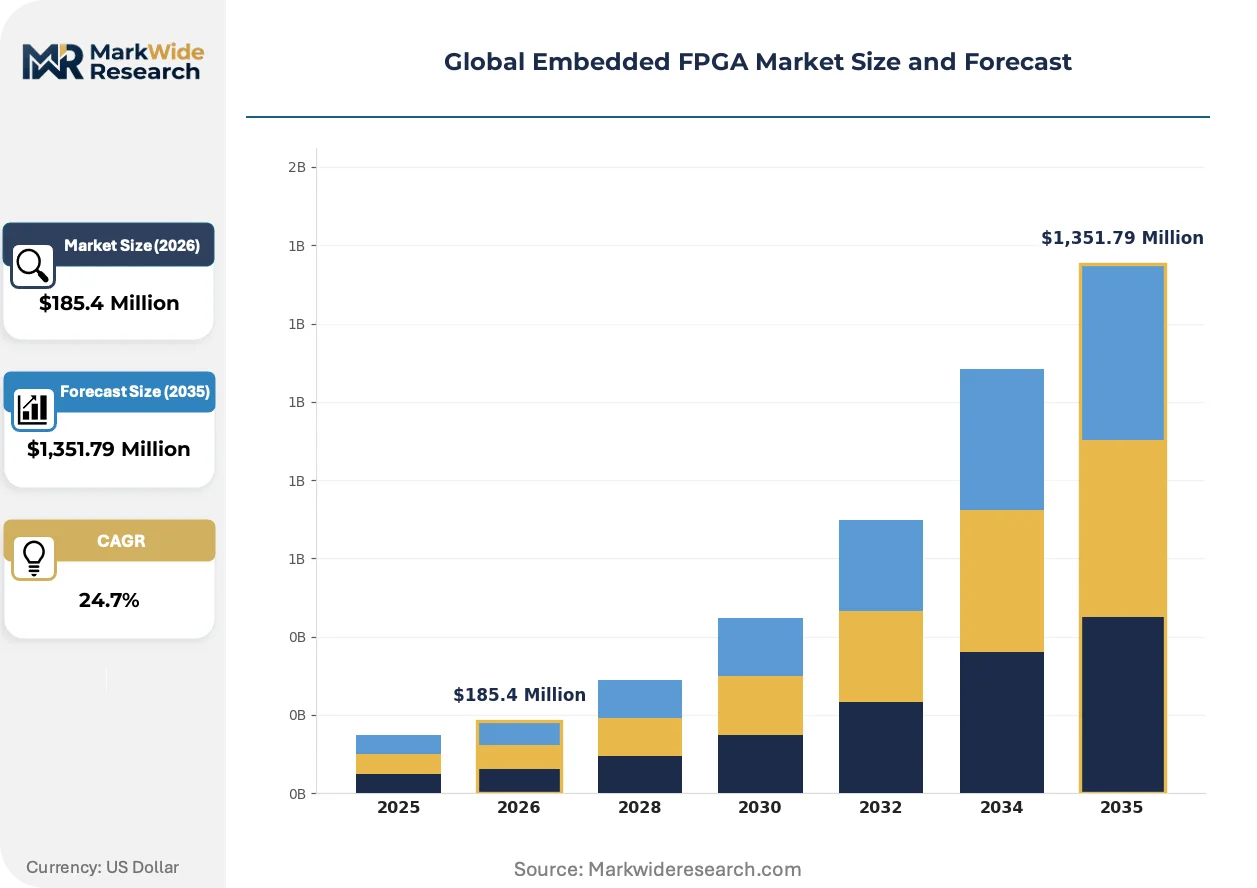
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,351.79 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density, Medium Density, High Density, Ultra High Density, Reconfigurable Logic Technology: Flash-Based, Antifuse, SRAM-Based, EEPROM, Magnetic RAM Application: Consumer Electronics, Telecommunications, Aerospace & Defense, Data Centers, Robotics End User: Semiconductor Manufacturers, System Integrators, Original Equipment Manufacturers, Electronic Design Automation Firms |
| Companies Covered | Microchip Technology Inc., Efinix, Inc., Advanced Micro Devices, Inc., Infineon Technologies AG, Intel Corporation, Altera Corporation, Achronix Semiconductor Corporation, QuickLogic Corporation, Lattice Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embedded FPGA Market Strategic Shifts & Innovations
The market's evolution is defined by hardware assuming software-like flexibility. This transformation allows semiconductor designs to adapt post-deployment, altering the economics of chip development and maintenance for complex systems.
Embedded FPGA IP cores are licensable blocks of programmable logic integrated directly within an SoC. Chip designers in telecommunications and data center sectors are rapidly adopting this technology. This integration is virtualizing a portion of the silicon, enabling hardware patches and feature upgrades through software-style updates after the chip has been manufactured and deployed.
Compliance with the US International Traffic in Arms Regulations (ITAR) is a critical factor for market access in the defense sector. The regulation places strict controls on the design and export of high-performance electronics. Consequently, vendors serving aerospace and defense clients must provide ITAR-compliant IP and maintain secure, auditable design and fabrication processes.
A fundamental shift is occurring as system designers move from buying discrete FPGA components to licensing eFPGA IP for custom silicon. This change bypasses traditional electronics distributors, favoring direct engagement between IP providers and SoC teams. The trend is most visible in high-volume data center and automotive applications where deep customization is paramount.
Global Embedded FPGA Market Segmentation
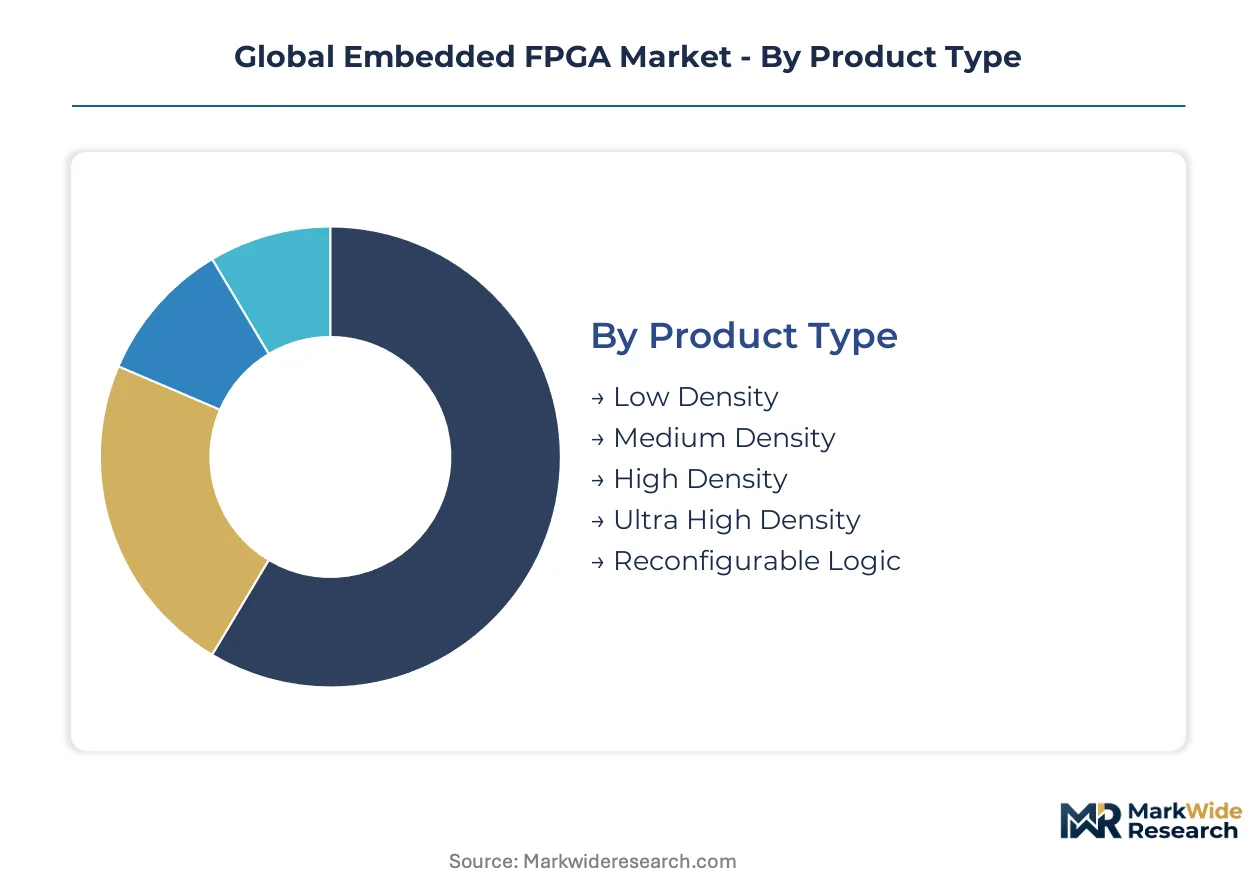
Understanding the embedded FPGA market through segmentation reveals distinct demand drivers and technological preferences across various industry verticals. This granular analysis highlights where specific eFPGA features and integration capabilities are most valued by chip designers and system integrators.
Product Type:
The intensity of after-sales service and ongoing support often correlates directly with the complexity and density of the eFPGA product type, influencing vendor selection criteria.
- High Density:These configurations incorporate complex logic blocks and a large number of look-up tables (LUTs). Demand concentrates in data centers and aerospace & defense for complex, adaptable algorithms.
- Ultra High Density:This segment offers extreme logic capacity and advanced routing capabilities for demanding applications. Demand is rising in AI infrastructure and advanced telecommunications for high-performance, real-time processing.
- Low Density:Provides basic programmable logic for simple control functions in IoT endpoints.
- Medium Density:Offers balanced logic resources for industrial control systems and consumer devices.
- Reconfigurable Logic:Emphasizes dynamic reprogramming for evolving protocols and hardware patches.
High Density holds the largest share; momentum sits with Ultra High Density.
Technology:
Cost tiering for eFPGA technology often reflects the underlying manufacturing complexity and power efficiency, impacting total cost of ownership.
- SRAM-Based:This technology utilizes standard CMOS logic processes for reconfigurability. Demand concentrates in data centers and telecommunications for rapid, in-field reprogramming.
- Flash-Based:Offers non-volatile configuration, retaining programming without power consumption. Demand is rising in automotive electronics for secure, persistent configurations.
- Antifuse:Provides one-time programmability for secure, tamper-resistant applications.
- EEPROM:Offers electrical erasability for moderate reprogramming needs in industrial controls.
- Magnetic RAM:Emerges as a non-volatile, high-endurance option for advanced, power-sensitive designs.
SRAM-Based technology dominates the market; Magnetic RAM is expanding most quickly.
Application:
The diverse application landscape for embedded FPGAs dictates specific performance, power, and reliability requirements for integrated IP.
- Data Centers:Accelerate workloads like AI inference and network processing within server architectures. Demand for eFPGAs provides crucial hardware acceleration for evolving algorithms.
- Telecommunications:Integrates into 5G base stations for flexible protocol adaptation and signal processing. China's national initiatives drive significant deployment in this sector.
- Consumer Electronics:Enables flexible feature sets and post-silicon updates in smart devices and wearables.
- Aerospace & Defense:Requires high-reliability, reconfigurable logic for mission-critical systems and secure communications.
- Robotics:Supports adaptable control and sensor fusion for evolving automation tasks and real-time processing.
Data Centers command a significant share; Telecommunications is gaining share fastest.
End User:
Different end-user types approach eFPGA integration with distinct procurement strategies and internal design capabilities.
- Semiconductor Manufacturers:Integrate eFPGA IP directly into their System-on-Chip designs. They seek robust IP and comprehensive toolchains for custom silicon development.
- System Integrators:Incorporate eFPGA-enabled SoCs into larger, complex systems for specific industry solutions. Their focus is on ease of integration and software-level reconfigurability.
- Original Equipment Manufacturers:Leverage eFPGA-enabled chips for product differentiation and field updates in their final products.
- Electronic Design Automation Firms:Provide essential design tools and verification flows that support eFPGA integration into SoCs.
Semiconductor Manufacturers form the primary customer base; System Integrators exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The embedded FPGA market sees significant IP flow from established semiconductor hubs to high-demand manufacturing centers. This dynamic trade pattern influences regional growth trajectories and local innovation. Key markets demonstrate diverse demand drivers and regulatory landscapes.
China
Demand for eFPGAs in China is propelled by ambitious national initiatives in AI infrastructure and 5G deployment. The Ministry of Industry and Information Technology (MIIT) specifications govern telecommunications equipment, mandating adaptable hardware. Shenzhen and Shanghai serve as major technology hubs, concentrating design and manufacturing for these advanced systems.
United States
Data centers and aerospace & defense applications drive substantial eFPGA demand across the United States. Compliance with US International Traffic in Arms Regulations (ITAR) is critical for military-grade reconfigurable logic. Silicon Valley and Austin house significant eFPGA IP development, supporting innovation in high-performance computing.
Germany
Automotive electronics and industrial IoT applications fuel eFPGA adoption in Germany. CE marking requirements ensure product safety and quality for devices integrated into European industrial systems. Munich and Stuttgart feature strong automotive and industrial automation clusters, leveraging eFPGA for adaptable control units.
Japan
Advanced telecommunications and robotics applications contribute to eFPGA market expansion in Japan. The Ministry of Economy, Trade and Industry (METI) supports semiconductor innovation through various industrial policies. Tokyo and Osaka are key centers for advanced electronics manufacturing, integrating eFPGA into next-generation devices.
South Korea
Consumer electronics and 5G infrastructure development create robust demand for eFPGAs in South Korea. The country's national telecom regulator oversees standards for advanced communication equipment. Seoul and Gyeonggi Province form a critical hub for semiconductor design and fabrication, focusing on high-density eFPGA integration.
Global Embedded FPGA Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established semiconductor giants alongside specialized IP providers. This market exhibits consolidation among core technology developers and fragmentation among niche solution providers. Strategic archetypes include integrated device manufacturers, pure-play IP vendors, and custom chiplet specialists. Dominant competitive moves involve technology licensing agreements and strategic partnerships to broaden market reach.
Specialists in high-performance eFPGA IP and custom chiplet solutions, such as Achronix Semiconductor Corporation, exemplify the innovation-driven segment, focusing on demanding data center acceleration. QuickLogic Corporation occupies a position among providers leveraging ultra-low-power technology, targeting mobile, AI, and IoT endpoints. Meanwhile, Intel Corporation, a major integrated device manufacturer, anchors the market with its internal FPGA technology integration. This represents a vertically integrated approach to processor architectures, distinct from companies like Efinix, Inc., which offer reconfigurable logic for diverse applications. These players collectively shape the competitive dynamics through their unique technological strengths and market focus.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Efinix, Inc. |
| Advanced Micro Devices, Inc. |
| Infineon Technologies AG |
| Intel Corporation |
| Altera Corporation |
| Achronix Semiconductor Corporation |
| QuickLogic Corporation |
| Lattice Semiconductor |
| Others |
Cost & Logistics Intelligence
Shenzhen's robust semiconductor manufacturing capacity directly influences embedded FPGA IP licensing costs and market accessibility. This capacity, coupled with national initiatives, shapes both pricing strategies and the flow of critical components within the ecosystem.
Pricing Analysis
The pricing gap between current-generation and next-generation eFPGA IP cores reflects performance and process node advancements. Licensing and royalty models dominate the market, with differentiation driven by high-density logic capacity and the quality of the IP integration toolchain. Pricing softness stems from increasing competition among IP vendors and the emergence of alternative reconfigurable logic solutions. Smaller design teams and startups exhibit the highest price sensitivity, often seeking lower-density or open-source compatible options, while large semiconductor manufacturers prioritize performance over cost for critical SoC integration.
Supply Chain Analysis
US International Traffic in Arms Regulations (ITAR) significantly restrict the flow of high-performance eFPGA IP for defense applications, creating segmented supply chains. Geographic supply concentration centers on the United States, South Korea, and Taiwan for advanced process node fabrication. The supply chain sources from specialized design tools and high-purity silicon wafers. Regulatory restrictions, such as MIIT specifications in China, represent a structural risk for market access. Distribution operates through direct engagement channels between IP providers and SoC design teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded FPGA market presents a fragmentation opportunity as AI acceleration drives specialized hardware demands across diverse applications.
For Market Incumbents:
Entrench market share by investing heavily in advanced process node compatibility and developing comprehensive IP integration toolchains. Acquire niche eFPGA IP specialists to broaden technology portfolios and mitigate the threat from lower-cost open-source alternatives. Deepen strategic partnerships with leading EDA vendors to ensure seamless design flows. Focus R&D on ultra-high-density configurations to maintain a performance edge against emerging entrants.
For New Entrants and Emerging Players:
Pursue white-space opportunities in industrial IoT and medical imaging, where adaptable processing pipelines are critical. The low-density eFPGA segment for IoT endpoints represents a penetrable market due to less stringent performance requirements. Develop open-source compatible toolchains and provide extensive community support to lower the barrier to entry for smaller design teams. Offer specialized IP tailored for specific application verticals.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized eFPGA IP providers with proven track records in advanced process nodes. The market offers long-term viability as reconfigurability becomes essential for complex, adaptable systems. Target acquisition profiles include firms with robust IP verification methodologies and strong customer relationships in high-growth sectors like automotive ADAS. Increased adoption of eFPGA in automotive platforms would serve as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop open-source integration tools | Lowers entry barriers for new users and expands the eFPGA ecosystem. |
| Acquire specialized eFPGA IP firms | Broadens technology portfolios and secures expertise in niche applications. |
| Invest in advanced process node compatibility | Ensures IP performance scales with next-generation semiconductor fabrication. |
| Form partnerships with EDA vendors | Streamlines design workflows and improves overall integration efficiency for SoC teams. |
| Expand into industrial IoT applications | Captures new revenue streams from a segment demanding adaptable, low-power solutions. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market reports anchors the qualitative findings. This approach included discussions with SoC architects, IP licensing managers, telecommunications engineers, and defense contractors. Secondary data sources encompassed MIIT specifications, ITAR regulations, company annual reports, and industry consortium publications. The analysis employed bottom-up and top-down triangulation to ensure comprehensive data coverage.
The calibration approach involved developing an analytical framework to project market trends over the projection horizon. Segmentation dimensions modeled included Product Type, Technology, Application, End User, and geographic regulatory environments. Compound annual growth rates were derived from historical trends and projected market shifts. Key industry-specific forecast inputs included semiconductor manufacturing capacity and AI workload growth rates, influencing future demand dynamics.
Sensitivities concentrate around geopolitical trade policies and rapid technological obsolescence, which could impact market trajectories. Forecasts reflect assumptions regarding current market conditions and expected industry developments. Material shifts in global trade agreements or the emergence of disruptive computing paradigms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Bipolar Transistors Market