
 Asia-Pacific Ultra-Low-Power Microcontroller Market | 2026-2036
Asia-Pacific Ultra-Low-Power Microcontroller Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ultra-Low-Power Microcontroller Market Outlook
Project finance tied to sovereign semiconductor funds is tilting competitive dynamics toward capital-heavy entrants across the Asia-Pacific. Renesas Electronics Corporation leverages its fabrication partnerships in Japan to sustain leadership in automotive-grade 32-bit designs. NXP Semiconductors anchors European-origin expertise through expanded R&D centers in Singapore and China. STMicroelectronics competes by controlling a broad portfolio spanning industrial automation to consumer wearables.
Ultra-low-power microcontrollers are integrated circuits engineered to operate below one milliwatt in active states, often incorporating sub-threshold voltage design and multiple sleep modes to extend battery life across multi-year deployments. Their primary purpose is enabling persistent sensing and edge processing in devices where wired power is impractical and battery replacement is costly. Within product type categories, 32-bit microcontrollers capture the dominant margin pool as embedded AI inference migrates to endpoint devices. Among end users, healthcare devices represent the fastest structural expansion as portable diagnostic equipment proliferates across aging populations in Japan, South Korea, and Australia.
Japan's METI enforces stringent standby power regulations that directly disqualify conventional microcontrollers from domestic smart home certification programs. China's MIIT and GB standards mandate progressive efficiency tiers for networked consumer electronics, compressing market access for non-compliant imports. India's BIS compulsory registration order for electronic components is tightening entry pathways for unregistered suppliers. Stakeholders must monitor how divergent national efficiency test protocols reshape component qualification costs and regional sourcing strategies.
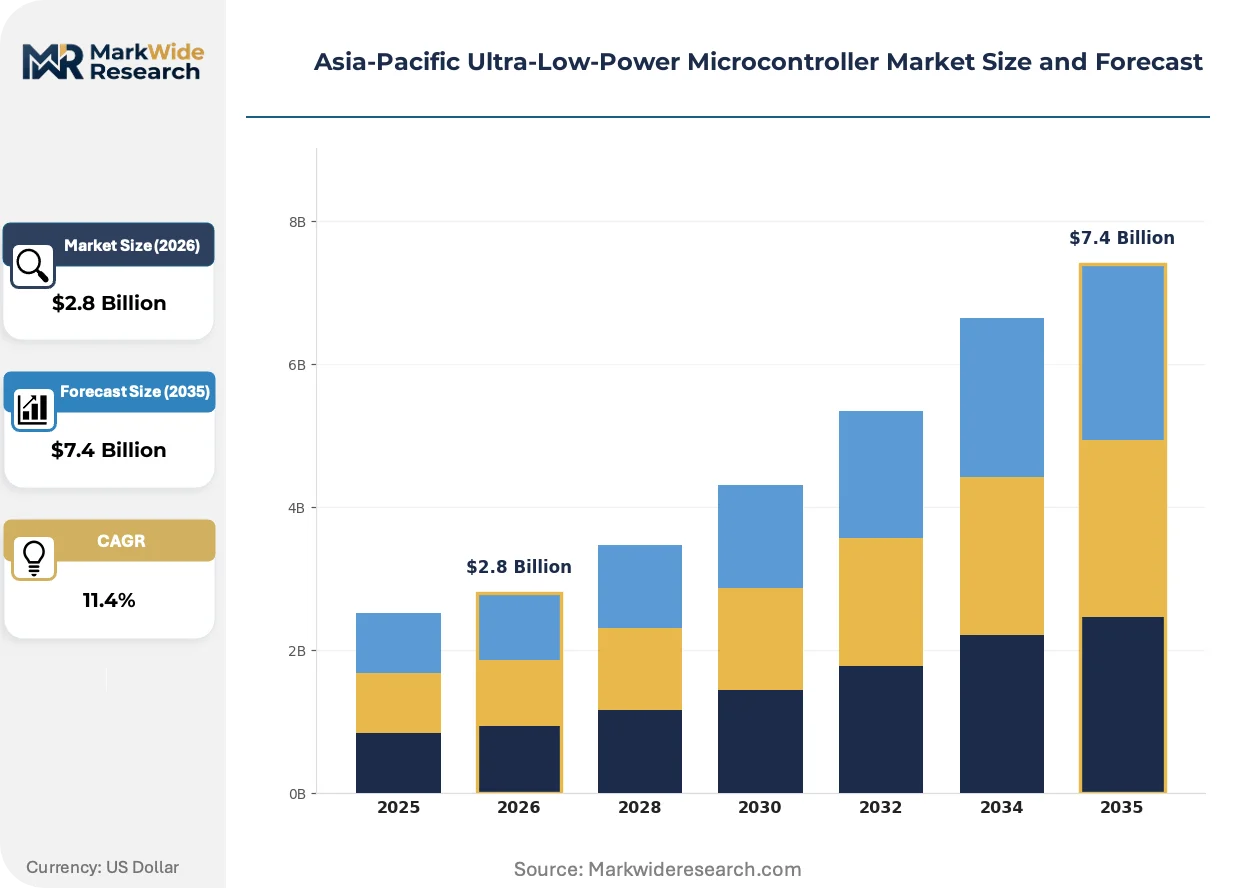
Market Dynamics
China's MIIT efficiency mandates and Japan's METI standby power regulations are forcing a coordinated phase-out of legacy 8-bit and 16-bit architectures across the Asia-Pacific, compressing qualification timelines and reshaping supplier certification priorities.
Growth Catalysts
- MIIT Tiered Efficiency Mandates:China's networked electronics standards accelerate replacement cycles in smart home and industrial sensor deployments.
- Wearable Technology Procurement:Japanese and South Korean manufacturers are expanding orders for Bluetooth Low Energy integrated units in fitness trackers and medical patches.
- Medical Monitoring Equipment:India's portable diagnostic sector drives sustained demand for sub-threshold voltage designs in continuous glucose monitors and pulse oximeters.
Market Restraints
- Advanced Node Wafer Costs:Sub-40nm fabrication for 32-bit ultra-low-power designs concentrates input cost volatility among Taiwan and South Korean foundry customers.
- IP Licensing Complexity:ARM Cortex-M architecture royalties and RISC-V fragmentation create structural margin pressure for mid-tier MCU vendors.
- BIS Registration Barriers:India's compulsory component registration tightens entry pathways for unregistered European and North American suppliers.
Strategic Opportunities
- Smart Agriculture Equipment:India's soil moisture and livestock monitoring sectors remain underpenetrated by purpose-built sub-milliwatt controllers.
- Dual Carbon Policy Tailwinds:China's national decarbonization framework subsidizes battery-free energy harvesting designs in industrial IoT gateways.
- Edge AI Convergence:Neural network accelerators are hybridizing with conventional MCU cores in Japanese factory automation and Australian mining sensors.
Industry Challenges
- Sub-Threshold Design Talent Scarcity:Mixed-signal architects capable of optimizing near-threshold voltage operation remain concentrated in Tokyo, Seoul, and Hsinchu.
- Multi-Jurisdiction Certification Timelines:Divergent METI, MIIT, and BIS test protocols extend product qualification cycles for regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ultra-Low-Power Microcontroller Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 16-bit Microcontrollers, 32-bit Microcontrollers, System on Chip (SoC), Analog Microcontrollers End User: Consumer Electronics, Automotive Applications, Industrial Automation, Healthcare Devices Technology: Bluetooth Low Energy, Zigbee, Wi-Fi, Thread Application: Smart Home Devices, Wearable Technology, Medical Monitoring, Smart Agriculture |
| Companies Covered | Renesas Electronics Corporation, NXP Semiconductors, STMicroelectronics, Infineon Technologies AG, Microchip Technology, Texas Instruments, Analog Devices, Silicon Labs, Nordic Semiconductor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ultra-Low-Power Microcontroller Market Strategic Shifts
Endpoint intelligence requirements are compressing the traditional boundary between microcontrollers and application processors across medical, industrial, and consumer segments in the Asia-Pacific.
Sub-threshold voltage design is hybridizing conventional digital logic with analog sensor interfaces to enable decade-long battery life in environmental monitoring nodes. Australian water utilities and Japanese building management contractors are adopting these architectures for distributed sensing networks. The technology is hybridizing procurement criteria, forcing buyers to prioritize sleep-mode current specifications over raw compute throughput.
METI's standby power regulations now disqualify conventional microcontrollers from Japan's smart home certification programs, directly shaping component selection for domestic appliance OEMs. The industrial consequence is accelerated validation of sub-100-nanowatt sleep-state designs in air conditioning and lighting control systems. South Korean white-goods manufacturers are responding by pre-qualifying only METI-compliant silicon for their 2026-2027 product cycles.
Certification-driven preference shifts are displacing price-first procurement in healthcare and industrial segments across the Asia-Pacific. Australian and Japanese hospital procurement committees now mandate TGA and PMDA pre-certification for portable diagnostic MCU platforms, filtering out uncertified suppliers regardless of unit cost. This behavior is most visible in continuous patient monitoring equipment where regulatory liability exposure concentrates buying authority among risk-averse procurement teams.
Asia-Pacific Ultra-Low-Power Microcontroller Market Segmentation
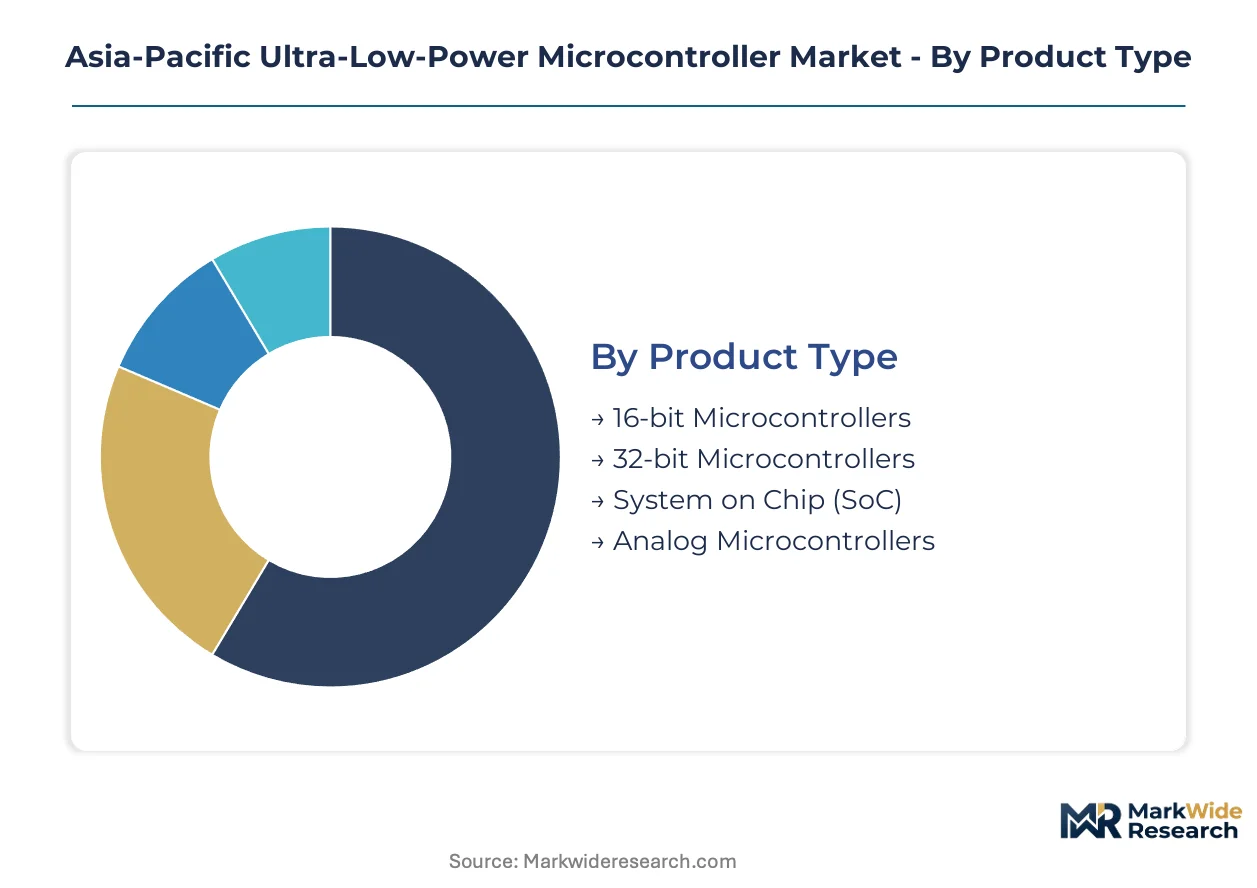
Ultra-low-power microcontroller procurement varies sharply across deployment contexts. Technical support requirements differ between mass-market consumer batches and mission-critical healthcare installations. Understanding these segmentation boundaries clarifies where margin pools concentrate versus where volume scales.
Product Type:
After-sales service intensity escalates with bit-depth and integration complexity. 32-bit designs demand firmware debugging support and toolchain calibration that 8-bit legacy replacements never required. Analog microcontroller deployments in industrial settings need field application engineers for sensor interface tuning.
- 32-bit Microcontrollers:These architectures incorporate ARM Cortex-M or RISC-V cores with DSP extensions and hardware security modules. Japanese automotive Tier-1 suppliers and South Korean wearable OEMs concentrate orders here as embedded AI inference migrates to endpoints. MIIT efficiency mandates accelerate displacement of legacy 8-bit alternatives in networked consumer electronics.
- System on Chip (SoC):Radio-integrated designs combine sub-threshold MCU cores with Bluetooth Low Energy or Zigbee transceivers on single die. South Korean fitness tracker manufacturers and Australian agricultural sensor vendors drive procurement volume. Sub-40nm fabrication constraints concentrate supply risk among Taiwan and South Korean foundry customers.
- 16-bit Microcontrollers:Transitional architectures persist in cost-optimized Indian medical monitoring equipment where sub-threshold voltage designs remain over-specified.
- Analog Microcontrollers:Mixed-signal units with precision ADCs and programmable gain amplifiers serve Japanese building automation and Chinese industrial sensor networks.
32-bit Microcontrollers holds the largest share; momentum sits with System on Chip (SoC).
End User:
Cost tier stratification separates premium-certified healthcare deployments from price-sensitive consumer electronics. Automotive-grade MCUs carry qualification overhead that industrial automation buyers partially absorb. Consumer segments prioritize unit economics over extended warranty terms.
- Healthcare Devices:Portable diagnostic equipment demands sub-100-nanowatt sleep states and TGA/PMDA pre-certification. Australian hospital procurement committees and Japanese home-care device manufacturers filter suppliers aggressively. Aging demographics across Japan, South Korea, and Australia expand addressable market for continuous glucose monitors and pulse oximeters.
- Automotive Applications:Functional safety requirements under ISO 26262 constrain vendor qualification to Renesas and NXP with proven fabrication partnerships. Japanese and South Korean EV powertrain controllers integrate these designs for battery management and thermal monitoring.
- Consumer Electronics:Smart home remote controls and appliance interfaces in China face MIIT standby power tiered mandates.
- Industrial Automation:Factory sensor nodes and predictive maintenance endpoints in Japanese automotive plants and Australian mining operations drive demand.
Healthcare Devices commands premium pricing; Consumer Electronics scales fastest by unit volume.
Technology:
Application context determines connectivity protocol selection. Medical patches prioritize Bluetooth Low Energy for smartphone pairing. Agricultural networks favor mesh topologies across extended ranges. Smart home ecosystems fragment across competing standards.
- Bluetooth Low Energy:2.4 GHz protocol optimized for intermittent burst transmission with sub-milliamp average current. Japanese and South Korean wearable manufacturers expand orders for fitness trackers and medical patches. Apple's ecosystem dominance in Australia and Japan reinforces protocol preference among accessory vendors.
- Zigbee:Mesh networking standard with 20-250 kbps data rates penetrating Chinese smart home and Indian agricultural monitoring deployments. Thread interoperability promises future convergence.
- Wi-Fi:Higher throughput protocol reserved for video-enabled security cameras and gateway devices in Australian and Japanese smart home installations.
- Thread:IPv6-native mesh architecture gaining traction in Matter-compatible smart home ecosystems across South Korean and Australian markets.
Bluetooth Low Energy dominates current shipments; Thread exhibits steepest expansion trajectory.
Application:
Geography shapes deployment velocity. India's agricultural sector lags in penetration. China's dual carbon policy accelerates industrial IoT adoption. Japan's regulatory environment forces rapid smart home refresh cycles.
- Smart Home Devices:Air conditioning controllers and lighting systems in Japan face METI standby power regulations that disqualify conventional MCUs. South Korean white-goods manufacturers pre-qualify only METI-compliant silicon for 2026-2027 product cycles. China's MIIT mandates create parallel certification pressure.
- Medical Monitoring:Continuous patient monitoring equipment concentrates buying authority among risk-averse Australian and Japanese hospital procurement committees. TGA and PMDA pre-certification filters out uncertified suppliers regardless of unit cost.
- Wearable Technology:Fitness bands and smartwatches in South Korea and Japan drive Bluetooth Low Energy integrated unit procurement.
- Smart Agriculture:Soil moisture and livestock monitoring in India remains underpenetrated by purpose-built sub-milliwatt controllers.
Smart Home Devices leads by revenue concentration; Smart Agriculture offers largest untapped expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium pricing for automotive-grade 32-bit designs while India concentrates volume demand in cost-optimized medical monitoring equipment. This asymmetry shapes supplier qualification strategies across the Asia-Pacific.
China
Industrial IoT gateway deployments and smart home appliance refreshes drive procurement of sub-threshold voltage designs. MIIT tiered efficiency mandates compress qualification timelines for networked consumer electronics. Shenzhen and Shanghai fabrication clusters concentrate sub-40nm wafer supply for Bluetooth Low Energy integrated units.
Japan
Aging demographics expand demand for continuous glucose monitors and home-care diagnostic devices. METI standby power regulations disqualify conventional microcontrollers from domestic smart home certification programs. Tokyo and Nagoya automotive Tier-1 suppliers anchor orders for functional safety-compliant 32-bit architectures.
South Korea
Fitness tracker manufacturers and white-goods OEMs expand orders for radio-integrated SoC designs. MFDS medical device regulations align with Japanese PMDA standards for portable diagnostic equipment. Seoul and Busan electronics clusters pre-qualify METI-compliant silicon for 2026-2027 appliance product cycles.
India
Portable diagnostic equipment and smart agriculture sensors drive demand for sub-milliwatt controllers. BIS compulsory registration tightens entry pathways for unregistered European and North American suppliers. Bengaluru and Hyderabad medical device startups scale domestic production of pulse oximeters and soil moisture monitors.
Australia
Water utility distributed sensing networks and mining predictive maintenance endpoints adopt decade-long battery life architectures. TGA pre-certification filters out uncertified MCU suppliers from hospital procurement committees. Perth and Brisbane industrial automation contractors integrate sub-100-nanowatt sleep-state designs.
Asia-Pacific Ultra-Low-Power Microcontroller Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with fabrication partnerships and architecture licensing. The Asia-Pacific market structures around three tiers: Japanese automotive-grade incumbents with captive foundry relationships, European-origin semiconductor houses with Singapore and China R&D expansion, and radio-specialist vendors concentrated in Nordic and US origins. Consolidation pressure concentrates among mid-tier vendors facing ARM royalty burdens and RISC-V fragmentation. Dominant competitive moves include strategic partnerships with Taiwan and South Korean foundries and portfolio diversification into edge AI accelerator hybrids.
Among Japanese-origin integrated device manufacturers, Renesas Electronics Corporation anchors the automotive-grade tier through fabrication partnerships sustaining 32-bit leadership. European-origin semiconductor houses NXP Semiconductors and STMicroelectronics exemplify the R&D expansion archetype, with the former anchoring European expertise through Singapore and China centers and the latter controlling broad industrial-to-consumer portfolios. These three occupy positions that reflect divergent strategic responses to MIIT and METI regulatory compression.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies AG |
| Microchip Technology |
| Texas Instruments |
| Analog Devices |
| Silicon Labs |
| Nordic Semiconductor |
| Others |
Value Chain & Pricing Dynamics
Taiwan and South Korean foundry concentration for sub-40nm wafers feeds directly into margin pool capture by automotive-grade 32-bit vendors with captive allocation agreements. Pricing power downstream reflects this upstream chokepoint, with METI-compliant designs commanding sustained premiums over commodity alternatives.
Pricing Analysis
Configured-to-order pricing for ARM Cortex-M based 32-bit designs spreads 40-60% above standard 8-bit replacement catalog pricing. Price differentiation rests on certification tier (METI standby power compliance vs baseline efficiency) and after-sales firmware support bundling. Cost compression in consumer-grade Bluetooth Low Energy integrated units is intensifying as RISC-V fragmentation erodes ARM royalty-based margin structures. Indian medical monitoring OEMs exhibit highest price sensitivity, while Japanese automotive Tier-1 suppliers absorb premium pricing for functional safety qualification.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment to Chinese fabrication facilities are reshaping regional wafer allocation priorities. Supply concentrates in Taiwan, South Korea, and Japan for sub-40nm ultra-low-power process nodes. Raw material dependencies span silicon wafers, specialty photoresists, and rare-earth elements for precision analog components. Single-source vulnerability concentrates around Taiwan's leading-edge foundry capacity. Distribution runs through authorized distributors serving EMS providers in Shenzhen, Seoul, and Nagoya electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ultra-low-power microcontroller market rewards mixed-signal architects capable of near-threshold voltage optimization, a skill set concentrated in Tokyo, Seoul, and Hsinchu. Firms without access to this talent pool or foundry partnerships face structural disadvantage regardless of capital availability.
For Market Incumbents: Entrench fabrication partnerships with Taiwan and South Korean foundries through long-term capacity reservation agreements. Accelerate edge AI accelerator hybrid development to defend against RISC-V based entrants attacking the mid-tier 32-bit segment. Prioritize METI and MIIT pre-certification investment to maintain qualification moats against European and North American competitors facing BIS registration barriers in India. For New Entrants and Emerging Players: India's smart agriculture equipment sector represents the most penetrable entry point, with soil moisture and livestock monitoring deployments still sourcing repurposed consumer-grade controllers. Target Bengaluru and Hyderabad medical device startups scaling domestic pulse oximeter production as anchor customers for sub-threshold voltage designs. Lead with field application engineering support rather than unit cost to differentiate against established catalog vendors. For Investors and Strategic Acquirers: Capital is best deployed toward radio-specialist vendors with proven Bluetooth Low Energy integration and existing METI compliance validation. Long-term viability hinges on foundry relationship depth rather than IP portfolio breadth alone. Watch for inflection in China's dual carbon subsidy disbursement rates to energy harvesting design vendors as signal of policy-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | Secures sub-40nm wafer allocation for automotive-grade 32-bit designs at Renesas and NXP. |
| Edge AI Accelerator Integration | Hybridizes neural network cores with MCU architectures for Japanese factory automation endpoints. |
| Regulatory Pre-Certification Investment | Accelerates METI and MIIT compliance timelines to capture South Korean white-goods refresh cycles. |
| Energy Harvesting Design Development | Aligns with China's dual carbon subsidies for battery-free industrial IoT gateway deployments. |
| Field Application Engineering Scale-Up | Supports Indian medical device startups with sensor interface tuning for continuous glucose monitors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT efficiency mandate documentation, METI standby power regulation filings, and foundry capacity disclosure statements. Primary interviews engaged MCU product managers at Japanese automotive Tier-1 suppliers, procurement leads at South Korean wearable OEMs, and biomedical engineers at Australian hospital systems. Secondary validation drew from BIS compulsory registration orders, TGA medical device listings, and SEC filings of publicly traded semiconductor houses. Bottom-up demand modeling triangulated against top-down wafer allocation estimates from Taiwan and South Korean fabrication clusters.
Forecast inputs span bit-depth migration rates, regulatory compliance timeline compression, and foundry yield assumptions across the projection horizon. Segmentation dimensions modeled include product type (32-bit, SoC, 16-bit, analog), end user (healthcare, automotive, consumer, industrial), and connectivity protocol (Bluetooth Low Energy, Zigbee, Wi-Fi, Thread). CAGRs were derived from regression analysis of historical pricing elasticity and forward-looking regulatory mandate implementation schedules. Edge AI inference migration rates and energy harvesting subsidy disbursement trajectories served as scenario-weighting variables.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or China-Taiwan trade flows would shift the trajectory. Forecasts reflect documented assumptions regarding foundry capacity expansion timelines and regulatory enforcement consistency. Material shifts in export control regimes or dual carbon policy implementation intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Gallium Oxide Transistor Market