
 3D TSV Device Market | 2026-2036
3D TSV Device Market Size, Share, and Industry Trends Forecast 2026-2036
3D TSV Device Market Analysis
Modular system-in-package configurations is recalibrating how OEMs evaluate die-to-die interconnect economics. Taiwan Semiconductor Manufacturing Company leverages captive CoWoS capacity to anchor high-bandwidth memory attach rates. Samsung Electronics sustains vertical control over both DRAM wafer output and TSV etch equipment. Intel Corporation differentiates through Foveros-style active interposers that merge logic and memory tiles.
3D TSV devices are semiconductor assemblies that use vertical copper-filled vias drilled through silicon wafers to create electrical pathways between stacked die layers, typically achieving interconnect pitches below 40 micrometers. These structures enable memory bandwidth densities exceeding 1 terabyte per second for artificial inference accelerators and network processors. Memory Devices applications dominate current wafer starts because HBM3E stacks require eight or more TSV-connected DRAM layers. Data Centers represents the fastest-growing application segment as hyperscalers expand training cluster footprints. Wafer-Level Packaging captures the largest margin pool due to yield-critical bond alignment and underfill processes that command premium pricing.
REACH and RoHS frameworks in Europe restrict lead-based solders and certain etchant chemistries used in TSV metallization, compelling foundries to qualify alternative barrier-seed layers. The US EPA and OSHA jointly influence fab chemical handling protocols and cleanroom emissions thresholds that shape domestic packaging capacity economics. China's MIIT enforces GB standards on semiconductor manufacturing energy intensity, affecting TSV process tool selection. Stakeholders must monitor how divergent regional substance restrictions and carbon-accounting rules reshape qualification timelines for next-generation memory-logic stacks.

Market Dynamics
Heterogeneous integration roadmaps are compressing die-to-wafer bond pitch tolerances below 10 micrometers, forcing packaging houses to retool for hybrid bonding while maintaining copper TSV throughput for HBM3E memory stacks.
Growth Catalysts
- Memory bandwidth density thresholds:AI training accelerators now require terabyte-per-second interconnects that only TSV-stacked DRAM can deliver, pulling wafer starts toward 12-high HBM configurations.
- China's MIIT dual carbon mandates:GB standards on semiconductor manufacturing energy intensity are accelerating qualification of low-temperature TSV metallization processes that reduce thermal budget.
- Hsinchu cluster foundry-packaging integration:Captive CoWoS capacity at TSMC anchors high-bandwidth memory attach rates for NVIDIA and AMD silicon, creating localized demand gravity.
Market Restraints
- Copper seed layer cost volatility:Palladium and ruthenium barrier metals face supply concentration from Russian and South African refiners, squeezing TSV metallization margins.
- Wafer-thinning yield loss:Backside grinding to 30-micrometer thickness induces edge chipping and die warpage, limiting stack height for memory-logic configurations.
- REACH substance restrictions:ECHA scrutiny of hexavalent chromium etchants and lead-based solders forces dual qualification tracks for European-bound versus Asian-bound production.
Strategic Opportunities
- Automotive sensor fusion modules:LIDAR and 4D imaging radar processors are adopting TSV-based SiP for thermal management and form-factor reduction in Germany and Japan.
- India's PLI scheme for semiconductor packaging:Subsidies for display and memory module assembly are drawing OSAT investment toward Gujarat and Tamil Nadu greenfield sites.
- Hybrid bonding-copper TSV convergence:Die-to-wafer oxide fusion bonding at sub-5-micrometer pitch enables logic-on-logic stacking for smartphone application processors.
Industry Challenges
- Thin-wafer handling automation:30-micrometer silicon substrates require electrostatic chuck redesigns and edge-support ring systems that extend equipment commissioning cycles.
- Cross-fab metrology standardization:Bond alignment tolerance disputes between memory foundries and logic packaging houses delay HBM3E stack qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D TSV Device Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer-Level Packaging, Chip-on-Wafer, System-in-Package, Multi-Chip Module End User: Consumer Electronics, Telecommunications, Automotive, Industrial Equipment Technology: IC Packaging, Chip Stacking, Through-Silicon Vias, Advanced Interconnects Application: Memory Devices, Data Centers, High-Performance Computing, Mobile Devices |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, Samsung Electronics, Intel Corporation, Amkor Technology, SK hynix, United Microelectronics Corporation, ASE Technology Holding, Toshiba Electronic Devices and Storage Corporation, Advanced Micro Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D TSV Device Market Emerging Trajectories
Process automation and materials substitution are converging to redefine yield economics for high-aspect-ratio TSV formation, with regulatory chemistry restrictions and AI-driven demand patterns accelerating tool refresh cycles across memory and logic packaging lines.
Laser-assisted TSV reveal is automating the transition from mechanical grinding to selective ablation for backside via exposure, reducing copper smear and delamination risk. Memory foundries in Taiwan and Korea are adopting this for 12-high HBM stacks. The technology is automating throughput bottlenecks that previously limited stack height to eight layers.
REACH and RoHS amendments are tightening restrictions on perfluorinated compounds used in TSV plasma etching and lead-free solder alternatives for microbump interconnects. European packaging facilities must now qualify fluorine-free etch chemistries and tin-silver-copper alloys that meet both substance restrictions and thermal cycling reliability. Memory module suppliers serving EU automotive OEMs face the steepest requalification burden.
Hyperscalers are consolidating procurement authority for AI accelerator substrates into centralized supply chain teams, displacing traditional OEM-mediated component sourcing. Direct contracts between cloud operators and OSATs for CoWoS capacity are compressing margin capture by intermediate distributors. This pattern is most visible in North American data center buildouts where Microsoft, Amazon, and Google account for dominant HBM attach volumes.
3D TSV Device Market Segmentation

Segmentation in 3D TSV devices separates packaging architectures by thermal budget constraints, die count economics, and interconnect density requirements. Buyers select configurations based on memory bandwidth targets, form-factor limits, and foundry integration depth.
Product Type:
Cost tier differentiation drives procurement patterns, with premium configurations commanding foundry-captive capacity while standard modules flow through OSAT channels.
- Wafer-Level Packaging:Bond alignment and underfill processes at sub-10-micrometer pitch command premium pricing from AI accelerator suppliers. TSMC's CoWoS capacity anchors demand in Taiwan's Hsinchu cluster, where NVIDIA and AMD secure allocation through direct contracts.
- System-in-Package:Modular die-to-die interconnect enables heterogeneous integration of logic, memory, and analog tiles in single substrates. Automotive sensor fusion modules in Germany and Japan adopt SiP for thermal management and LIDAR processor miniaturization.
- Chip-on-Wafer:Die-to-wafer bonding suits high-volume smartphone application processors with moderate stack heights.
- Multi-Chip Module:Legacy side-by-side die placement serves cost-sensitive industrial controllers with relaxed bandwidth requirements.
Volume sits with Wafer-Level Packaging; growth tilts toward System-in-Package.
End User:
Application maturity separates early-adopter segments with captive packaging investment from price-sensitive buyers dependent on merchant supply.
- Telecommunications:5G baseband processors and network interface cards require TSV-stacked memory for terabyte-per-second backplane throughput. Hyperscalers in North America consolidate procurement authority into centralized supply chain teams, displacing traditional OEM-mediated sourcing.
- Automotive:4D imaging radar and autonomous driving compute platforms drive qualification of AEC-Q100-rated TSV stacks. Germany's KBA and Japan's METI shape reliability standards for thermal cycling endurance in engine-compartment installations.
- Consumer Electronics:Smartphone application processors adopt hybrid bonding for logic-on-logic stacking at sub-5-micrometer pitch.
- Industrial Equipment:Programmable logic controllers and motor drives employ modest TSV configurations for deterministic latency.
Procurement concentrates in Telecommunications; Automotive climbs the fastest on sensor fusion module adoption.
Technology:
Process complexity determines equipment depreciation schedules and barrier-to-entry height for packaging houses.
- Through-Silicon Vias:Vertical copper-filled vias drilled through silicon wafers achieve interconnect pitches below 40 micrometers. Laser-assisted TSV reveal automates backside via exposure in Taiwan and Korea, reducing copper smear for 12-high HBM stacks.
- Advanced Interconnects:Hybrid bonding and thermocompression integration enable sub-10-micrometer die-to-wafer attachment. Samsung Electronics sustains upstream control over both DRAM wafer output and TSV etch equipment for captive stack production.
- IC Packaging:Wire bond and flip-chip foundations support legacy device categories with minimal TSV penetration.
- Chip Stacking:Thermocompression bonding serves mid-range memory modules with eight-layer HBM configurations.
Revenue pools in Through-Silicon Vias; Advanced Interconnects gains share fastest on hybrid bonding adoption.
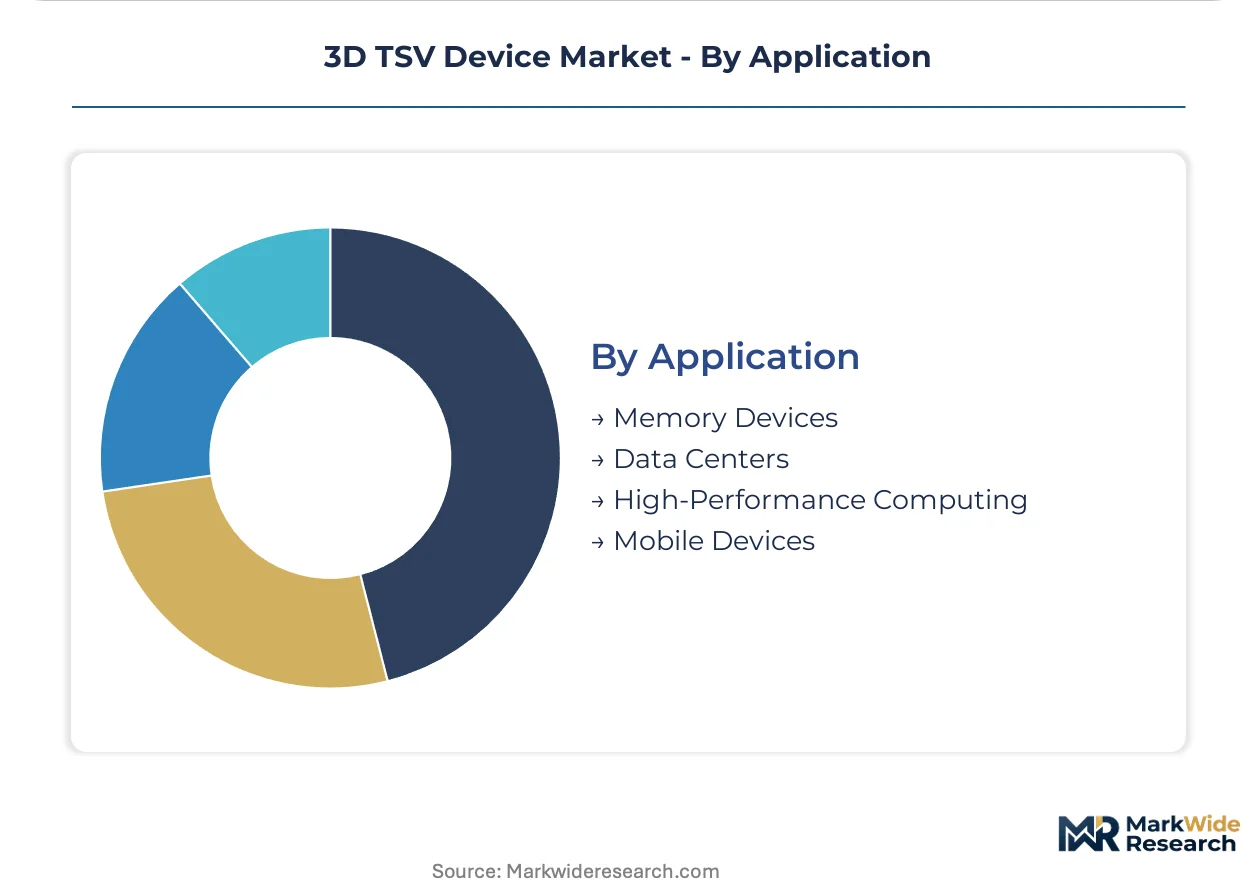
Application:
Bandwidth density thresholds separate memory-centric stacks from logic-dominated configurations in customer specifications.
- Memory Devices:HBM3E stacks require eight or more TSV-connected DRAM layers with terabyte-per-second aggregate bandwidth. Intel Corporation differentiates through Foveros-style active interposers that merge logic and memory tiles for AI training accelerators.
- Data Centers:Hyperscaler training cluster expansions pull wafer starts toward 12-high HBM configurations. Microsoft's Azure and Amazon Web Services account for dominant attach volumes in North American buildouts.
- High-Performance Computing:Government and academic supercomputing sites specify custom TSV stacks for exascale simulation workloads.
- Mobile Devices:Smartphone form-factor constraints limit stack height to four-layer configurations with reduced thermal envelopes.
Wafer starts concentrate in Memory Devices; Data Centers shows steepest expansion trajectory on AI infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park's tax-incentive framework anchors foundry-packaging integration density. Taiwan's captive CoWoS capacity draws NVIDIA and AMD allocation contracts. South Korea's Yongin cluster houses Samsung Electronics' DRAM-TSV vertical stack.
Taiwan
Memory bandwidth requirements from AI training accelerators pull wafer starts toward 12-high HBM configurations. The National Development Council's industrial park incentives sustain Hsinchu Science Park's captive CoWoS capacity. Taichung's precision machinery corridor supplies electrostatic chuck systems for 30-micrometer wafer handling.
South Korea
SK hynix and Samsung Electronics sustain upstream control over both DRAM wafer output and TSV etch equipment. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative subsidizes Yongin and Pyeongtaek packaging investments. Seoul Capital Area's equipment vendors qualify laser-assisted TSV reveal tools for backside via exposure.
United States
Hyperscalers consolidate procurement authority for AI accelerator substrates into centralized supply chain teams. The EPA and OSHA jointly influence fab chemical handling protocols and cleanroom emissions thresholds. Arizona's Phoenix metro attracts Intel Corporation's Foveros-style active interposer investments.
China
MIIT dual carbon goals tighten energy-efficiency benchmarks for advanced packaging facilities. GB standards on semiconductor manufacturing energy intensity accelerate qualification of low-temperature TSV metallization. Shanghai's Zhangjiang Hi-Tech Park concentrates OSAT capacity for domestic memory module assembly.
Germany
Automotive sensor fusion modules for LIDAR and 4D imaging radar processors adopt TSV-based SiP for thermal management. The KBA shapes reliability standards for thermal cycling endurance in engine-compartment installations. Dresden's Silicon Saxony cluster hosts automotive-qualified TSV stack qualification labs.
3D TSV Device Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the 3D TSV device landscape. Foundry-captive operators command premium pricing through bond alignment and underfill process control. Merchant OSATs compete on volume throughput for standard memory module configurations. Strategic moves concentrate on hybrid bonding tool qualification and geographic expansion into subsidized packaging zones.
Within the foundry-captive tier, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify vertical integration archetypes that merge logic wafer fabrication with advanced packaging capacity. Intel Corporation occupies a position bridging IDM and foundry service models. These three anchors represent divergent responses to terabyte-per-second memory bandwidth requirements: TSMC through CoWoS capacity concentration in Hsinchu, Samsung through Yongin-based DRAM-TSV stack control, and Intel through Arizona-based Foveros interposer development.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| Samsung Electronics |
| Intel Corporation |
| Amkor Technology |
| SK hynix |
| United Microelectronics Corporation |
| ASE Technology Holding |
| Toshiba Electronic Devices and Storage Corporation |
| Advanced Micro Devices |
| Others |
Supply Flow & Price Mechanics
Precision bonding engineers in Taiwan's Hsinchu corridor command wage premiums that compress margin spreads between captive foundry output and merchant OSAT tiers. Labor-cost differentials between Hsinchu and emerging packaging zones in India and Vietnam drive pricing-tier spreads across wafer-level packaging configurations.
Pricing Analysis
Short lead-time premiums for CoWoS capacity allocation at TSMC reach multiples of standard contract pricing, while spot-market inventory of legacy multi-chip modules trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates bond-alignment-critical AI accelerator substrates from automotive-qualified stacks and cost-sensitive industrial controllers. Cost compression in standard-tier memory modules is intensifying because palladium and ruthenium barrier metal supply concentration from Russian and South African refiners squeezes metallization margins. Hyperscalers exhibit lowest price sensitivity due to training cluster deployment timelines, while industrial equipment buyers demand economy-tier configurations with extended delivery windows.
Supply Chain Analysis
Dual-sourcing mandates from NVIDIA and AMD for HBM3E stacks require qualification of both SK hynix and Samsung Electronics DRAM output, preventing single-supplier lock-in. Geographic supply concentration centers on Taiwan for CoWoS packaging, South Korea for DRAM-TSV vertical integration, and China's Yangtze River Delta for OSAT assembly capacity. Raw material dependencies rest on Japanese fluorinated etch chemistries, German electrostatic chuck systems, and US-designed bond alignment tools. Single-source vulnerability concentrates in 30-micrometer wafer-thinning equipment where Japanese vendors dominate. Distribution runs through direct contracts between hyperscalers and foundry-captive packagers, displacing traditional component distributor channels.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from terabyte-per-second bandwidth requirements and billion-dollar packaging tool investments is forcing sub-scale OSATs toward acquisition or exit. Capital intensity barriers favor players with captive DRAM supply or foundry integration depth.
For Market Incumbents: Anchor CoWoS allocation contracts through multi-year direct agreements with hyperscalers, locking out merchant competitors from high-margin AI accelerator substrate volumes. Defend yield advantages by deepening in-house production of bond alignment metrology systems, reducing dependence on Japanese equipment vendors. Prioritize qualification of low-temperature TSV metallization processes ahead of China's MIIT energy-intensity enforcement timelines.
For New Entrants and Emerging Players: India's PLI scheme for semiconductor packaging opens a window for greenfield OSAT investment in Gujarat and Tamil Nadu, capturing subsidy-backed cost positions for display and memory module assembly. Target automotive sensor fusion modules in Germany and Japan where AEC-Q100 qualification requirements create incumbent switching costs below data center thresholds. Pursue joint development agreements with LIDAR processor fabless designers to secure initial volume commitments before foundry-captive competitors expand capacity.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap OSATs possessing hybrid bonding tool qualifications given convergence of copper TSV and oxide fusion bonding roadmaps. Long-term viability over the next decade hinges on positioning within AI accelerator supply chains rather than legacy smartphone or industrial exposure. Watch hyperscaler capital expenditure disclosure patterns as the inflection indicator for CoWoS capacity utilization and pricing power direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Tool Qualification | Enables sub-5-micrometer logic-on-logic stacking for smartphone application processors at Samsung Electronics. |
| CoWoS Capacity Expansion | TSMC's Hsinchu investments anchor NVIDIA and AMD allocation contracts for AI training accelerators. |
| Low-Temperature TSV Metallization | Qualification ahead of China's MIIT GB standards enforcement protects margin structure from energy-intensity penalties. |
| Automotive AEC-Q100 Certification | Opens sensor fusion module opportunities with Germany's KBA-regulated LIDAR and 4D imaging radar suppliers. |
| Laser-Assisted TSV Reveal Adoption | Automates backside via exposure for 12-high HBM stacks, reducing copper smear at SK hynix and Samsung Electronics. |
Methodological Framework
Independent corroboration across equipment vendor technical documentation, foundry capacity disclosure filings, and hyperscaler procurement manager interviews underwrites the qualitative findings. Primary fieldwork engaged TSV process engineers at memory foundries, packaging procurement leads at AI accelerator designers, bond alignment equipment specialists, and automotive semiconductor qualification managers. Secondary validation drew from SEC semiconductor capital expenditure filings, Korean Ministry of Trade K-Semiconductor Belt policy documents, Taiwan National Development Council industrial park incentive records, and EPA cleanroom emissions compliance databases. Bottom-up wafer start estimates and top-down packaging revenue aggregates were reconciled across the analysis window.
Comparable-period anchoring tied forward projections to historical CoWoS capacity ramp patterns and HBM generation transition timelines. The analytical framework modeled segmentation dimensions spanning packaging architecture type, end-use application maturity, interconnect technology complexity, and foundry integration depth. CAGRs were derived from slope-consistency checks against memory bandwidth demand curves and packaging tool shipment data. Forecast inputs incorporated hyperscaler training cluster deployment schedules and China's MIIT dual carbon enforcement trajectory.
The model assumes a particular technology adoption path; alternative pathways for hybrid bonding-copper TSV convergence would alter the outlook if oxide fusion bonding achieves cost parity ahead of projected timelines. Forecasts reflect assumptions on palladium and ruthenium supply stability, AEC-Q100 automotive qualification timelines, and HBM3E yield ramp trajectories. Deviation in hyperscaler capital expenditure commitment levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Japan International CEP Market