
 Automotive Grade Emmc Market | 2026-2036
Automotive Grade Emmc Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Grade Emmc Market Insights
South Korean memory fabs is pivoting toward automotive-qualified output as consumer electronics margins compress. Samsung Electronics leverages captive wafer capacity to secure long-term supply agreements with German OEMs. Kioxia anchors its competitive position through BiCS 3D NAND technology leadership in high-temperature automotive grades. SK Hynix competes aggressively on 128GB and 256GB density tiers for next-generation cockpit systems.
Automotive grade eMMC denotes embedded MultiMediaCard storage engineered to AEC-Q100 temperature grades, with operating ranges from -40°C to 105°C and built-in ECC, wear leveling, and bad block management for mission-critical data retention in vibration-intensive vehicle environments. The technology serves as the primary non-volatile storage medium for infotainment head units, telematics control modules, and ADAS sensor fusion buffers. NAND Flash technology dominates the architecture, with 3D NAND displacing planar 2D NAND across 128GB and 256GB capacity tiers where bit density and cost-per-gigabyte advantages concentrate margin pools. TLC cells capture volume share in mainstream infotainment applications, while SLC persists in brake-by-wire and steering systems demanding maximum write endurance.
FDA oversight of software-defined vehicle health monitoring interfaces intersects with NHTSA cybersecurity guidelines for connected car data integrity. EPA fuel-economy tracking mandates and EMA-equivalent European type-approval requirements for digital odometer storage create compliance pull-through for tamper-resistant eMMC modules. Stakeholders must monitor how ISO 26262 functional safety等级 and emerging UN R155 cybersecurity regulations reshape qualification timelines and supplier certification barriers.
Market Dynamics
AEC-Q100 qualification timelines are compressing as automakers accelerate platform refresh cycles, forcing memory suppliers to front-load reliability testing while 3D NAND process migrations simultaneously demand new characterization protocols.
Growth Catalysts
- ADAS sensor fusion architectures:Multi-camera surround-view systems and lidar point-cloud buffering require high-throughput embedded storage with deterministic latency profiles.
- UN R155 cybersecurity mandates:European type-approval requirements for tamper-evident data logging are pulling hardened eMMC modules into telematics gateways.
- Electric vehicle cockpit digitization:Battery electric platforms from Stuttgart to Shenzhen are eliminating mechanical gauge clusters, expanding addressable storage sockets per vehicle.
Market Restraints
- 300mm wafer supply concentration:Frontend fab capacity for automotive-qualified NAND remains concentrated among three Korean and two Japanese producers, creating allocation vulnerability during consumer electronics demand spikes.
- SLC NAND process sunset:Planar 1Xnm SLC production is yielding to 3D TLC economics, eroding supply for brake-by-wire and steering systems requiring million-cycle write endurance.
- ISO 26262 ASIL-D certification costs:Functional safety documentation for storage controllers adds eighteen-to-twenty-four month qualification overhead before production release.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for electric vehicle production are creating localized demand for AEC-Q100 qualified storage as Tata Motors and Mahindra scale domestic platforms.
- Vehicle-to-everything data logging:Edge computing architectures for V2X safety messaging require fault-tolerant local storage before cloud transmission.
- Software-defined vehicle OTA buffering:Firmware update staging in gateway modules is creating incremental density demand beyond infotainment head units.
Industry Challenges
- Automotive reliability engineering talent scarcity:Specialized expertise in zero-defect methodologies and accelerated life testing for memory devices commands premium compensation in Dresden, Yokohama, and Austin hiring markets.
- Legacy 2D NAND qualification amortization:Long-life vehicle programs demand supply continuity for planar process nodes that fabs have already deprecated, forcing lifetime buy strategies or costly process requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Grade Emmc Market |
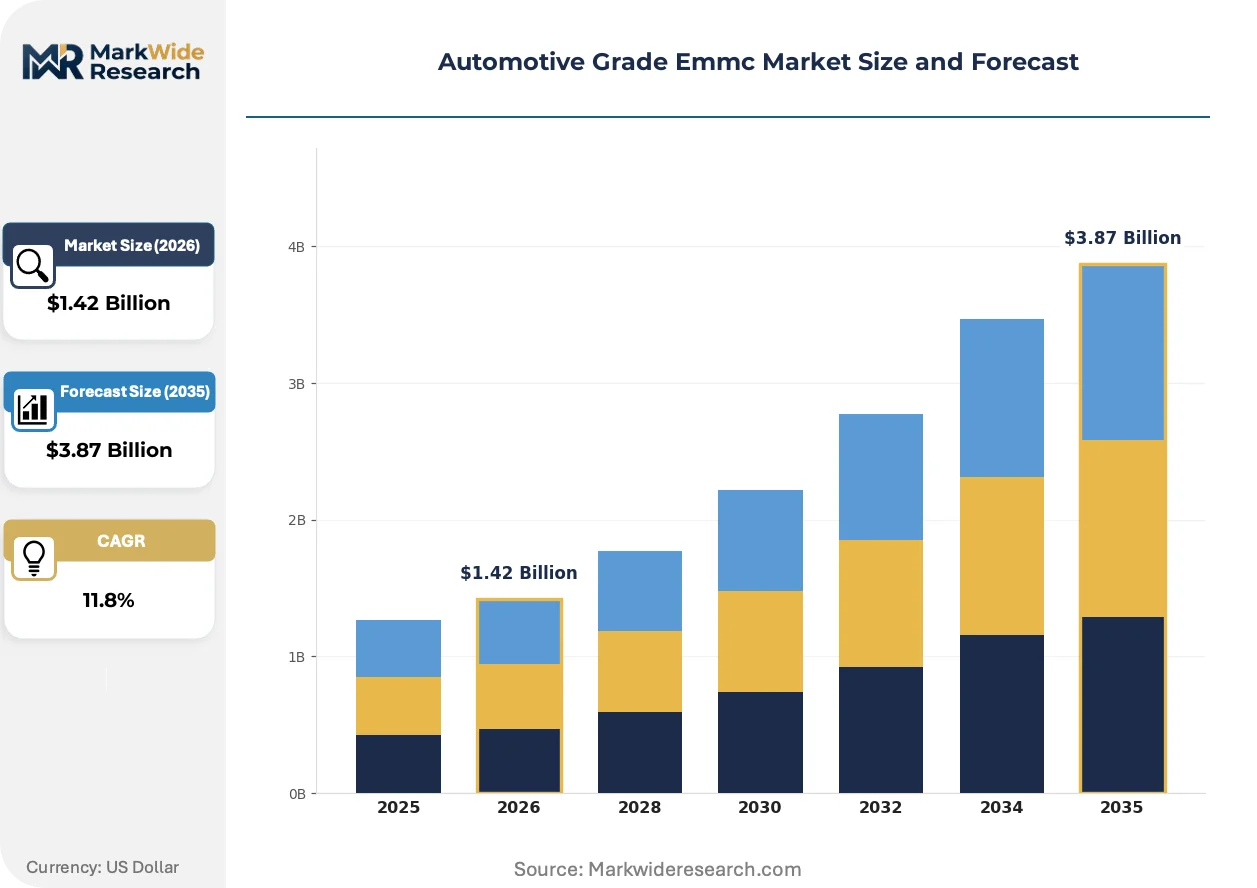
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MLC, TLC, QLC, SLC End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Technology: NAND Flash, DRAM, 3D NAND, 2D NAND Capacity: 32GB, 64GB, 128GB, 256GB |
| Companies Covered | Samsung Electronics, Kioxia, Western Digital, Micron Technology, SK Hynix, Toshiba Corporation, ATP Electronics, Longsys, SiliconGo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Grade Emmc Market Trends and Innovations
Storage architecture decisions in next-generation vehicle platforms are decoupling from infotainment-centric legacy designs, with compute consolidation and zonal E/E architectures redistributing memory requirements across domain controllers.
3D TLC NAND with pseudo-SLC caching is modularizing automotive storage subsystems, enabling tiered endurance allocation within single physical devices. Tier-1 suppliers including Bosch and Continental are adopting these configurable partitions for mixed-criticality workloads. The approach is modularizing what were previously discrete SLC and eMMC component selections into unified bill-of-materials strategies.
NHTSA cybersecurity guidelines for connected vehicles are mandating hardware-rooted secure boot and encrypted storage partitions for safety-critical ECUs. The regulation is forcing controller redesigns that segregate infotainment and chassis domains at the physical layer. German OEMs are responding fastest, with BMW and Mercedes-Benz requiring Common Criteria EAL4+ certified storage controllers in gateway modules from 2026 platforms.
Fleet operators and mobility service providers are compressing supplier qualification cycles, bypassing traditional Tier-1 distribution channels for direct memory procurement. Leasing companies including Sixt and Enterprise are specifying eMMC endurance metrics in vehicle residual value calculations. This behavior is most visible in North American and Western European commercial fleet segments where total cost of ownership models dominate procurement decisions.
Automotive Grade Emmc Market Segmentation
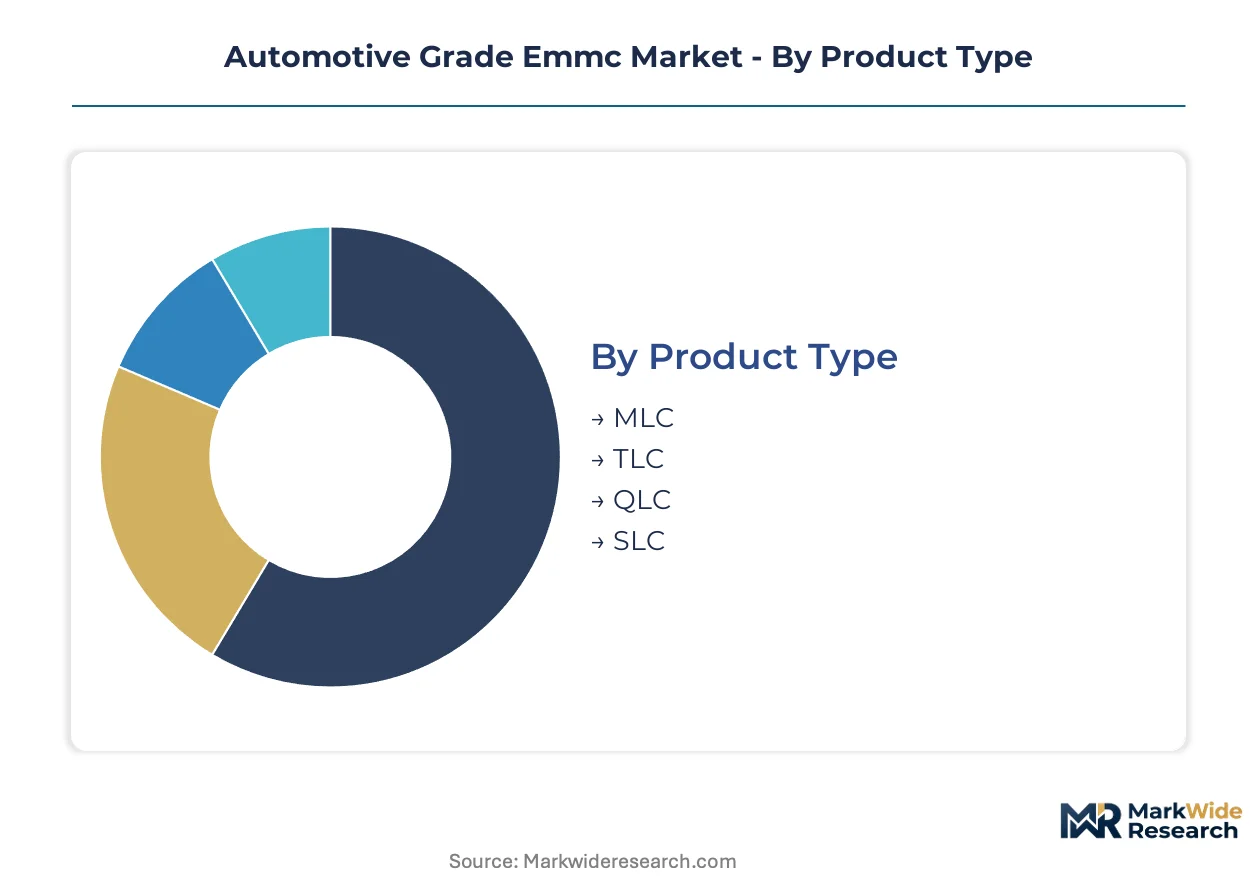
eMMC procurement decisions in automotive electronics hinge on qualification tier, capacity density, and endurance requirements that vary sharply across infotainment, ADAS, and chassis control applications. Memory suppliers must align process technology roadmaps with platform-specific AEC-Q100 grade demands to secure socket wins.
Product Type:
Cost-per-gigabyte and write endurance requirements drive cell-level selection across vehicle subsystems.
- MLC:Stores two bits per cell with moderate endurance profiles suited for navigation map caching and media storage in mid-range infotainment systems. German OEMs specify MLC for economy-segment head units where 3,000-5,000 program-erase cycles satisfy replacement-cycle durability.
- TLC:Triple-level cell architecture dominates 128GB and 256GB sockets through superior bit density, with pseudo-SLC caching modes extending effective endurance for mixed-criticality workloads. China-based EV manufacturers source TLC eMMC aggressively for digital cockpit consolidation.
- QLC:Quadruple-level cell technology targets read-intensive cold storage applications such as firmware archives and diagnostic log buffers where write frequency remains minimal.
- SLC:Single-level cell devices deliver million-cycle endurance for brake-by-wire and electric power steering modules, though planar process discontinuation is tightening supply.
Volume sits with TLC; growth tilts toward QLC as read-heavy edge computing workloads expand.
End User:
Procurement authority and qualification timelines vary substantially across the automotive value chain.
- OEMs:Volkswagen, Toyota, and Ford retain direct sourcing control for gateway and ADAS domain controllers, mandating Common Criteria EAL4+ certified storage for cybersecurity compliance.
- Tier-1 Suppliers:Bosch, Continental, and Denso integrate eMMC into pre-validated ECU platforms, amortizing ISO 26262 ASIL-D certification costs across multiple OEM programs.
- Vehicle Assemblers:Contract manufacturers in India and Mexico execute build-to-print specifications without design authority, creating price-sensitive spot procurement for standardized infotainment modules.
- Aftermarket Providers:Independent service channels source unqualified commercial-grade eMMC for telematics retrofits and head unit upgrades, bypassing AEC-Q100 testing to capture margin.
Revenue concentrates with Tier-1 suppliers; direct OEM procurement is expanding fastest.
Technology:
Process node selection determines thermal tolerance, supply security, and controller complexity requirements.
- NAND Flash:The foundational non-volatile memory technology underlying all automotive eMMC architectures, with floating-gate and charge-trap variants competing for high-temperature grade sockets.
- DRAM:Volatile memory complements eMMC in sensor fusion buffers requiring high-speed temporary storage before persistent logging, though DRAM lacks automotive qualification density.
- 3D NAND:Vertical stacking architectures from 64-layer to 176-layer configurations dominate new platform designs, offering cost and density advantages that planar processes cannot match.
- 2D NAND:Legacy planar processes persist in long-life commercial vehicle programs where requalification costs exceed lifetime buy premiums for established SLC supply.
Shipments favor 3D NAND; 2D NAND retains niche defense in 15-year service-life segments.
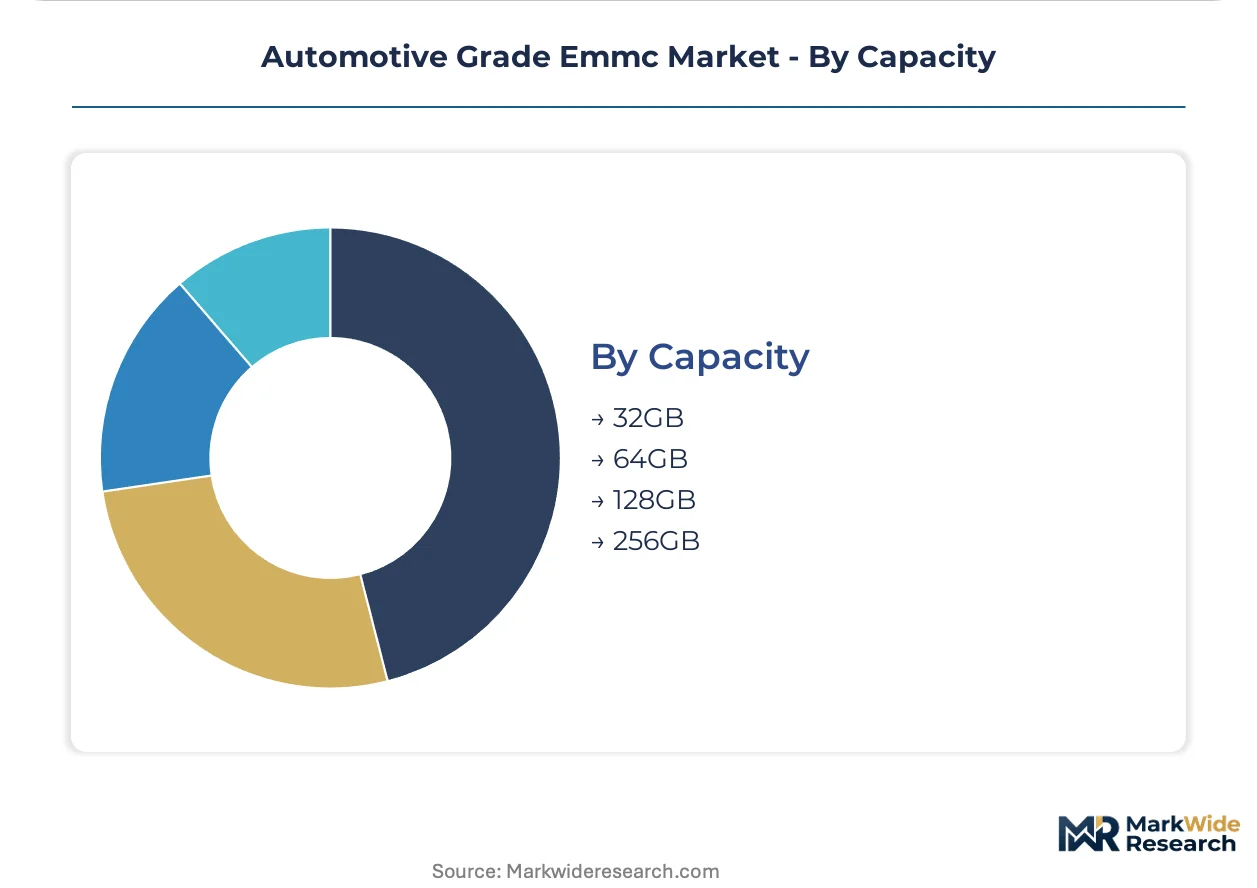
Capacity:
Density selection tracks software bloat in infotainment and expanding sensor data retention mandates.
- 32GB:Entry-level capacity tier serving instrument cluster graphics rendering and basic telematics datalogging in emerging market vehicle platforms.
- 64GB:Mid-range density accommodating consolidated navigation, media, and vehicle settings storage for compact and mid-size vehicle segments.
- 128GB:Surround-view camera buffering and over-the-air update staging are concentrating demand here, with Korean fabs allocating wafer starts to this tier for next-generation cockpit systems.
- 256GB:Premium density grade supporting 4K display content, extended map caching, and V2X edge computing workloads in luxury electric platforms from Stuttgart to Shenzhen.
128GB anchors current volume; 256GB is climbing the fastest as cockpit digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NAND wafer fabrication concentrates in South Korea and Japan, creating geographic dependencies that reshape procurement patterns for automotive-qualified memory across final assembly markets.
China
Domestic EV manufacturers from BYD to NIO are localizing cockpit system production, pulling AEC-Q100 qualified eMMC through Shenzhen and Shanghai electronics corridors. MIIT cybersecurity standards for connected vehicles mandate tamper-evident storage architectures. Yangtze River Delta clusters around Suzhou and Wuxi host module integration facilities serving both local OEMs and export programs.
Germany
Stuttgart and Munich OEMs specify Common Criteria EAL4+ certified storage for gateway modules in next-generation platforms launching from 2026. KBA type-approval processes integrate UN R155 cybersecurity requirements that harden data logging specifications. Bavaria's semiconductor ecosystem around Ingolstadt and Regensburg anchors qualification testing for Tier-1 suppliers supplying European premium platforms.
United States
Detroit Three automakers and Tesla are consolidating compute architectures, expanding addressable sockets per vehicle beyond traditional infotainment boundaries. NHTSA cybersecurity guidelines for connected vehicles mandate hardware-rooted secure boot capabilities. Austin and Phoenix emerging as design centers where automotive reliability engineering talent commands premium compensation.
India
Tata Motors and Mahindra scaling domestic EV platforms under PLI scheme incentives, creating localized demand for AEC-Q100 qualified storage components. BIS certification requirements for automotive electronics are tightening import substitution timelines. Tamil Nadu and Gujarat manufacturing corridors attracting module assembly investments to serve ASEAN export markets.
Japan
Toyota and Honda retaining direct sourcing control for ADAS domain controllers, specifying extended temperature grades for harsh-environment applications. METI industrial policy supports domestic NAND fabrication capacity for strategic autonomy in automotive semiconductors. Kyushu fabrication clusters maintain legacy process continuity for long-life commercial vehicle programs.
Automotive Grade Emmc Market Competitive Landscape
Global majors compete with regional champions across qualification tiers and density segments, creating a bifurcated structure where captive wafer capacity separates strategic suppliers from module integrators. Korean and Japanese fabricators dominate frontend production, while Chinese specialists capture downstream module assembly. Three archetypes define competitive positioning: integrated IDMs with captive NAND fabs, fabless controller designers partnering for automotive qualification, and module specialists aggregating components for Tier-1 ECU platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing long-term supply agreements or backward integrating into test and qualification capabilities.
Among integrated device manufacturers, Samsung Electronics, Kioxia, and SK Hynix exemplify the wafer-captive archetype, occupying positions where in-house NAND production enables volume commitments to German and US OEMs. These Korean and Japanese entities represent the supply-side anchor for AEC-Q100 qualified output, with their geographic concentration in East Asian fabrication clusters shaping allocation dynamics during demand spikes. Western Digital and Micron Technology sit within the multinational tier, leveraging diversified manufacturing footprints to serve qualification requirements across multiple regulatory jurisdictions.
| Leading Market Players |
|---|
| Samsung Electronics |
| Kioxia |
| Western Digital |
| Micron Technology |
| SK Hynix |
| Toshiba Corporation |
| ATP Electronics |
| Longsys |
| SiliconGo |
| Others |
Pricing and Supply Chain Analysis
NAND flash spot price indices from DRAMeXchange cascade through automotive eMMC supply chains, compressing margins for module integrators while wafer-captive IDMs capture value through long-term supply agreements with German and US OEMs. AEC-Q100 qualification tiers stratify pricing across premium automotive-grade certifications and economy commercial-grade alternatives.
Pricing Analysis
Warranty bundling separates qualified automotive-grade eMMC with extended temperature validation from unbundled commercial-grade alternatives lacking AEC-Q100 certification. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 ASIL-D certification overhead, volume scale commitments, and geographic delivery logistics. Pricing pressure stems from Korean fab allocation constraints during consumer electronics demand spikes. Tier-1 suppliers exhibit lowest price sensitivity due to amortized qualification costs, while vehicle assemblers in India and Mexico drive spot-market negotiation.
Supply Chain Analysis
India's PLI scheme and China's MIIT localization mandates are reshaping sourcing patterns, pulling module assembly toward Tamil Nadu and Yangtze River Delta corridors. Frontend wafer supply concentrates in South Korea, Japan, and Taiwan, drawing from 300mm NAND fabrication facilities. Raw material dependencies span silicon wafers, specialty gases, and lithography equipment. Single-source vulnerability concentrates in Korean fab allocation during demand spikes. Distribution runs through Tier-1 ECU platforms rather than direct OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
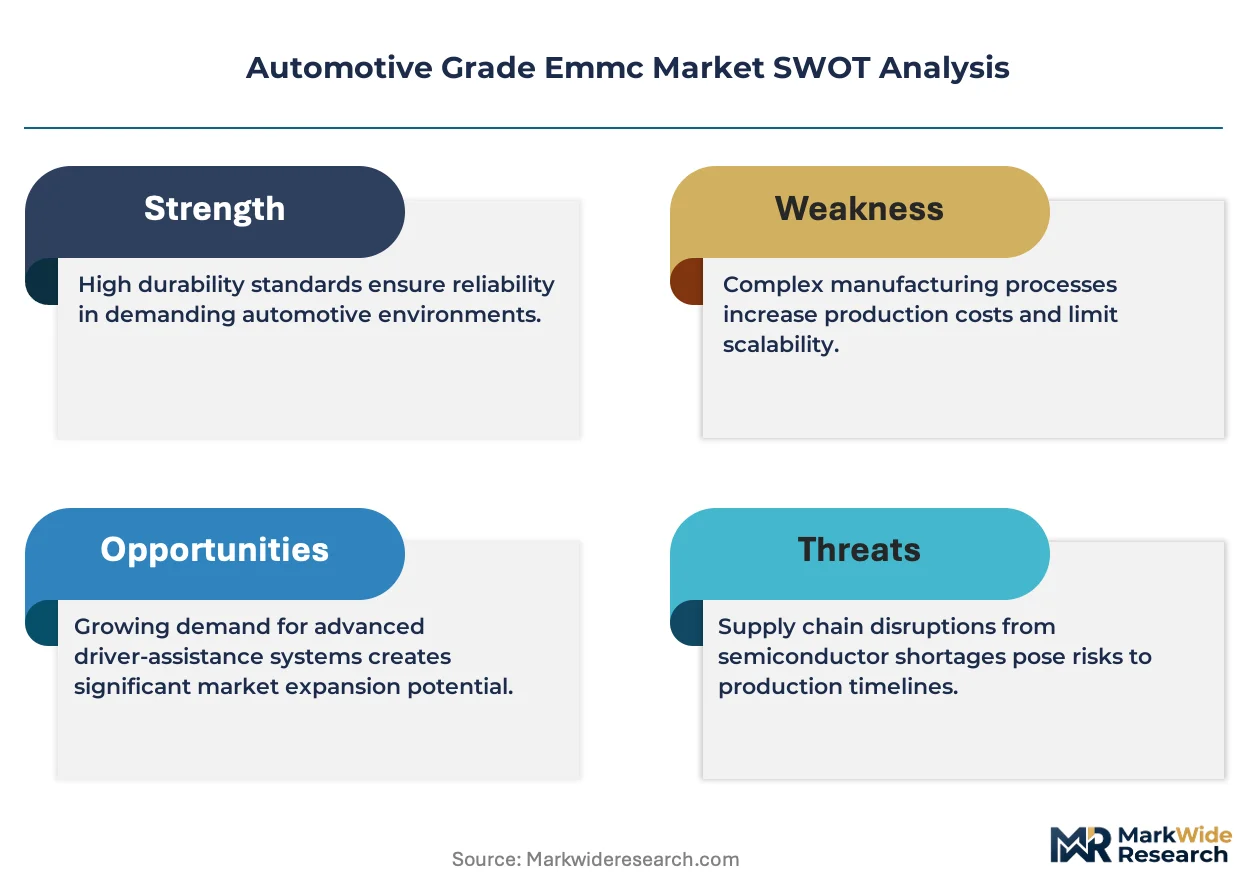
Automotive-grade eMMC operates as a supply-constrained market where 300mm wafer capacity at Korean and Japanese fabs props pricing power for integrated device manufacturers. Memory suppliers must secure allocation priority through long-term agreements.
For Market Incumbents: Deepen captive wafer utilization through backward integration into test and qualification capabilities, securing socket wins as Chinese EV manufacturers localize cockpit production. Threaten emerging fabless controller designers by accelerating AEC-Q100 Grade 2 certification timelines. Prioritize capacity addition in South Korean clusters serving Stuttgart and Detroit OEMs. For New Entrants and Emerging Players: The premium-economy price-point gap in 64GB and 128GB density tiers opens white-space for module specialists aggregating components for Indian and ASEAN vehicle assemblers. Target PLI scheme beneficiaries in Tamil Nadu and Gujarat manufacturing corridors. Pursue direct procurement relationships with fleet operators bypassing traditional Tier-1 channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless controller designers with automotive qualification expertise in Taiwan and China, positioned for acquisition by integrated IDMs seeking controller IP. Long-term viability centers on software-defined vehicle OTA buffering demand expanding addressable sockets per vehicle. Watch NHTSA cybersecurity guideline enforcement as inflection signal for hardened storage controller demand.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Samsung Electronics secures wafer allocation priority with German OEMs through multi-year contracts. |
| AEC-Q100 Grade 2 Certification | Kioxia accelerates qualification timelines to capture ADAS domain controller sockets from Bosch. |
| Geographic Manufacturing Footprint | Module assembly investments in Tamil Nadu serve Tata Motors PLI scheme localization requirements. |
| Software-Defined Vehicle Investment | SK Hynix targets gateway module OTA buffering density demand beyond infotainment boundaries. |
| Backward Integration into Testing | Longsys acquires reliability engineering capabilities to reduce ISO 26262 certification overhead. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive semiconductor analysis. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, NAND fab planning directors, and aftermarket distributors validated demand assumptions. Secondary sources included AEC component qualification databases, MIIT cybersecurity standards, NHTSA connected vehicle guidelines, and vehicle production registration data. Bottom-up socket-per-vehicle modeling triangulated against top-down wafer allocation estimates from Korean and Japanese fabrication clusters.
Data-stream reconciliation across shipment volumes, fab utilization rates, and OEM platform launch timelines informed the projection framework. Segmentation dimensions spanned cell architecture, capacity density, AEC-Q100 grade tier, end-user procurement authority, and regional production cluster. CAGRs derived from fitted growth curves applied to vehicle electrification penetration and cockpit digitization content-per-vehicle trajectories. Forecast inputs incorporated UN R155 cybersecurity mandate implementation schedules and PLI scheme incentive disbursement patterns.
Inputs from NAND fab utilization disclosures and OEM platform roadmaps were available through the study window; gaps in long-term SLC NAND supply continuity introduce uncertainty bands around brake-by-wire endurance requirements. Forecasts reflect assumptions regarding AEC-Q100 qualification timeline compression and 3D NAND process migration stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Nanowires Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Ram BOP Market