
 Semiconductor X-Ray Diffractometers Market | 2026-2036
Semiconductor X-Ray Diffractometers Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor X-Ray Diffractometers Market Insights
REACH chemical restrictions on lead-based shielding materials is pivoting equipment design priorities across the supply chain. Rigaku Corporation leverages its rotating anode heritage to compete in high-brightness configurations for advanced node inspection. Bruker Corporation anchors its position through R&D intensity in parallel beam geometries for strained silicon analysis. Malvern Panalytical differentiates via application-specific software bundles that reduce operator training burdens in foundry environments.
Semiconductor X-Ray Diffractometers are analytical instruments that determine crystal structure, phase composition, and epitaxial strain in semiconductor materials by measuring X-ray diffraction patterns at angular resolutions typically below 0.0001 degrees. These systems employ sealed-tube or rotating-anode X-ray sources with specialized optics to characterize thin films, wafers, and device structures during process development and quality assurance. High-Resolution Diffractometers command attention for silicon-germanium and III-V compound semiconductor characterization where lattice parameter precision determines device yield. Powder Diffractometers occupy a mature niche in raw material qualification, while Microdiffraction capabilities are extending into packaged die failure analysis where spot sizes below 50 micrometers isolate individual interconnect structures.
EPA radiation safety standards and EU RoHS substance restrictions shape X-ray tube construction, detector cooling architectures, and end-of-life disposal protocols for equipment deployed in US and European facilities. Japan's METI oversees industrial X-ray equipment certification through JIS standards that influence export specifications for Asian-manufactured systems. China's NMPA and GB standards create parallel compliance pathways for equipment entering domestic fabs operated by SMIC and Yangtze Memory Technologies. Stakeholders must monitor how divergent regional radiation safety thresholds affect platform standardization strategies and service part inventory requirements across multinational install bases.
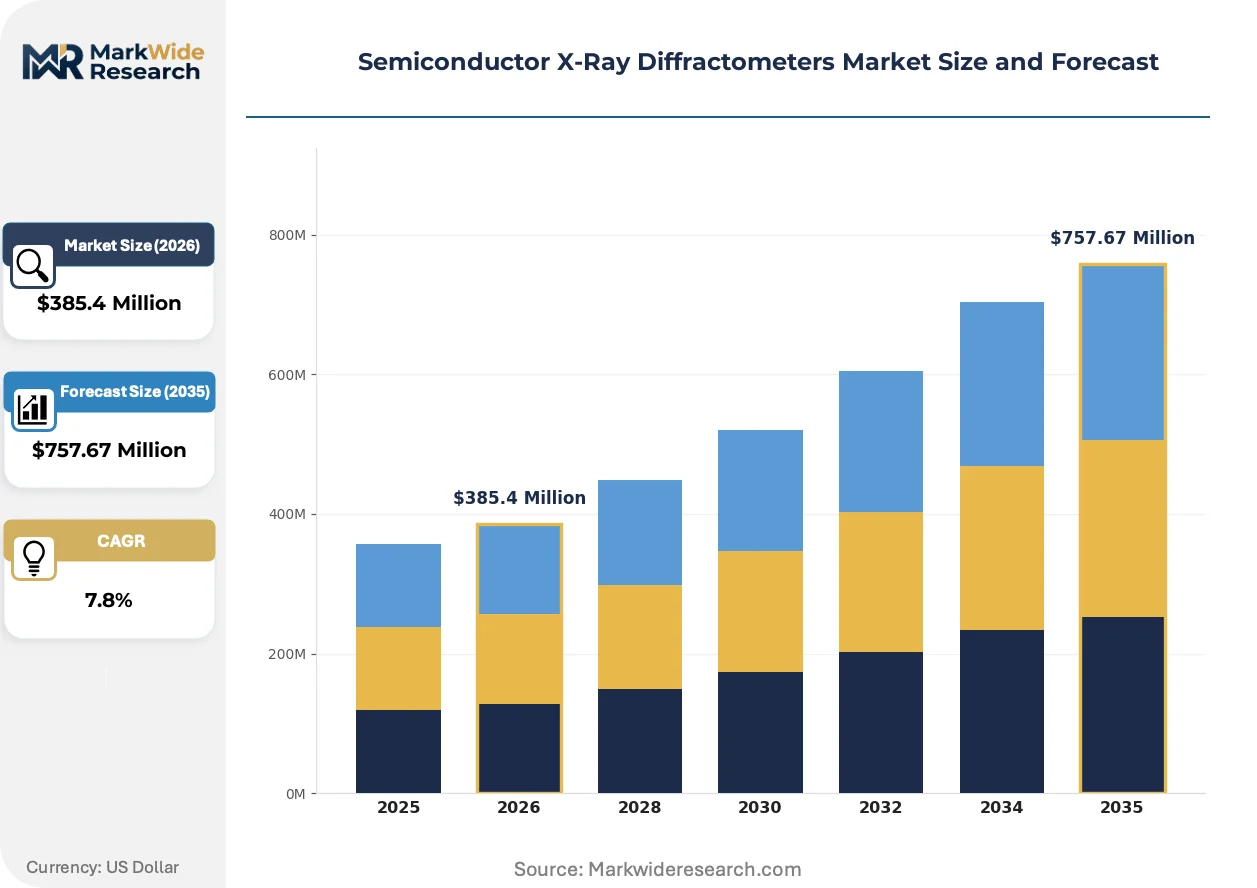
Market Dynamics
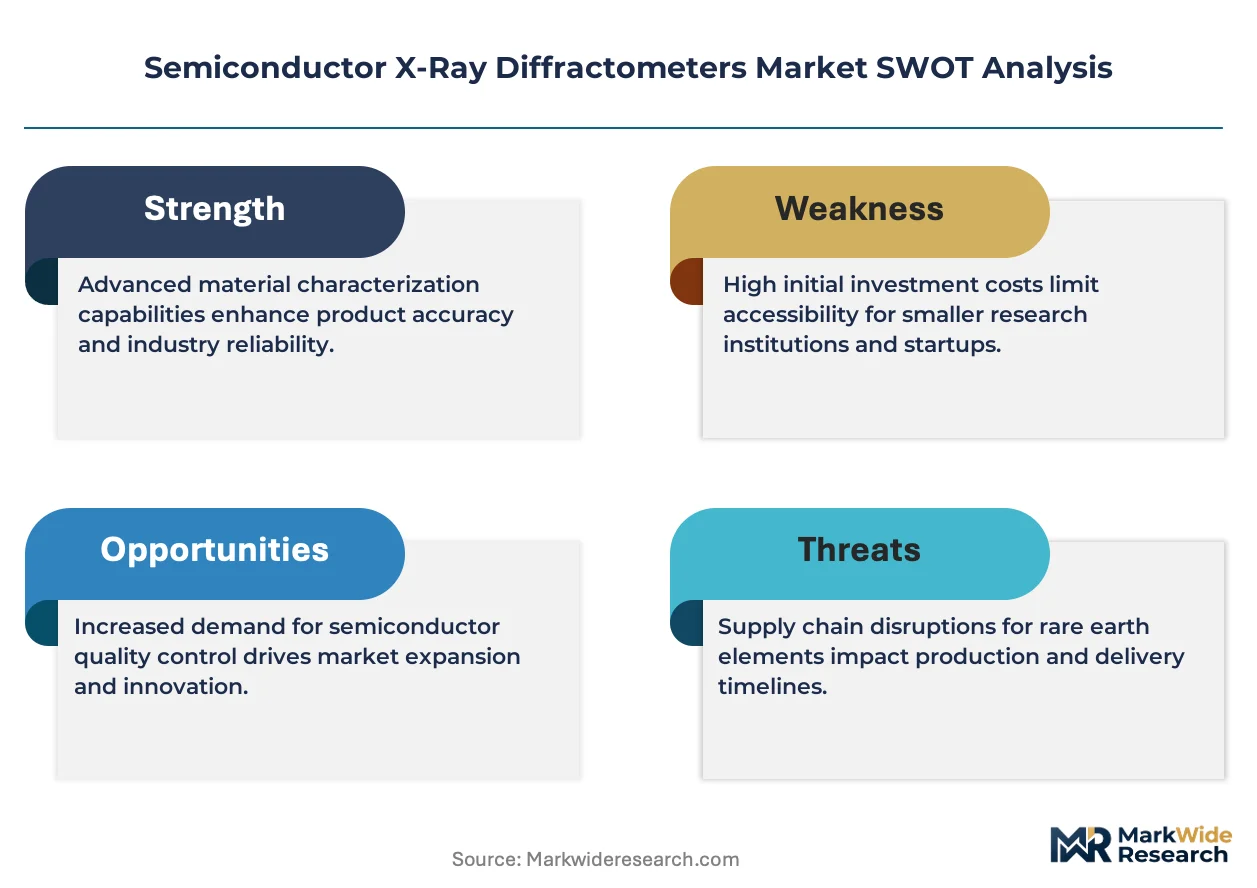
EUV lithography node shrinkage below 3nm is forcing foundry operators to expand metrology budgets and upgrade X-ray diffraction capabilities for lattice strain mapping at atomic-scale precision.
Growth Catalysts
- EU Green Deal chemical compliance:Equipment vendors are redesigning X-ray tube housings and coolant systems to eliminate hazardous substances, creating replacement demand across European install bases.
- Hsinchu Science Park corridor concentration:Taiwan's foundry cluster is driving concentrated procurement of high-brightness rotating anode systems for advanced node characterization.
- EUV lithography node shrinkage:Sub-3nm process development requires angular resolutions below 0.0001 degrees for silicon-germanium strain analysis, pulling premium system configurations.
Market Restraints
- Lead-based shielding phase-out:REACH chemical restrictions on traditional radiation shielding materials are forcing costly housing redesigns and extending equipment certification timelines.
- Rotating anode supply concentration:High-brightness X-ray source manufacturing clusters in Japan and Germany create single-source vulnerability for advanced system configurations.
- Detector cooling complexity:Liquid nitrogen and closed-cycle cryostat architectures add operational overhead that limits deployment in fabs without specialized infrastructure.
Strategic Opportunities
- Packaged die failure analysis:Microdiffraction capabilities with spot sizes below 50 micrometers are extending into post-packaging inspection, opening semiconductor assembly and test facilities as new customer segments.
- South Korea memory fab expansion:Samsung and SK Hynix capacity additions are creating localized demand for parallel beam geometries optimized for strained silicon analysis.
- Application-specific software bundles:Automated pattern recognition and reduced operator training requirements are creating differentiation in foundry environments where technician turnover is high.
Industry Challenges
- Crystallography technician scarcity:Specialized expertise in epitaxial strain interpretation is concentrating among senior metrologists, constraining fab ramp speeds.
- Multinational compliance fragmentation:Divergent radiation safety thresholds across EPA, METI JIS standards, and China GB standards complicate platform standardization and inflate service part inventory costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor X-Ray Diffractometers Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Crystal Diffractometers, Powder Diffractometers, High-Resolution Diffractometers, Rotating Anode Diffractometers Application: Material Analysis, Thin Film Measurement, Quality Control, Stress Analysis End User: Academic Research Institutes, Semiconductor Manufacturers, Material Science Labs, Aerospace Companies Technology: Bragg-Brentano Geometry, Laue Diffraction, Parallel Beam Geometry, Microdiffraction |
| Companies Covered | Rigaku Corporation, Bruker Corporation, Malvern Panalytical, Thermo Fisher Scientific, Shimadzu Corporation, Agilent Technologies, PerkinElmer, Anton Paar, JEOL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor X-Ray Diffractometers Market Trends and Innovations
Parallel beam geometry advances and detector cooling architectures are compressing measurement cycles while regulatory pressure on hazardous materials is rewriting equipment design priorities across the supply chain.
High-brightness rotating anode configurations is rewriting competitive positioning in advanced node inspection. Foundry operators in Taiwan and South Korea are adopting these systems aggressively for silicon-germanium characterization. The technology is compressing measurement times from hours to minutes for strained layer superlattice analysis.
REACH chemical restrictions on lead-based shielding materials are forcing housing redesigns across European-deployed equipment. Vendors must substitute bismuth or tungsten composites while maintaining radiation attenuation performance. This regulatory pressure falls most heavily on legacy system upgrades where retrofit certification timelines extend 12-18 months.
After-sales service unbundling is emerging as procurement departments separate hardware acquisition from maintenance contracts and software licensing. Foundry operators in East Asia are negotiating standalone calibration and training packages. This pattern is most pronounced in South Korea where memory manufacturers operate multi-vendor metrology suites.
Semiconductor X-Ray Diffractometers Market Segmentation
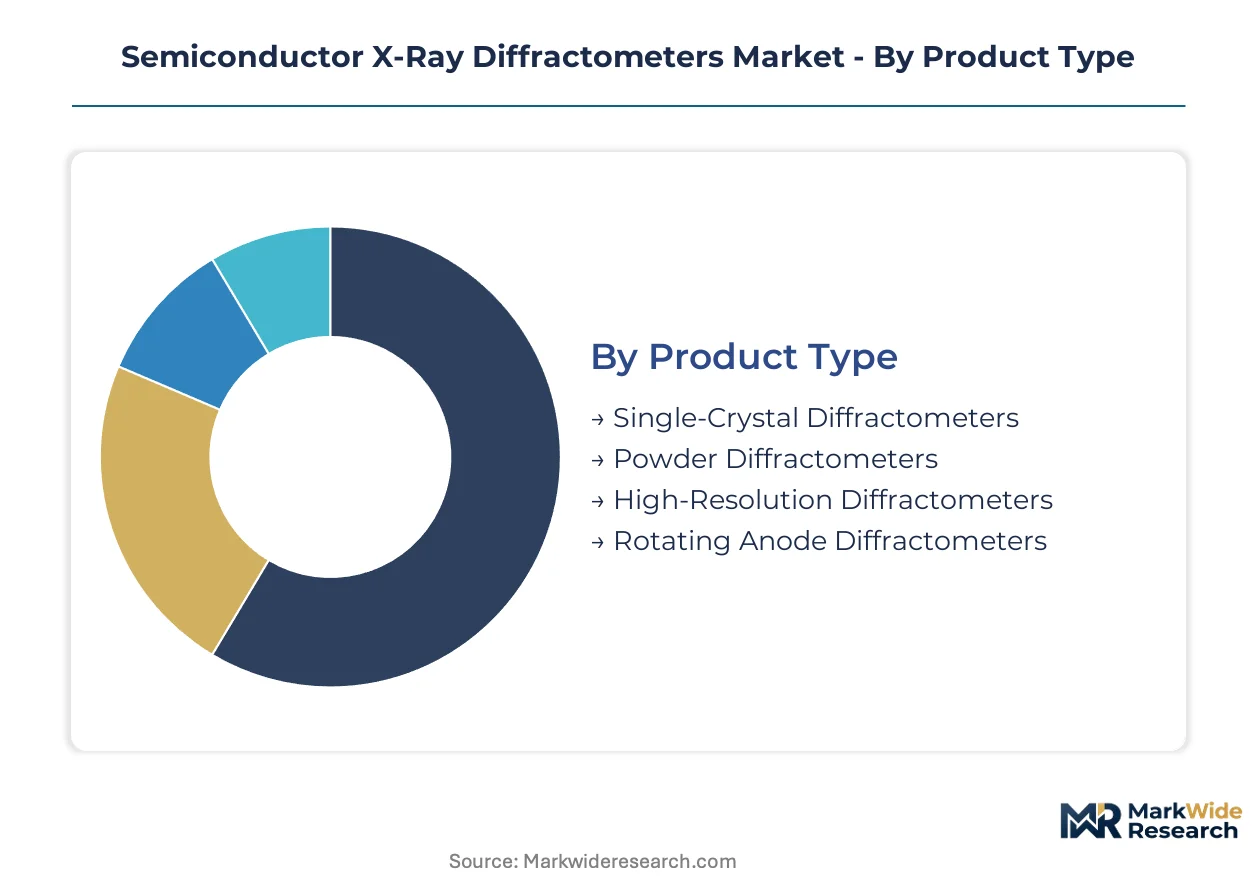
Semiconductor X-Ray Diffractometer segmentation reflects distinct integration depths across fabrication workflows. Standalone systems dominate high-throughput quality control lines, while embedded configurations serve inline process monitoring. Procurement patterns diverge sharply between research environments requiring configurability and fabs prioritizing throughput stability.
Product Type:
Integration depth separates benchtop research units from fully automated fab floor systems, with rotating anode configurations occupying the highest-brightness tier for advanced node inspection.
- High-Resolution Diffractometers:These systems achieve angular resolutions below 0.0001 degrees through specialized monochromator optics and precision goniometers. Demand concentrates in Taiwan's Hsinchu Science Park corridor where silicon-germanium strain analysis determines device yield at sub-3nm nodes. EUV lithography shrinkage is pulling premium configurations as foundries expand metrology budgets for atomic-scale lattice mapping.
- Rotating Anode Diffractometers:High-brightness X-ray sources with rotating copper or molybdenum anodes deliver intensities five to ten times above sealed-tube designs. Procurement clusters in South Korea's memory fab corridor where Samsung and SK Hynix require rapid throughput for strained superlattice characterization. Supply concentration in Japan and Germany creates single-source vulnerability for these advanced configurations.
- Single-Crystal Diffractometers:Specialized for epitaxial layer orientation and mosaic spread determination in compound semiconductor development.
- Powder Diffractometers:Mature systems serving raw material qualification and phase identification in precursor chemical supply chains.
Volume placements concentrate in Powder Diffractometers for baseline material screening; the faster expansion belongs to Rotating Anode Diffractometers.
Application:
Cost tier stratification separates high-value process development from routine production monitoring, with thin film measurement commanding premium pricing for multilayer stack characterization.
- Thin Film Measurement:Epitaxial thickness determination, composition grading, and superlattice period analysis require specialized rocking curve and reciprocal space mapping capabilities. Taiwan foundry operators deploy these systems extensively for III-V compound semiconductor development. EU Green Deal chemical compliance is forcing coolant system redesigns that extend certification timelines for European installations.
- Quality Control:Automated pass-fail screening of wafer batches against crystallographic specifications dominates high-volume production lines. South Korea memory manufacturers operate multi-vendor suites with unbundled service contracts. After-sales service separation is emerging as procurement departments negotiate standalone calibration packages.
- Material Analysis:Phase identification and lattice parameter refinement support process development and failure investigation workflows.
- Stress Analysis:Residual strain mapping in packaged dies and interconnect structures serves reliability engineering requirements.
Revenue concentration sits with Quality Control for production volume; Thin Film Measurement is climbing the fastest on advanced node complexity.
End User:
Customer type determines specification priorities, with semiconductor manufacturers demanding automation and academic institutes prioritizing experimental flexibility.
- Semiconductor Manufacturers:Foundry and memory producers require high uptime, automated sample handling, and fab-compatible contamination protocols. Taiwan and South Korea clusters drive concentrated procurement of rotating anode systems. Crystallography technician scarcity constrains ramp speeds as specialized epitaxial strain interpretation expertise concentrates among senior metrologists.
- Academic Research Institutes:Universities and national laboratories prioritize configurability for novel materials investigation and method development. Funding cycles and publication timelines shape procurement decisions differently than production economics.
- Material Science Labs:Industrial R&D facilities bridge fundamental research and manufacturing implementation.
- Aerospace Companies:Wide-bandgap semiconductor qualification for radiation-hardened electronics creates specialized requirements.
Procurement volume concentrates in Semiconductor Manufacturers; Academic Research Institutes are gaining share fastest on compound semiconductor research expansion.
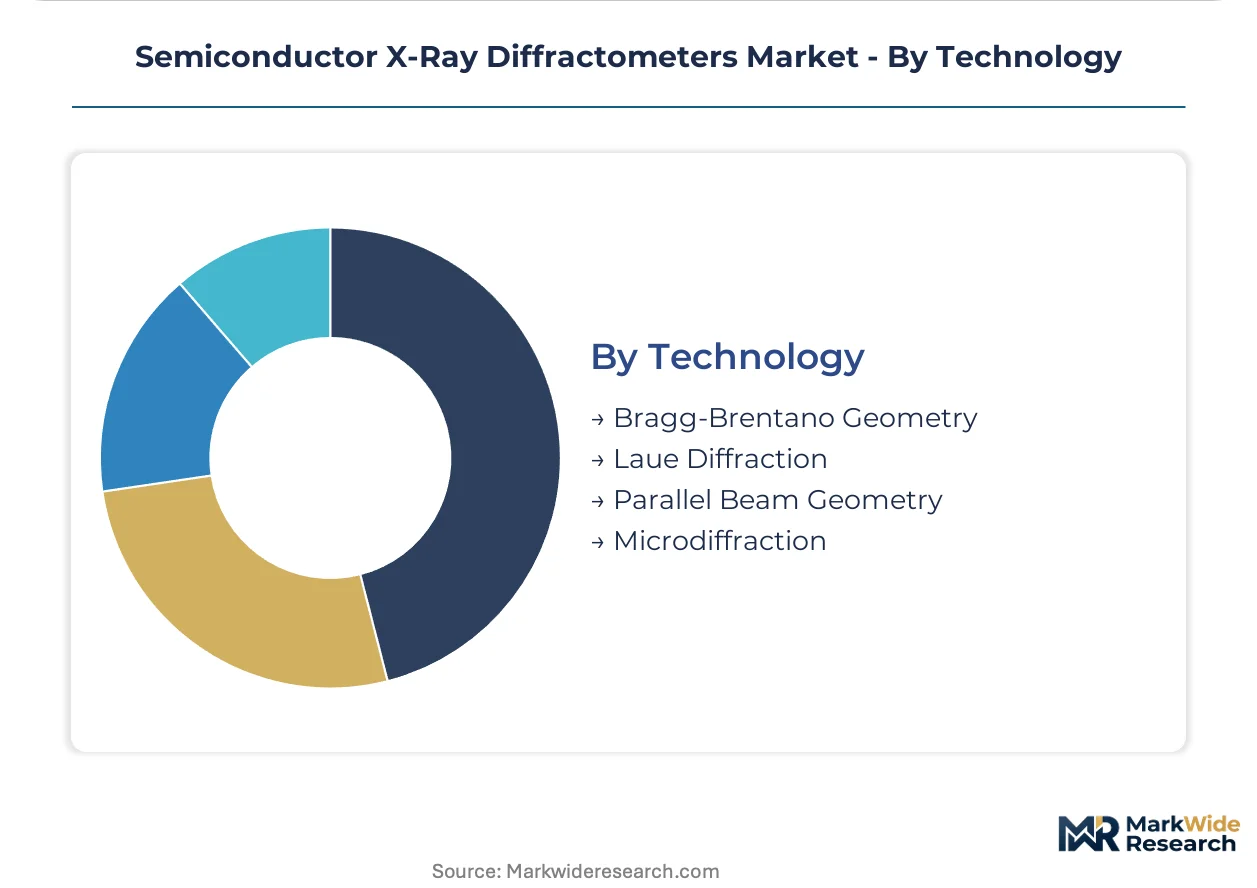
Technology:
Supply concentration in optical component manufacturing shapes competitive positioning across geometry types, with parallel beam architectures displacing traditional divergent beam designs.
- Parallel Beam Geometry:Collimated X-ray paths eliminate defocusing errors for curved samples and enable rapid area mapping. Bruker Corporation anchors position through R&D intensity in this architecture for strained silicon analysis. South Korea memory fab expansion is creating localized demand for these systems optimized for large-diameter wafer handling.
- Microdiffraction:Sub-50 micrometer spot sizes isolate individual interconnect structures and packaged die features. Capabilities are extending into semiconductor assembly and test facilities as new customer segments. Application-specific software bundles reduce operator training burdens in high-turnover foundry environments.
- Bragg-Brentano Geometry:Conventional focusing optics maintain presence in powder diffraction and routine phase identification.
- Laue Diffraction:Back-reflection orientation determination serves single-crystal alignment and ingot slicing preparation.
Install base concentration remains in Bragg-Brentano Geometry; Microdiffraction shows the steepest expansion trajectory on packaged die failure analysis demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment consumption concentrates in East Asian semiconductor manufacturing clusters while production of critical subsystems remains anchored in Japan and Germany. Taiwan and South Korea absorb the majority of high-brightness rotating anode configurations for sub-3nm node development. North American and European facilities face extended certification timelines from divergent radiation safety standards.
Taiwan
Foundry operators at TSMC and UMC are expanding metrology budgets for EUV lithography nodes below 3nm. Taiwan's Industrial Development Bureau enforces semiconductor equipment safety protocols aligned with METI JIS standards for export compatibility. The Hsinchu Science Park corridor drives concentrated procurement of high-resolution systems for silicon-germanium strain analysis.
South Korea
Samsung and SK Hynix capacity additions are creating localized demand for parallel beam geometries optimized for strained silicon characterization. The Korean Agency for Technology and Standards (KATS) certifies industrial X-ray equipment under KC marking requirements. The Yongin and Icheon fab clusters anchor rotating anode system deployments for memory process development.
Japan
METI oversees industrial X-ray equipment certification through JIS standards that shape export specifications for Asian-manufactured systems. Japanese suppliers concentrate high-brightness anode manufacturing for the premium system tier. The Kyoto-Osaka industrial corridor hosts precision optics fabrication for monochromator components.
China
SMIC and Yangtze Memory Technologies operate domestic fabs under NMPA and GB standards compliance pathways. China's dual carbon goals are pressuring equipment vendors to redesign coolant architectures for reduced environmental impact. The Yangtze River Delta and Pearl River Delta clusters are absorbing powder diffractometer volumes for raw material qualification.
United States
EPA radiation safety standards govern X-ray tube construction and end-of-life disposal protocols for equipment deployed in domestic facilities. Intel and GlobalFoundries are upgrading metrology capabilities for advanced node process development. The Southwest fab corridor in Arizona and New Mexico is pulling high-resolution configurations for III-V compound semiconductor research.
Semiconductor X-Ray Diffractometers Market Competitive Landscape
The competitive structure tilts toward diversified analytical instrument conglomerates with heritage in precision optics and detection systems. Market positions stratify across three tiers: heritage Japanese precision manufacturers, diversified European analytical platforms, and North American life sciences conglomerates with materials characterization divisions. Consolidation pressure is intensifying as foundry operators demand bundled software-hardware-service contracts. Technology licensing agreements and application-specific software development partnerships are emerging as dominant competitive moves.
Among heritage Japanese precision manufacturers, Rigaku Corporation and JEOL occupy positions exemplifying rotating anode heritage and electron optics integration respectively. Bruker Corporation anchors the diversified European analytical platform archetype through its R&D intensity in parallel beam geometries. Malvern Panalytical sits within the same tier, differentiating via application-specific software bundles that reduce operator training burdens in foundry environments.
| Leading Market Players |
|---|
| Rigaku Corporation |
| Bruker Corporation |
| Malvern Panalytical |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| Agilent Technologies |
| PerkinElmer |
| Anton Paar |
| JEOL |
| Others |
Pricing and Supply Chain Analysis
Crystallography technician scarcity in Japan and Germany feeds labor-cost differentials that widen pricing-tier spreads between premium rotating anode systems and economy-grade sealed-tube configurations. Buyers in Taiwan's Hsinchu Science Park corridor absorb premium pricing for high-brightness systems while European facilities face extended certification timelines that compress negotiation leverage.
Pricing Analysis
Cost-down pressure on economy-tier sealed-tube systems accelerates because foundry operators in South Korea unbundle after-sales service contracts and negotiate standalone calibration packages. Three-tier pricing structure across premium rotating anode, standard high-resolution, and economy powder diffractometer levels reflects certification grade differentiation under EU REACH and Japan METI JIS standards. Price differentiation traces to angular resolution performance and coolant system compliance architecture. Memory manufacturers in the Yongin and Icheon fab clusters exhibit highest price sensitivity; Taiwan foundry operators at advanced nodes show lowest sensitivity due to yield-critical strain analysis requirements.
Supply Chain Analysis
High-brightness rotating anode manufacturing rests on Japanese and German precision optics producers for monochromator components and specialized anode assemblies. Raw material dependencies include high-purity copper and molybdenum anodes, synthetic single-crystal germanium detectors, and liquid nitrogen coolant infrastructure. Single-source vulnerability concentrates in Japan's Kyoto-Osaka industrial corridor for specialized X-ray tube housings. Distribution runs through direct OEM sales to foundry operators with certified service technician networks, supplemented by regional distributors for academic and industrial R&D accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU REACH chemical restrictions on lead-based shielding materials erect barrier-to-entry moats favoring vendors with retrofit certification capabilities and bismuth-tungsten composite housing expertise.
For Market Incumbents: Cement market position by deepening backward integration into rotating anode manufacturing to offset supply concentration risk in Japan and Germany. Invest in parallel beam geometry R&D to defend against Bruker Corporation's established position in strained silicon analysis. Prioritize application-specific software bundles that reduce crystallography technician training burdens, addressing workforce scarcity constraints on fab ramp speeds. For New Entrants and Emerging Players: The premium-to-economy price-point gap in high-resolution diffractometer configurations creates white-space opportunity for mid-tier entrants offering rotating anode brightness at sealed-tube price positioning. Target academic research institutes in China and India where compound semiconductor research expansion outpaces procurement sophistication. Pursue go-to-market partnerships with regional distributors possessing established service technician networks. For Investors and Strategic Acquirers: Re-rating potential sits with precision optics specialists possessing rotating anode heritage given EU Green Deal chemical compliance timelines extending replacement demand across European install bases. Long-term viability favors vendors with captive supply of high-brightness X-ray sources and software-hardware bundling capabilities. Watch for crystallography technician training program expansion as inflection indicator for foundry operator capacity absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rotating Anode Manufacturing | Reduces single-source dependency on Japanese and German suppliers for high-brightness X-ray sources. |
| REACH-Compliant Housing Redesign | Captures replacement demand across European fabs facing 12-18 month retrofit certification timelines. |
| Application-Specific Software Bundling | Addresses crystallography technician scarcity by reducing operator training burdens in high-turnover foundry environments. |
| Microdiffraction Capability Expansion | Opens semiconductor assembly and test facilities as new customer segments for packaged die failure analysis. |
| Regional Service Technician Certification Programs | Accelerates fab ramp speeds by mitigating specialized epitaxial strain interpretation expertise concentration. |
Research Methodology
Independent corroboration across metrology equipment executives, fab operations directors, and crystallography technicians underwrites the qualitative findings presented in this study. Primary interviews with semiconductor manufacturers in Taiwan and South Korea, precision optics suppliers in Japan, and academic research institute procurement officers were validated against secondary sources including EPA radiation safety filings, METI JIS certification databases, and EU REACH substance restriction updates. Bottom-up equipment shipment tracking and top-down fab capex analysis were triangulated to anchor segmentation estimates.
Rate-of-change decomposition across the analysis window separates volume effects from mix-shift and pricing contributions. The analytical framework models demand by product type (high-resolution, rotating anode, powder, microdiffraction), application (thin film measurement, quality control, material analysis), end user (semiconductor manufacturer, academic institute), and technology geometry (parallel beam, microdiffraction, Bragg-Brentano). CAGRs were derived from install base expansion rates, replacement cycle compression, and node transition timing. Forecast inputs include EUV lithography node roadmaps, foundry metrology budget disclosures, and regional radiation safety standard divergence patterns.
Inputs from equipment vendor shipment disclosures and fab operator procurement announcements were available through the study window; gaps in real-time rotating anode supply chain inventory data introduce uncertainty bands around high-brightness system penetration assumptions. Forecasts reflect documented assumptions regarding technician training pipeline expansion and REACH compliance timeline adherence. Regulatory acceleration in China under NMPA GB standards or tariff disruption in Japan-Germany precision optics trade routes warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Thermogravimetric Analyzer Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Global Electron Microscopes Market