
 Automotive Cabin Air Quality Sensors Market | 2026-2036
Automotive Cabin Air Quality Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cabin Air Quality Sensors Market Analysis
EURO 7 standards is decoupling basic particulate detection from premium cabin air management, forcing suppliers to absorb new certification costs or exit OEM supply chains. Robert Bosch GmbH leverages its MEMS fabrication depth to bundle humidity and VOC detection on single substrates. Sensirion AG sustains Swiss precision positioning in low-drift optical sensing for luxury vehicle programs. DENSO Corporation anchors its advantage through captive integration with Toyota and Lexus climate control modules.
Automotive cabin air quality sensors are electrochemical, optical, MEMS, or metal-oxide devices that detect particulate matter, volatile organic compounds, carbon dioxide, and humidity within vehicle interiors, typically operating across temperature ranges of minus forty to eighty-five degrees Celsius with response times under thirty seconds to protect occupant respiratory health. Gas sensors and VOC sensors command the widest OEM specification sheets as manufacturers consolidate multi-analyte detection behind unified climate controllers. MEMS technology leads unit economics through silicon wafer scalability, while electrochemical architectures retain share in cost-sensitive commercial vehicle configurations where absolute precision matters less than fault tolerance.
FDA maintains indirect influence through indoor air quality guidelines referenced by fleet occupational health contracts, while EPA tailpipe rules cascade into cabin ventilation load calculations that sensor networks must support. EMA and ECHA jointly shape European material restrictions on sensor substrates and bonding agents through REACH and MDR adjacent compliance frameworks. Stakeholders must monitor whether China MIIT extends NEV cabin environment standards to mandate real-time pollutant reporting through vehicle telematics backends.
Market Dynamics
EURO 7 emission standards are compressing development cycles for cabin air quality sensors by mandating real-time multi-pollutant detection that basic particulate counters cannot satisfy, forcing suppliers to redesign optical and electrochemical architectures or surrender OEM contracts to MEMS-integrated competitors.
Growth Catalysts
- EURO 7 cabin purity mandates:European OEMs must deploy VOC and NOx-capable sensors to meet interior air quality thresholds, creating specification pull for multi-analyte detection modules.
- Electric vehicle thermal management:Battery thermal runaway risk requires CO2 and humidity sensors integrated with climate control systems to manage cabin pressurization during rapid charging cycles.
- Silicon wafer scalability:MEMS fabrication economics enable single-substrate consolidation of humidity, particulate, and gas sensing at unit costs compatible with mass-market vehicle programs.
Market Restraints
- Indium tin oxide price volatility:Transparent conductive layers essential for optical sensor electrodes face supply concentration in Chinese smelting operations, compressing margin buffers for European and Japanese suppliers.
- Calibration drift limitations:Metal-oxide semiconductor sensors require recalibration intervals shorter than vehicle service cycles, creating warranty exposure and aftermarket service cost burdens.
- REACH substrate restrictions:ECHA limitations on cadmium and lead in sensor housings force redesign of legacy electrochemical cell geometries, extending qualification timelines by 12-18 months.
Strategic Opportunities
- India NEV cabin standards:BIS is evaluating mandatory air quality monitoring for electric bus and taxi fleets, opening specification windows for suppliers with automotive-grade humidity and CO2 portfolios.
- Telematics backend integration:Real-time pollutant reporting through vehicle connectivity platforms enables subscription-based air quality services, shifting sensor value capture from hardware to data monetization.
- Optical-MEMS convergence:Low-drift photonic sensing combined with silicon microfabrication permits single-package detection of particulate matter, VOCs, and carbon dioxide at luxury and mid-market price points simultaneously.
Industry Challenges
- Automotive functional safety certification:ISO 26262 ASIL compliance for sensors integrated with autonomous vehicle climate systems demands specialized firmware validation capabilities scarce among component suppliers.
- Legacy HVAC controller integration:Proprietary communication protocols from established climate module manufacturers force sensor suppliers to maintain multiple software stacks, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cabin Air Quality Sensors Market |
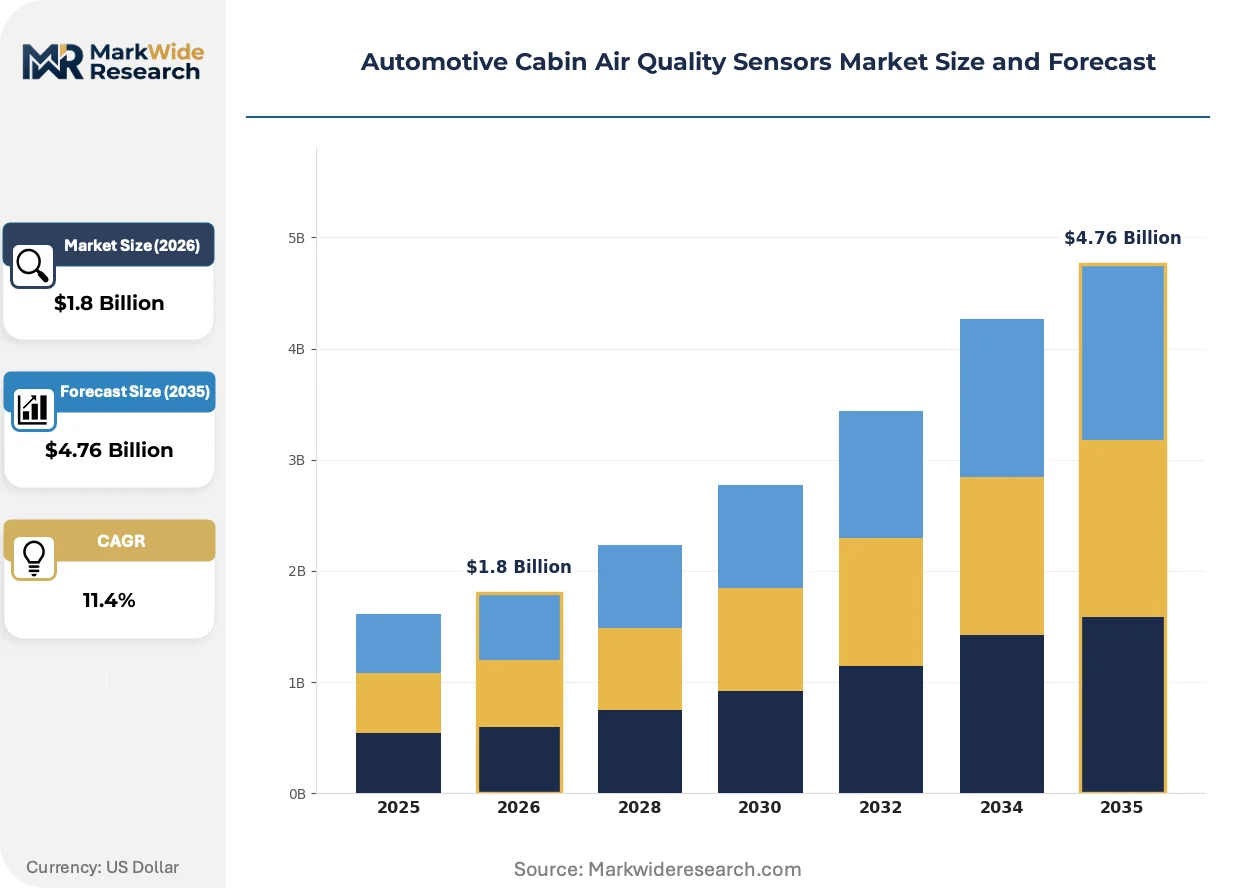
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Particulate Matter Sensors, Gas Sensors, VOC Sensors, Humidity Sensors Technology: Electrochemical, Optical, MEMS, Metal-Oxide End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Electric Vehicles |
| Companies Covered | Honeywell International Inc, DENSO Corporation, Robert Bosch GmbH, Valeo, Sensirion AG, Amphenol Corporation, HELLA GmbH & Co. KGaA, ams OSRAM AG, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cabin Air Quality Sensors Market Emerging Trajectories
Sensor architectures are consolidating from discrete single-analyte modules toward unified climate control inputs, with MEMS and optical technologies converging on common substrates while regulatory mandates accelerate replacement cycles for basic detection technologies.
Photonic interference sensing is electrifying particulate detection by replacing resistive heating elements with laser-based particle counting, reducing power draw by sixty percent. Premium German and Japanese OEMs are specifying these modules for electric vehicle platforms where battery load management is critical. This technology is electrifying competitive positioning by compressing the performance gap between luxury and mid-market sensor configurations.
REACH authorization requirements for sensor substrate materials are tightening bonding agent specifications and accelerating substitution of solvent-based adhesives with UV-cured alternatives. European suppliers face reformulation costs that Asian competitors with newer production lines absorb more readily. Aftermarket sensor replacement demand in Germany and France is concentrating toward certified-compliant modules as independent workshops face liability exposure.
Fleet procurement managers are consolidating sensor specifications across passenger car and commercial vehicle programs, rejecting supplier-proprietary designs in favor of open-architecture modules compatible with multiple climate controller brands. This standardization push is compressing margins for integrated specialists while expanding addressable market for modular sensor suppliers. The United States and South Korea exhibit the most aggressive fleet standardization, with municipal procurement leading specification convergence.
Automotive Cabin Air Quality Sensors Market Segmentation
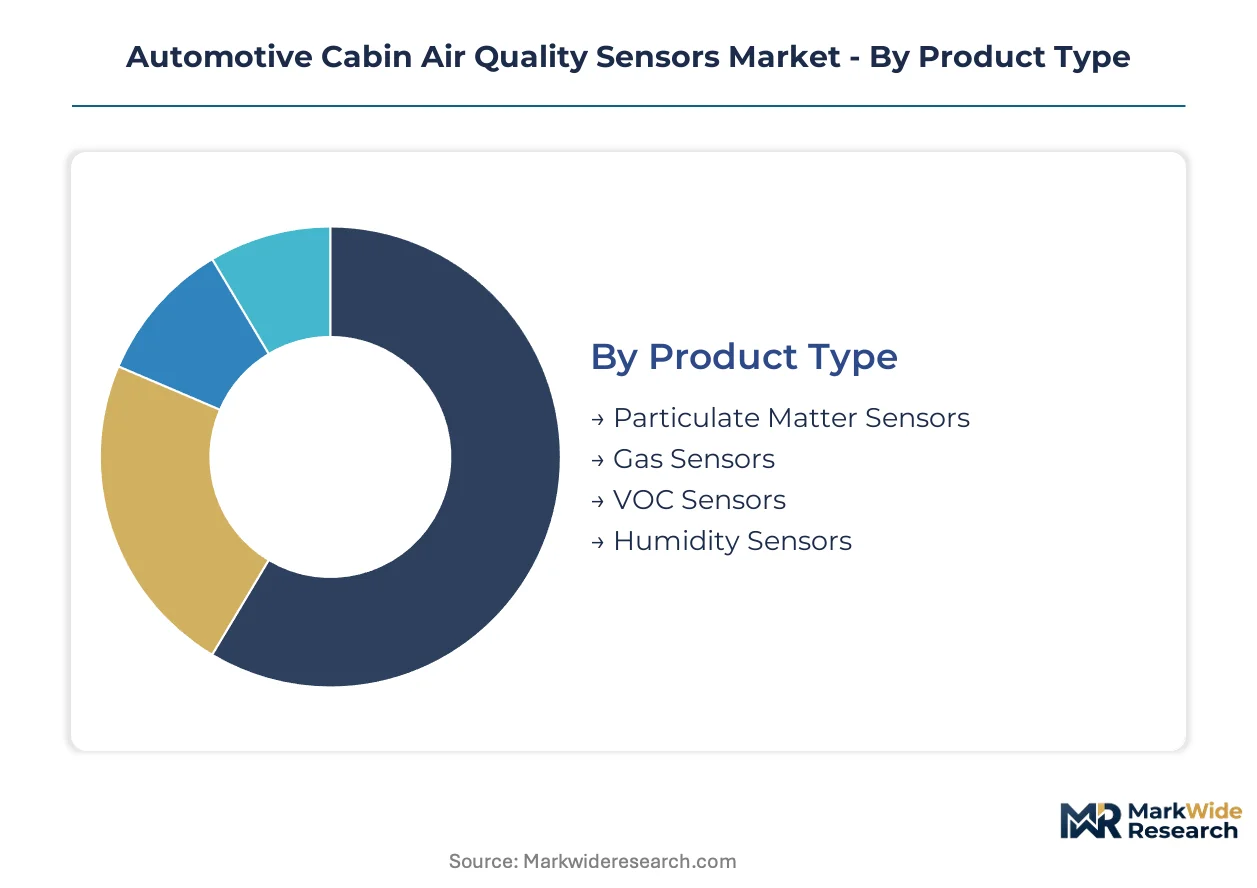
Automotive cabin air quality sensors fragment across four intersecting dimensions that determine pricing power and qualification barriers. Product type and technology choices lock suppliers into specific OEM approval cycles, while end-user concentration and application requirements dictate volume scale and margin structure.
Product Type:
Volume concentration sits with multi-analyte modules, while premium positioning attaches to specialized detection for luxury climate systems.
- Gas Sensors:Electrochemical and optical architectures detect CO2, NOx, and oxygen levels with precision meeting Euro 7 interior thresholds. German and Japanese OEMs specify these for unified climate controllers in premium electric vehicle programs where cabin pressurization management is critical.
- VOC Sensors:Metal-oxide and optical technologies identify formaldehyde, benzene, and toluene concentrations at parts-per-billion sensitivity. Demand concentrates in California and EU member states with stringent interior air quality mandates for fleet occupational health contracts.
- Particulate Matter Sensors:Optical scattering modules measure PM2.5 and PM10 concentrations for basic filtration feedback.
- Humidity Sensors:MEMS capacitive elements monitor relative humidity to prevent windshield fogging and optimize HVAC efficiency.
Today's leader: Gas Sensors. Tomorrow's challenger: VOC Sensors.
Technology:
Cost tier separation runs deepest here, with silicon scalability at the low end and precision photonics commanding qualification premiums.
- MEMS:Silicon microfabrication enables single-substrate integration of humidity, temperature, and gas sensing at unit economics compatible with mass-market vehicle programs. Toyota and Hyundai specify MEMS modules for high-volume climate control standardization.
- Optical:Laser-based photonic interference and infrared absorption deliver low-drift multi-pollutant detection for luxury OEMs. BMW and Mercedes-Benz programs require optical architectures for VOC and particulate discrimination at sub-30-second response times.
- Electrochemical:Amperometric cells provide absolute precision for commercial vehicle safety-critical applications.
- Metal-Oxide:Semiconductor films offer cost-sensitive VOC detection with shorter calibration intervals.
MEMS commands current volume. Optical architectures are climbing the fastest as electric vehicle thermal management demands intensify.
End User:
Procurement authority determines specification control, with captive integration favoring climate module specialists and open architecture benefiting independent sensor suppliers.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and General Motors direct sensor specifications through proprietary climate controller partnerships, locking suppliers into multi-year program commitments with ASIL-compliant firmware requirements.
- Fleet Operators:Municipal procurement departments in the United States and South Korea consolidate specifications across passenger and commercial vehicle programs, rejecting proprietary designs in favor of modular open-architecture sensors compatible with multiple HVAC brands.
- Aftermarket Providers:Independent workshops in Germany and France face REACH liability exposure, concentrating demand toward certified-compliant replacement modules.
- Vehicle Assemblers:Contract manufacturers in emerging markets source basic particulate detection for cost-optimized vehicle configurations.
OEMs retain specification authority today. Fleet operators are gaining procurement leverage fastest through consolidated tender processes.
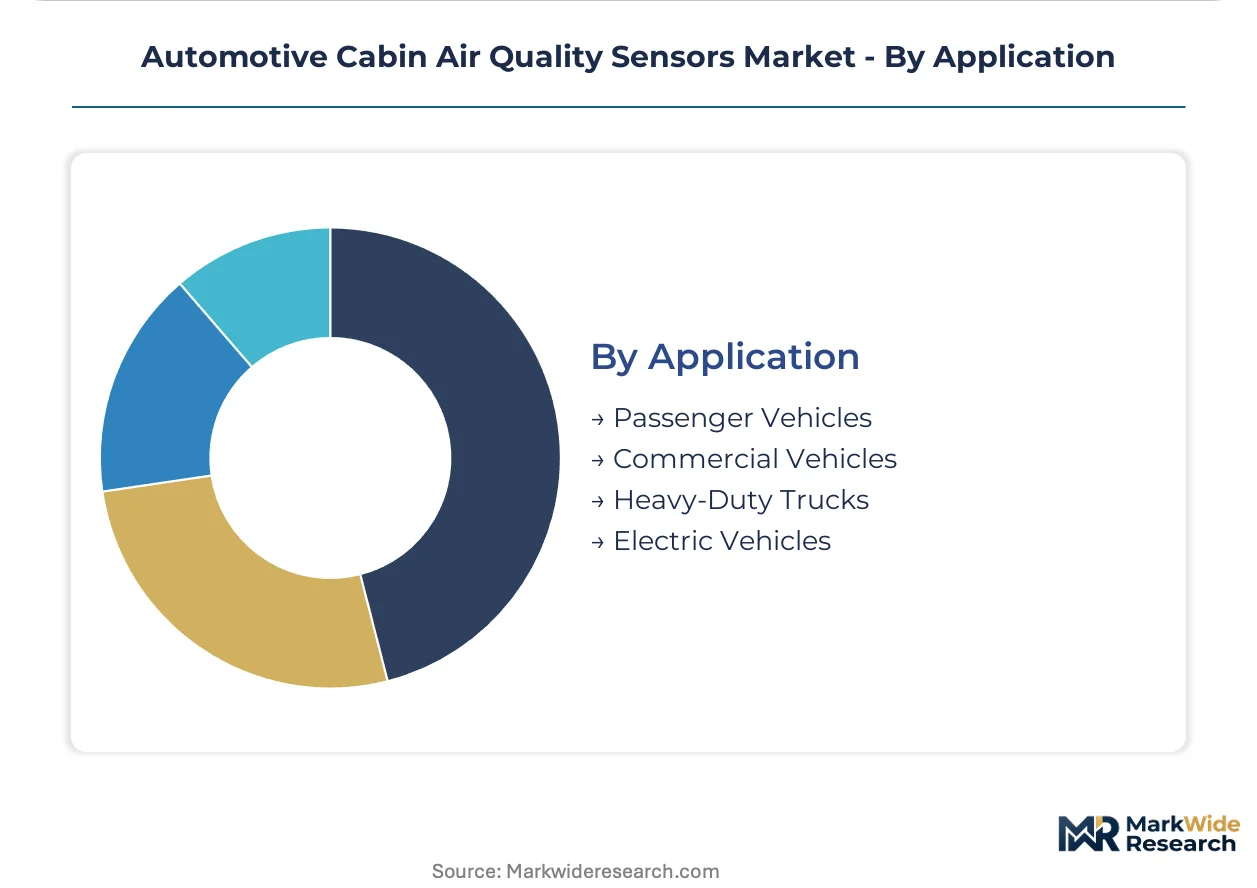
Application:
Maturity differentiation separates established internal combustion platforms from emerging electric vehicle requirements with fundamentally different sensor loads.
- Electric Vehicles:Battery thermal runaway protocols demand CO2, humidity, and VOC sensing integrated with rapid-charge cabin pressurization systems. Tesla, BYD, and Hyundai specifications are displacing basic particulate modules with multi-analyte suites.
- Passenger Vehicles:Premium German and Japanese OEMs standardize advanced filtration with real-time pollutant reporting through telematics backends.
- Commercial Vehicles:Fleet occupational health contracts reference FDA indoor air quality guidelines for driver cabin specifications.
- Heavy-Duty Trucks:Long-haul operator fatigue management drives humidity and CO2 monitoring for sleeper cab configurations.
Passenger vehicles dominate current volumes. Electric vehicles represent the steepest expansion trajectory as NEV cabin standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Nagoya, and Detroit anchor sensor development for automotive applications. These concentrations feed directly into OEM climate control engineering centers. Regulatory pressure from multiple jurisdictions shapes where qualification investments flow.
Germany
Premium OEM engineering centers in Munich and Stuttgart drive multi-pollutant sensor specifications for Euro 7 compliance. KBA enforcement of cabin air purity thresholds forces suppliers to maintain ASIL-certified firmware capabilities. Baden-Württemberg hosts Bosch and Valeo development facilities where MEMS and optical architectures converge.
United States
EPA tailpipe rules cascade into cabin ventilation load calculations that sensor networks must support for domestic OEM programs. Michigan-based climate control engineering teams specify modules compatible with telematics backend integration. California Air Resources Board interior air quality guidelines create specification pull for VOC-capable sensors in fleet contracts.
Japan
Toyota and Lexus climate control standardization drives captive integration demand through DENSO's Nagoya engineering base. METI NEV cabin environment guidelines shape sensor loads for battery thermal management applications. Kansai region suppliers concentrate on humidity and CO2 sensing for rapid-charge pressurization protocols.
China
MIIT evaluates extending NEV cabin standards to mandate real-time pollutant reporting through vehicle telematics backends. Yangtze River Delta clusters supply BYD and Tesla Gigafactory Shanghai with multi-analyte sensing suites. Shanghai and Shenzhen engineering centers focus on cost-optimized MEMS fabrication for mass-market electric vehicle programs.
South Korea
Hyundai Motor Group specifications drive MEMS module standardization across high-volume climate control platforms. MFDS-referenced occupational health contracts for commercial fleets create demand for certified-compliant replacement sensors. Busan-Ulsan manufacturing corridors concentrate sensor assembly operations serving domestic and export OEM programs.
Automotive Cabin Air Quality Sensors Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive automotive relationships. German and Japanese suppliers leverage climate control integration partnerships to lock in multi-year OEM commitments. Three archetypes dominate: MEMS fabrication specialists, optical sensing precision players, and diversified tier-one suppliers with HVAC controller captive integration. Consolidation pressure intensifies through ASIL compliance requirements and Euro 7 qualification costs that fragment smaller participants.
Among diversified industrial technology groups, Robert Bosch GmbH and DENSO Corporation exemplify the integrated tier-one archetype through climate control module standardization. Sensirion AG occupies a precision positioning within optical sensing for luxury vehicle programs. Honeywell International Inc and Amphenol Corporation represent North American diversified electronics manufacturers with automotive sensor portfolios. Valeo and HELLA GmbH & Co. KGaA sit within the European climate system integration tier.
| Leading Market Players |
|---|
| Honeywell International Inc |
| DENSO Corporation |
| Robert Bosch GmbH |
| Valeo |
| Sensirion AG |
| Amphenol Corporation |
| HELLA GmbH & Co. KGaA |
| ams OSRAM AG |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
MEMS fabrication engineers concentrated in Stuttgart and Nagoya command wage premiums that compress margin buffers for European and Japanese suppliers, widening the spread between mass-market MEMS modules and precision optical sensors calibrated for luxury OEM programs.
Pricing Analysis
Bundled climate-controller integration versus unbundled standalone sensor procurement splits pricing architectures sharply. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-certified optical suites for German luxury EVs from basic particulate modules for emerging-market vehicle assemblers. Price differentiation rests on certification grade and firmware validation depth. Pricing pressure stems from Chinese MEMS foundries absorbing REACH reformulation costs more readily than European competitors. Fleet operators exhibit highest price sensitivity, while captive OEM partnerships show lowest.
Supply Chain Analysis
Warehouse-distribution layer concentration around Stuttgart, Nagoya, and Detroit regional distribution centers feeds directly into OEM climate control engineering centers with hub-and-spoke replenishment patterns. Silicon wafer supply concentrates in Taiwan, South Korea, and Japan. Indium tin oxide for optical sensor electrodes and MEMS substrate materials draw from Chinese smelting operations. Single-source vulnerability in transparent conductive layer supply compresses margin buffers. Distribution runs through tier-one climate module manufacturers with proprietary protocol integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as Euro 7 mandates displace basic particulate detection with multi-pollutant sensing suites that command specification premiums.
For Market Incumbents: Deploy backward integration into MEMS foundry capacity to capture silicon wafer scalability economics before Chinese competitors consolidate mass-market supply. Lock in multi-year ASIL-certified firmware development partnerships with German and Japanese OEMs to raise qualification barriers against modular entrants. Climate controller captive integration represents the primary defensive moat under pressure from fleet procurement standardization. For New Entrants and Emerging Players: Photonic interference sensing combined with silicon microfabrication offers entry into mid-market electric vehicle programs where laser-based particle counting displaces resistive heating modules. Target India's emerging NEV cabin standards for electric bus and taxi fleets before specification windows close. Pursue open-architecture modular positioning compatible with multiple HVAC controller brands rather than proprietary integration. For Investors and Strategic Acquirers: Valuations sit cheapest among European electrochemical specialists facing REACH substrate reformulation costs and extended qualification timelines. Five-to-ten-year viability hinges on successful MEMS-optical convergence execution rather than legacy metal-oxide retention. Watch for MIIT mandates on real-time pollutant telematics reporting as inflection signal for data-monetization revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS-Optical Convergence R&D | Single-substrate integration of humidity, VOC, and particulate sensing compresses unit costs for mid-market EV programs. |
| ASIL-Certified Firmware Investment | ISO 26262 compliance capabilities lock suppliers into multi-year German and Japanese OEM climate controller partnerships. |
| Telematics Backend Integration | Real-time pollutant data monetization shifts value capture from hardware sales to subscription services for fleet operators. |
| REACH-Compliant Material Reformulation | UV-cured adhesive substitution for solvent-based bonding agents accelerates European supplier qualification timelines. |
| India NEV Specification Entry | BIS-mandated cabin air monitoring for electric bus and taxi fleets opens addressable market before competitors consolidate. |
Methodological Framework
Multiple input streams — OEM platform engineering directors, tier-one climate controller procurement leads, aftermarket distribution channel managers, and sensor component R&D heads — were reconciled against secondary validation from vehicle production databases, IHS Markit registration data, EPA tailpipe rule filings, and ECHA REACH authorization updates. Bottom-up unit shipment estimates triangulated with top-down OEM program content analysis across propulsion architectures and vehicle classes.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmentation modeling across product type, technology architecture, end-user procurement authority, and application requirements including battery thermal management protocols. CAGRs derived from fitted growth curves applied to OEM program ramp schedules and regulatory mandate phase-in timelines. Electric vehicle platform sensor load intensification and Euro 7 cabin purity thresholds served as primary demand-side forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT telematics mandate timing, indium tin oxide supply concentration disruptions, and fleet procurement standardization velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Meteorological Devices Market