
 Thin Film Transistors (TFT) Market | 2026-2036
Thin Film Transistors (TFT) Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Transistors (TFT) Market Analytics
The EU F-Gas Regulation is pivoting manufacturing cost structures for European-bound TFT panels. BOE Technology Group Co., Ltd leverages its Gen 10.5 fab network to dominate large-area LCD supply. Samsung Electronics anchors premium AMOLED capacity for smartphones and tablets. AU Optronics Corp. specializes in high-refresh-rate gaming and automotive panels, differentiating through niche application focus.
Thin Film Transistors are semiconductor devices built on glass or flexible substrates using amorphous silicon, low-temperature polysilicon, or metal oxide semiconductors such as IGZO, enabling precise pixel control in flat-panel displays. Their primary purpose is to drive individual pixels in active-matrix displays for consumer electronics, automotive instrumentation, and medical imaging systems. LCD and TFT-LCD segments retain volume leadership in industrial and cost-sensitive applications, while AMOLED commands premium margins in smartphones and wearables. Flexible displays represent the fastest-expanding structural category as foldable handset designs proliferate and automotive interior surfaces adopt conformable screen architectures.
The EPA enforces hazardous substance rules affecting TFT manufacturing effluent in the United States, while REACH governs chemical disclosure and restriction across European supply chains. China's MIIT sets domestic display industry standards and subsidizes advanced panel capacity through national industrial policy. Japan's METI coordinates next-generation display R&D consortia targeting microLED and quantum-dot integration. Stakeholders must monitor how divergent chemical compliance regimes reshape supplier qualification timelines and regional cost competitiveness.
Market Dynamics
Automotive OEMs are forcing a structural pivot in TFT substrate specifications as curved instrument clusters and head-up displays displace flat panels, compressing legacy LCD qualification timelines while elevating flexible OLED and metal oxide backplane requirements.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating capital redeployment toward low-temperature polysilicon and IGZO process lines, tightening supply discipline for European-bound panels.
- Foldable handset proliferation:Samsung Electronics and Chinese OEMs are scaling UTG-covered flexible AMOLED volumes, pulling LTPO backplane capacity expansion across South Korean and Chinese fabs.
- Medical imaging digitization:Diagnostic display replacement cycles are shortening as radiology departments adopt higher-resolution TFT-LCD and AMOLED modalities for PACS workstations.
Market Restraints
- Indium supply concentration:IGZO semiconductor manufacturing depends on Chinese indium refining capacity, exposing metal oxide TFT producers to export control volatility and price swings.
- Amorphous silicon technical ceiling:Electron mobility limitations below 1 cm²/V·s block a-Si from high-refresh-rate automotive and gaming applications, segmenting the technology to cost-driven industrial displays.
- REACH chemical disclosure:European supply chains face extended qualification timelines for photoresist and etchant formulations, inflating compliance costs for panel imports.
Strategic Opportunities
- MicroLED transfer integration:Convergence of mass transfer equipment with existing TFT backplane infrastructure offers fabs a path to next-generation display architecture without greenfield construction.
- India PLI scheme:Display manufacturing incentives under the country's production-linked incentive framework are attracting module assembly investments, creating an alternative supply node to East Asian concentration.
- Automotive surface conformability:Interior designers are specifying free-form displays for pillar-to-pillar integration, opening white space for laser-lift-off flexible OLED and molded LCD technologies.
Industry Challenges
- LTPO process engineering talent:Low-temperature polycrystalline oxide fabrication requires specialized equipment tuning and defect management expertise that remains concentrated among South Korean and Japanese engineering teams.
- Gen 10.5+ equipment lead times:Vacuum deposition and photolithography tools for large-area substrate processing carry 18-24 month delivery cycles, constraining capacity response to demand spikes.
- Dual certification burden:Automotive panels must simultaneously satisfy AEC-Q100 reliability standards and OEM-specific optical performance protocols, elongating product validation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Transistors (TFT) Market |
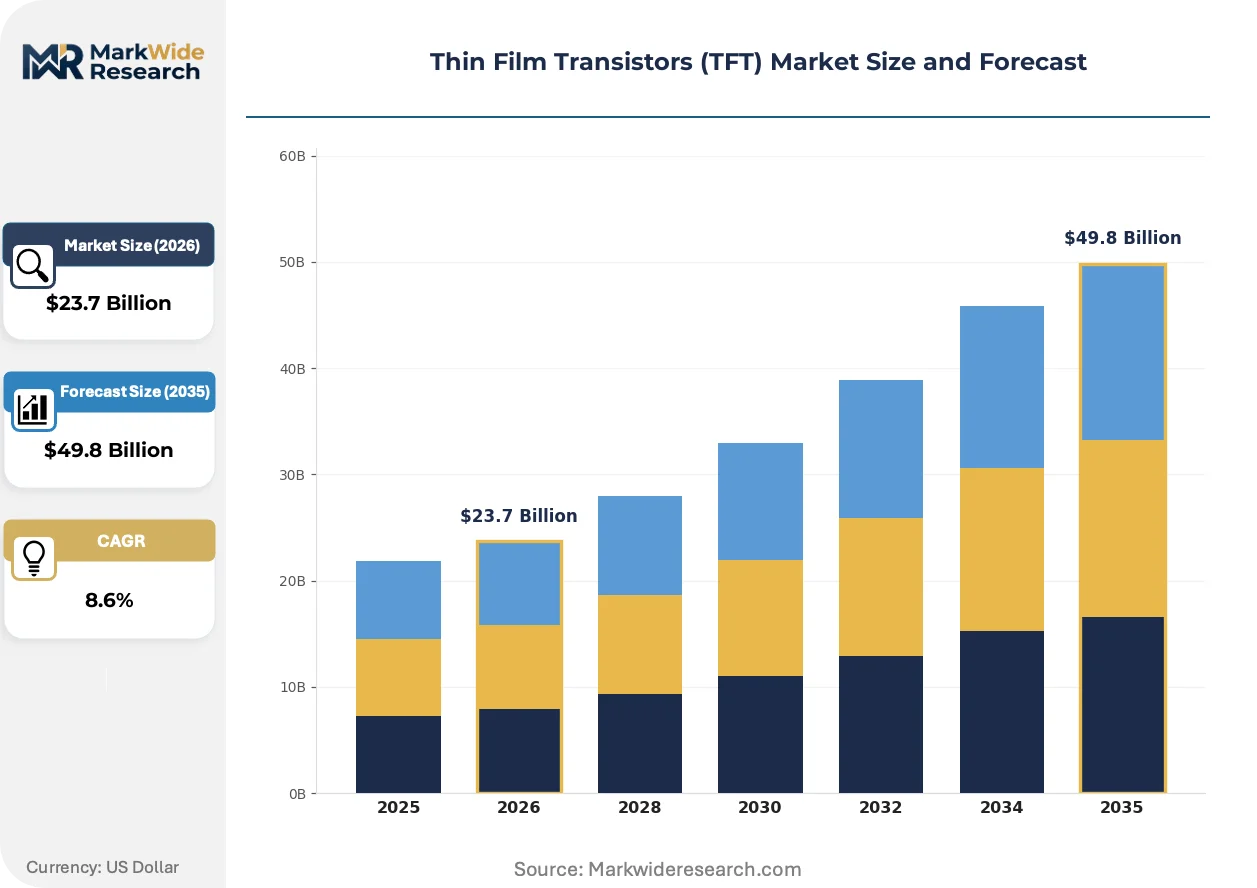
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AMOLED, LCD, TFT-LCD, Flexible Displays End User: Consumer Electronics, Automotive, Healthcare, Industrial Applications Technology: Transparent, Organic, Inorganic, Hybrid Application: Smartphones, Tablets, Laptops, Wearables |
| Companies Covered | LG Display Co., Ltd, Samsung Electronics, AU Optronics Corp., BOE Technology Group Co., Ltd, Innolux Corporation, Sharp Corporation, Panasonic Corporation, Sony Corporation, Japan Display Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Transistors (TFT) Market Evolving Landscape
Metal oxide semiconductor backplanes are compressing the performance gap between amorphous silicon cost structures and LTPS mobility, enabling a unified manufacturing platform across smartphone, tablet, and automotive display segments.
IGZO is unifying previously segmented backplane requirements by delivering electron mobility above 10 cm²/V·s at processing temperatures compatible with Gen 8.5+ glass substrates. Panel makers are adopting IGZO for laptop and tablet lines previously split between a-Si and LTPS, consolidating equipment footprints and reducing mask count. This unification is compressing capital intensity per square meter of display area while extending refresh-rate capabilities into gaming monitor segments.
REACH chemical restriction lists are forcing reformulation of photoresist strippers and wet etchants used in TFT patterning, raising input costs for European-bound production. Manufacturers are qualifying aqueous-based alternatives and closed-loop solvent recovery systems to maintain market access. Medical and automotive display segments face the steepest compliance cost escalation given their stringent contamination limits and traceability requirements.
Procurement consolidation among top-five smartphone OEMs is compressing panel supplier margins and accelerating direct fab investment strategies. Apple and Samsung are deepening captive supply arrangements through exclusive capacity reservations and equipment co-investment, displacing spot-market transactions. This concentration is most visible in South Korea and China, where display makers are accepting lower unit economics to secure volume commitments from anchor customers.
Thin Film Transistors (TFT) Market Segmentation
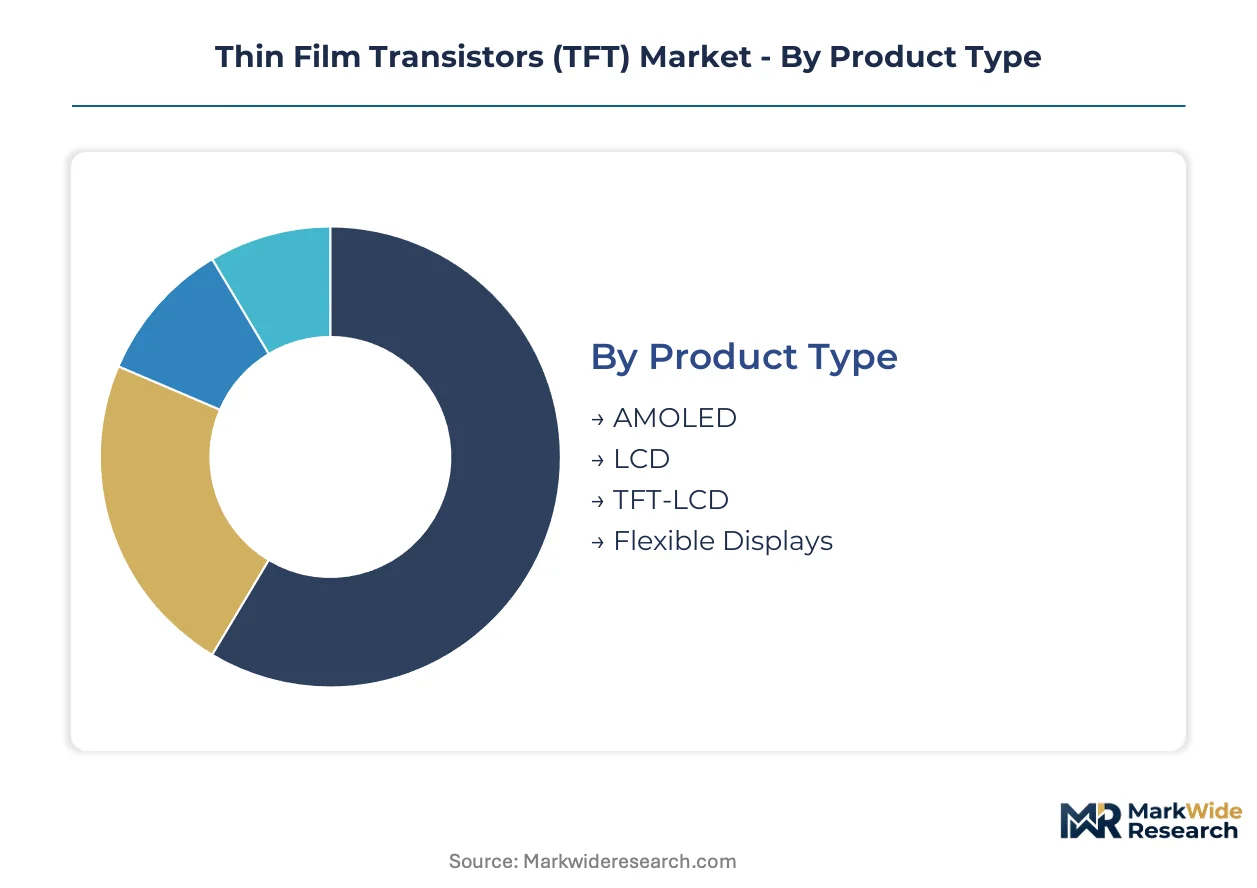
TFT technology selection directly determines upgrade feasibility across display replacement cycles. Panel makers align product roadmaps with end-user refresh timelines to optimize fab utilization and minimize stranded capacity.
Product Type:
Replacement cycle compression varies sharply across display technologies, with premium segments shortening intervals while industrial applications extend depreciation schedules.
- AMOLED:Self-emissive pixel architecture eliminates backlight assembly, enabling sub-2mm panel thickness for flagship smartphones. Samsung Electronics and LG Display anchor capacity expansion in South Korea as Chinese fabs qualify LTPO backplanes for foldable handset integration.
- LCD:Mature a-Si and IGZO backplane infrastructure supports cost-optimized production for commercial monitors and industrial instrumentation. BOE Technology dominates Gen 10.5 substrate throughput, capturing volume share in education and enterprise display procurement.
- TFT-LCD:Active-matrix addressing delivers precise voltage control for high-resolution medical imaging and automotive cluster applications.
- Flexible Displays:Polyimide substrate laser-lift-off processing enables conformable screen architectures for curved automotive surfaces and foldable consumer devices.
LCD sits at the top of the volume ranking, with Flexible Displays climbing the fastest.
End User:
Customer procurement patterns stratify across cost tier, with premium segments demanding customized optical specifications and economy buyers prioritizing unit cost minimization.
- Consumer Electronics:Smartphone OEMs drive specification escalation through annual refresh cycles, pulling higher-refresh-rate and lower-power backplane technologies into mainstream adoption. Chinese and South Korean handset brands concentrate procurement among captive panel suppliers, compressing spot-market liquidity.
- Automotive:Curved instrument clusters and pillar-to-pillar display integration are displacing flat panel architectures, elevating flexible OLED and free-form LCD qualification priorities. Dual AEC-Q100 and OEM-specific certification requirements elongate supplier onboarding timelines.
- Healthcare:Diagnostic imaging workstations demand calibrated color accuracy and luminance stability for radiology PACS compliance.
- Industrial Applications:Extended operating temperature ranges and sunlight readability specifications dominate procurement criteria for outdoor signage and factory automation.
Consumer Electronics commands the largest revenue base, while Automotive is expanding most quickly.
Technology:
Backplane semiconductor selection determines electron mobility thresholds and processing temperature compatibility, directly constraining substrate material options and manufacturing capital intensity.
- Transparent:Oxide semiconductor formulations with wide bandgap properties enable visible-light transmission for heads-up display and smart window applications. Research consortia in Japan and South Korea are advancing deposition uniformity across Gen 6+ substrate formats.
- Organic:Solution-processable semiconductor layers offer roll-to-roll manufacturing potential for low-cost flexible electronics, though carrier mobility limitations restrict application to low-frequency switching circuits.
- Inorganic:Crystalline silicon and metal oxide compositions deliver established reliability records for high-volume display production.
- Hybrid:Stacked organic-inorganic architectures attempt to merge solution processing economics with inorganic charge transport performance.
Inorganic technology retains volume leadership, with Transparent gaining share fastest in emerging display form factors.
Application:
Device form factor dictates pixel density requirements, diagonal dimension ranges, and power consumption constraints that backplane technology must satisfy.
- Smartphones:Sub-7-inch diagonal specifications prioritize extreme pixel density above 500 ppi and variable refresh rate adaptation for battery optimization. LTPO backplane penetration is accelerating across flagship tier handsets from Samsung, Apple, and Chinese OEMs.
- Tablets:Mid-size diagonal ranges balance portability with productivity use cases, favoring LCD cost structures for education and enterprise volume segments while premium consumer lines adopt OLED for contrast ratio differentiation.
- Laptops:Mini-LED backlighting and oxide backplanes are displacing traditional a-Si architectures for high-refresh-rate gaming and creator-oriented panel specifications.
- Wearables:Ultra-low-power operation and circular or irregular form factors drive specialized backplane design for smartwatch and fitness tracker integration.
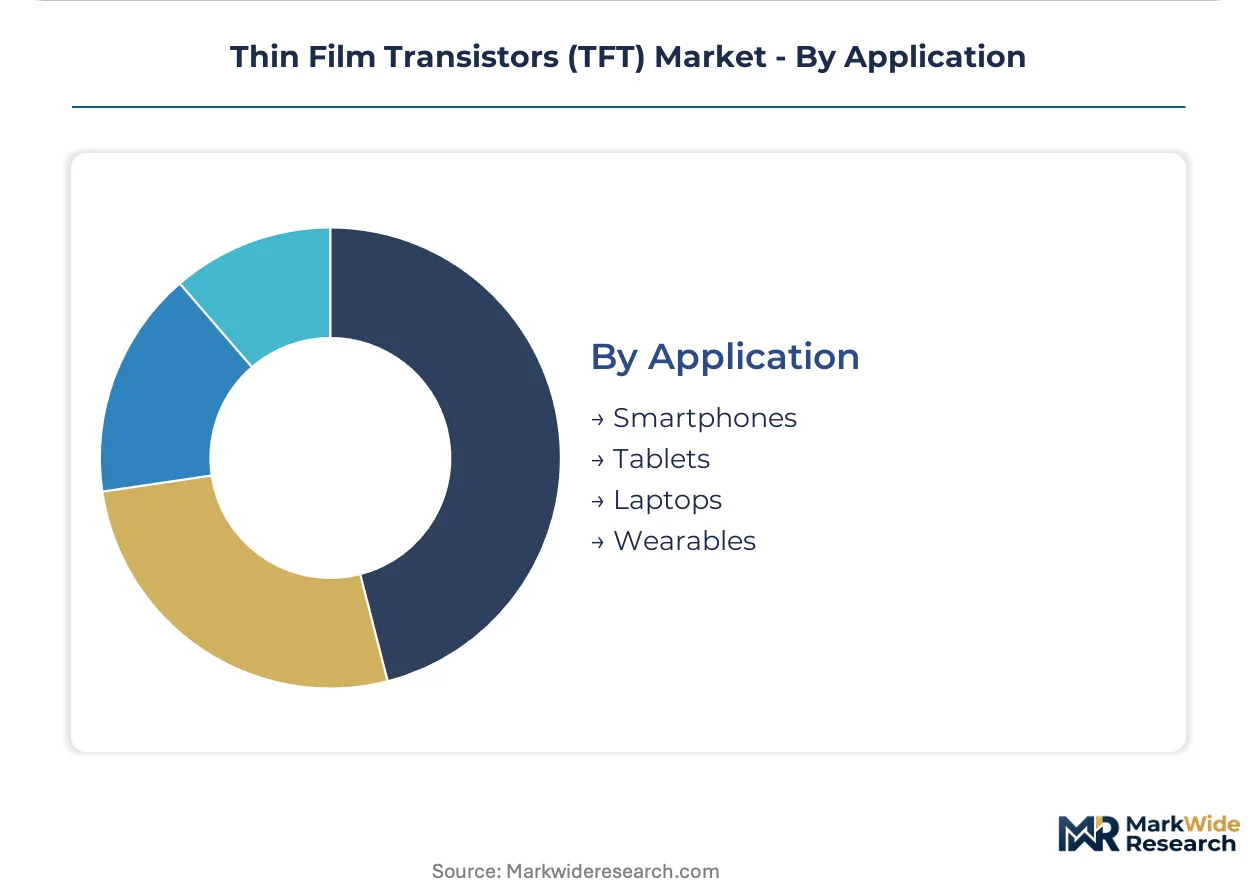
Smartphones maintains the highest unit volume position, with Wearables showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process engineering talent concentrates in South Korean and Japanese fabrication clusters, anchoring advanced backplane development for mobile and automotive displays.
South Korea
LTPO backplane expertise and UTG flexible OLED capacity expansion drive display investment around Seoul and Gyeonggi Province. The Ministry of Trade, Industry and Energy coordinates national R&D consortia targeting next-generation microLED transfer technologies. Samsung Electronics and LG Display anchor large-area substrate processing in the Seoul Capital Area, pulling equipment suppliers and specialty chemical vendors into dense supplier networks.
China
Gen 10.5+ substrate throughput and indium refining capacity support cost-competitive LCD and IGZO metal oxide production. MIIT subsidizes advanced panel capacity through national industrial policy directives. BOE Technology dominates substrate glass processing in the Yangtze River Delta and Pearl River Delta regions, capturing volume procurement from education and enterprise display buyers.
Japan
Deposition equipment manufacturing and semiconductor materials expertise sustain backplane technology leadership. METI coordinates display industry R&D targeting quantum-dot integration and microLED mass transfer. Sharp Corporation and Japan Display Inc. maintain fabrication presence in Chubu and Kansai regions, specializing in high-reliability automotive and medical imaging panels.
Germany
Automotive OEM demand for curved instrument clusters and head-up displays elevates flexible OLED qualification priorities. The EU F-Gas Regulation tightens fluorinated greenhouse gas phase-down mandates for European-bound panel production. Industrial clusters in Bavaria and Baden-Württemberg host precision optics and deposition equipment suppliers serving display backplane manufacturers.
United States
Medical imaging digitization and diagnostic display replacement cycles pull high-resolution TFT-LCD and AMOLED procurement. EPA hazardous substance rules govern manufacturing effluent from domestic fabrication and module assembly operations. Equipment vendors and specialty materials distributors concentrate in Greater Boston and Silicon Valley, supporting captive R&D operations of major consumer electronics brands.
Thin Film Transistors (TFT) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate size and application segments. The vendor base stratifies into three tiers: integrated electronics conglomerates with captive display divisions, independent panel specialists serving multiple OEMs, and equipment or materials suppliers with backward integration into backplane processing. Strategic moves center on exclusive capacity reservation agreements and co-investment in next-generation deposition tools.
Among East Asian panel fabricators, LG Display Co., Ltd, Samsung Electronics, and BOE Technology Group Co., Ltd exemplify scale-driven competitive positioning. LG Display Co., Ltd represents the diversified conglomerate archetype with integrated materials and finished panel operations. Samsung Electronics occupies a position bridging captive supply for affiliated handset divisions and merchant market sales. BOE Technology Group Co., Ltd anchors the Chinese state-supported capacity expansion model, leveraging domestic substrate glass and indium supply chain proximity.
| Leading Market Players |
|---|
| LG Display Co., Ltd |
| Samsung Electronics |
| AU Optronics Corp. |
| BOE Technology Group Co., Ltd |
| Innolux Corporation |
| Sharp Corporation |
| Panasonic Corporation |
| Sony Corporation |
| Japan Display Inc. |
| Others |
Value Network & Pricing Analysis
Indium spot price volatility cascades through TFT backplane manufacturing cost structures, compressing margins for IGZO metal oxide producers while amplifying pricing power for South Korean and Chinese fabs with captive indium refining arrangements.
Pricing Analysis
Backplane technology selection splits the TFT panel market into bundled process-service packages and unbundled component transactions. A three-tier pricing structure across premium, standard, and economy levels stratifies by electron mobility performance and automotive certification grade. Pricing pressure stems from procurement consolidation among top-five smartphone OEMs demanding exclusive capacity reservations. Economy-tier LCD panel buyers exhibit highest price sensitivity, while automotive OEMs absorbing AEC-Q100 certification premiums show lowest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Apple and Samsung Electronics, while merchant spot markets serve secondary handset brands and industrial display purchasers. Supply concentrates in South Korea, China, and Japan, with substrate glass and deposition equipment feeding from specialized industrial clusters. Raw material dependencies center on indium metal, high-purity silicon precursors, and photoresist formulations. Single-source vulnerability in EUV photolithography tools creates supply chain risk. Distribution runs through captive fab networks for premium tiers and open-market brokers for legacy LCD segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TFT market reads as a late-cycle quality story, with automotive curved display specifications and foldable handset architectures pulling premium backplane technologies into mainstream procurement.
For Market Incumbents: Deepen LTPO process engineering capabilities to defend against Chinese IGZO cost incursions. Lock in exclusive indium supply agreements before export control volatility escalates. Expand Gen 10.5+ capacity in the Yangtze River Delta to capture education and enterprise display procurement consolidation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in automotive flexible OLED panels offers white-space entry for specialized backplane foundries. Target India PLI scheme incentives for module assembly investments. Pursue medical imaging display niches with shorter certification timelines than automotive AEC-Q100 protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with oxide semiconductor deposition equipment specialists serving the IGZO unification trend. Long-term viability favors vendors with process expertise transferable to microLED backplane integration. Watch for LTPO yield rate inflections at Chinese fabs as signal of competitive parity achievement.| Strategic Initiative | Industry Significance |
|---|---|
| LTPO Backplane Capacity Expansion | Samsung Electronics and LG Display anchor South Korean investment to capture foldable handset specification escalation. |
| IGZO Process Line Conversion | BOE Technology consolidates laptop and tablet manufacturing footprints under unified metal oxide semiconductor platforms. |
| Automotive Flexible OLED Qualification | Free-form display architectures for pillar-to-pillar integration open new content-per-vehicle expansion vectors. |
| MicroLED Transfer Equipment Co-Investment | Mass transfer tool development offers fabs next-generation display architecture without greenfield construction requirements. |
| India PLI Module Assembly Investment | Production-linked incentive schemes attract display module operations to diversify beyond East Asian concentration. |
Research Methodology
Bottom-up display application modeling reconciled against top-down fab capacity tracking forms the analytical core of this study. Primary interviews with deposition equipment engineers, panel procurement managers at smartphone OEMs, automotive display specification leads, and specialty chemical formulators combined with secondary validation from SEC filings, MIIT capacity disclosures, and customs trade data. Top-down triangulation against industry association shipment reports ensures demand-side calibration.
Input-output matrices map backplane technology selection to end-use volume requirements across the projection horizon. Segmentation dimensions include product type, end user industry, semiconductor technology, and application form factor. CAGRs derive from installed base replacement cycle analysis and content-per-device expansion rates. Forecast inputs incorporate EU F-Gas Regulation phase-down timelines and automotive certification protocol evolution.
The model assumes a particular technology adoption path; alternative pathways for microLED direct-emission architectures would alter the outlook. Forecasts reflect assumptions about indium supply continuity, LTPO yield improvement trajectories, and automotive display integration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market