
 Global Cryptocurrency Mining Hardware Market | 2026-2036
Global Cryptocurrency Mining Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryptocurrency Mining Hardware Market Foresight
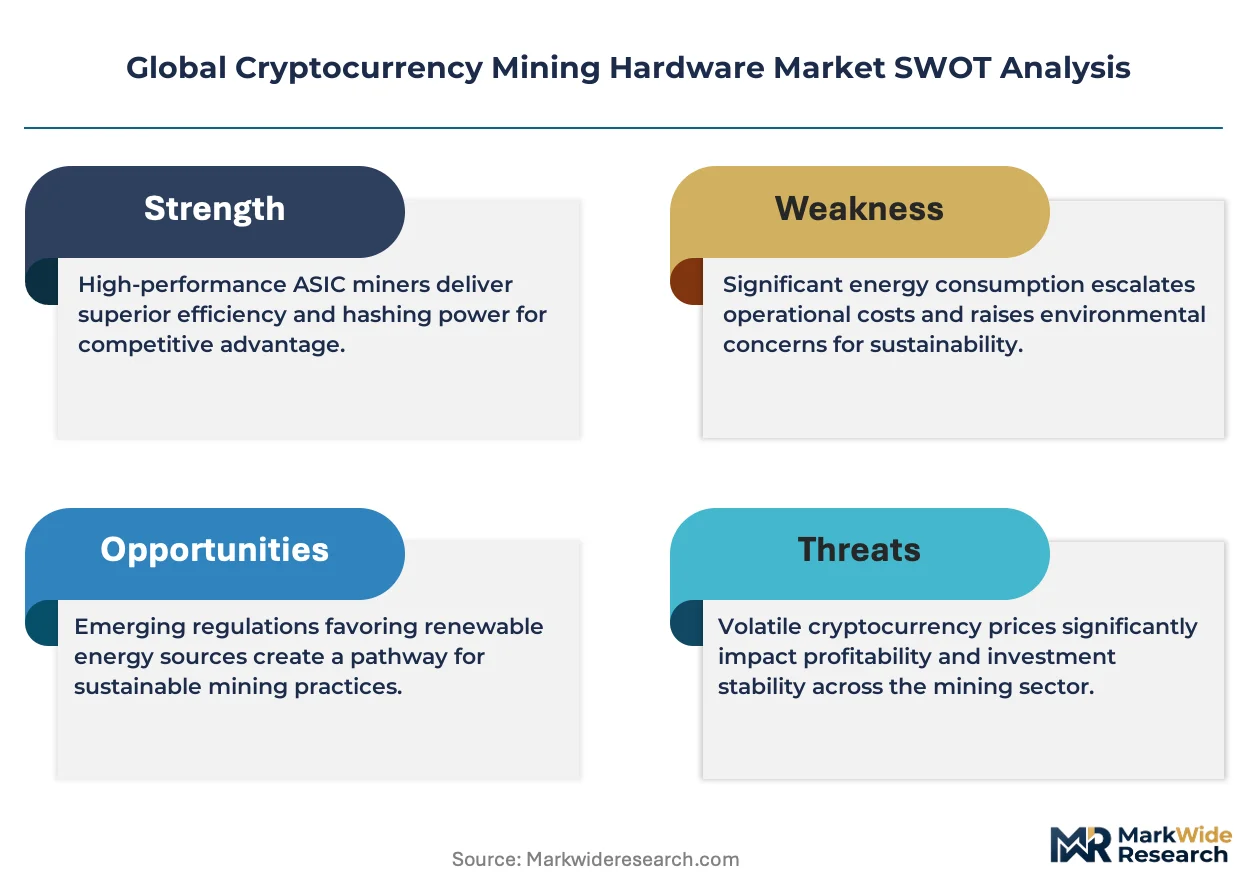
IEC 62368-1 safety certification for high-power computing equipment is bifurcating the competitive landscape into qualified incumbents and excluded newcomers. Bitmain leverages its vertical foundry partnerships to sustain cost leadership in SHA-256 ASIC output. MicroBT anchors its position through R&D intensity in immersion-cooled architectures. Canaan differentiates via energy-efficient design wins among North American hosting providers.
Cryptocurrency mining hardware denotes specialized computing systems engineered to execute hash functions at terahash-scale throughput, typically fabricated on 5nm or 7nm process nodes with power densities exceeding 30 joules per terahash. These machines validate blockchain transactions and secure decentralized networks against Byzantine faults. ASIC miners occupy the dominant value pool due to algorithm-specific optimization and unit economics that GPU miners cannot match in Bitcoin applications. Proof of Work technology retains structural priority despite energy scrutiny, while FPGA miners carve a niche in multi-algorithm flexibility for altcoin mining. Mining farms represent the fastest-growing end-user segment as institutional capital consolidates operations.
EPA energy efficiency mandates in the United States, EU Ecodesign requirements under the EU Green Deal, and China's dual carbon goals enforced by MEE collectively constrain permissible power consumption per validated transaction. These frameworks redirect procurement toward next-generation hardware with superior joule-per-terahash metrics. Stakeholders must monitor regulatory threshold adjustments and hash-rate migration patterns to time capacity deployment and geographic diversification decisions.
Market Dynamics
ASIC supply concentration in Taiwan and South Korean foundries is compressing hardware availability timelines while Kazakhstan, Texas, and Quebec absorb displaced mining capacity from China's 2021 crackdown. This geographic redistribution is forcing procurement patterns toward long-term foundry contracts and vertical integration strategies.
Growth Catalysts
- EPA Energy Efficiency Mandates:The EPA's tightening power consumption thresholds for data center equipment are accelerating replacement cycles among North American hosting providers seeking next-generation joule-per-terahash performance.
- Immersion Cooling Adoption:Mining farms in Kazakhstan and Texas are deploying dielectric fluid immersion systems to achieve 40% thermal efficiency gains over air-cooled architectures, unlocking higher rack densities.
- Institutional Capital Inflows:Sovereign wealth funds and energy utilities in Quebec and Iceland are co-investing in captive mining facilities to monetize stranded renewable generation assets.
Market Restraints
- Foundry Capacity Bottlenecks:Taiwan Semiconductor and Samsung Foundry allocate sub-7nm wafer starts to smartphone and AI chip priorities, constraining ASIC miner output volumes.
- Power Grid Interconnection Queues:ERCOT and Hydro-Québec interconnection backlogs extend facility commissioning timelines by 18-24 months for new entrants.
- Algorithm Obsolescence Risk:Ethereum's 2022 consensus mechanism transition eliminated GPU mining demand, demonstrating protocol-level substitution threats to hardware-specific investments.
Strategic Opportunities
- Sub-Saharan Africa Electrification:Excess geothermal capacity in Kenya and Ethiopia remains untapped for Bitcoin mining, offering sub-$0.04 per kilowatt-hour operational economics.
- EU Ecodesign Compliance Hardware:The EU Green Deal's 2027 efficiency benchmarks will create premium pricing tiers for ASICs certified under forthcoming ecodesign implementing measures.
- Flare Gas Monetization:Convergence of portable modular data centers with stranded natural gas assets in North Dakota and West Texas enables carbon-negative mining operations through methane capture.
Industry Challenges
- IEC 62368-1 Certification Timelines:Safety testing protocols for high-power computing equipment extend product launch windows by 8-12 months, disadvantaging smaller hardware designers against qualified incumbents.
- Thermal Engineering Talent Scarcity:The specialized skill set combining computational fluid dynamics with blockchain protocol architecture commands premium compensation that squeezes R&D budgets at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryptocurrency Mining Hardware Market |
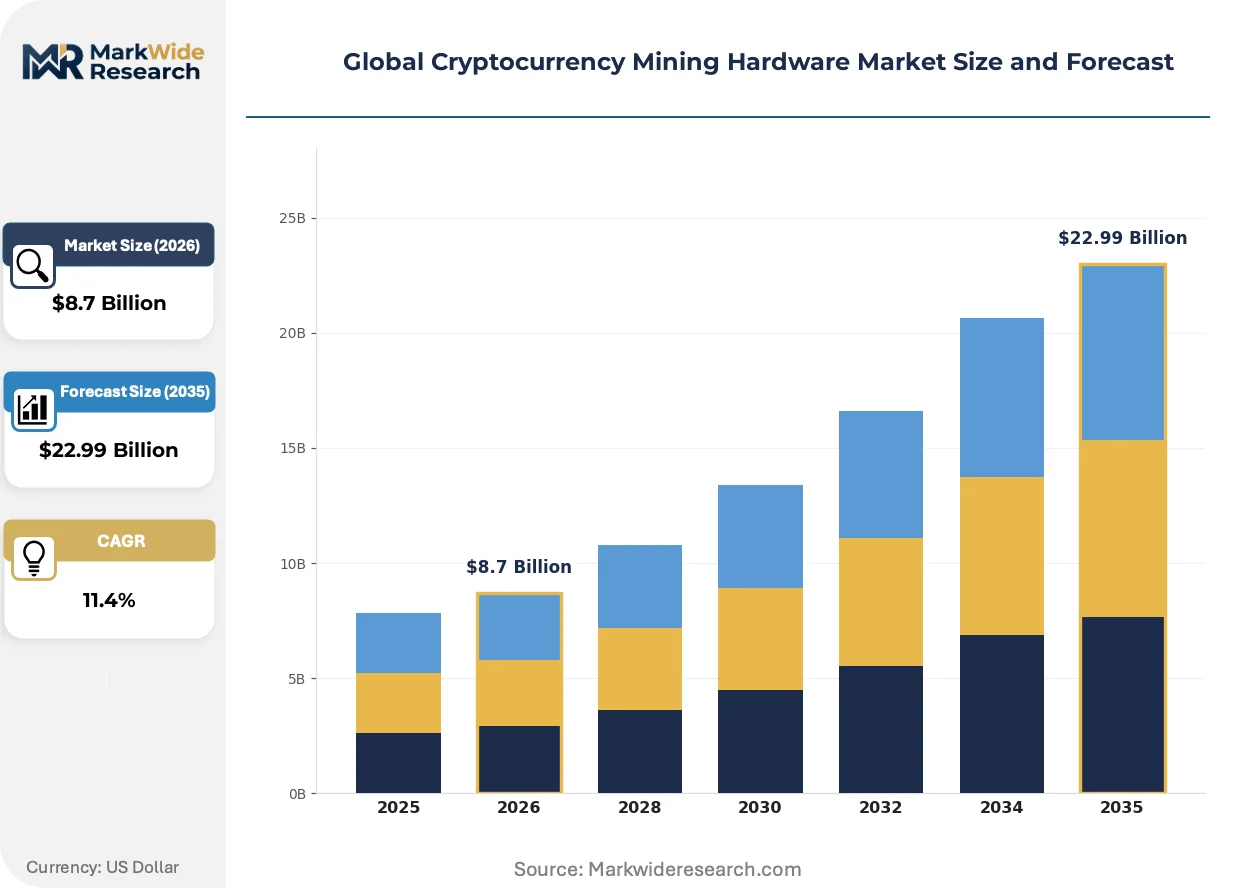
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ASIC Miners, GPU Miners, FPGA Miners, CPU Miners Technology: Proof of Work, Proof of Stake, Hybrid Consensus, Multi-Algorithm Application: Altcoin Mining, Bitcoin Mining, Litecoin Mining, Dash Mining, Monero Mining End User: Individual Miners, Mining Farms, Cloud Mining Providers, Data Centers |
| Companies Covered | Bitdeer, VolcMiner, Bitmain, ElphaPex, IceRiver, MicroBT, Auradine, Goldshell, Canaan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryptocurrency Mining Hardware Market Shifts & Advancements
Hardware design priorities are pivoting from raw hash-rate output toward total cost of ownership optimization, with thermal management and power delivery architectures commanding equal engineering resources as silicon layout. This rebalancing reflects margin pressure from electricity costs and regulatory efficiency floors.
Three-dimensional chiplet stacking is fragmenting traditional monolithic ASIC design paradigms. Bitmain and MicroBT are deploying chiplet-based hash boards that mix 5nm compute tiles with 12nm I/O dies to improve yield economics. Mining farms in Texas and Kazakhstan are piloting these configurations to achieve 15% capital expenditure reductions per terahash of deployed capacity.
EU Ecodesign requirements under the EU Green Deal are mandating disclosure of embodied carbon and operational energy efficiency for imported computing equipment. German and Swedish customs authorities are already rejecting shipments lacking CE-marked efficiency declarations. This regulatory friction is bifurcating export markets into compliant and non-compliant hardware tiers, with North American manufacturers accelerating certification investments to maintain European market access.
Hash-rate marketplace models are displacing direct hardware ownership among smaller operators. Luxor and NiceHash are aggregating demand from retail miners in Russia and Venezuela who prefer variable-cost exposure to fixed-capital deployment. This behavioral shift concentrates hardware procurement decisions among fewer institutional buyers with balance-sheet capacity for fleet-scale purchases, compressing manufacturer sales channel diversity.
Global Cryptocurrency Mining Hardware Market Segmentation
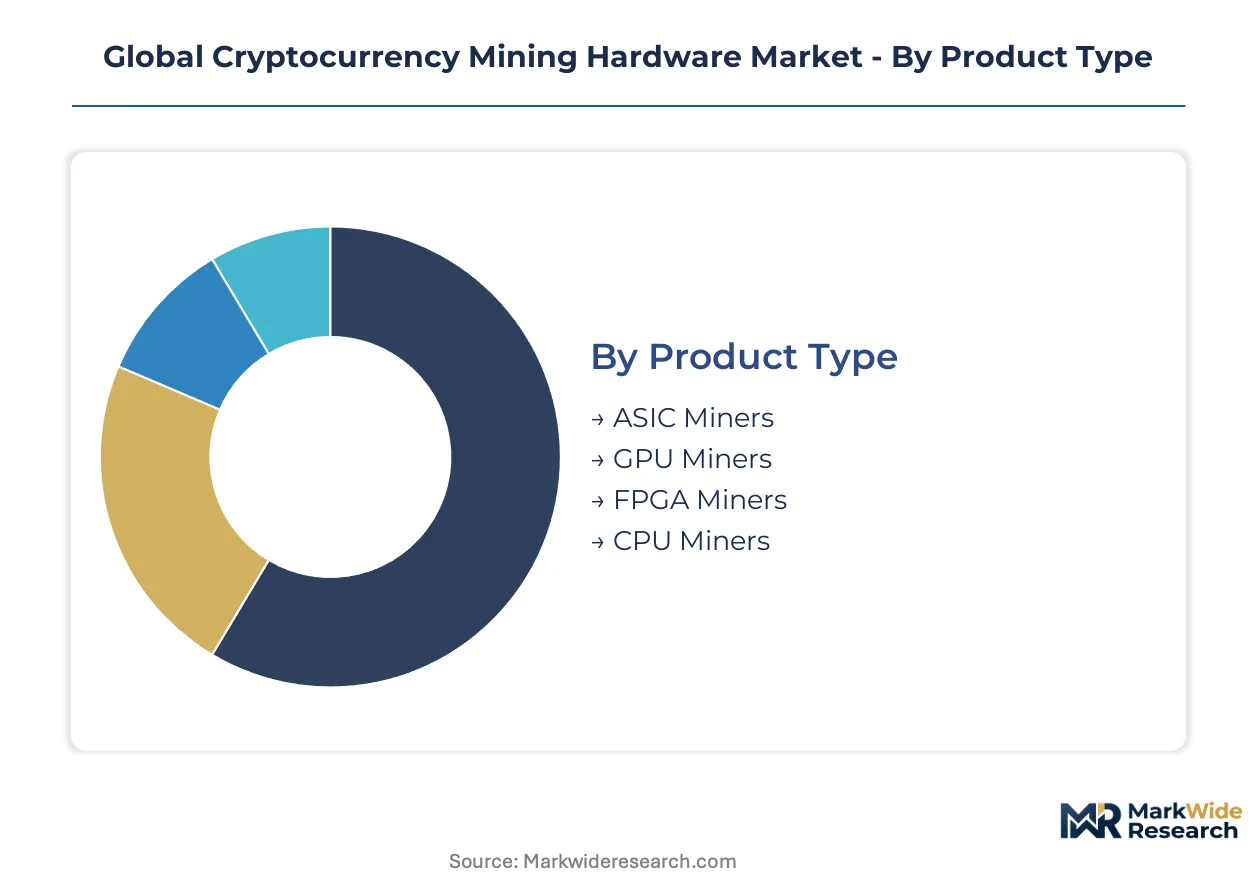
Segmentation in cryptocurrency mining hardware reveals how value migrates between efficiency-optimized silicon and flexible compute architectures. Procurement patterns diverge sharply between institutional fleet operators prioritizing unit economics and retail participants seeking algorithmic optionality.
Product Type:
Margin pools concentrate in algorithm-specific silicon where foundry partnerships and thermal engineering capabilities erect defensive moats.
- ASIC Miners:Application-specific integrated circuits fabricated on 5nm or 7nm process nodes deliver terahash-scale throughput with sub-30 joules per terahash efficiency. Mining farms in Kazakhstan and Texas are consolidating procurement around these units as EPA mandates tighten power density thresholds. Bitmain and MicroBT dominate supply through captive foundry allocations at Taiwan Semiconductor and Samsung Foundry.
- GPU Miners:Graphics processing units retain relevance in altcoin applications requiring memory-hard algorithms, though Ethereum's consensus transition eliminated their largest demand pool. Individual miners in Russia and Venezuela continue deploying NVIDIA and AMD hardware for speculative mining of emerging proof-of-work tokens.
- FPGA Miners:Field-programmable gate arrays offer post-deployment algorithm reconfiguration for multi-coin operators.
- CPU Miners:General-purpose processors occupy niche roles in privacy-focused networks like Monero.
ASIC Miners hold installed capacity. FPGA Miners is rotating up the share rankings as algorithm uncertainty persists.
Technology:
Technology choice determines hardware depreciation schedules and residual value risk exposure for fleet operators.
- Proof of Work:Energy-intensive consensus mechanisms secure Bitcoin, Litecoin, and derivative networks through computational expenditure. Mining farms in Quebec and Iceland favor this technology for its compatibility with stranded renewable assets and predictable revenue streams. Regulatory pressure from EU Ecodesign and EPA efficiency mandates is accelerating hardware replacement cycles.
- Proof of Stake:Capital-locked validation eliminates hardware requirements entirely, rendering mining equipment obsolete for networks adopting this mechanism. Ethereum's transition demonstrated protocol-level substitution risk that now constrains financing for GPU and FPGA deployments.
- Hybrid Consensus:Mixed mechanisms balance security and efficiency in networks like Dash.
- Multi-Algorithm:Flexible validation supports rapid coin switching based on profitability metrics.
Proof of Work commands capital deployment. Multi-Algorithm is climbing the fastest as volatility rewards operational flexibility.
Application:
Application segmentation tracks hash-rate migration between established monetary networks and speculative alternatives.
- Bitcoin Mining:SHA-256 algorithm dominance drives the largest hardware revenue pool, with institutional capital concentrating in North American hosting facilities. Texas and Kazakhstan absorbed significant capacity following China's regulatory crackdown, with ERCOT interconnection queues now extending commissioning timelines.
- Altcoin Mining:Diverse algorithm requirements span Scrypt, Ethash variants, and memory-hard functions, sustaining demand for GPU and FPGA architectures. Cloud mining providers aggregate retail exposure to these networks through subscription models.
- Litecoin Mining:Scrypt-based validation maintains secondary ASIC demand.
- Dash Mining:X11 algorithm hybrid consensus supports masternode operations.
- Monero Mining:RandomX CPU optimization resists ASIC specialization.
Bitcoin Mining absorbs manufacturing priority. Altcoin Mining is expanding most quickly as retail participation fragments across emerging tokens.
End User:
End-user structure determines sales channel economics and customer acquisition cost profiles for hardware manufacturers.
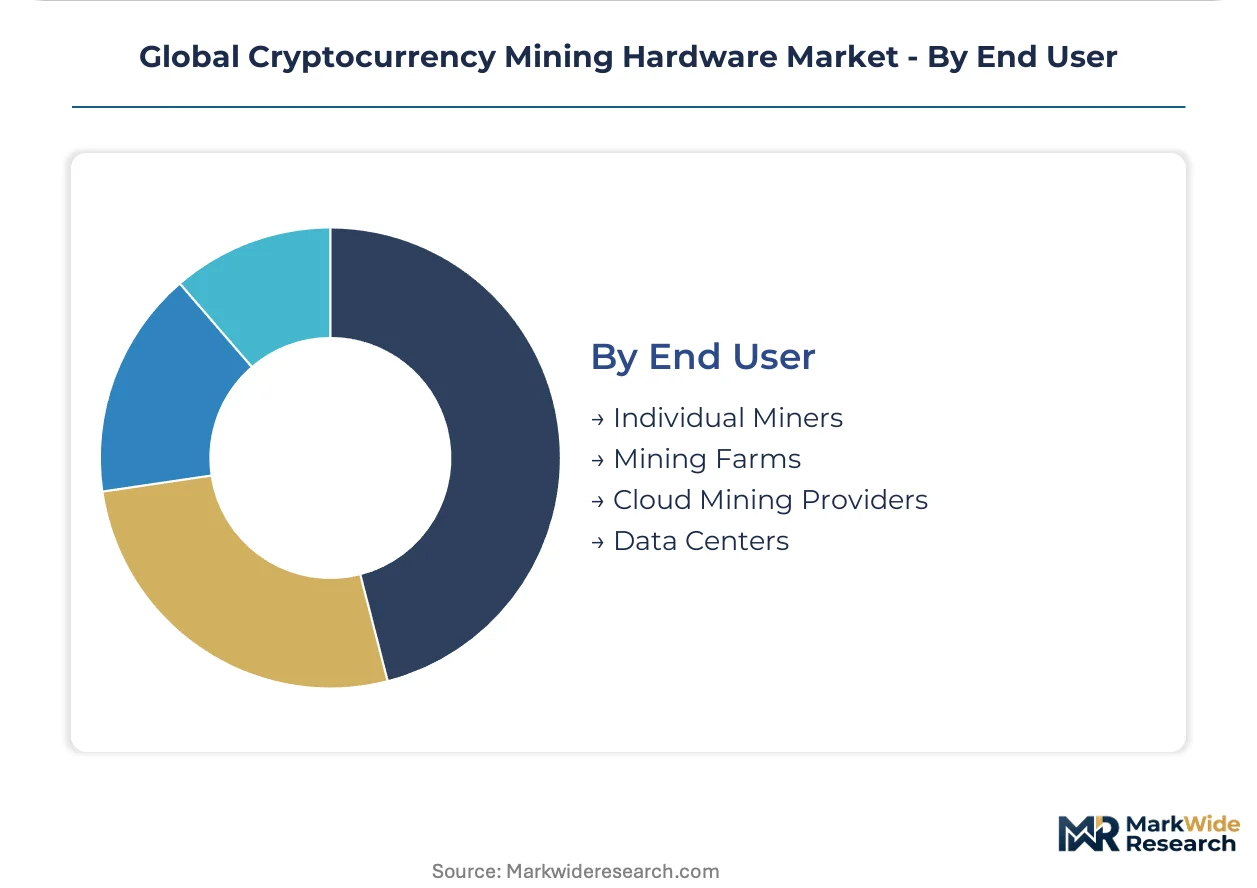
- Mining Farms:Industrial-scale operations exceeding 10 megawatts dominate hardware procurement volumes, leveraging power purchase agreements and immersion cooling infrastructure. Sovereign wealth funds in Quebec and energy utilities in Iceland are co-investing in captive facilities to monetize excess generation.
- Data Centers:Colocation providers in Texas and Kazakhstan offer hosted mining services, separating hardware ownership from operational execution. These operators prioritize IEC 62368-1 certified equipment to satisfy insurer and lender requirements.
- Individual Miners:Retail participants face margin compression from industrial scale economies.
- Cloud Mining Providers:Subscription models abstract hardware ownership for speculative exposure.
Mining Farms concentrate procurement decisions. Data Centers is gaining share fastest as institutional capital prefers operational outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentives and stranded energy assets are redistributing mining hardware demand across jurisdictions with favorable power economics and permissive regulatory frameworks. Kazakhstan, Texas, and Quebec absorbed significant displaced capacity following China's 2021 regulatory crackdown. Procurement patterns now favor regions offering long-term power purchase agreements and streamlined interconnection processes.
United States
Texas dominates North American hardware deployment through ERCOT's competitive wholesale electricity market and abundant stranded natural gas assets. EPA energy efficiency mandates for data center equipment are accelerating replacement cycles toward sub-30 joules per terahash ASICs. The Permian Basin and West Texas host the densest concentration of flare-gas-powered mining facilities.
Kazakhstan
Abundant coal and hydroelectric reserves delivered sub-$0.03 per kilowatt-hour operational economics that attracted Chinese-miner relocation post-crackdown. The Ministry of Ecology, Geology and Natural Resources now enforces carbon intensity disclosures for industrial energy consumers. Northern regions around Pavlodar and Ekibastuz concentrate the bulk of immersion-cooled mining farm construction.
Canada
Quebec's Hydro-Québec utility leverages surplus hydroelectric generation to attract institutional mining capital through dedicated load programs. The province's 2023 moratorium on new crypto-mining connections has redirected expansion toward Alberta's natural gas fields. Calgary and Edmonton host emerging data center clusters serving North American hosting demand.
Iceland
Geothermal and hydroelectric resources provide 100% renewable baseload power with minimal cooling requirements due to ambient temperatures. The country's national energy authority regulates industrial load allocation through competitive tender processes. Reykjanes Peninsula and the Troll Peninsula host captive mining facilities co-invested by Nordic energy utilities and sovereign wealth vehicles.
Russia
Siberian hydroelectric surplus and Arctic climate conditions offer operational economics competitive with Central Asian alternatives. The central bank's 2024 framework for cross-border crypto settlements has clarified regulatory status for industrial mining operations. Irkutsk Oblast and Krasnoyarsk Krai concentrate off-grid mining farms exploiting stranded hydropower from Soviet-era aluminum smelter infrastructure.
Global Cryptocurrency Mining Hardware Market Competitive Landscape
Player mix skews toward vertically integrated silicon designers with captive foundry access and thermal engineering specialists serving immersion-cooled deployments. The competitive structure concentrates around three strategic tiers: premium ASIC architects controlling sub-7nm tape-outs, mid-tier fabricators assembling hash boards from merchant silicon, and modular infrastructure providers integrating hardware with captive energy assets. Dominant competitive moves include backward integration into wafer-level supply commitments and geographic expansion through joint ventures with regional hosting operators.
Among Beijing-based and Shenzhen-based designers, Bitmain, MicroBT, and Canaan occupy positions within the premium-tier ASIC segment. These entities exemplify the vertically integrated archetype through direct foundry relationships and in-house thermal engineering capabilities. Their market presence anchors procurement decisions among institutional mining farms in Kazakhstan, Texas, and Quebec. Mid-tier competition clusters around specialists in algorithm-specific optimization and regional fabricators serving price-sensitive retail demand in Russia and Venezuela.
| Leading Market Players |
|---|
| Bitdeer |
| VolcMiner |
| Bitmain |
| ElphaPex |
| IceRiver |
| MicroBT |
| Auradine |
| Goldshell |
| Canaan |
| Others |
Supply & Pricing Matrix
Foundry-scale economies at Taiwan Semiconductor and Samsung Foundry compress unit costs for 5nm ASIC tape-outs while simultaneously concentrating pricing power among vertically integrated designers. This concentration elevates price floors for mid-tier fabricators lacking captive wafer allocations, forcing procurement decisions toward long-term supply commitments or merchant silicon premiums.
Pricing Analysis
Certification level creates the primary spread between IEC 62368-1 qualified hardware and uncertified alternatives, with CE-marked efficiency declarations under EU Ecodesign commanding premium positioning. Three-tier pricing structure separates immersion-cooled premium units from air-cooled standard configurations and refurbished economy hardware. Pricing pressure stems from foundry capacity bottlenecks redirecting sub-7nm wafer starts toward AI chip priorities. Mining farms exhibit lowest price sensitivity due to power purchase agreement economics, while retail individual miners face acute margin compression from industrial scale advantages.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for 5nm and 7nm ASIC compute tiles, while Malaysia and Vietnam host downstream hash board assembly and system integration. Raw material dependencies center on high-purity silicon wafers, copper interconnect substrates, and dielectric thermal interface materials. Single-source vulnerability concentrates in Taiwan Semiconductor's leading-edge node capacity, exposing procurement timelines to smartphone and AI chip allocation priorities. Distribution runs through direct manufacturer-to-farm contracts for institutional buyers, with regional distributors serving fragmented retail demand in Russia and Venezuela.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is approaching a platform-economics inflection as hash-rate marketplace models displace direct hardware ownership, concentrating procurement decisions among fewer institutional buyers with balance-sheet capacity for fleet-scale purchases.
For Market Incumbents: Compound foundry partnership depth through multi-year wafer supply commitments to defend against merchant silicon cost disadvantages. Prioritize IEC 62368-1 certification maintenance to preserve European market access under tightening EU Ecodesign enforcement. Thermal engineering talent scarcity threatens R&D velocity at mid-tier competitors, creating acquisition opportunities for qualified incumbents. For New Entrants and Emerging Players: Lead with modular infrastructure integration targeting stranded energy assets in Kenya and Ethiopia where sub-$0.04 per kilowatt-hour economics offset hardware cost premiums. Sub-Saharan Africa electrification gaps represent the most penetrable geography for portable data center deployments. Go-to-market execution should emphasize joint venture structures with regional utilities rather than direct hardware sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hash-rate marketplace operators and hosted mining providers with long-term power purchase agreements. Five-to-ten year viability favors entities controlling captive renewable generation or flared gas monetization infrastructure. Acquisition targets should demonstrate backward integration into energy assets rather than pure hardware exposure. The signal to watch is ERCOT and Hydro-Québec interconnection queue clearance rates as leading indicators of North American capacity expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Supply Commitment | Multi-year wafer allocations at Taiwan Semiconductor secure 5nm ASIC output priority against AI chip competition. |
| Immersion Cooling Deployment | Dielectric fluid systems in Kazakhstan and Texas unlock 40% thermal efficiency gains over air-cooled architectures. |
| EU Ecodesign Certification | CE-marked efficiency declarations preserve German and Swedish customs clearance under Green Deal implementing measures. |
| Stranded Energy Joint Venture | Partnerships with Quebec Hydro-Québec and Iceland utilities monetize excess renewable generation through captive facilities. |
| Hash-Rate Marketplace Integration | Aggregation platforms like Luxor concentrate retail demand exposure without fixed-capital hardware ownership burdens. |
Research Methodology
Operator-level perspectives from mining farm procurement directors, data center facility managers, foundry account executives, and energy utility planning officers anchored the qualitative base. Secondary validation drew from Taiwan Semiconductor and Samsung Foundry capacity disclosures, ERCOT interconnection queue data, Hydro-Québec load program filings, and EU Ecodesign implementing measure drafts. Bottom-up hardware shipment estimates triangulated against top-down hash-rate migration patterns across Kazakhstan, Texas, and Quebec.
Sensitivity analysis tested forecast outputs against variables including foundry allocation shifts, EPA efficiency mandate threshold adjustments, and protocol-level consensus mechanism transitions. Segmentation dimensions modeled span product type, technology architecture, application algorithm, and end-user scale tier. CAGRs were derived from installed capacity growth trajectories and replacement cycle acceleration under regulatory efficiency floors. Industry-specific inputs incorporated joule-per-terahash performance curves and immersion cooling adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained Proof of Work algorithm dominance, stable foundry capacity expansion, or permissive regulatory frameworks in anchor geographies would require recalibration. Forecasts reflect documented assumptions regarding hash-rate migration patterns and hardware depreciation schedules. Algorithm obsolescence risk, power grid interconnection delays, and thermal engineering talent scarcity constitute primary revision triggers. Recalibration cycles align with material shifts in EPA mandate enforcement, EU Ecodesign benchmark adoption, and foundry node allocation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Transistor Arrays Market