
 Europe MLCC Market | 2026-2036
Europe MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
Europe MLCC Market Insights
Central European production corridors is fragmenting as new capacity investments spread across Poland, Hungary, and the Czech Republic. TDK Corporation anchors high-volume automotive-grade output from its regional manufacturing footprint. Murata Manufacturing Co., Ltd. leverages proprietary thin-layer technology to sustain premium positioning in telecommunications infrastructure. Würth Elektronik GmbH & Co. KG specializes in customized solutions for industrial equipment OEMs, competing on engineering proximity rather than commodity scale.
Europe multilayer ceramic capacitors (MLCCs) are passive electronic components constructed from alternating layers of ceramic dielectric and metal electrodes, sintered into monolithic blocks that store and filter electrical charge in circuits operating from DC to several gigahertz. Their primary industrial purpose centers on decoupling, filtering, and energy storage in high-density printed circuit boards where space constraints and reliability requirements dominate design decisions. Ceramic dielectric formulations dominate volume demand across the region, with X7R and C0G/NP0 temperature-stable grades commanding margin premiums in automotive and telecommunications applications. Consumer electronics represents a mature, price-sensitive consumption pool, while automotive electrification and 5G base station rollouts concentrate growth in higher-reliability product tiers.
REACH compliance and the EU Green Deal's material traceability mandates are forcing reformulation of dielectric compositions and electrode metallurgy across European suppliers. The CE marking framework under the Radio Equipment Directive governs electromagnetic compatibility performance for MLCCs deployed in telecommunications infrastructure. ECHA substance restrictions on nickel and tin supply chains are reshaping raw material sourcing strategies for manufacturers serving European OEMs. Stakeholders must monitor evolving F-Gas Regulation amendments and their indirect pressure on semiconductor and passive component cleanroom energy intensity standards.
Market Dynamics
Automotive electrification is compressing MLCC qualification timelines while simultaneously elevating reliability standards beyond consumer-grade specifications. Tier-one suppliers now demand AEC-Q200 certification for powertrain modules, forcing capacitor manufacturers to reconfigure dielectric formulations and electrode metallurgy.
Growth Catalysts
- EU Green Deal material mandates:REACH and RoHS directives are accelerating substitution of lead-based dielectrics with barium titanate formulations in automotive applications.
- Electric vehicle powertrains:On-board chargers and DC-DC converters require high-voltage MLCCs with X7R temperature stability ratings.
- Poland:New cleanroom capacity investments near Wrocław are expanding regional substrate processing capabilities for telecommunications-grade components.
Market Restraints
- Palladium electrode costs:Precious metal price volatility in thick-film electrode formulations compresses gross margins for mid-tier manufacturers.
- Japanese supplier concentration:Thin-layer ceramic technology remains captive to proprietary sintering expertise concentrated in Osaka and Kyoto production clusters.
- Base metal electrode limitations:Nickel-barrier termination systems exhibit inferior solder leach resistance versus palladium in high-temperature automotive environments.
Strategic Opportunities
- Hungary:Underdeveloped automotive-grade MLCC finishing capacity creates white space for AEC-Q200 certified contract manufacturers serving German OEMs.
- 5G millimeter-wave infrastructure:Ultra-low equivalent series resistance specifications in sub-6 GHz base stations demand C0G/NP0 dielectric grades with tight capacitance tolerances.
- F-Gas Regulation amendments:Cleanroom energy efficiency mandates are incentivizing heat recovery systems in new Eastern European fabrication facilities.
Industry Challenges
- Ceramic powder synthesis expertise:Qualified materials engineers with barium titanate particle size distribution control experience remain scarce across Central European labor markets.
- CE marking electromagnetic compatibility testing:Radio Equipment Directive certification timelines for telecommunications MLCCs now extend 14-18 months due to backlog at notified bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe MLCC Market |
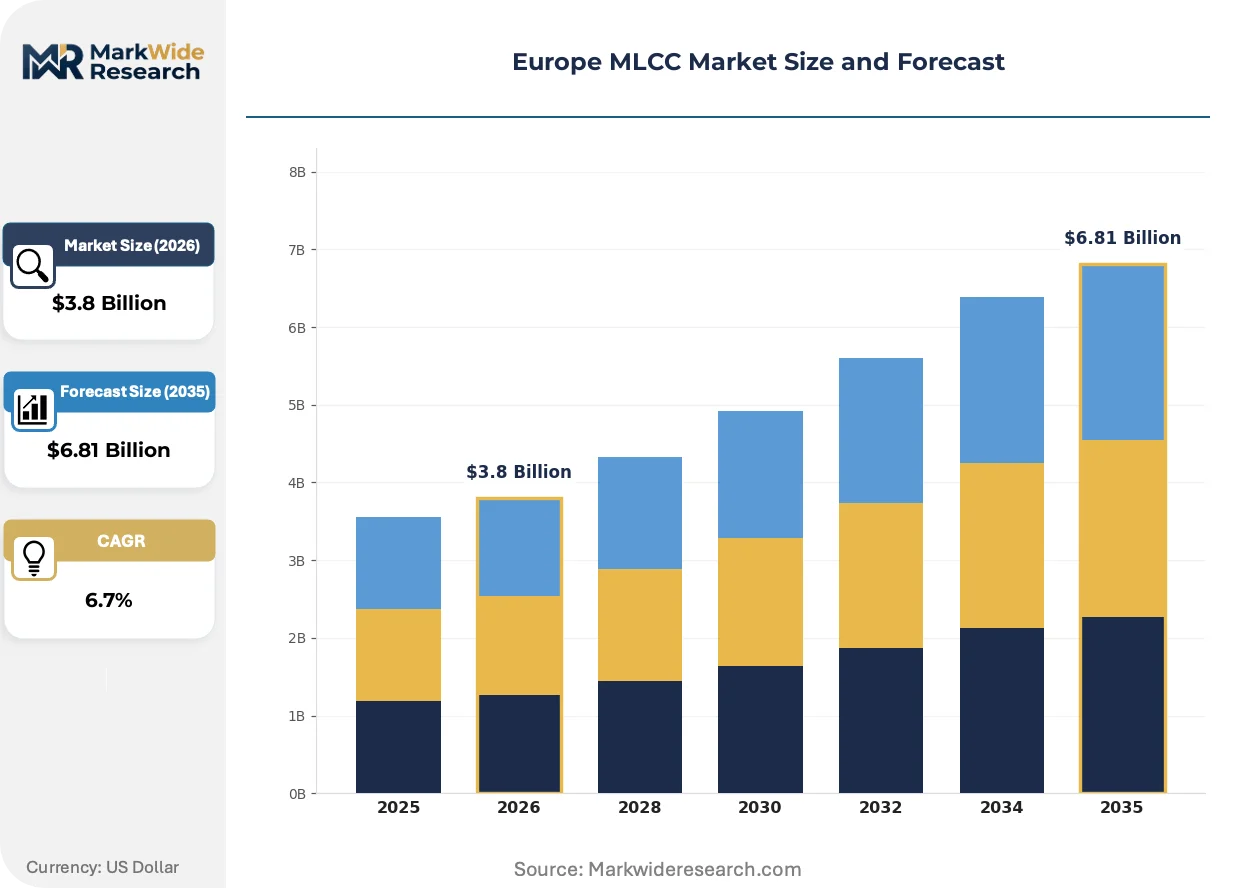
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Tantalum, Aluminum, Film Application: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment End User: OEMs, Aftermarket Providers, Distributors, Retailers Delivery Mode: Direct Shipping, Wholesale, Online Orders, Local Pickup |
| Companies Covered | KYOCERA AVX Components Corporation, Maruwa Co., Ltd., Murata Manufacturing Co., Ltd., Panasonic Industry, Nippon Chemi-Con Corporation, TDK Corporation, Würth Elektronik GmbH & Co. KG, Vishay Intertechnology Inc., Samsung Electro-Mechanics Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe MLCC Market Trends and Innovations
Dielectric engineering and electrode metallurgy are converging to address thermal cycling demands in automotive power electronics. Manufacturers are reformulating ceramic compositions while simultaneously thinning active layers to maintain volumetric efficiency.
Base metal electrode technology is hybridizing nickel-copper termination systems with thin-film palladium flash layers to achieve automotive reliability at reduced precious metal loadings. German tier-one suppliers are qualifying these hybrid constructions for 800V battery management systems. The technology is hybridizing cost structures across premium and standard product tiers previously separated by electrode material selection.
ECHA substance restrictions on nickel compounds are forcing reformulation of termination metallurgy and barrier layer compositions. Suppliers serving European OEMs must now document supply chain provenance for all nickel-bearing raw materials under REACH Article 33. Automotive-grade MLCC producers are responding by accelerating copper-nickel alloy substitution programs in electrode formulations.
Consolidated procurement contracts are displacing spot-market purchasing for high-reliability telecommunications infrastructure. Nordic Mobile Telephone operators now negotiate three-year supply agreements directly with Japanese manufacturers, bypassing traditional distribution channels. This concentration is most visible in Scandinavian 5G base station deployments where Ericsson and Nokia anchor regional procurement volumes.
Europe MLCC Market Segmentation
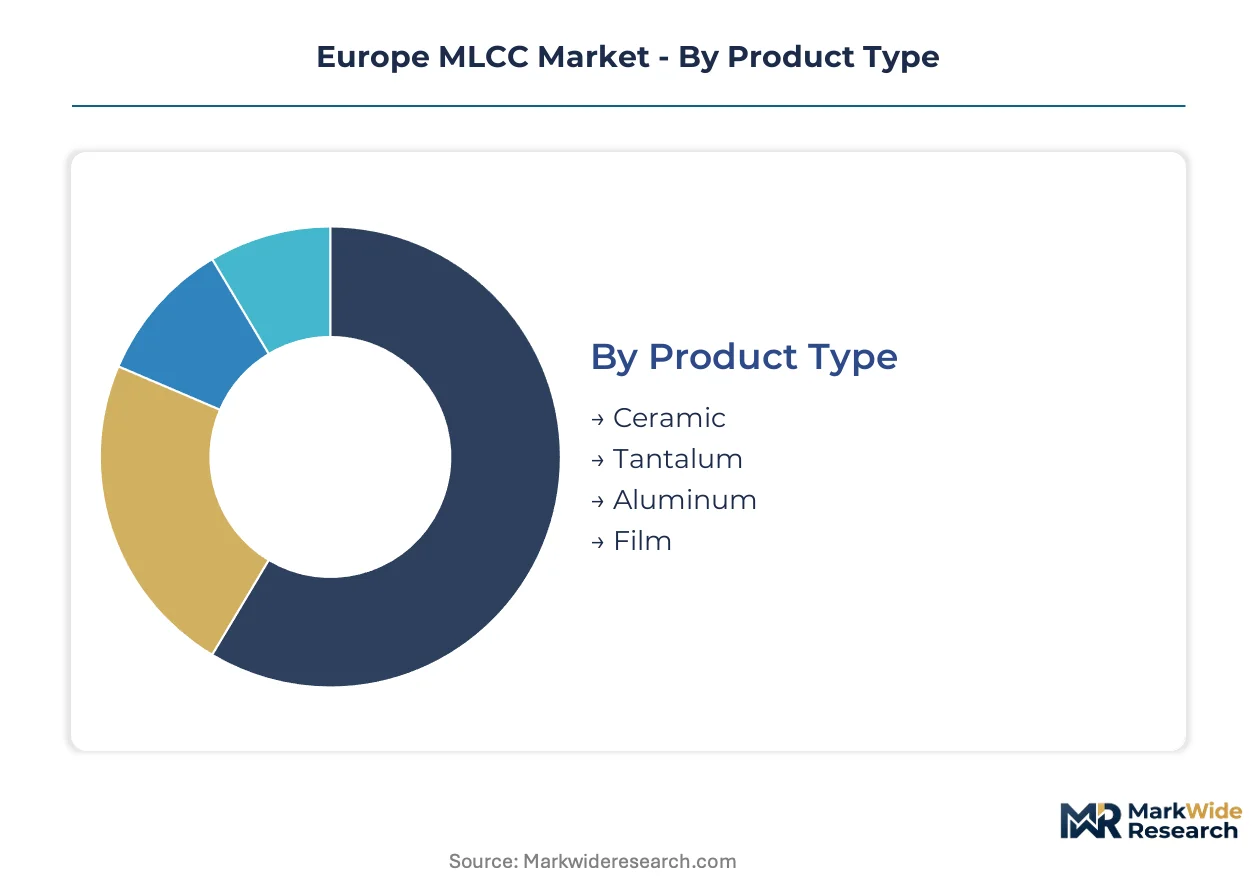
MLCC procurement patterns diverge sharply across dielectric formulations and voltage ratings, with automotive qualification cycles stretching 18-24 months while consumer electronics refresh quarterly. Segmentation clarity enables suppliers to align inventory buffers with actual consumption velocity rather than aggregated forecasts.
Product Type:
Ceramic formulations turn inventory fastest in telecommunications spot markets, while tantalum and film capacitors lock working capital through extended automotive validation pipelines.
- Ceramic:Barium titanate dielectric layers sintered with nickel or palladium electrodes dominate volumetric efficiency in high-density PCB assemblies. German automotive OEMs concentrate procurement for powertrain modules requiring X7R temperature stability ratings under AEC-Q200 certification.
- Tantalum:Manganese dioxide or polymer cathode systems deliver superior capacitance density in space-constrained medical and aerospace applications. Demand concentrates in Swiss precision instrumentation clusters where ECHA substance restrictions on conflict minerals complicate supply chain documentation.
- Aluminum:Electrolytic constructions with etched foil electrodes serve high-voltage bulk capacitance in industrial motor drives.
- Film:Polypropylene or polyester dielectrics withstand high ripple currents in renewable energy inverters across Nordic wind farm installations.
Ceramic dominates installed base across all voltage tiers. Tantalum is where expansion concentrates for mission-critical reliability specifications.
Application:
Margin structures stratify sharply across end-use certification requirements, with telecommunications infrastructure commanding premium pricing for C0G/NP0 dielectric precision.
- Consumer Electronics:Smartphones and wearables drive high-volume demand for compact case sizes with relaxed temperature coefficients. Polish contract manufacturers concentrate assembly capacity near Wrocław, feeding distribution hubs serving Western European retail channels.
- Automotive:On-board chargers and DC-DC converters in 800V architectures require high-voltage MLCCs with AEC-Q200 validation. Hungarian tier-one suppliers anchor regional procurement volumes for German OEM powertrain programs.
- Telecommunications:5G base station rollouts demand ultra-low ESR specifications in sub-6 GHz and millimeter-wave frequencies.
- Industrial Equipment:Factory automation systems prioritize long-term stability over miniaturization in harsh thermal environments.
Consumer electronics commands volume leadership. Automotive electrification is climbing the fastest as a share of supplier revenue.
End User:
Procurement authority is consolidating among OEMs with captive engineering resources, squeezing distributor margins on standard-grade components.
- OEMs:Tier-one automotive and telecommunications equipment manufacturers negotiate direct supply agreements with Japanese and Korean manufacturers. Ericsson and Nokia anchor Nordic procurement volumes through three-year consolidated contracts bypassing traditional distribution.
- Aftermarket Providers:Repair and refurbishment specialists source legacy case sizes through independent distributors serving industrial maintenance channels.
- Distributors:Arrow Electronics and Avnet maintain regional inventory buffers for mid-volume industrial customers lacking direct manufacturer relationships.
- Retailers:Electronics component retailers serve hobbyist and prototype engineering demand through online portals with next-day fulfillment.
OEMs dominate procurement value. Distributors retain relevance in fragmented industrial aftermarket segments.
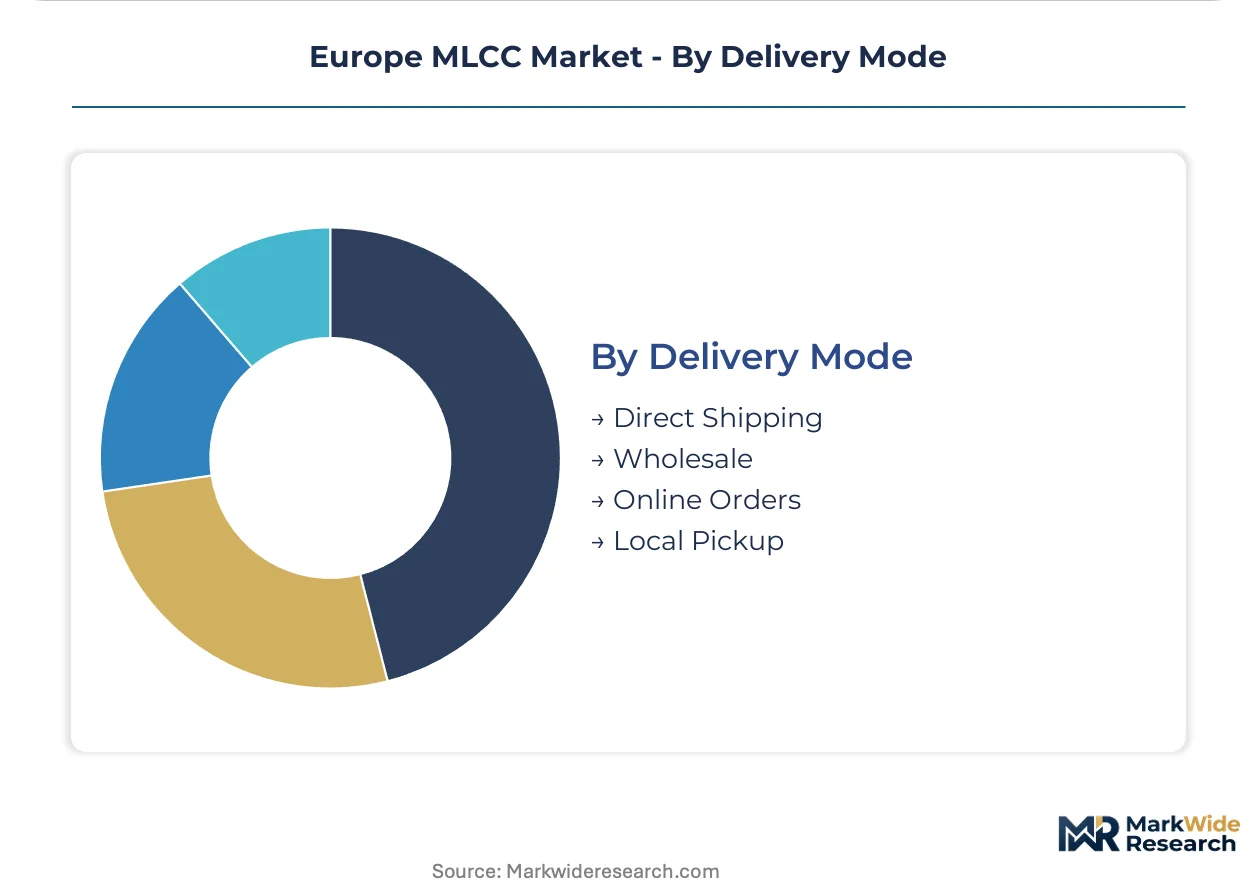
Delivery Mode:
Logistics configuration tracks order predictability, with scheduled direct shipping commanding lowest unit economics and emergency local pickup extracting maximum premium.
- Direct Shipping:Scheduled sea and air freight from East Asian manufacturing clusters serves high-volume OEM programs with forecast-driven MRP systems. TDK Corporation routes automotive-grade shipments through Rotterdam for just-in-time delivery to German assembly plants.
- Wholesale:Pallet-quantity transactions through regional distribution centers buffer demand volatility for contract manufacturers.
- Online Orders:E-commerce portals enable rapid prototype sourcing with credit-card purchasing and real-time inventory visibility.
- Local Pickup:Will-call counter service at distribution facilities serves emergency replacement demand with same-day availability premiums.
Direct shipping handles the majority of volume tonnage. Online ordering is gaining share fastest in prototype and small-batch production segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement volumes concentrate in Germany, while Eastern European manufacturing corridors expand substrate processing capacity. REACH and RoHS compliance mandates reshape supplier qualification requirements across the region.
Germany
Bavarian automotive clusters anchor AEC-Q200 certified MLCC procurement for 800V powertrain architectures. KBA vehicle type approval standards enforce electromagnetic compatibility testing for on-board charging modules. Stuttgart and Ingolstadt production corridors concentrate tier-one supplier engineering resources.
Poland
Wrocław cleanroom investments expand telecommunications-grade component substrate processing capabilities. EU Green Deal material traceability mandates accelerate barium titanate dielectric qualification programs. Lower Silesian manufacturing zones attract Japanese capital for high-volume automotive finishing capacity.
Hungary
Underdeveloped automotive-grade MLCC finishing creates white space for AEC-Q200 contract manufacturers serving German OEMs. CE marking under the Radio Equipment Directive governs 5G base station component deployments. Budapest and Győr industrial zones concentrate electronics assembly for Western European distribution.
France
ANSM medical device regulations drive tantalum capacitor demand in Swiss-border precision instrumentation clusters. ECHA substance restrictions on nickel compounds force termination metallurgy reformulation. Île-de-France telecommunications equipment manufacturers negotiate direct supply agreements with Japanese producers.
Sweden
Ericsson anchors Nordic 5G base station procurement volumes through consolidated three-year supply contracts. CE marking electromagnetic compatibility certification timelines extend 14-18 months at notified bodies. Stockholm and Gothenburg engineering centers specify C0G/NP0 dielectric grades for millimeter-wave infrastructure.
Europe MLCC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in dielectric formulation and electrode metallurgy. The European MLCC supplier base concentrates around Japanese and Korean manufacturers with proprietary thin-layer sintering expertise. Three archetypes dominate: integrated materials-to-components conglomerates, specialized passive component houses, and automotive-focused contract finishers. Capacity expansion and strategic technology licensing represent the primary competitive vectors.
Among Japanese manufacturers, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify integrated conglomerates with captive ceramic powder synthesis and proprietary thin-layer technology. Würth Elektronik GmbH & Co. KG represents the specialized European fabricator archetype, competing on engineering proximity to German industrial OEMs rather than commodity scale. Samsung Electro-Mechanics Co., Ltd. anchors Korean presence in telecommunications infrastructure supply chains.
| Leading Market Players |
|---|
| KYOCERA AVX Components Corporation |
| Maruwa Co., Ltd. |
| Murata Manufacturing Co., Ltd. |
| Panasonic Industry |
| Nippon Chemi-Con Corporation |
| TDK Corporation |
| Würth Elektronik GmbH & Co. KG |
| Vishay Intertechnology Inc. |
| Samsung Electro-Mechanics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Palladium electrode cost volatility compresses gross margins for mid-tier manufacturers while simultaneously widening pricing tier spreads between automotive-grade and consumer-grade MLCCs. REACH and RoHS compliance mandates force European suppliers to absorb reformulation costs that commodity buyers refuse to shoulder, segmenting procurement into certification-gated premium channels and spot-market standard tiers.
Pricing Analysis
REACH and RoHS directives dictate the pricing tier structure across the European MLCC market. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 certified automotive components from telecommunications-grade precision units and consumer electronics commodities. Price differentiation hinges on certification level and volume scale, with German OEMs locking long-term contracts while Polish contract manufacturers compete on spot-market agility. Pricing pressure stems from precious metal volatility in palladium-thick-film electrode formulations. Consumer electronics buyers exhibit highest price sensitivity; automotive powertrain procurement teams prioritize reliability premiums over unit cost.
Supply Chain Analysis
Barium titanate ceramic powder synthesis expertise concentrates in Japanese production clusters around Osaka and Kyoto. Raw material supply draws from Australian tantalum ore, Chinese rare earth processing, and German specialty chemical precursors. Single-source vulnerability pervades thin-layer sintering technology captive to proprietary Japanese know-how. Distribution runs through Rotterdam port logistics for just-in-time delivery to German automotive assembly corridors, with Wrocław emerging as Eastern European substrate processing hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified materials engineers with barium titanate particle size distribution control experience remain scarce across Central European labor markets, constraining capacity expansion regardless of capital availability.
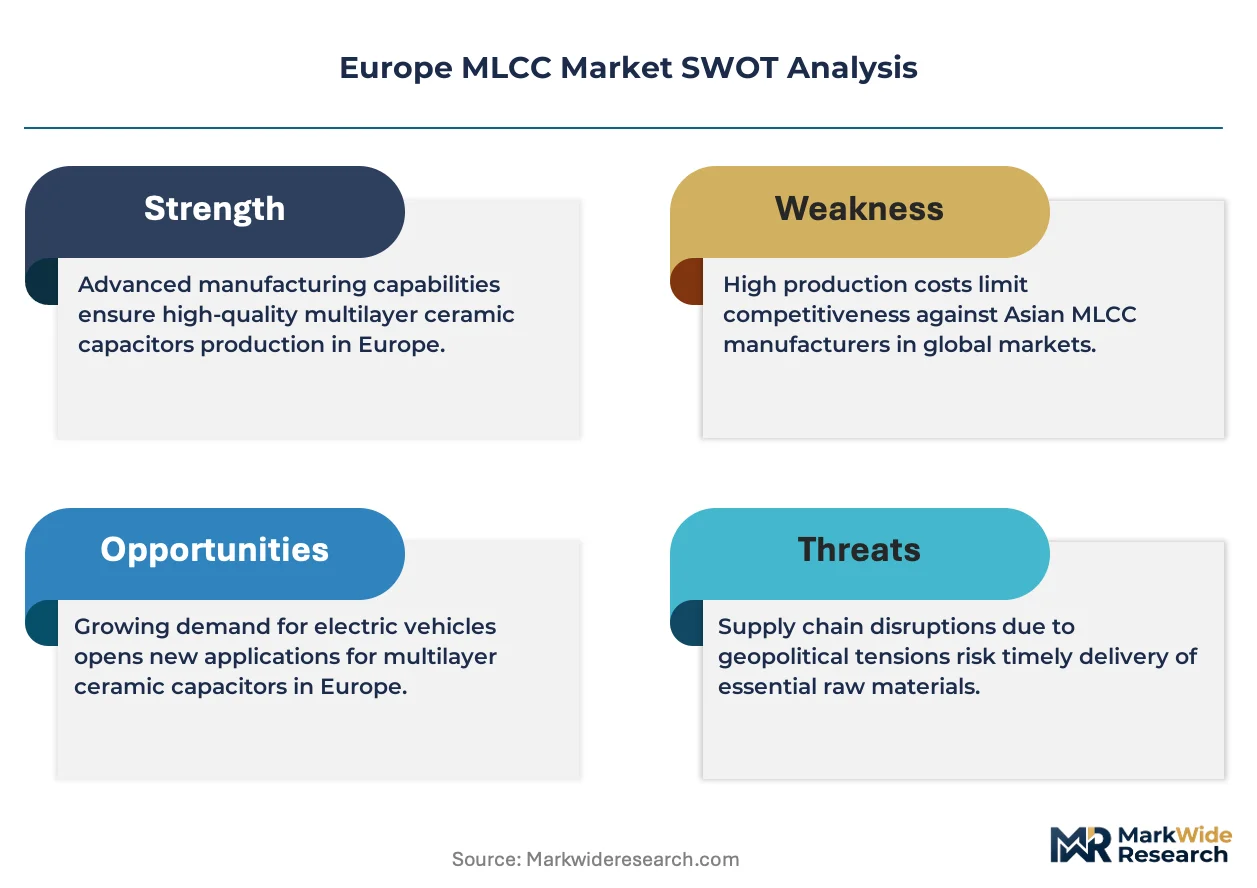
For Market Incumbents: Pre-empt Hungarian automotive-grade MLCC finishing capacity before German tier-one suppliers consolidate contract manufacturer relationships. Secure backward integration into ceramic powder synthesis capabilities to reduce dependency on Japanese feedstock suppliers. Accelerate copper-nickel alloy electrode qualification programs ahead of ECHA substance restriction enforcement timelines. For New Entrants and Emerging Players: Underdeveloped AEC-Q200 certified finishing capacity in Hungary offers white-space entry for contract manufacturers serving Bavarian automotive clusters. Target telecommunications infrastructure spot markets in Poland where substrate processing investments lag dielectric engineering demand. Pursue engineering proximity positioning alongside Würth Elektronik's industrial OEM service model rather than commodity scale competition. For Investors and Strategic Acquirers: Specialized passive component houses with captive thin-layer technology licensing agreements present asymmetric upside exposure to automotive electrification capex cycles. Long-term viability hinges on regulatory compliance infrastructure depth rather than unit cost positioning alone. Monitor CE marking electromagnetic compatibility certification backlog durations at notified bodies as early signal of supply-constrained pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Synthesis | Captive barium titanate production reduces Japanese feedstock dependency and REACH documentation burden. |
| AEC-Q200 Certification Investment | Qualification for 800V powertrain modules unlocks German OEM direct supply contract eligibility. |
| Hungary Manufacturing Footprint Expansion | Proximity to Stuttgart and Ingolstadt corridors shortens just-in-time logistics lead times. |
| Copper-Nickel Alloy Electrode Reformulation | ECHA nickel compound restriction compliance secures European OEM supply chain continuity. |
| Three-Year Supply Agreement Negotiation | Ericsson and Nokia consolidated procurement bypasses distributor margin extraction in Nordic 5G rollout. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with capacitor manufacturing executives, automotive tier-one procurement directors, telecommunications infrastructure engineers, and ECHA regulatory affairs specialists; and secondary validation against SEC 10-K filings, EU customs trade databases, CE marking notification records, and IHS Markit vehicle production data. Bottom-up bill-of-materials estimation for electric vehicle powertrain content triangulated against top-down market size reconstruction from Japanese and Korean manufacturer shipment disclosures.
Forecast inputs considered dielectric formulation segmentation, voltage rating tiers, application-specific qualification requirements, and regional automotive production cluster capacity across the analysis window. CAGRs derived from regression against historical electric vehicle adoption curves and 5G base station deployment schedules. Modeled variables included AEC-Q200 certification penetration rates, barium titanate raw material cost trajectories, and cleanroom energy intensity standards under F-Gas Regulation amendment scenarios.
Practitioners should monitor ECHA substance restriction amendment timelines, palladium spot price volatility bands, and notified body certification backlog durations for early signals of forecast revision triggers. Cross-checking against Japanese Ministry of Economy, Trade and Industry passive component export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Polymer Core Solder Ball Market