
 Global Vacuum Capacitors Market | 2026-2036
Global Vacuum Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vacuum Capacitors Market Outlook
CE marking under the EU's Low Voltage Directive is redrawing competitive boundaries for vacuum capacitor suppliers seeking European industrial access. COMET leverages its Swiss manufacturing heritage to sustain premium positioning in RF amplifier applications. Richardson Electronics anchors North American distribution through extensive aftermarket service networks for legacy broadcast transmitters.
Vacuum capacitors hermetically seal electrode assemblies within glass or ceramic envelopes to achieve ultra-low loss and self-healing dielectric performance under high RF stress, typically rated from kilovolts to megavolts across the tuning range. Their primary purpose centers on impedance matching in high-power RF systems where conventional solid-state alternatives fail from thermal runaway or arcing. High voltage products dominate current revenue pools given semiconductor etcher and deposition tool requirements, while specialty variants for fusion research and particle accelerators capture disproportionate margins despite smaller volumes. Ceramic technology leads in unit shipments for telecommunications infrastructure, though glass-envelope designs retain preference in medical equipment where outgassing specifications from the FDA prove more stringent.
The FCC in the United States mandates electromagnetic interference limits that elevate specification thresholds for capacitors deployed in broadcast and radar systems, while China's SAMR enforces GB standards on insulation coordination that shape product architectures for Asia-Pacific deployments. Japan's METI energy efficiency directives for industrial RF equipment indirectly tighten loss-tangent requirements across supplier portfolios. Stakeholders must monitor divergence between regional qualification regimes when allocating R&D budgets across envelope materials and electrode geometries.
Market Dynamics
Semiconductor fabrication tool cycles now dictate vacuum capacitor procurement rhythms more than traditional broadcast infrastructure replacement schedules. East Asian foundry expansions compress lead times while European REACH compliance forces material substitutions in ceramic envelope formulations.
Growth Catalysts
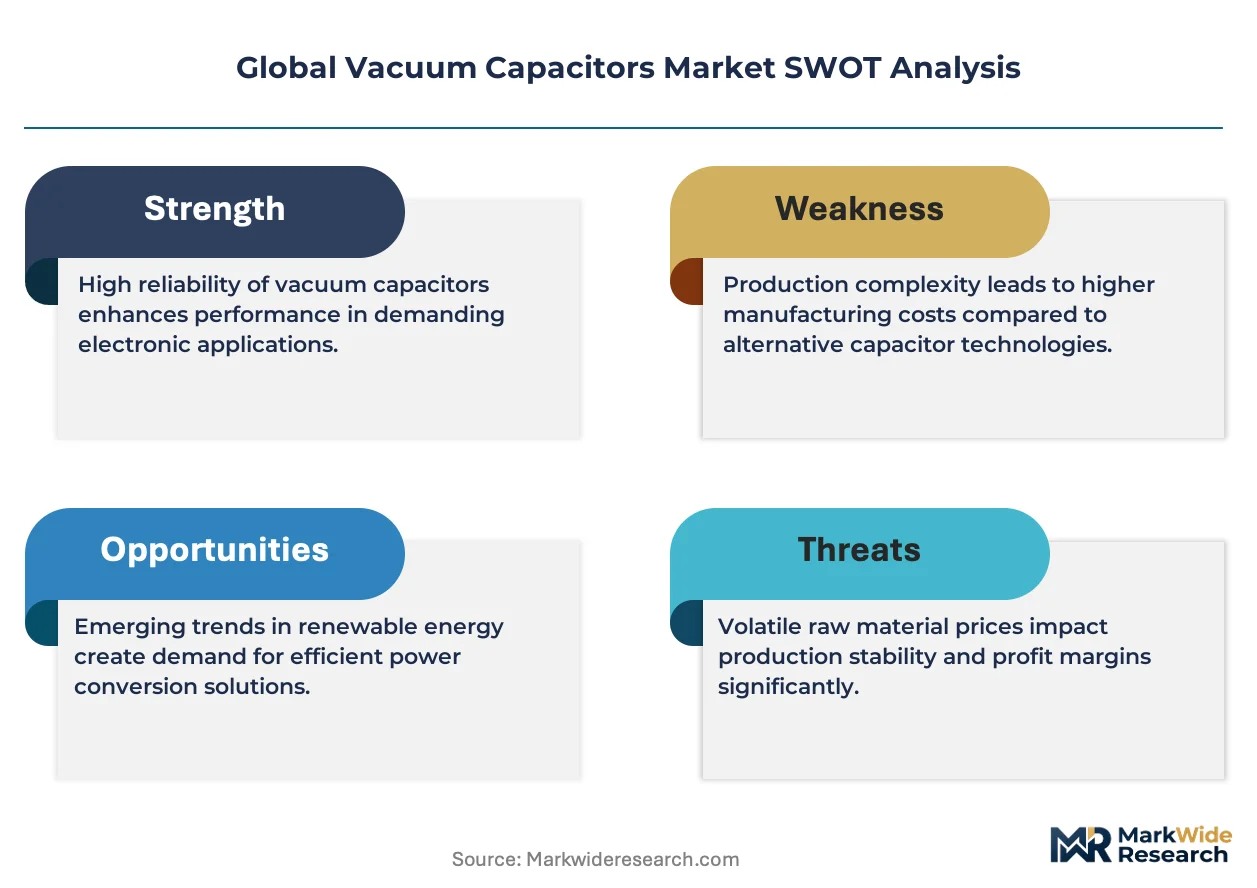
- Etcher tool density:Semiconductor manufacturers in South Korea deploy multi-chamber etcher architectures that multiply vacuum capacitor counts per tool platform. Each additional chamber requires dedicated impedance matching networks.
- CE marking convergence:The EU's Low Voltage Directive harmonization simplifies cross-border industrial RF equipment certification. Swiss and German suppliers leverage this to consolidate distribution across Benelux and Nordic markets.
- Fusion research scale-up:ITER and private tokamak ventures in France and the United States commission ultra-high-voltage capacitor banks for plasma heating systems. These orders carry 3-5 year delivery horizons.
Market Restraints
- Ceramic powder oligopoly:High-purity alumina supply concentrates among Japanese and German specialty chemical producers. Earthquake or energy disruption risks propagate through capacitor envelope manufacturing.
- Copper electrode volatility:OFHC copper constitutes 35-40% of variable material costs. LME price swings compress margin predictability for fixed-price foundry contracts.
- Solid-state RF substitution:Wide-bandgap semiconductors encroach on sub-50kW broadcast applications. Vacuum capacitors retreat toward higher-power niches where thermal dissipation limits persist.
Strategic Opportunities
- India semiconductor corridor:Gujarat and Tamil Nadu fab incentives under the PLI scheme create first-mover positioning for capacitor suppliers qualifying under BIS standards. Domestic assembly partnerships circumvent import duty structures.
- Medical imaging convergence:MRI gradient amplifiers and proton therapy gantries merge RF power requirements. Dual-use capacitor platforms reduce SKU complexity.
- Japan METI efficiency mandates:Industrial RF equipment loss-tangent standards tighten through 2030. Premium low-loss ceramic formulations command pricing power in replacement markets.
Industry Challenges
- Hermetic sealing artisanry:Glass-to-metal and ceramic-to-metal seal expertise concentrates among aging technician cohorts in Switzerland and Japan. Knowledge transfer bottlenecks constrain capacity scaling.
- Multi-regional certification stacking:Simultaneous FCC, CE, and GB standard compliance extends product development timelines by 8-14 months. Test protocol divergence between US and Chinese electromagnetic compatibility requirements forces parallel validation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vacuum Capacitors Market |
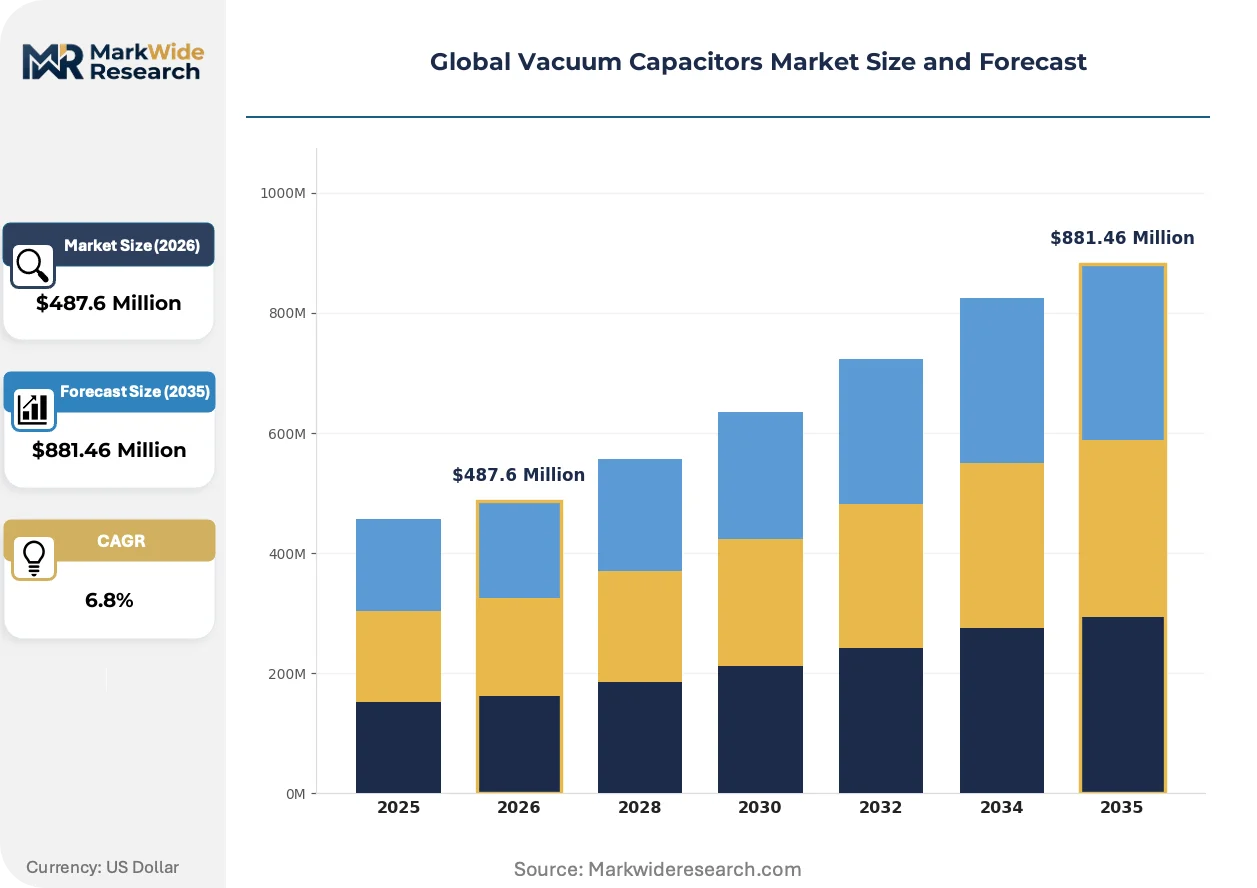
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Specialty Application: RF Amplifiers, Power Electronics, Communication Systems, Medical Equipment End User: Telecommunications, Aerospace, Healthcare, Automotive Technology: Ceramic, Glass, Metal, Polymer |
| Companies Covered | COMET, GLVAC, Meidensha, Richardson Electronics, Highhope, ABB, Omnicor, CG Global, Ross Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vacuum Capacitors Market Strategic Shifts
Envelope material science and electrode cooling architectures are diverging from historical glass-ceramic bifurcation toward application-specific hybrids. Suppliers now engineer for thermal shock resistance in semiconductor tools separately from outgassing purity in medical systems.
Ceramic-metal composite envelopes are fragmenting the traditional glass-versus-ceramic taxonomy. These hybrids bond thin ceramic cylinders to Kovar alloy endcaps for thermal expansion matching in rapid-cycling etcher applications. Lam Research and Applied Materials specify them for 300mm wafer processing nodes. The technology is fragmenting supplier R&D budgets away from unified platform development toward niche specialization.
REACH Article 33 substance disclosure requirements are tightening supply chain documentation burdens for European industrial customers. Ceramic envelope manufacturers must now certify beryllium-free electrode alloys and conflict-mineral-free copper provenance. German and French broadcast transmitter operators increasingly specify full material pedigree as a contract precondition.
Foundry consolidation in South Korea and Taiwan compresses buyer counts while inflating individual procurement volumes. Samsung Display and LG Display now negotiate multi-year capacitor supply agreements with volume commitments exceeding historical annual purchases. Supplier qualification cycles extend to 18-24 months, locking out second-tier vendors from high-volume RF matching network contracts.
Global Vacuum Capacitors Market Segmentation
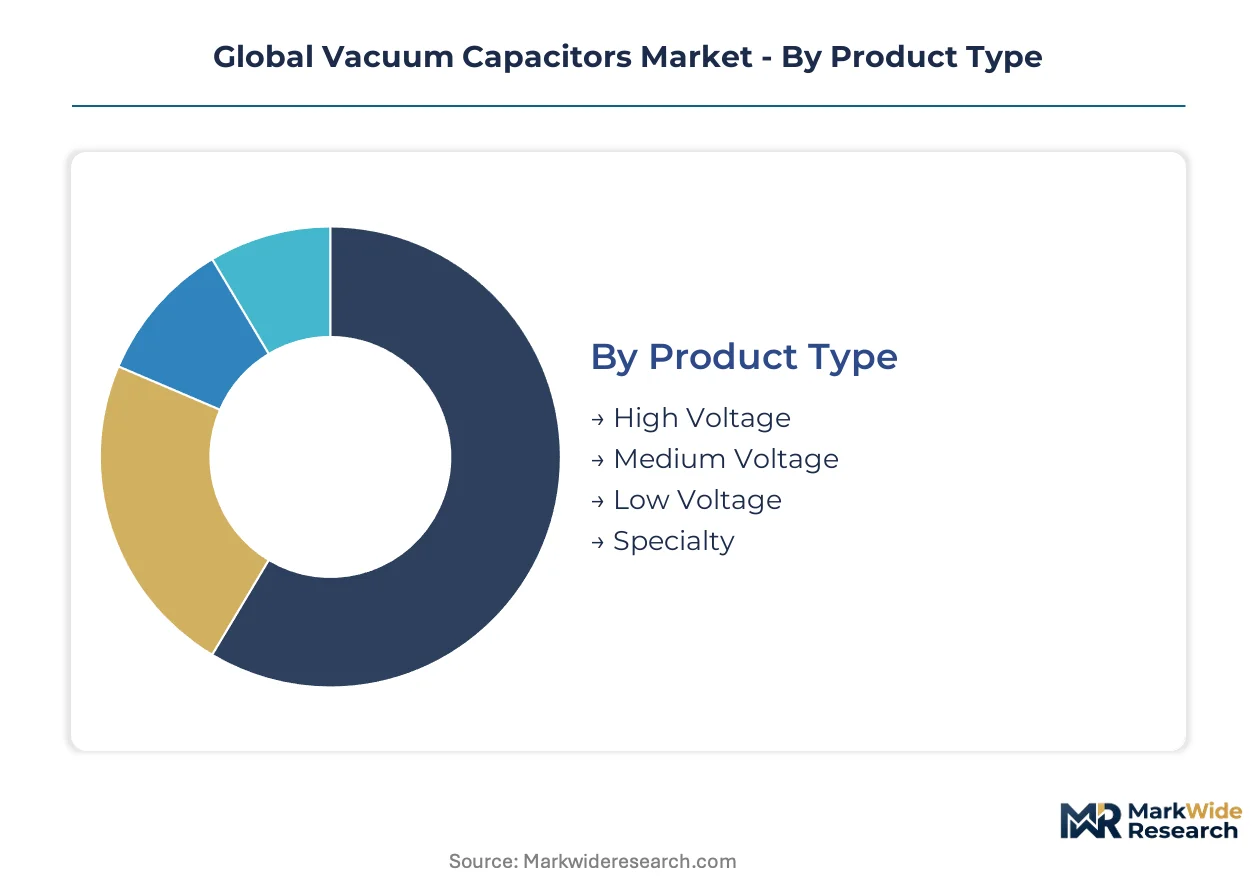
Vacuum capacitor procurement channels diverge sharply by voltage class and end-use certification requirements. Semiconductor tool OEMs in South Korea and Taiwan drive specification intensity through direct technical collaboration, while medical equipment distributors in Germany and the United States manage aftermarket replacement flows.
Product Type:
High-voltage units move through foundry-direct channels with 18-24 month qualification cycles, while low-voltage variants distribute through RF component distributors serving broadcast and telecommunications infrastructure.
- High Voltage:Rated from kilovolts to megavolts across tuning ranges, these hermetically sealed assemblies serve plasma etcher impedance matching networks. Samsung Display and LG Display in South Korea specify them for multi-chamber 300mm wafer processing nodes where thermal cycling tolerance determines tool uptime.
- Medium Voltage:Ceramic-envelope designs dominate this tier for telecommunications base station RF power amplifiers. China's GB standards on insulation coordination shape product architectures for Asia-Pacific deployments, with SAMR enforcement tightening material documentation requirements.
- Low Voltage:Glass-envelope variants retain preference in legacy broadcast transmitter installations across North America and Europe.
- Specialty:Ultra-high-voltage banks for ITER tokamak plasma heating systems in France carry 3-5 year delivery horizons and disproportionate margins despite minimal volumes.
High Voltage dominates installed base. Specialty is where expansion concentrates for suppliers seeking margin protection against copper price volatility.
Application:
Cost tier stratification separates premium impedance matching networks from standard replacement components, with RF amplifier applications commanding 40-50% price premiums over power electronics equivalents.
- RF Amplifiers:Impedance matching networks in semiconductor fabrication tools and broadcast transmitters require ultra-low loss dielectrics. Japanese METI energy efficiency directives tighten loss-tangent specifications through 2030, favoring premium ceramic formulations.
- Power Electronics:Fusion research facilities in France and the United States commission capacitor banks for plasma heating, with procurement timelines extending across multiple fiscal cycles.
- Communication Systems:Telecommunications infrastructure in South Korea and Japan drives ceramic technology unit shipments.
- Medical Equipment:FDA outgassing specifications prove more stringent than industrial applications, preserving glass-envelope preference for MRI gradient amplifiers and proton therapy gantries.
RF Amplifiers anchors revenue concentration. Medical Equipment is climbing the fastest as proton therapy installations multiply across German and Swiss hospital networks.
End User:
Volume concentration in East Asian foundries contrasts with geographic dispersion in aerospace and healthcare, where regulatory fragmentation complicates supplier qualification.
- Telecommunications:Base station deployment cycles in Japan and South Korea sustain ceramic envelope demand for RF power handling.
- Aerospace:Radar systems for military and civilian applications specify hermetic sealing for altitude and temperature extremes.
- Healthcare:MRI and proton therapy equipment manufacturers in Germany and the United States require material pedigree documentation under REACH Article 33 and FDA conflict-mineral rules.
- Automotive:Emerging demand from electric vehicle charging infrastructure and wireless power transfer testing.
Telecommunications holds the largest unit volumes. Healthcare delivers the steepest expansion trajectory as imaging and therapy modalities converge.
Technology:
Supply concentration in Japanese and German specialty chemical producers shapes envelope material availability, with ceramic powder oligopoly risks propagating through manufacturing.
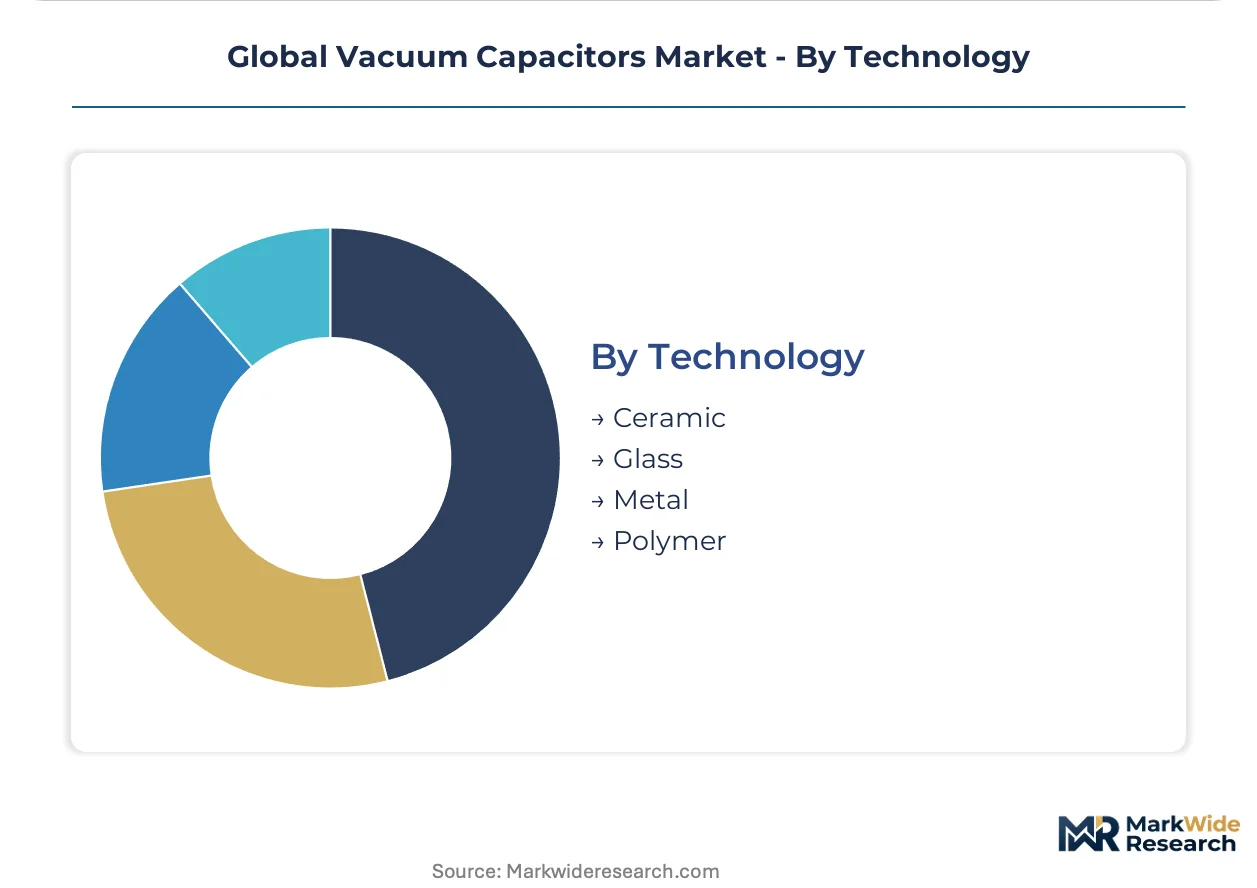
- Ceramic:High-purity alumina cylinders bonded to Kovar alloy endcaps serve rapid-cycling etcher applications. Lam Research and Applied Materials specify these for thermal expansion matching in 300mm wafer processing.
- Glass:Borosilicate and aluminosilicate envelopes retain medical equipment preference where outgassing purity exceeds ceramic alternatives.
- Metal:Ceramic-metal composite hybrids fragment traditional taxonomy for semiconductor tool applications.
- Polymer:Limited penetration in vacuum applications due to thermal and outgassing limitations.
Ceramic leads unit shipments. Metal-envelope hybrids are gaining share fastest as foundry tool specifications diverge from legacy broadcast requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for semiconductor manufacturing is catalyzing new procurement channels as Gujarat and Tamil Nadu build fab capacity. South Korea's display panel foundry corridor concentrates multi-chamber etcher demand. Switzerland and Germany leverage CE marking harmonization to consolidate European industrial RF equipment distribution.
United States
FCC electromagnetic interference mandates elevate specification thresholds for broadcast and radar system capacitors. The FDA enforces stringent outgassing requirements for medical equipment applications. Massachusetts and California host proton therapy and MRI equipment manufacturers sourcing glass-envelope designs.
South Korea
Samsung Display and LG Display negotiate multi-year supply agreements with volume commitments exceeding historical annual purchases. METI energy efficiency directives from Japan indirectly tighten loss-tangent requirements for suppliers serving the Korean market. The Gyeonggi-do corridor anchors multi-chamber 300mm wafer processing node expansion.
China
SAMR enforces GB standards on insulation coordination that shape product architectures for domestic deployments. The dual carbon goals program indirectly pressures industrial RF equipment efficiency specifications. Yangtze River Delta foundry clusters drive ceramic envelope demand for telecommunications infrastructure.
Germany
REACH Article 33 substance disclosure requirements tighten supply chain documentation burdens for industrial customers. ECHA compliance timelines force material substitutions in ceramic envelope formulations. Bavarian broadcast transmitter operators increasingly specify full material pedigree as contract preconditions.
Japan
METI energy efficiency directives for industrial RF equipment tighten loss-tangent requirements through 2030. High-purity alumina supply concentrates among domestic specialty chemical producers. Nagoya and Osaka industrial zones sustain ceramic technology unit shipments for telecommunications base stations.
Global Vacuum Capacitors Market Competitive Environment
Listed leaders compete with private specialists across hermetic sealing expertise and regional certification capabilities. The supplier base concentrates around Swiss and Japanese incumbents with glass-to-metal seal artisanry, while Chinese and Korean challengers scale ceramic envelope production for foundry-direct channels. Two archetypes dominate: premium heritage manufacturers leveraging CE marking convergence, and volume-focused fabricators capturing East Asian semiconductor tool procurement. Competitive moves center on multi-regional certification stacking acceleration and ceramic powder supply security partnerships.
Within the premium heritage tier, COMET leverages its Swiss manufacturing origin to sustain positioning in RF amplifier applications. Richardson Electronics anchors North American distribution through aftermarket service networks. GLVAC and Meidensha occupy positions within East Asian supply chains serving display panel foundry corridors. These named entities exemplify how geographic origin and corporate structure shape competitive positioning without specifying proprietary technologies or customer relationships.
| Leading Market Players |
|---|
| COMET |
| GLVAC |
| Meidensha |
| Richardson Electronics |
| Highhope |
| ABB |
| Omnicor |
| CG Global |
| Ross Engineering |
| Others |
Value Chain & Pricing Dynamics
Multi-chamber etcher deployments in South Korea's Gyeonggi-do corridor generate scale economies that compress unit costs while simultaneously concentrating buyer leverage. This dynamic tightens price floors for fixed-price foundry contracts even as OFHC copper volatility propagates through variable cost structures.
Pricing Analysis
Certification level creates the primary spread between CE-marked industrial units and FDA-grade medical variants. Three-tier pricing structure across premium hermetic-seal artisanry, standard ceramic-envelope production, and economy glass designs anchors transactional models. Cost compression in standard tiers intensifies because wide-bandgap semiconductor substitution erodes sub-50kW broadcast volumes. Semiconductor tool OEMs exhibit lowest price sensitivity given 18-24 month qualification lock-in, while legacy broadcast operators in North America face acute budget pressure from solid-state RF encroachment.
Supply Chain Analysis
Japan and Germany anchor high-purity alumina ceramic powder production for envelope manufacturing. The supply chain draws from OFHC copper electrodes, Kovar alloy endcaps, and beryllium-free electrode alloys. Single-source vulnerability concentrates in Japanese specialty chemical producers where seismic disruption risks propagate through capacitor envelope availability. Distribution runs through foundry-direct channels for high-voltage units and RF component distributors for telecommunications infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor substitution and ITER-scale fusion research are reshaping demand bifurcation in this high-growth disruption. Regulatory divergence between FCC electromagnetic compatibility and SAMR GB standards accelerates R&D fragmentation.
For Market Incumbents: Compound hermetic sealing expertise through knowledge transfer programs targeting Switzerland's aging technician cohorts. Deepen backward integration into high-purity alumina supply partnerships with Japanese specialty chemical producers to defend against ceramic powder oligopoly risks. Accelerate multi-regional certification stacking capabilities to compress 8-14 month validation timelines.
For New Entrants and Emerging Players: Differentiate on rapid-cycling ceramic-metal composite envelopes for 300mm wafer processing nodes. India's Gujarat and Tamil Nadu semiconductor corridors under PLI incentives represent the most penetrable geography with domestic assembly partnerships circumventing import duty structures. Pursue BIS qualification pathways ahead of foundry commissioning timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Swiss and Japanese heritage manufacturers with captive aftermarket service networks for legacy broadcast transmitters. Long-term viability over the projection horizon rests on ceramic envelope specialization rather than glass-envelope commoditization. Target acquisition archetypes combine hermetic sealing artisanry with CE marking convergence capabilities. Monitor ITER and private tokamak commissioning schedules as inflection indicators for ultra-high-voltage specialty demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Powder Supply Security Partnership | Mitigates earthquake disruption risks from Japanese specialty chemical producers. |
| Multi-Regional Certification Acceleration | Compresses parallel FCC, CE, and SAMR validation tracks for foundry-direct channels. |
| Hermetic Sealing Knowledge Transfer Program | Addresses aging technician cohort constraints in Switzerland and Japan. |
| Domestic Assembly Partnership in India | Circumvents BIS import duty structures for Gujarat and Tamil Nadu fab corridors. |
| Low-Loss Ceramic Formulation R&D | Captures METI energy efficiency mandate premiums through 2030. |
Study Parameters
A spread of perspectives from semiconductor tool OEM procurement directors, RF amplifier design engineers, hermetic sealing technicians, ceramic powder supply specialists, and medical equipment regulatory affairs leads converged on the working assumptions. Primary interview insights combined with secondary validation from SEC filings, customs and trade databases, ECHA REACH substance disclosures, and METI efficiency directive documentation. Bottom-up unit shipment estimates triangulated against top-down foundry capital expenditure patterns across the analysis window.
Segmentation dimensions modeled include voltage class, envelope material technology, end-use application, and regional regulatory cluster. CAGRs derived from tool density coefficients in multi-chamber etcher architectures and replacement cycle analysis for legacy broadcast infrastructure. Industry-specific forecast inputs incorporate ITER tokamak plasma heating system commissioning timelines and PLI scheme fab construction schedules.
Material uncertainties — copper price volatility, seismic disruption in Japanese ceramic powder production, and wide-bandgap semiconductor substitution thresholds — sit outside the modeled envelope. Forecasts reflect assumptions about qualification cycle durations and regional certification harmonization trajectories. Recalibration cycles align with material shifts in foundry capital expenditure announcements and fusion research facility procurement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Spin Filters Market