
 IT & Telecom Discrete Semiconductor Market | 2026-2036
IT & Telecom Discrete Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
IT & Telecom Discrete Semiconductor Market Insights
Silicon Carbide is pivoting into RF power applications where thermal performance determines base station reliability. Infineon Technologies AG leverages its wafer fabrication scale to dominate European telecom supply chains for discrete RF components. STMicroelectronics NV anchors its position through captive SiC substrate production that controls cost structures for high-power telecom modules. onsemi Corporation specializes in silicon carbide MOSFET designs optimized for 5G massive MIMO antenna arrays.
IT and Telecom Discrete Semiconductors are non-integrated circuit devices—transistors, diodes, and thyristors—fabricated from compound or elemental semiconductors, typically rated for switching frequencies above 1 GHz and power handling from milliwatts to kilowatts, serving signal amplification and power conversion in communication infrastructure. Transistors command the largest volume share as power amplifiers in cellular base stations, while Gallium Nitride technology captures the fastest expansion due to its breakdown field strength exceeding 3 MV/cm enabling smaller form factors at higher frequencies. Silicon retains maturity in low-cost consumer router applications where thermal budgets permit legacy designs.
FCC equipment authorization rules in the United States mandate electromagnetic compatibility testing that filters out uncertified discrete RF suppliers from telecom infrastructure procurement. REACH restrictions in Europe constrain hexavalent chromium use in semiconductor packaging plating, forcing ROHM Co., Ltd. and Toshiba Electronic Devices & Storage Corp. to reformulate lead frame finishes. Stakeholders must monitor how NMPA certification timelines in China affect qualification schedules for GaN-on-SiC devices destined for domestic 5G network builds.
Market Dynamics
Gallium Nitride-on-Silicon Carbide substrates are compressing amplifier footprints in 5G massive MIMO arrays, forcing incumbent silicon LDMOS suppliers to accelerate process node transitions or cede macro cell transmitter sockets to compound semiconductor foundries.
Growth Catalysts
- 5G Massive MIMO Deployment:Telecom operators in China are densifying urban networks with 64T64R antenna configurations that demand higher power density per square centimeter than legacy silicon can deliver.
- REACH Packaging Reforms:ECHA restrictions on hexavalent chromium plating are compelling European suppliers to adopt trivalent chrome and electroless nickel-palladium-gold finishes that extend component reliability in humid climates.
- GaN-on-SiC Epitaxy Scaling:Domestic Chinese foundries are expanding 6-inch GaN-on-SiC wafer capacity to serve state-directed import substitution programs for base station RF chains.
Market Restraints
- Silicon Carbide Substrate Scarcity:Wolfspeed and Coherent control over 80% of merchant SiC substrate supply creates allocation bottlenecks for GaN RF device manufacturers outside vertically integrated conglomerates.
- Gold Wire Bonding Cost Inflation:Precious metal price volatility in interconnect materials elevates bill-of-materials exposure for high-power discrete transistors rated above 100W.
- Thermal Management Complexity:Diamond composite heat spreaders remain cost-prohibitive for sub-6 GHz base stations, constraining power output in thermally constrained small cell enclosures.
Strategic Opportunities
- Open RAN Disaggregation:O-RAN Alliance specifications are fragmenting traditional integrated radio unit procurement, creating sockets for specialized discrete amplifier vendors to supply white-box base station manufacturers.
- India PLI Incentives:India's production-linked incentive scheme for telecom equipment is attracting GaN foundry investments to serve domestic 5G network builds and export markets.
- Millimeter-Wave Backhaul:E-band and V-band point-to-point links for 5G fronthaul are opening volume opportunities for GaN MMICs operating above 70 GHz where silicon germanium performance degrades.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Foundries report acute shortages of epitaxial growth technicians and RF test engineers capable of characterizing large-signal GaN device parameters.
- FCC Equipment Authorization Timelines:Electromagnetic compatibility certification queues for novel GaN power amplifiers extend lead times by four to six months, compressing product launch windows for infrastructure OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT & Telecom Discrete Semiconductor Market |
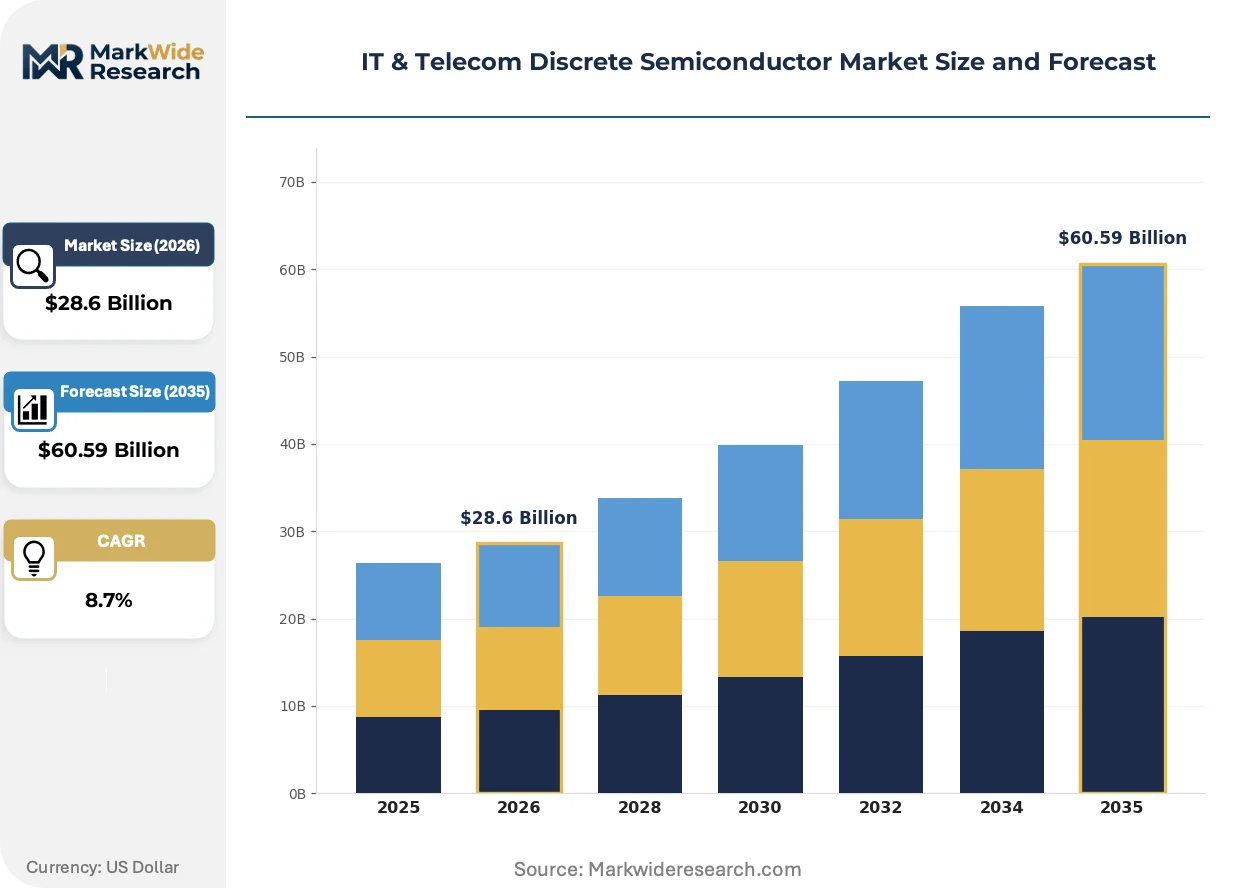
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Transistors, Diodes, Thyristors, ICs Output Power: Low Power, Medium Power, High Power, Ultra High Power Technology: Silicon, Gallium Nitride, Silicon Carbide, GaAs Application: Telecommunication, Consumer Electronics, Computing, Automotive |
| Companies Covered | Infineon Technologies AG, STMicroelectronics NV, onsemi Corporation, Vishay Intertechnology Inc., Toshiba Electronic Devices & Storage Corp., NXP Semiconductors N.V., Diodes Incorporated, ROHM Co., Ltd., Texas Instruments Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT & Telecom Discrete Semiconductor Market Trends and Innovations
Radio frequency front-end architectures are fragmenting into disaggregated subsystems, enabling specialized discrete component suppliers to bypass traditional integrated module vendors and contract directly with open radio access network implementers.
GaN HEMT technology is modularizing power amplifier designs across macro cell, small cell, and distributed antenna system tiers. Base station OEMs are adopting standardized 50-ohm reference planes that allow swappable power pallets without redesigning matching networks. This modularity is compressing qualification cycles from eighteen months to under nine months for second-source amplifier suppliers.
REACH restrictions on hexavalent chromium are mandating wholesale reformulation of lead frame plating chemistries across European supply chains. Semiconductor packaging houses are qualifying trivalent chromium and electroless nickel-palladium-gold alternatives that eliminate carcinogenic process steps. Telecom infrastructure OEMs serving EU markets are now requiring full material disclosure documentation from discrete RF component suppliers.
Carrier procurement departments are consolidating amplifier vendor lists from twelve to four qualified sources per frequency band, privileging suppliers with captive substrate supply and in-house packaging capability. This concentration is displacing fabless GaN designers who lack backward integration into SiC wafer production. Chinese state-owned operators are most aggressive in supplier rationalization, driven by national security screening requirements for critical network infrastructure components.
IT & Telecom Discrete Semiconductor Market Segmentation
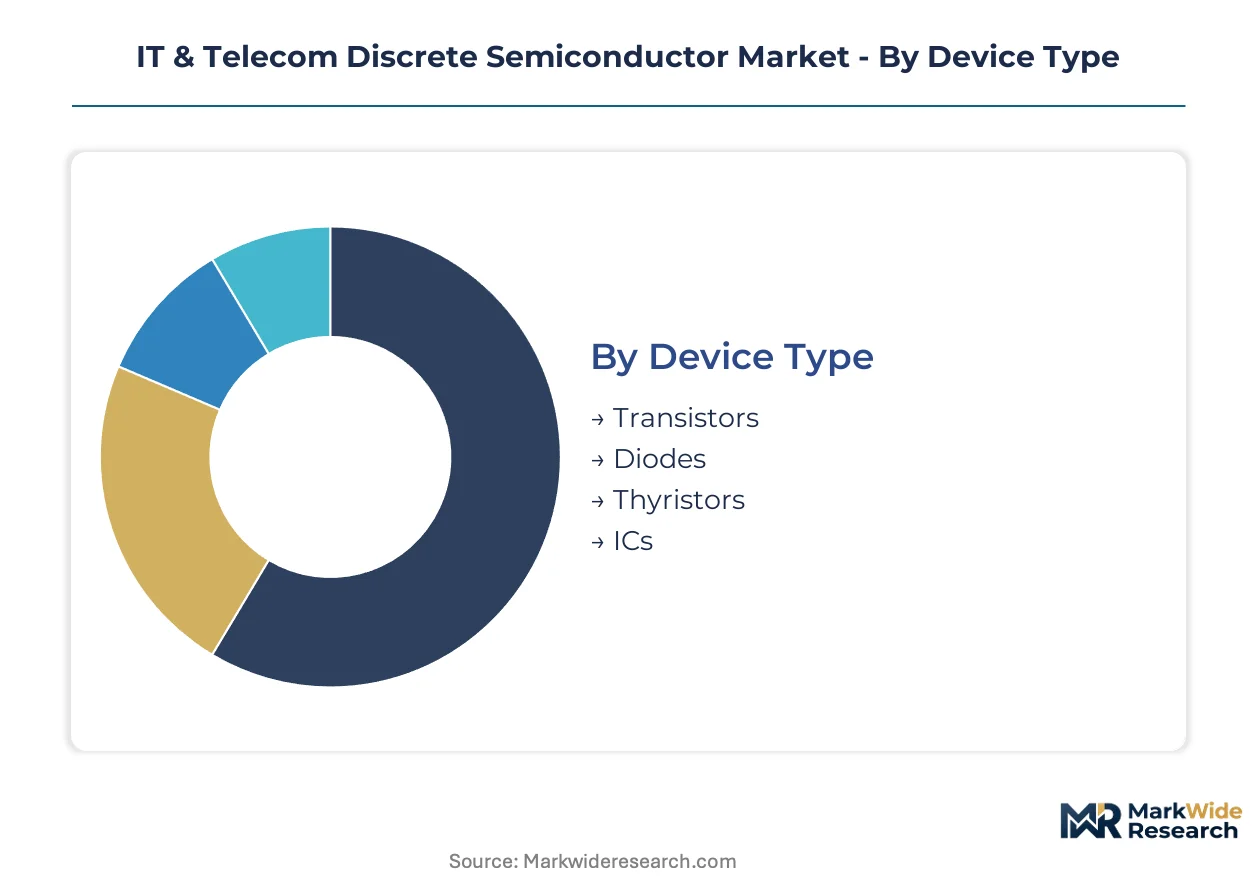
Discrete semiconductor procurement in IT and telecom infrastructure follows distinct technical hierarchies that determine supplier qualification pathways. Equipment manufacturers segment sourcing strategies by power handling thresholds, frequency performance, and thermal constraints rather than treating components as interchangeable commodities.
Device Type:
Upgrade cycles for base station transmitters are accelerating replacement demand for discrete power devices as 5G massive MIMO architectures obsolete legacy silicon LDMOS inventories.
- Transistors:Power amplification in cellular base stations relies on discrete transistors rated for frequencies above 1 GHz. China Telecom and China Mobile procurement tenders specify GaN HEMT devices for 64T64R antenna arrays where power density per square centimeter exceeds silicon capabilities.
- Diodes:Rectification and switching functions in telecom power supplies employ Schottky and PIN diodes. European operators sourcing Open RAN equipment prioritize diodes with REACH-compliant trivalent chromium plating to satisfy ECHA material disclosure requirements.
- Thyristors:Phase-controlled power regulation in legacy macro cell transmitters continues limited procurement for maintenance spares. Indian BSNL network modernization programs are phasing out thyristor-based RF stages in favor of solid-state alternatives.
- ICs:Integrated circuit segments in this classification comprise driver and protection circuits packaged with discrete power devices. Japanese NTT DOCOMO specifications mandate integrated gate drivers for GaN amplifiers to reduce parasitic inductance in millimeter-wave front-ends.
Volume placements concentrate in Transistors; the faster expansion belongs to GaN-configured variants within that segment.
Output Power:
Cost tier differentiation separates qualification pathways for consumer router components from infrastructure-grade power devices subject to carrier certification.
- High Power:Devices rated above 100W serve macro cell transmitters where thermal management determines base station reliability. Wolfspeed and Coherent substrate allocation bottlenecks constrain supply for GaN-on-SiC amplifiers in this tier, privileging vertically integrated suppliers.
- Ultra High Power:Kilowatt-rated discrete semiconductors address broadcast and satellite ground station applications. FCC equipment authorization timelines extend four to six months for novel amplifiers in this category, compressing product launch windows for infrastructure OEMs.
- Medium Power:10-100W devices populate small cell and distributed antenna system tiers. India's PLI scheme for telecom equipment is attracting foundry investments to serve domestic 5G network builds in this power range.
- Low Power:Sub-10W components serve consumer Wi-Fi routers and enterprise access points. Silicon retains maturity here where thermal budgets permit legacy designs and gold wire bonding cost inflation remains manageable.
Revenue concentrates in High Power devices for macro infrastructure; Ultra High Power applications are climbing the fastest as satellite backhaul deployments multiply.
Technology:
Application-specific performance requirements dictate material selection, with thermal conductivity and breakdown field strength determining suitability for frequency bands and power levels.
- Gallium Nitride:GaN HEMT technology achieves breakdown field strength exceeding 3 MV/cm, enabling smaller form factors at higher frequencies. Domestic Chinese foundries are expanding 6-inch GaN-on-SiC wafer capacity to serve state-directed import substitution programs.
- Silicon Carbide:SiC substrates provide thermal conductivity above 400 W/mK for RF power applications. STMicroelectronics anchors its position through captive SiC substrate production that controls cost structures for high-power telecom modules.
- Silicon:LDMOS transistors retain cost advantages in sub-6 GHz applications where thermal budgets permit legacy designs. Consumer router manufacturers in Taiwan continue silicon sourcing for 2.4 GHz and 5 GHz Wi-Fi front-ends.
- GaAs:Gallium Arsenide devices address niche millimeter-wave applications above 70 GHz where silicon germanium performance degrades. E-band and V-band point-to-point links for 5G fronthaul sustain limited demand for GaAs MMICs.
Silicon maintains volume dominance in consumer applications; Gallium Nitride is gaining share fastest as 5G massive MIMO deployment accelerates.
Application:
Customer type segmentation reveals divergent procurement patterns between carrier infrastructure teams and enterprise IT departments with distinct certification requirements.
- Telecommunication:Carrier-grade base stations and backhaul equipment demand discrete semiconductors qualified to 3GPP and O-RAN Alliance specifications. Open RAN disaggregation is fragmenting traditional integrated radio unit procurement, creating sockets for specialized discrete amplifier vendors.
- Computing:Data center power conversion and server motherboard voltage regulation employ discrete MOSFETs and diodes. Hyperscale operators in the United States specify 80 PLUS Titanium efficiency standards that favor GaN-based totem-pole PFC stages.
- Consumer Electronics:Smartphone RF front-end modules and laptop power adapters consume low-power discrete devices. Chinese ODMs concentrate procurement for USB-C PD controllers and GaN-based compact chargers.
- Automotive:Connected vehicle telematics and V2X communication modules require automotive-grade discrete semiconductors. AEC-Q100 qualification timelines extend component development cycles for suppliers targeting this adjacent market.
Procurement volume clusters in Telecommunication infrastructure; Computing applications are expanding most quickly as hyperscale data center construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate GaN-on-SiC foundry investments. State-directed import substitution programs accelerate domestic capacity for 5G base station components. Equipment manufacturers cluster in Shanghai and Suzhou industrial parks.
United States
FCC equipment authorization rules filter uncertified discrete RF suppliers from telecom infrastructure procurement. The IRA provides domestic manufacturing incentives for compound semiconductor production. Austin and Phoenix anchor GaN device design clusters serving Open RAN implementers.
China
NMPA certification timelines affect qualification schedules for GaN-on-SiC devices destined for domestic 5G network builds. MIIT directs state-owned operators to consolidate amplifier vendor lists for national security screening. Beijing-Tianjin-Hebei corridor houses captive substrate production for vertically integrated conglomerates.
Germany
REACH restrictions constrain hexavalent chromium use in semiconductor packaging plating, forcing reformulation of lead frame finishes. ECHA material disclosure requirements now govern telecom infrastructure OEM procurement. Bavaria's semiconductor packaging houses qualify trivalent chrome alternatives for humid climate reliability.
Japan
METI specifications mandate integrated gate drivers for GaN amplifiers to reduce parasitic inductance in millimeter-wave front-ends. Kanto region manufacturers supply driver and protection circuits packaged with discrete power devices. Tokyo-Osaka industrial corridor concentrates RF test engineering talent for large-signal GaN characterization.
India
TRAI spectrum allocations enable 5G network densification requiring higher power density components. PLI scheme incentives attract GaN foundry investments to serve domestic builds and export markets. Karnataka and Telangana host emerging design centers for medium-power small cell applications.
IT & Telecom Discrete Semiconductor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The supplier base concentrates around vertically integrated conglomerates with captive substrate supply and in-house packaging capability. Three archetypes dominate: European diversified semiconductor conglomerates, Japanese precision component specialists, and American fabless designers with foundry partnerships. Competitive moves center on backward integration into SiC wafer production and strategic consolidation of amplifier vendor lists by carrier procurement departments.
Within the European conglomerate tier, Infineon Technologies AG and STMicroelectronics NV exemplify scale-driven positions anchored by wafer fabrication assets. STMicroelectronics occupies a position reinforced by captive SiC substrate production. Among American suppliers, onsemi Corporation represents the specialized RF power archetype. These three entities sit within the premium tier where carrier certification requirements and substrate allocation bottlenecks privilege established players with integrated manufacturing footprints.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics NV |
| onsemi Corporation |
| Vishay Intertechnology Inc. |
| Toshiba Electronic Devices & Storage Corp. |
| NXP Semiconductors N.V. |
| Diodes Incorporated |
| ROHM Co., Ltd. |
| Texas Instruments Inc. |
| Others |
Pricing and Supply Chain Analysis
Gold wire bonding cost inflation cascades through amplifier bill-of-materials, stratifying procurement into three tiers: vertically integrated conglomerates absorb precious metal volatility through captive substrate supply, mid-tier foundries pass through interconnect cost swings via quarterly price adjustments, and fabless designers face margin compression when carrier procurement departments consolidate vendor lists.
Pricing Analysis
Lead-time-driven pricing separates urgent procurement premiums from spot inventory discounts across GaN-on-SiC amplifier markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FCC-authorized devices commanding sustained premiums over uncertified alternatives. Cost compression in high-power macro cell transmitters is intensifying because Wolfspeed and Coherent substrate allocation bottlenecks constrain supply, forcing smaller OEMs toward price-sensitive medium-power small cell tiers where silicon retains cost advantages.
Supply Chain Analysis
Epitaxial growth technician shortages in China's Yangtze River Delta and Arizona's Phoenix corridor constrain wafer throughput expansion. Taiwan and South Korea anchor merchant GaN-on-SiC foundry capacity, while Japan's Kanto region supplies driver and protection circuit integration. Supply chain risk centers on single-source vulnerability for 6-inch SiC substrates, with distribution running through carrier-direct contracts and Open RAN white-box manufacturer procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate scarcity props pricing power for vertically integrated suppliers, creating a supply-constrained market where capacity bottlenecks outpace demand absorption.
For Market Incumbents: Lock in long-term offtake agreements with Wolfspeed and Coherent before substrate allocation queues extend further, while accelerating in-house packaging capability to satisfy carrier material disclosure requirements. Threatened by Chinese state-directed import substitution programs, incumbents must deepen backward integration into SiC wafer production or cede macro cell sockets to domestic champions. For New Entrants and Emerging Players: GaN-on-Silicon technology offers a technology-first wedge into consumer router and enterprise access point tiers where thermal budgets permit lower-cost substrates. India's PLI scheme for telecom equipment represents the most penetrable geography, with Karnataka and Telangana design centers enabling medium-power small cell qualification without competing directly for scarce SiC substrate allocation. For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless GaN designers with qualified amplifier designs but strained working capital in the United States and Europe. Long-term viability hinges on acquisition targets securing alternative substrate supply or pivoting to GaN-on-Silicon architectures. Watch NMPA certification timeline compression in China as the inflection indicator—accelerated approvals signal state-backed domestic capacity maturation that would strand non-integrated foreign assets.| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Production | STMicroelectronics controls cost structures through in-house wafer supply, insulating margins from merchant allocation bottlenecks. |
| Open RAN Amplifier Socket Capture | Specialized discrete vendors bypass integrated module suppliers by contracting directly with O-RAN Alliance implementers. |
| REACH-Compliant Packaging Reformulation | ROHM and Toshiba eliminated hexavalent chromium to satisfy ECHA material disclosure requirements for European telecom OEMs. |
| India PLI Scheme Foundry Investment | Domestic GaN capacity buildout serves TRAI-enabled 5G densification while capturing export demand from supply-constrained markets. |
| Millimeter-Wave Backhaul MMIC Development | E-band and V-band point-to-point links above 70 GHz exploit GaAs performance where silicon germanium degrades. |
Research Methodology
Multi-period observation of carrier procurement tender awards, substrate allocation announcements, and equipment authorization timelines anchored the trend analysis, supplemented by interviews with GaN device design engineers, RF test engineering directors, telecom infrastructure procurement managers, and semiconductor packaging house operations leads. Secondary validation drew from FCC equipment authorization databases, ECHA REACH restriction updates, MIIT directive releases, SEC 10-K filings from listed semiconductor suppliers, and 3GPP specification releases. Bottom-up and top-down triangulation cross-checked wafer capacity announcements against carrier deployment schedules.
Segment-weighting across device type, output power tier, technology material, and application vertical informed the analytical framework over the projection horizon. CAGRs derived from installed base replacement cycles, technology displacement curves, and carrier capex commitment trajectories. Industry-specific forecast inputs incorporated Open RAN disaggregation pace and NMPA certification velocity for GaN-on-SiC devices.
Several conditions sit outside the modeled scope, including unannounced substrate capacity expansions, abrupt tariff regime shifts on compound semiconductor trade, and breakthrough silicon LDMOS performance advances that could delay GaN displacement timelines. Forecasts reflect documented assumptions about carrier procurement consolidation and state-directed import substitution intensity. Material deviation in FCC authorization queue lengths or MIIT vendor list consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market