
 FPGA Market | 2026-2036
FPGA Market Size, Share, and Industry Trends Forecast 2026-2036
FPGA Market Analysis
Market Context
Automotive sensor fusion and autonomous driving platforms are broadening FPGA demand beyond traditional telecom infrastructure. Advanced Micro Devices, Inc. leverages its Xilinx acquisition to dominate high-performance adaptive computing for data center acceleration. Intel Corporation sustains manufacturing scale through its Intel Foundry Services arm, anchoring supply for defense-qualified programmable logic. Lattice Semiconductor Corporation specializes in ultra-low power architectures, competing aggressively in edge AI and industrial vision applications.
Technical Definition and Segment Structure
Field-programmable gate arrays are semiconductor devices comprising configurable logic blocks and programmable interconnects that engineers reconfigure post-manufacture using hardware description languages, with lookup tables typically implementing 4-to-6 input combinational functions and flip-flops providing sequential logic storage. Their primary commercial purpose is enabling rapid prototyping and volume-flexible deployment where non-recurring engineering costs for custom ASICs prove prohibitive or where algorithms evolve faster than silicon revision cycles permit. SoC FPGA variants integrating ARM Cortex processors and dedicated AI engines are capturing the fastest expansion as embedded systems demand heterogeneous compute at the edge. High-performance FPGA lines command the deepest margin pools in data communication and signal processing, while low-cost FPGA segments face commoditization pressure from expanding Chinese suppliers.
Regulatory Framework
US Bureau of Industry and Security export controls, EU dual-use regulation, and China's GB standards for information security shape FPGA market access by restricting transfer of advanced programmable logic to designated entities and mandating cryptographic certification for domestic procurement. These frameworks fragment supply chains as vendors maintain separate product SKUs for US-controlled, EU-autonomous, and China-compliant channels. Stakeholders must monitor evolving semiconductor equipment restrictions and sovereign compute initiatives to anticipate which programmable logic tiers face next-wave trade barriers.
Market Dynamics
Programmable logic vendors face structural pressure from US Bureau of Industry and Security export controls fragmenting product roadmaps into jurisdiction-specific SKUs, while aerospace and defense procurement accelerates demand for reconfigurable silicon over fixed-function ASICs.
Growth Catalysts
- EU Cyber Resilience Act:Mandates embedded cybersecurity certification for connected devices, forcing automotive and industrial OEMs toward FPGAs with hardware root-of-trust capabilities rather than vulnerable processor-only architectures.
- 5G base station deployment:China's domestic infrastructure buildout consumes high-bandwidth programmable logic for massive MIMO beamforming, creating concentrated demand for RF-optimized FPGA lines.
- Sensor fusion architectures:Autonomous driving platforms integrate lidar, radar, and camera pipelines through programmable logic, as deterministic latency requirements exceed GPU scheduling guarantees.
Market Restraints
- Advanced packaging substrate shortage:CoWoS and EMIB capacity constraints at TSMC and Intel Foundry Services bottleneck high-performance FPGA deliveries, extending lead times for data center acceleration cards.
- ASIC NRE cost compression:Google's TPU and Amazon's Trainium demonstrate that hyperscale captive silicon achieves unit economics rivaling FPGA flexibility at volume, threatening mid-range programmable logic sockets.
- US export control fragmentation:BIS Entity List restrictions force vendors to maintain parallel silicon revisions, inflating R&D overhead and complicating inventory management across supply channels.
Strategic Opportunities
- Edge AI inference:Ultra-low-power FPGA families enable milliwatt-class neural network acceleration in battery-constrained industrial sensors and medical wearables, displacing microcontroller-plus-accelerator two-chip solutions.
- India PLI scheme:Production-linked incentives for electronics manufacturing attract programmable logic packaging and test investment, creating regional supply hubs for defense and telecom procurement.
- Post-quantum cryptography migration:NIST-standardized lattice algorithms require hardware acceleration for acceptable performance, opening FPGA sockets in government and financial infrastructure ahead of ASIC availability.
Industry Challenges
- Hardware description language expertise scarcity:RTL design talent concentrates at legacy vendors and defense contractors, forcing system houses to rely on high-level synthesis tools with suboptimal quality-of-results.
- Multi-die integration complexity:Chiplets and 3D stacking architectures demand thermal and signal integrity co-design capabilities that stretch traditional FPGA vendor support models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FPGA Market |
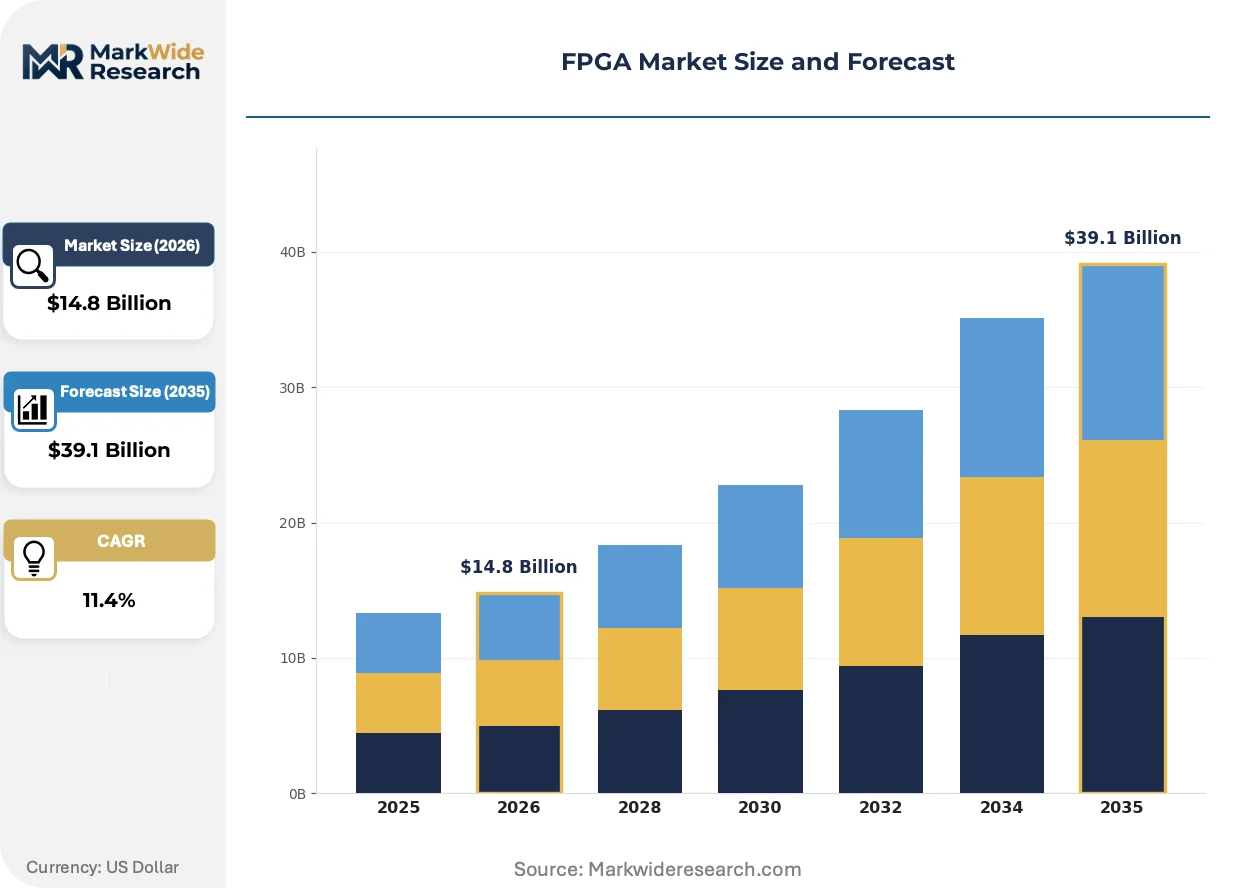
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Cost FPGA, High-Performance FPGA, Ultra-Low Power FPGA, SoC FPGA End User: Aerospace, Defense, Telecommunications, Automotive Technology: SRAM-Based, Flash-Based, Antifuse, Mixed-Technology Application: Signal Processing, Data Communication, Embedded Systems, Video Processing |
| Companies Covered | Advanced Micro Devices, Inc., Intel Corporation, Lattice Semiconductor Corporation, Microchip Technology Inc., Achronix Semiconductor Corporation, QuickLogic Corporation, Efinix, Inc., GOWIN Semiconductor Corporation, FlexLogix Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FPGA Market Emerging Trajectories
Heterogeneous compute integration and sovereign silicon mandates are compressing FPGA product cycles while expanding the addressable market beyond traditional hardware prototyping into production deployment at scale.
AI engines embedded within programmable fabric are rewriting the competitive boundary between FPGAs and dedicated neural processors. Automotive tier-1 suppliers now specify adaptive SoCs for real-time perception pipelines, compressing algorithm-to-silicon deployment from 18 months to under six weeks. This velocity is eroding GPU incumbency in latency-sensitive inference workloads.
REACH substance restrictions and EU AI Act conformity requirements are forcing programmable logic vendors to pre-certify hardware security modules and document training data provenance for edge AI deployments. Industrial automation OEMs in Germany and France now demand CE-marked adaptive computing modules with embedded cryptographic accelerators, shifting procurement evaluation criteria from raw LUT count to compliance bundling.
Hyperscale buyers are consolidating FPGA procurement through direct foundry relationships and custom silicon programs, bypassing traditional distribution. Cloud service providers in North America and China now specify die-level traceability and country-of-origin wafer documentation, displacing value-added reseller channels for volume deployments. This concentration is visible most acutely in AI training infrastructure procurement, where single buyers represent multi-million-unit annual demand.
FPGA Market Segmentation
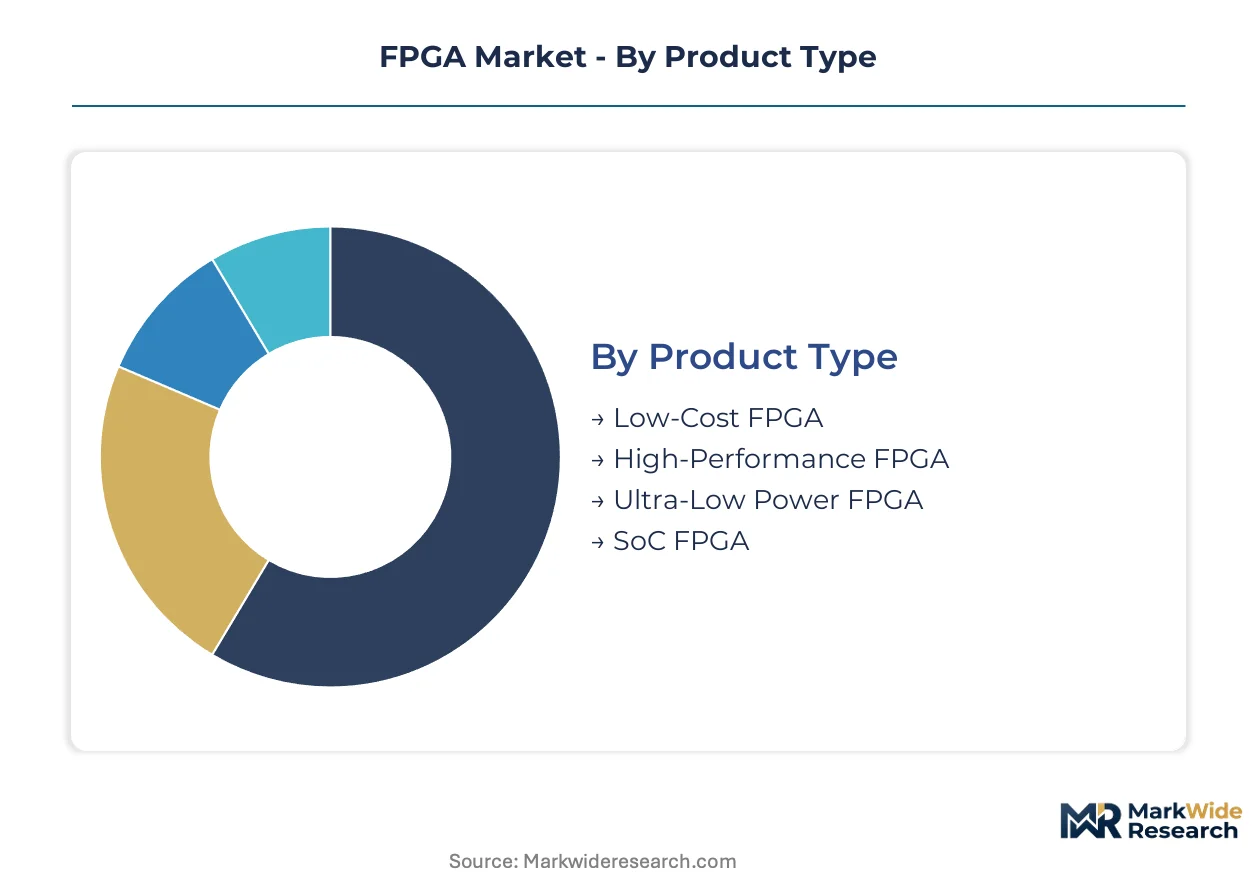
FPGA segmentation reveals how programmable logic vendors architect product portfolios around divergent power budgets, reconfigurability requirements, and security postures. Each dimension—product type, end user, technology, and application—carries distinct margin profiles and competitive dynamics that shape vendor resource allocation.
Product Type:
Upgrade cycles vary dramatically across product tiers, with aerospace and defense customers holding platforms for 15-20 years while data center acceleration cards refresh every 3-4 years.
- High-Performance FPGA:These devices integrate millions of logic elements with high-speed transceivers operating at 112 Gbps and beyond, targeting AI training infrastructure and 5G baseband processing. Demand concentrates in China for domestic massive MIMO deployments and in US hyperscale data centers for SmartNIC acceleration, constrained by CoWoS packaging capacity at TSMC.
- SoC FPGA:Heterogeneous devices embed ARM Cortex-A53 or RISC-V cores alongside programmable fabric, enabling single-chip implementation of complex control loops. Automotive tier-1 suppliers in Germany and Japan specify these for sensor fusion gateways, driven by deterministic latency requirements that disqualify discrete processor-plus-FPGA architectures.
- Low-Cost FPGA:Entry-level devices with 10K-100K logic cells serve industrial motor control and LED display driving. Chinese suppliers are compressing pricing in this tier through mature-node manufacturing.
- Ultra-Low Power FPGA:Sub-milliwatt static power consumption enables always-on voice wake-word detection and battery-powered medical sensors. Lattice Semiconductor and QuickLogic dominate this niche with specialized SRAM architectures.
High-Performance FPGA sits at the top of the volume ranking, with SoC FPGA climbing the fastest.
End User:
Customer procurement patterns split between long-platform-life defense programs and fast-iterating commercial deployments.
- Telecommunications:Equipment vendors including Ericsson, Nokia, and Huawei consume programmable logic for baseband processing, fronthaul aggregation, and timing synchronization. China's domestic 5G buildout drives concentrated demand for RF-optimized devices with integrated digital predistortion, while Open RAN disaggregation in Europe and India creates sockets for smaller-form-factor FPGAs in distributed units.
- Automotive:Tier-1 suppliers integrate adaptive SoCs for lidar point-cloud preprocessing, camera ISP pipelines, and radar signal conditioning. German OEMs now mandate ISO 26262 ASIL-D certification for programmable logic in autonomous driving domains, extending qualification cycles but deepening vendor incumbency.
- Aerospace:Satellite payload processing and avionics systems favor antifuse-based devices for radiation tolerance and configuration permanence. NASA and ESA qualification requirements limit qualified vendor pools to Microchip and Lattice.
- Defense:Electronic warfare and signals intelligence systems require rapid algorithm reconfiguration in the field. US Department of Defense procurement is shifting from ASICs to reprogrammable logic to counter adversary adaptation cycles.
Telecommunications commands the largest revenue share, with Automotive expanding most quickly as ADAS penetration deepens.
Technology:
Fabric architecture selection involves trade-offs between reconfigurability speed, power consumption, and security against configuration tampering.
- SRAM-Based:Dominant architecture using volatile lookup tables loaded from external flash at power-up, enabling unlimited reconfiguration. Xilinx and Intel ship primarily SRAM devices for commercial applications where power-on latency is acceptable.
- Flash-Based:Non-volatile configuration storage eliminates external boot memory and enables instant-on operation. Microchip's IGLOO and ProASIC3 families serve power-sensitive industrial and medical applications where configuration security matters.
- Antifuse:One-time programmable links provide radiation hardness and configuration tamper resistance. Microchip RTAX-S devices hold qualified positions in spaceflight and strategic weapons systems where reprogramming is prohibited.
- Mixed-Technology:Hybrid architectures combining SRAM programmable fabric with flash configuration storage or embedded non-volatile memory blocks. These target industrial automation requiring both field upgradability and fast boot times.
SRAM-Based technology anchors commercial volume, with Flash-Based architectures gaining share in edge AI and battery-constrained deployments.
Application:
Workload characteristics determine whether FPGA acceleration outperforms GPU or ASIC alternatives on latency, power, or flexibility metrics.
- Data Communication:SmartNICs, load balancers, and encryption offload engines leverage FPGA packet processing at line rate. Hyperscale buyers in the US and China specify custom acceleration cards with direct foundry relationships, bypassing traditional distribution.
- Signal Processing:Radar, sonar, and software-defined radio systems exploit FPGA parallelism for FFT and filter bank implementation. Defense contractors in the US, UK, and Israel maintain captive FPGA design teams for classified algorithm protection.
- Embedded Systems:Industrial controllers and medical devices integrate programmable logic for deterministic I/O timing and safety-critical shutdown logic. EU machinery directives and FDA device regulations are mandating hardware-based safety monitors.
- Video Processing:Broadcast encoders, surveillance analytics, and medical imaging systems use FPGA parallelism for real-time compression and AI inference. Japanese broadcast equipment vendors specify 8K HEVC encoding engines with sub-frame latency guarantees.
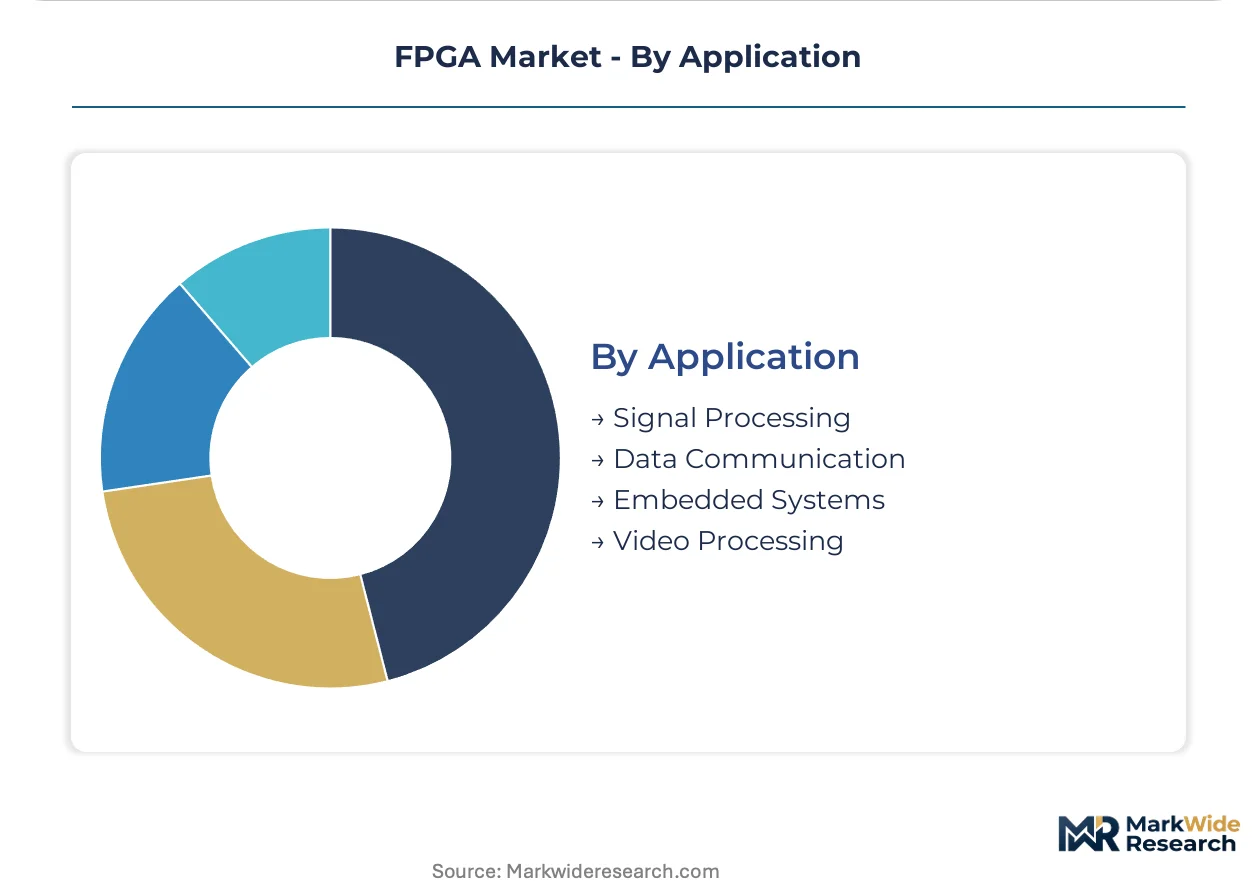
Data Communication leads application revenue, with Signal Processing showing steepest expansion trajectory driven by defense modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor concentrates programmable logic demand for 5G infrastructure and consumer electronics acceleration, drawing FPGA procurement from domestic base station builders and export-oriented hardware developers.
United States
Hyperscale data center operators in Northern Virginia and Oregon drive SmartNIC and AI training accelerator procurement. The Bureau of Industry and Security maintains Entity List restrictions on advanced semiconductor exports to designated Chinese entities. Austin and San Jose host defense contractor design centers developing reprogrammable logic for electronic warfare systems.
China
Domestic 5G massive MIMO deployment and automotive sensor fusion applications absorb high-bandwidth programmable logic. MIIT enforces GB standards for information security in critical infrastructure procurement. The Yangtze River Delta cluster around Shanghai supplies packaging and test capacity for local FPGA vendors serving state-directed semiconductor independence programs.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich specify adaptive SoCs for autonomous driving perception pipelines. The KBA mandates ISO 26262 ASIL-D certification for programmable logic in safety-critical vehicle domains. Bavaria's industrial automation corridor demands hardware security modules compliant with EU machinery directives.
Japan
Broadcast equipment vendors in Tokyo specify 8K HEVC encoding engines with sub-frame latency guarantees. METI promotes sovereign compute initiatives reducing dependence on foreign programmable logic for critical infrastructure. The Kansai region around Osaka maintains captive FPGA design teams for medical imaging and industrial vision applications.
South Korea
Memory semiconductor manufacturers in Seoul and Pyeongtaek integrate programmable logic for test and validation equipment. The MFDS regulates hardware-based safety monitors in medical device certification. The Busan-Ulsan industrial complex consumes low-latency signal processing chips for shipbuilding sonar and offshore radar systems.
FPGA Market Vendor Landscape
Strategic acquisitions dominate the current landscape as semiconductor conglomerates absorb specialized programmable logic vendors to secure adaptive computing portfolios. The vendor base concentrates around three large-scale integrated manufacturers with captive foundry relationships, while mid-tier specialists defend niche positions in ultra-low-power and radiation-hardened segments. Two strategic archetypes prevail: diversified semiconductor giants leveraging manufacturing scale, and focused FPGA pure-plays emphasizing application-specific optimization. Competitive moves center on foundry capacity reservation and jurisdiction-specific product SKU development to navigate export control fragmentation.
Within the diversified semiconductor tier, Advanced Micro Devices, Inc. and Intel Corporation exemplify scale-driven positioning through integrated manufacturing and data center acceleration focus. Lattice Semiconductor Corporation occupies the specialized tier, representing ultra-low-power architecture development for edge AI and industrial vision sockets. These three entities anchor the competitive structure, with Chinese suppliers including GOWIN Semiconductor Corporation emerging as cost-competitive alternatives in mature-node, low-complexity programmable logic segments.
| Leading Market Players |
|---|
| Advanced Micro Devices, Inc. |
| Intel Corporation |
| Lattice Semiconductor Corporation |
| Microchip Technology Inc. |
| Achronix Semiconductor Corporation |
| QuickLogic Corporation |
| Efinix, Inc. |
| GOWIN Semiconductor Corporation |
| FlexLogix Technologies |
| Others |
Supply Flow & Price Mechanics
Captive foundry capacity at TSMC and Intel Foundry Services anchors pricing power for high-performance FPGA lines, while outsourced packaging dependencies constrain margin expansion across the programmable logic tier. This integration pattern separates vendors with wafer-level control from fabless competitors exposed to CoWoS substrate shortages and advanced packaging bottlenecks.
Pricing Analysis
Input-cost pass-through from silicon wafer and advanced substrate expenses shapes FPGA pricing structures across product tiers. Three-tier pricing stratification separates radiation-hardened aerospace devices from commercial SRAM-based lines and cost-optimized Chinese alternatives. Price differentiation hinges on certification grade—ISO 26262 ASIL-D automotive qualification commands substantial premiums over industrial-grade offerings—and volume scale, with hyperscale buyers negotiating direct foundry pricing that undercuts distribution channels. Cost compression in low-complexity segments is intensifying because GOWIN Semiconductor and domestic Chinese suppliers exploit mature-node manufacturing economics. Automotive tier-1 suppliers exhibit the lowest price sensitivity due to safety-critical qualification requirements, while consumer electronics integrators drive aggressive procurement terms for high-volume sockets.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for data center acceleration cards, displacing traditional value-added reseller relationships. Manufacturing concentration rests on Taiwan for leading-edge wafer fabrication at TSMC, the United States for Intel Foundry Services production, and China for mature-node packaging and domestic vendor supply. Raw material dependencies include silicon wafers, ABF substrates for advanced packaging, and specialized chemicals for etching and deposition processes. Single-source vulnerability at CoWoS packaging capacity creates delivery risk for high-bandwidth FPGA lines serving AI training infrastructure. Distribution runs through authorized distributors for mid-market industrial and automotive procurement, with defense contractors maintaining direct vendor relationships for ITAR-controlled devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FPGA procurement is shifting toward premium specifications as automotive safety certification and post-quantum cryptography hardware requirements displace commodity programmable logic. This late-cycle quality story favors vendors with embedded security IP and radiation-hardened product lines over cost-optimized competitors.
For Market Incumbents: Hedge against hyperscale captive silicon programs by deepening heterogeneous compute integration and reserving advanced packaging capacity through multi-year foundry commitments. Defensive moves center on jurisdiction-specific SKU development to navigate US Bureau of Industry and Security export controls, alongside certification investment for EU Cyber Resilience Act compliance. Vertical integration into embedded AI engines displaces discrete accelerator competition in edge inference sockets. For New Entrants and Emerging Players: Capture white-space in ultra-low-power medical wearables and battery-constrained industrial sensors where Lattice Semiconductor's SRAM architectures hold limited presence. The most penetrable segment spans post-quantum cryptography acceleration ahead of ASIC availability, targeting government and financial infrastructure procurement. Go-to-market execution requires hardware security module bundling to meet EU machinery directive compliance mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where export control fragmentation inflates R&D overhead and complicates inventory management across parallel silicon revisions. Long-term viability over a multi-year window favors vendors with captive foundry relationships and defense-qualified product portfolios. Acquisition target archetypes include radiation-hardened specialists with NASA and ESA qualifications. The signal to watch is sovereign compute initiative funding levels in Japan and South Korea as indicators of captive demand creation.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Reservation | Secures CoWoS and EMIB supply for high-bandwidth FPGA lines serving AI training infrastructure. |
| Jurisdiction-Specific SKU Development | Enables compliance with US BIS export controls, EU dual-use regulation, and China GB standards. |
| Embedded AI Engine Integration | Compresses algorithm-to-silicon deployment timelines for automotive sensor fusion applications. |
| Post-Quantum Cryptography Hardware Certification | Opens FPGA sockets in government infrastructure ahead of NIST-standardized ASIC availability. |
| Radiation-Hardened Product Line Acquisition | Deepens incumbency in satellite payload processing with NASA and ESA qualification requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct the FPGA market analysis. Primary fieldwork engaged programmable logic vendor product managers, automotive tier-1 supplier procurement directors, defense contractor hardware architects, and hyperscale data center infrastructure planners. Secondary validation drew from Bureau of Industry and Security export control filings, MIIT GB standard documentation, SEC semiconductor company disclosures, and ESA/NASA qualification databases. Bottom-up demand modeling across end-use applications triangulated against top-down supply-side capacity assessments.
Segment-weighting approaches distributed volume and value projections across product type, end user, technology architecture, and application workload dimensions. The analytical framework incorporated heterogeneous compute integration velocity, sovereign silicon initiative funding trajectories, and defense procurement shifts from ASICs to reprogrammable logic. CAGRs were derived from regression analysis of historical shipment data and elasticity-adjusted demand curves. Industry-specific forecast inputs included 5G base station deployment schedules and automotive ADAS penetration assumptions.
Export control escalation, advanced packaging substrate availability constraints, and hyperscale captive silicon program acceleration are the dominant revision risks to baseline projections. Forecasts reflect assumptions regarding foundry capacity allocation, regulatory enforcement intensity, and algorithm-hardware co-design adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
MBE Components Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market