
 Global Precision Parts Market | 2026-2036
Global Precision Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Parts Market Outlook
Aftermarket service revenue is reconfiguring margin pools away from pure component sales across the precision parts sector. Barnes Group Inc. leverages its aerospace aftermarket footprint to capture recurring maintenance streams. Sandvik AB anchors its position through captive supply of cemented carbide tool materials that downstream fabricators depend upon. Mecachrome Group specializes in complex titanium aerostructures for engine programs where technical barriers limit competitor entry.
Precision parts are engineered components manufactured to tight dimensional tolerances, typically within micrometers, using processes such as CNC machining, electrical discharge machining, or additive manufacturing to achieve specified surface finishes and geometric accuracy for critical functional assemblies. Mechanical components dominate current output volumes across aerospace and industrial equipment applications where fatigue resistance and interchangeability standards govern procurement. Electronic parts represent the fastest-expanding category as medical devices and automotive sensor housings require miniaturized conductive assemblies with hermetic sealing properties. Composite material segments command premium positioning due to autoclave curing complexity and the limited number of qualified suppliers serving aviation certification pathways.
The EPA enforces machining coolant discharge limits that elevate environmental compliance costs for US-based fabricators, while REACH restricts chromium-based surface treatments across European supply chains, forcing conversion to trivalent passivation chemistries. China's SAMR enforces GB standards on dimensional tolerances for exported aluminum precision components, creating a dual-certification burden for suppliers serving both domestic and international OEMs. Stakeholders must monitor evolving cross-border material traceability mandates that threaten to fragment qualified supplier pools and extend qualification timelines for new manufacturing sources.
Market Dynamics
Aftermarket service revenue streams are reconfiguring margin pools across the precision parts sector as OEMs prioritize total cost of ownership contracts over discrete component sales. This structural shift compresses pure manufacturing margins while elevating technical service capabilities as competitive differentiators.
Growth Catalysts
- REACH compliance mandates:European ECHA restrictions on chromium-based surface treatments are accelerating supplier conversion to trivalent passivation chemistries, creating qualification advantages for early-adopting fabricators serving aerospace and medical device OEMs.
- Minimally invasive surgical instrument demand:Precision medical device machining across Switzerland, the United States, and South Korea is pulling specialized titanium and stainless steel micro-components with sub-micron tolerance requirements.
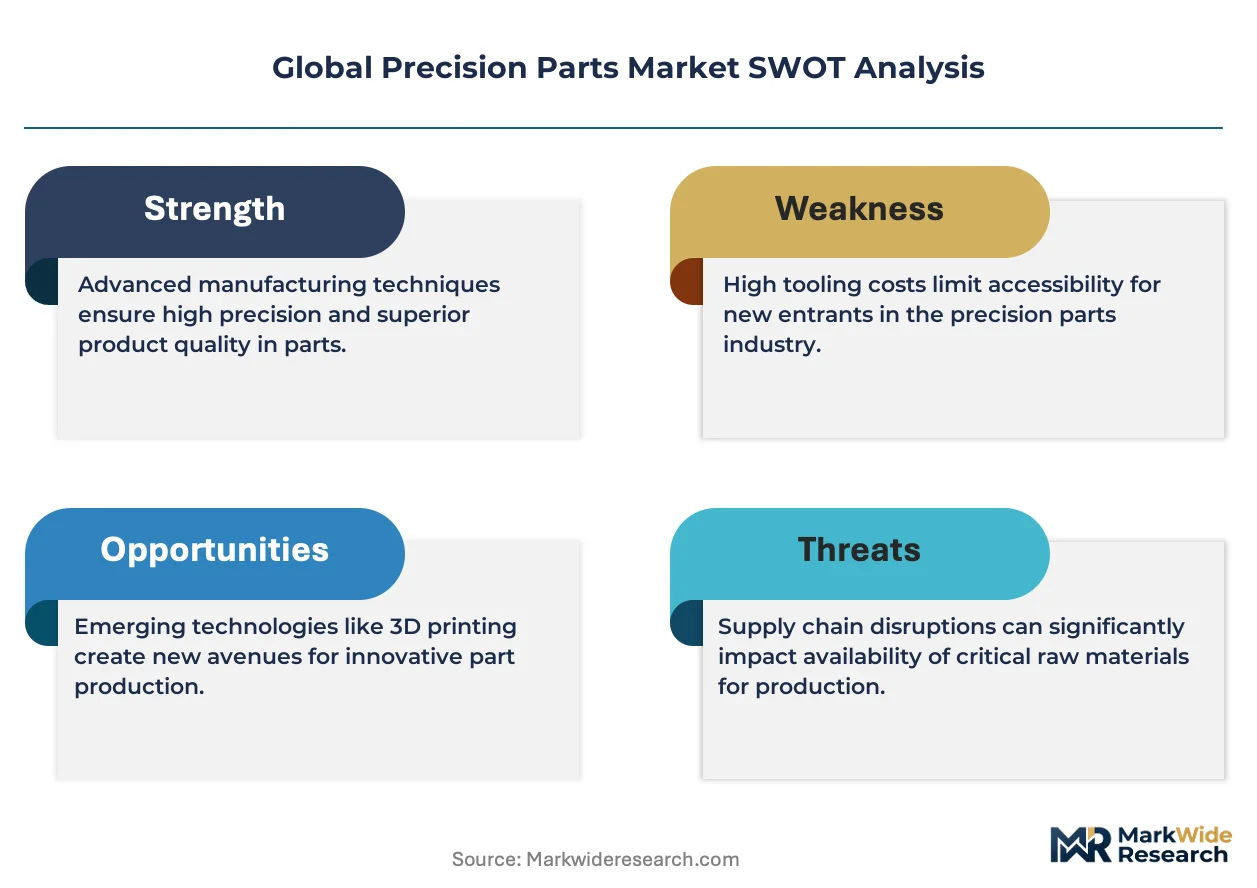
- Additive manufacturing convergence:Hybrid CNC-additive workflows are enabling near-net-shape titanium aerostructures that reduce material waste and machining time for complex engine components.
Market Restraints
- Cemented carbide supply concentration:Downstream fabricators depend on captive supply from a limited pool of tungsten carbide powder producers, creating input cost volatility and qualification bottlenecks for new tooling sources.
- Dual-certification burden:China's SAMR enforcement of GB standards on dimensional tolerances for exported aluminum precision components forces suppliers serving both domestic and international OEMs to maintain parallel quality systems.
- EPA machining coolant discharge limits:US-based fabricators face elevated environmental compliance costs that disadvantage high-volume, low-margin production relative to jurisdictions with less stringent effluent controls.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Production-linked incentives for advanced components are attracting greenfield investments in CNC machining clusters serving aerospace and medical device export markets.
- Sensor housing miniaturization:Automotive and medical device OEMs are specifying hermetic conductive assemblies with integrated electromagnetic shielding that command premium positioning over standard machined enclosures.
- Composite autoclave curing complexity:Aviation certification pathways limit qualified suppliers for carbon fiber reinforced polymer structural components, creating defensive moats for incumbents with FAA and EASA process approvals.
Industry Challenges
- Cross-border material traceability mandates:Evolving documentation requirements threaten to fragment qualified supplier pools and extend qualification timelines for new manufacturing sources across German, Japanese, and US aerospace supply chains.
- EDM electrode wear modeling:Electrical discharge machining operations lack predictive tooling life algorithms for exotic alloys, forcing conservative process parameters that elevate cycle times and consumable costs.
- Interchangeability standard maintenance:Fatigue resistance specifications for aerospace mechanical components require statistical process control investments that strain mid-cap fabricator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Parts Market |
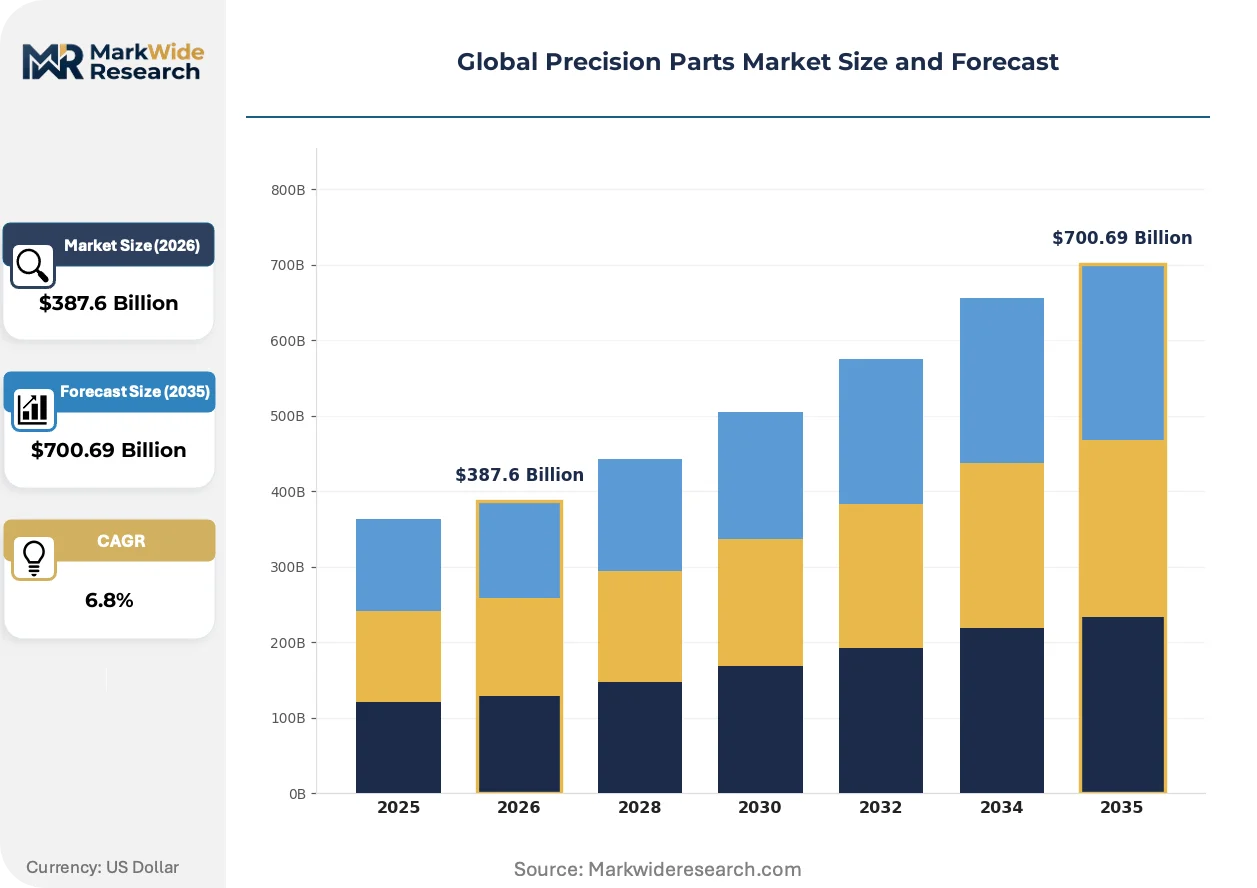
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Components, Electronic Parts, Optical Components, Structural Parts Material: Aluminum, Stainless Steel, Plastic, Composite Application: Aerospace, Automotive, Medical Devices, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions |
| Companies Covered | Barnes Group Inc., GKN Aerospace, Precision Castparts Corp., Mecachrome Group, Sandvik AB, Linamar Corporation, Howmet Aerospace Inc., Senior plc, Martinrea International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Parts Market Strategic Shifts
Digital thread integration across design-to-manufacturing workflows is compressing iteration cycles and enabling real-time quality feedback loops that were previously impractical at precision tolerances.
Hybrid manufacturing platforms combining directed energy deposition with five-axis CNC finishing are digitizing legacy subtractive-only workflows for titanium aerostructures. Aerospace engine OEMs in Germany and Japan are qualifying these cells for structural components previously machined from solid billet. The technology is digitizing supplier capability requirements by merging metallurgical expertise with robotic programming competencies.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in precision cleaning operations for electronic parts. Fabricators serving medical device and sensor housing markets are converting to modified alcohol and aqueous cleaning chemistries with equivalent particulate removal performance. Swiss and German machining clusters are absorbing capital costs for closed-loop solvent recovery systems to maintain CE marking compliance.
Buyers are consolidating vendor bases around full-service precision parts partners capable of delivering mechanical, electronic, and composite assemblies under single-source contracts. Automotive Tier-1 suppliers are displacing fragmented machining job shops with integrated component-and-subsystem providers. South Korean medical device OEMs are most advanced in this consolidation, bundling minimally invasive instrument procurement across multiple instrument families.
Global Precision Parts Market Segmentation
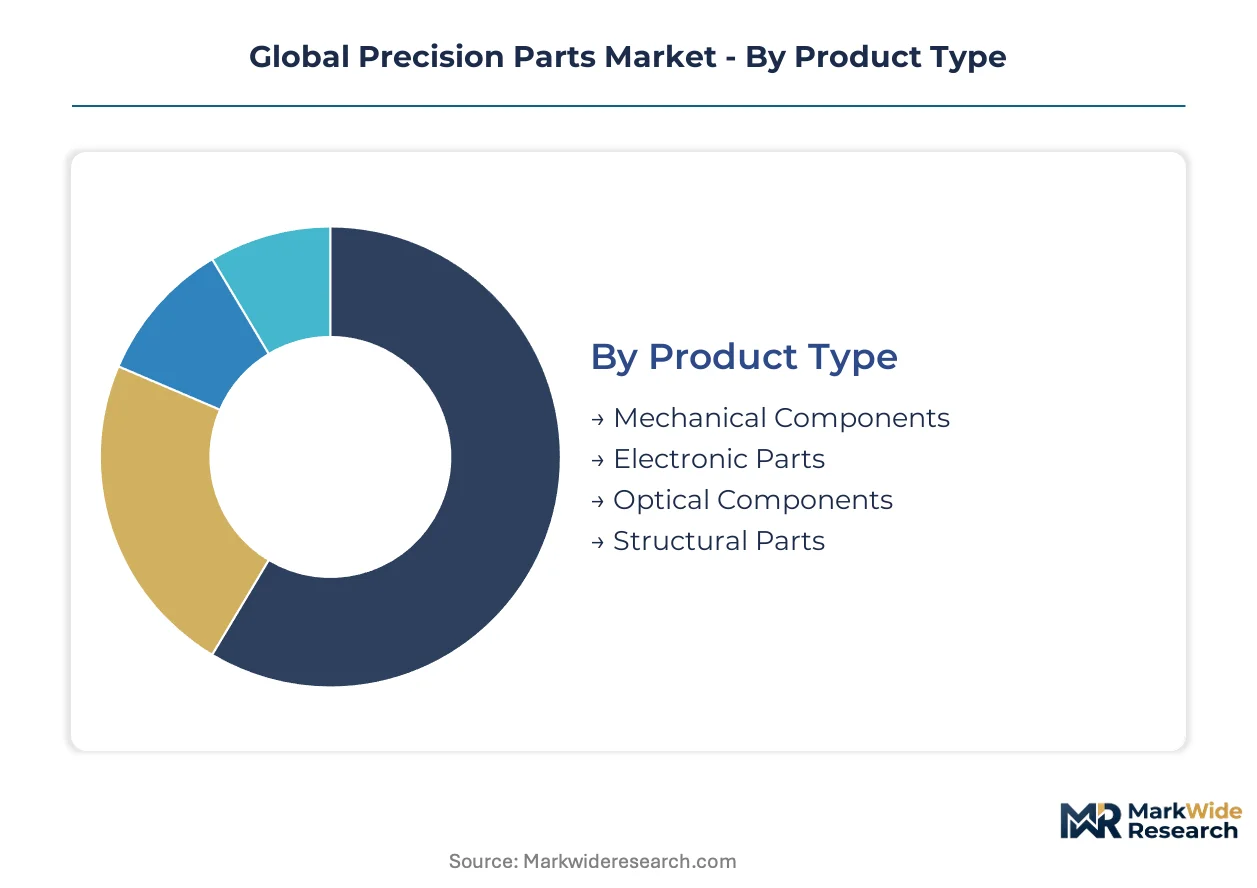
Segmentation in precision parts reveals how tolerance requirements, material certification burdens, and end-use criticality fragment manufacturing economics across distinct supply tiers. Buyers select fabrication partners based on process capability maps rather than commodity pricing, creating specialized competitive arenas within each segment boundary.
Product Type:
Component families span a use-case spectrum from fatigue-critical mechanical assemblies to hermetic electronic enclosures, each demanding incompatible process investments and qualification pathways.
- Mechanical Components:CNC-machined gears, shafts, and bearing housings manufactured to ISO 2768-mK tolerances for aerospace and industrial power transmission. Fatigue resistance specifications from Germany's KBA and Japan's METI certification regimes govern procurement of titanium and alloy steel variants for engine and drivetrain applications.
- Electronic Parts:Miniaturized conductive assemblies with hermetic sealing properties for medical sensors and automotive control modules. South Korean medical device OEMs and German automotive Tier-1s are specifying integrated electromagnetic shielding that commands premium positioning over standard machined enclosures.
- Optical Components:Precision-ground lenses, mirrors, and waveguide housings requiring sub-micron surface roughness for laser and imaging systems. Swiss machining clusters dominate fabrication of ceramic and nickel-phosphor plated aluminum optical benches for semiconductor lithography equipment.
- Structural Parts:Load-bearing titanium and composite assemblies for airframes and satellite platforms. FAA and EASA certification pathways limit qualified suppliers, creating defensive moats for incumbents with autoclave curing and non-destructive testing capabilities.
The dominant share belongs to Mechanical Components, while Electronic Parts is closing the gap fastest.
Material:
Raw material selection drives cost tier stratification from commodity aluminum to qualification-intensive composites, with each tier locking fabricators into distinct customer relationships and margin structures.
- Aluminum:6061-T6 and 7075-T7351 alloys dominate high-volume aerospace and automotive machining. China's SAMR enforces GB standards on dimensional tolerances for exported precision components, forcing dual-certification maintenance for suppliers serving domestic and international OEMs simultaneously.
- Stainless Steel:17-4 PH and 316L variants serve medical device and corrosive environment applications. REACH restrictions on chromium-based surface treatments are accelerating conversion to trivalent passivation chemistries across European supply chains.
- Plastic:PEEK, PTFE, and medical-grade polycarbonate for minimally invasive surgical instruments and chemical-resistant housings. Swiss and US fabricators specialize in tight-tolerance polymer machining where metallic contamination risks govern cleanroom protocols.
- Composite:Carbon fiber reinforced polymer and ceramic matrix composites for aviation primary structures. Autoclave curing complexity and limited qualified suppliers create supply concentration that downstream OEMs manage through long-term offtake agreements.
Aluminum retains volume leadership across aerospace and automotive procurement, though Composite is expanding most quickly in engine and airframe applications.
Application:
End-use verticals impose divergent quality system requirements, with aerospace and medical demanding full material traceability while industrial equipment tolerates statistical sampling.
- Aerospace:Engine and airframe components subject to FAA, EASA, and CAAC certification with 100% inspection protocols. German and Japanese OEMs are expanding procurement of titanium structural components and qualifying hybrid additive-CNC manufacturing cells.
- Automotive:Powertrain and sensor housing production with IATF 16949 quality mandates. Tier-1 suppliers are consolidating vendor bases around full-service partners capable of delivering mechanical and electronic assemblies under single-source contracts.
- Medical Devices:Minimally invasive surgical instruments with ISO 13485 and FDA 21 CFR Part 820 compliance. Switzerland, the United States, and South Korea concentrate demand for specialized titanium and stainless steel micro-components with sub-micron tolerances.
- Industrial Equipment:Hydraulic manifolds, valve bodies, and automation fixtures with shorter qualification cycles. EPA machining coolant discharge limits elevate environmental compliance costs for US-based fabricators in this price-sensitive segment.
Aerospace commands the highest value per kilogram, while Medical Devices is gaining share fastest as surgical robotics and diagnostic miniaturization accelerate.
End User:
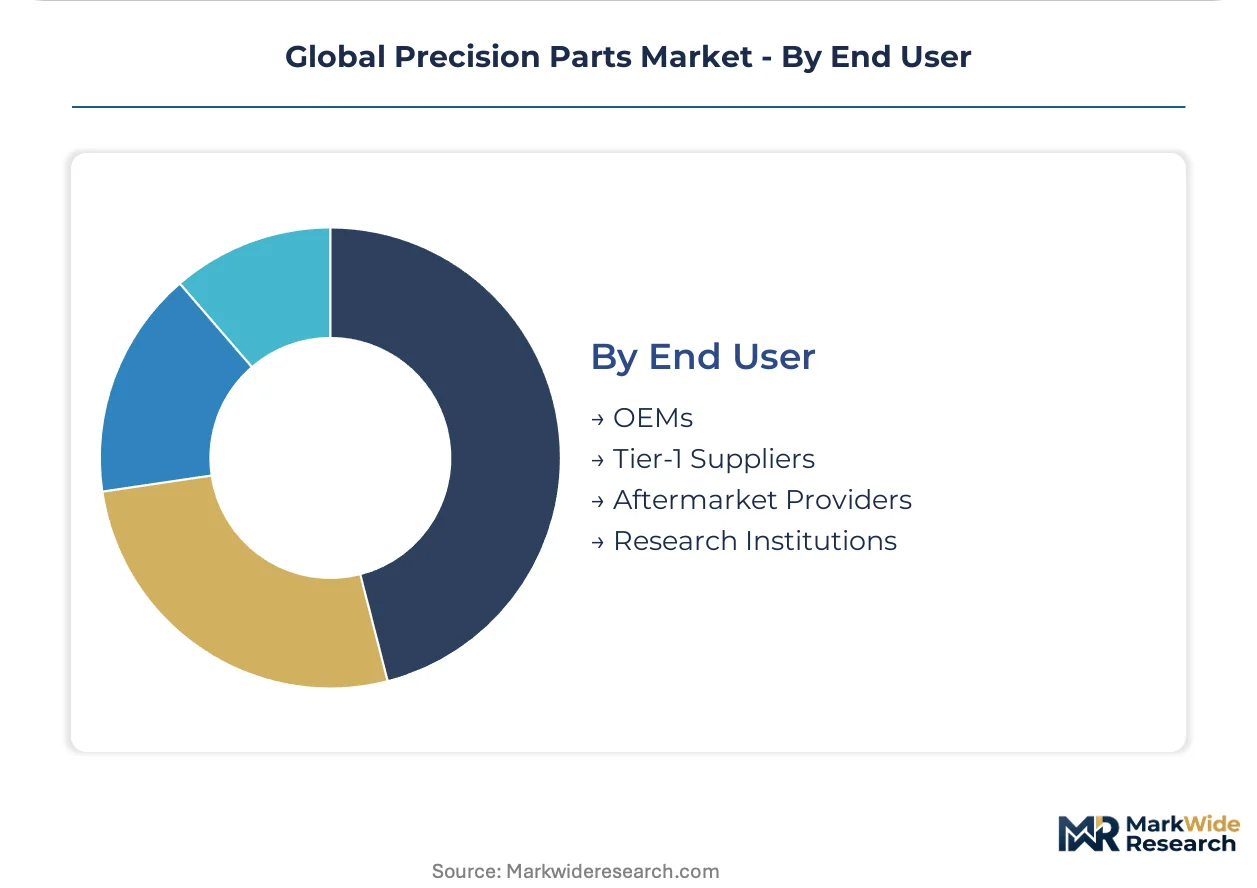
Customer type determines contract structure, with OEMs and Tier-1s shifting toward total cost of ownership agreements that reconfigure margin pools away from discrete component sales.
- OEMs:Airbus, Boeing, and medical device original manufacturers specifying design-to-manufacture partnerships with early supplier involvement. These relationships lock in capacity and extend qualification timelines for alternative fabrication sources.
- Tier-1 Suppliers:Automotive and aerospace subsystem integrators consolidating fragmented machining job shops. South Korean medical device Tier-1s are most advanced in bundling procurement across multiple instrument families.
- Aftermarket Providers:Maintenance, repair, and overhaul operators capturing recurring revenue streams. Barnes Group and similar specialists leverage aerospace aftermarket footprints to displace pure manufacturing margins with technical service capabilities.
- Research Institutions:National laboratories and university fabrication facilities prototyping next-generation materials and geometries. These users tolerate longer lead times and higher per-unit costs in exchange for process flexibility and confidentiality.
The dominant share belongs to OEMs, while Aftermarket Providers are climbing the fastest as fleet age and installed base maintenance expand addressable revenue pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in industrial equipment segments across the United States exhibit acute price sensitivity, whereas aerospace OEMs in Germany and Japan tolerate substantial premiums for titanium structural components with full material traceability.
United States
Aerospace aftermarket providers and medical device OEMs drive demand for fatigue-resistant mechanical components and minimally invasive surgical instruments. EPA machining coolant discharge limits elevate environmental compliance costs for domestic fabricators serving high-volume industrial segments. Connecticut-based Barnes Group anchors the aerospace maintenance, repair, and overhaul ecosystem through technical service capabilities that displace pure manufacturing margins.
Germany
Engine OEMs expand procurement of titanium structural components and qualify hybrid additive-CNC manufacturing cells for complex aerostructures. KBA fatigue resistance specifications govern procurement of alloy steel variants for powertrain applications, forcing statistical process control investments. Bavarian machining clusters absorb capital costs for closed-loop solvent recovery systems to maintain CE marking compliance under Europe's F-Gas Regulation.
Japan
METI certification regimes for fatigue-critical mechanical assemblies sustain demand for precision-machined gears and bearing housings in engine and drivetrain applications. Aerospace OEMs qualify hybrid manufacturing platforms for titanium structural components previously machined from solid billet. Nagoya-area fabricators merge metallurgical expertise with robotic programming competencies to digitize legacy subtractive-only workflows.
Switzerland
Medical device OEMs concentrate demand for specialized titanium and stainless steel micro-components with sub-micron tolerance requirements for minimally invasive surgical instruments. Swissmedic regulations enforce cleanroom protocols where metallic contamination risks govern polymer machining operations. Swiss machining clusters dominate fabrication of ceramic and nickel-phosphor plated aluminum optical benches for semiconductor lithography equipment.
South Korea
Medical device OEMs advance vendor consolidation by bundling procurement across multiple instrument families for surgical robotics and diagnostic miniaturization. MFDS oversight shapes qualification pathways for hermetic conductive assemblies with integrated electromagnetic shielding. Seoul-area Tier-1 suppliers displace fragmented machining job shops with integrated component-and-subsystem providers.
Global Precision Parts Market Competitive Environment
Vertically integrated material suppliers and specialized aerostructure fabricators split the market into distinct competitive arenas with incompatible capability requirements. The vendor base organizes around three strategic archetypes: cemented carbide powder producers controlling captive tooling supply, titanium machining specialists serving engine qualification pathways, and diversified industrial conglomerates spanning mechanical and electronic assemblies. Dominant competitive moves include capacity expansion in India's PLI-subsidized CNC machining clusters and strategic partnerships bundling aftermarket service contracts with discrete component sales.
Among North American fabricators, Barnes Group Inc. and Howmet Aerospace Inc. occupy positions within the aerospace aftermarket and structural components tiers respectively. Barnes Group exemplifies the technical-service archetype through recurring maintenance revenue streams. Howmet Aerospace sits within the premium-tier structural fabrication segment where FAA and EASA certification pathways limit qualified suppliers. Sandvik AB anchors the cemented carbide supply tier through captive tungsten carbide powder production that downstream fabricators depend upon.
| Leading Market Players |
|---|
| Barnes Group Inc. |
| GKN Aerospace |
| Precision Castparts Corp. |
| Mecachrome Group |
| Sandvik AB |
| Linamar Corporation |
| Howmet Aerospace Inc. |
| Senior plc |
| Martinrea International Inc. |
| Others |
Value Chain & Pricing Dynamics
Cemented carbide powder production concentrates in Sweden and Austria, locking downstream fabricators into captive supply relationships that shift margin pools toward upstream material suppliers and away from pure machining operations.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture across aerospace and medical device verticals, displacing discrete component sales as the dominant revenue architecture. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified titanium aerostructures from industrial aluminum components and commodity job-shop work. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in standard-tier aluminum machining is intensifying because China's SAMR dual-certification requirements elevate compliance overhead for export-bound suppliers. Industrial equipment buyers exhibit acute price sensitivity, while German and Japanese aerospace OEMs tolerate substantial premiums for full material traceability.
Supply Chain Analysis
Extended payment terms from Tier-1 aerospace OEMs are squeezing working capital for mid-cap fabricators, forcing supply-chain finance facility adoption to bridge cash conversion cycles. Raw material sourcing centers on China for tungsten carbide powder, Sweden for cemented carbide tool materials, and Japan for precision-grade titanium billet. Downstream distribution runs through captive Tier-1 supplier networks rather than open merchant markets. Single-source vulnerability in cemented carbide supply creates qualification bottlenecks when incumbent powder producers restrict new customer onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent precision parts fabricators face substitution pressure from hybrid additive-CNC manufacturing platforms that digitize legacy subtractive-only workflows and compress qualification timelines for new entrants.
For Market Incumbents: Insulate titanium aerostructure positions through backward integration into heat treatment and non-destructive testing capabilities that hybrid manufacturing startups cannot replicate overnight. Deepen certification moats by pursuing early EASA and FAA approvals for trivalent passivation chemistries ahead of REACH compliance deadlines. Lock in capacity through long-term offtake agreements with German and Japanese engine OEMs expanding procurement of structural components.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized CNC machining clusters serving medical device export markets, where greenfield investments bypass legacy cost structures. Target hermetic sensor housing miniaturization for South Korean automotive Tier-1s, as electromagnetic shielding specifications create technical barriers that commodity machinists cannot cross. Lead with integrated component-and-subsystem capabilities rather than discrete parts to match vendor consolidation trends.
For Investors and Strategic Acquirers: Capital is best deployed toward captive cemented carbide suppliers and diversified precision parts platforms spanning mechanical, electronic, and composite assemblies under single-source contracts. Long-term viability favors incumbents with FAA and EASA process approvals that limit qualified supplier pools for aviation primary structures. Monitor India's PLI scheme uptake as an inflection indicator for production gravity shifts in aerospace and medical device supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captures value-add steps that hybrid manufacturing competitors cannot easily replicate for FAA-certified titanium aerostructures. |
| REACH-Compliant Surface Treatment Conversion | Early trivalent passivation adoption creates qualification advantages with European aerospace and medical device OEMs. |
| India PLI Scheme Capacity Expansion | Greenfield CNC machining clusters gain cost positioning for aerospace and medical device export markets. |
| Hermetic Sensor Housing Development | Integrated electromagnetic shielding commands premium positioning with South Korean automotive Tier-1 suppliers. |
| Aftermarket Service Contract Bundling | Recurring maintenance revenue displaces pure manufacturing margins across aerospace MRO ecosystems. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aerospace procurement directors, medical device quality engineers, cemented carbide plant managers, and Tier-1 supplier manufacturing heads. Secondary validation drew from FAA certification databases, EASA process approval records, SAMR GB standard filings, and SEC 10-K disclosures from listed precision parts manufacturers. Bottom-up fabrication capacity estimates were triangulated against top-down OEM procurement spend allocations across the analysis window.
Calibration against historical production volumes and disclosed order backlogs anchored forward projections without reliance on extrapolation. Segmentation dimensions modeled include product type, material grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed capacity expansion timelines and OEM sourcing announcements. Industry-specific forecast inputs incorporated REACH compliance phase-in schedules and India's PLI scheme disbursement trajectories.
Stress conditions across tungsten carbide price volatility, dual-certification burden escalation, and hybrid manufacturing adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and OEM qualification protocols. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Epi Wafer Market