
 Bipolar Transistors Market | 2026-2036
Bipolar Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Bipolar Transistors Market Outlook
Distributor consolidation across Asia-Pacific is reshaping how bipolar transistors reach mid-volume industrial buyers. Infineon Technologies AG leverages captive silicon carbide substrate capacity to anchor premium power transistor supply chains. Texas Instruments Incorporated sustains broad catalog dominance through die-bank inventory programs that reduce lead times for automotive customers. ON Semiconductor competes aggressively in image-sensor adjacent bipolar lines for advanced driver-assistance systems.
Bipolar transistors are three-terminal semiconductor devices constructed with alternating p-type and n-type doped silicon layers, operating via minority carrier injection to achieve current amplification with typical gain values from ten to several hundred. These devices serve as fundamental switching and amplification elements in power management circuits, audio systems, and radio-frequency front ends where linearity and ruggedness outweigh pure switching speed. High-power silicon devices occupy the mature revenue core, while gallium nitride technology captures the fastest expansion as thermal and frequency performance requirements intensify in base stations and radar systems. Radio-frequency bipolar transistors concentrate margin pools in defense and telecommunications applications where packaging miniaturization through chip-on-board configurations reduces parasitic inductance.
The EPA regulates semiconductor manufacturing effluents including perfluorinated compounds used in etching processes for bipolar transistor fabrication. REACH compliance across Europe restricts certain dopant chemistries and mandates substance disclosure through supply chains, elevating qualification costs for imported devices. China's GB standards and MIIT directives increasingly govern domestic procurement specifications for industrial-grade bipolar components. Stakeholders must monitor how regional carbon-border adjustments and material traceability rules recalibrate cost structures against performance advantages in next-generation wide-bandgap alternatives.
Market Dynamics
Silicon carbide substrate qualification under automotive-grade certification frameworks is compressing supplier lead times and forcing legacy silicon bipolar portfolios into price-sensitive industrial niches. Tier-1 automotive electronics buyers now mandate AEC-Q101 compliance for power transistors, rewiring procurement criteria across the supply base.
Growth Catalysts
- Electric powertrain electrification:Battery management systems and DC-DC converters in EVs require rugged switching devices. Automotive electronics adoption expands the addressable component base as mechanical systems retire.
- China's domestic semiconductor fabrication expansion:Industrial and consumer applications concentrate demand within the country's growing captive supply base, reducing import dependency for standard-grade devices.
- REACH substance disclosure mandates:European supply chain transparency requirements elevate qualification costs for imported devices, advantaging compliant regional suppliers in premium industrial segments.
Market Restraints
- Gallium nitride substitution in RF power:Base station and radar applications increasingly specify GaN-on-SiC devices for thermal and frequency performance, eroding silicon bipolar margins in high-frequency amplification.
- Silicon wafer supply concentration:Disruptions in polysilicon refining and epitaxial growth capacity in East Asia propagate cost volatility through bipolar transistor foundry networks.
- EPA perfluorinated compound effluent limits:Etching process chemistry restrictions tighten fabrication cost structures for US-based manufacturing, compressing returns on mature process nodes.
Strategic Opportunities
- Chip-on-board packaging miniaturization:Defense and telecommunications applications demand reduced parasitic inductance through advanced interconnect geometries, opening premium margin pools in RF bipolar lines.
- India's PLI scheme for electronics manufacturing:Domestic assembly incentives attract component sourcing for industrial automation and renewable energy inverters, building regional demand clusters.
- Wide-bandgap material convergence:Hybrid module designs combining silicon bipolar gate drivers with silicon carbide power stages enable gradual technology transitions without full system redesigns.
Industry Challenges
- Analog design engineering scarcity:Minority carrier device physics expertise concentrates among aging specialists, constraining product development velocity for new bipolar introductions.
- AEC-Q101 certification timeline compression:Automotive qualification cycles now demand concurrent thermal cycling and humidity testing, extending time-to-revenue for new power transistor families.
- Legacy system integration friction:Industrial equipment refresh cycles lag semiconductor innovation by 15-20 years, forcing dual-source strategies across incompatible voltage ratings and package footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bipolar Transistors Market |
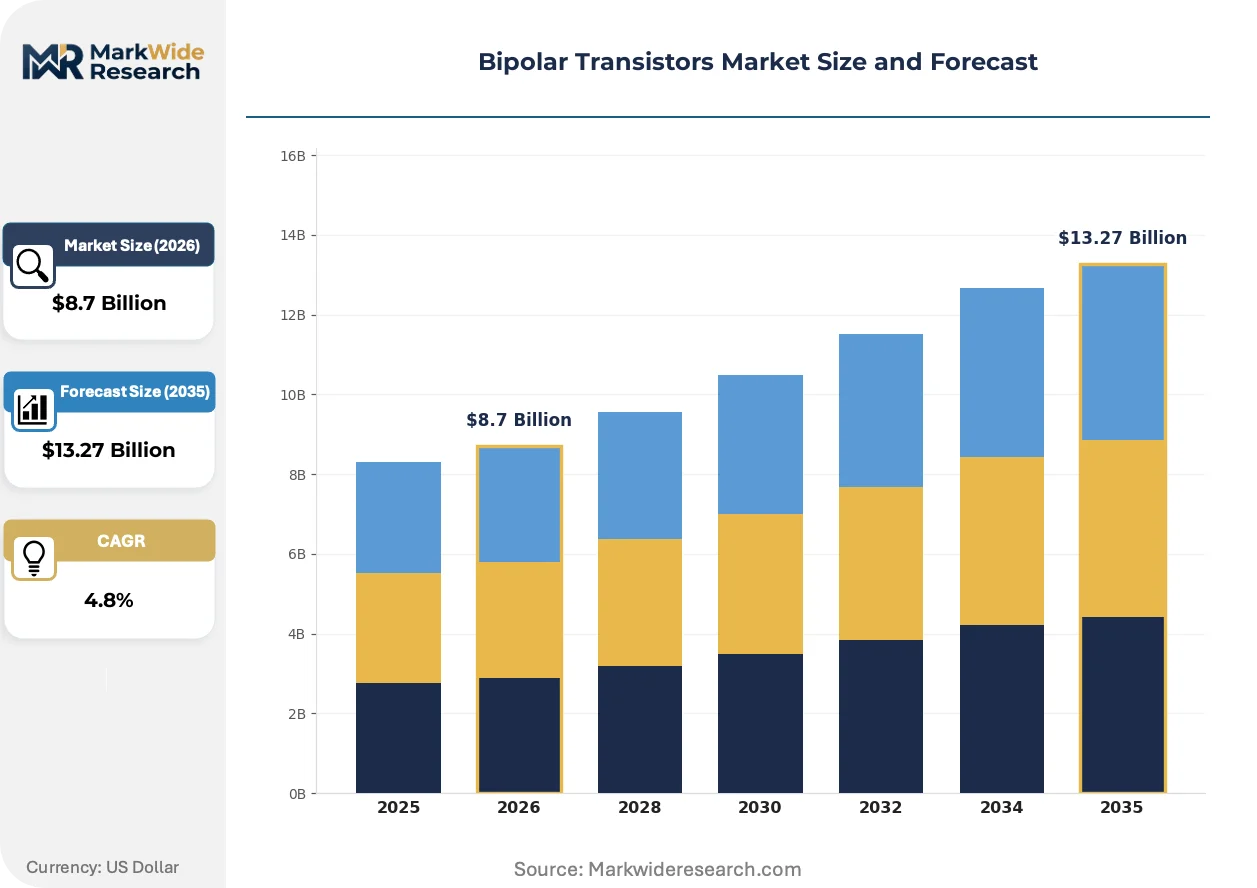
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, High Power, Low Noise, Radio Frequency Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Equipment Technology: Silicon, Silicon Carbide, Gallium Nitride, Organic Packaging Type: TO Package, Surface Mount, Chip-On-Board, Other |
| Companies Covered | STMicroelectronics, ON Semiconductor, Infineon Technologies AG, Vishay Intertechnology, Diodes Incorporated, Toshiba Electronic Devices & Storage Corporation, Renesas Electronics Corporation, Nexperia, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bipolar Transistors Market Strategic Shifts
Process node migration and packaging topology evolution are bifurcating the bipolar transistor landscape into high-volume commodity silicon and premium wide-bandgap alternatives. Device physics constraints now dictate application-specific material selection rather than universal silicon dominance.
Gallium nitride high-electron-mobility transistor technology is migrating from defense radar and telecommunications infrastructure into commercial 5G base station amplifiers. Network equipment manufacturers specify GaN devices for thermal efficiency at millimeter-wave frequencies. This migration is compressing silicon bipolar market presence to sub-6 GHz applications where linearity requirements persist.
REACH restrictions on certain dopant chemistries are forcing reformulation of boron and phosphorus implantation processes in European fabrication facilities. Substance disclosure mandates propagate through supply chains, elevating documentation burdens for imported devices. Industrial-grade bipolar component procurement in Germany and France now prioritizes EU-originated supply to mitigate compliance latency.
Die-bank inventory programs are displacing traditional distributor stockholding for automotive-qualified power transistors. Tier-1 suppliers now contract directly for wafer bank capacity, compressing lead times from 26 weeks to 8 weeks. This concentration is most visible in German and Japanese automotive electronics clusters, where just-in-sequence manufacturing tolerates minimal component variability.
Bipolar Transistors Market Segmentation
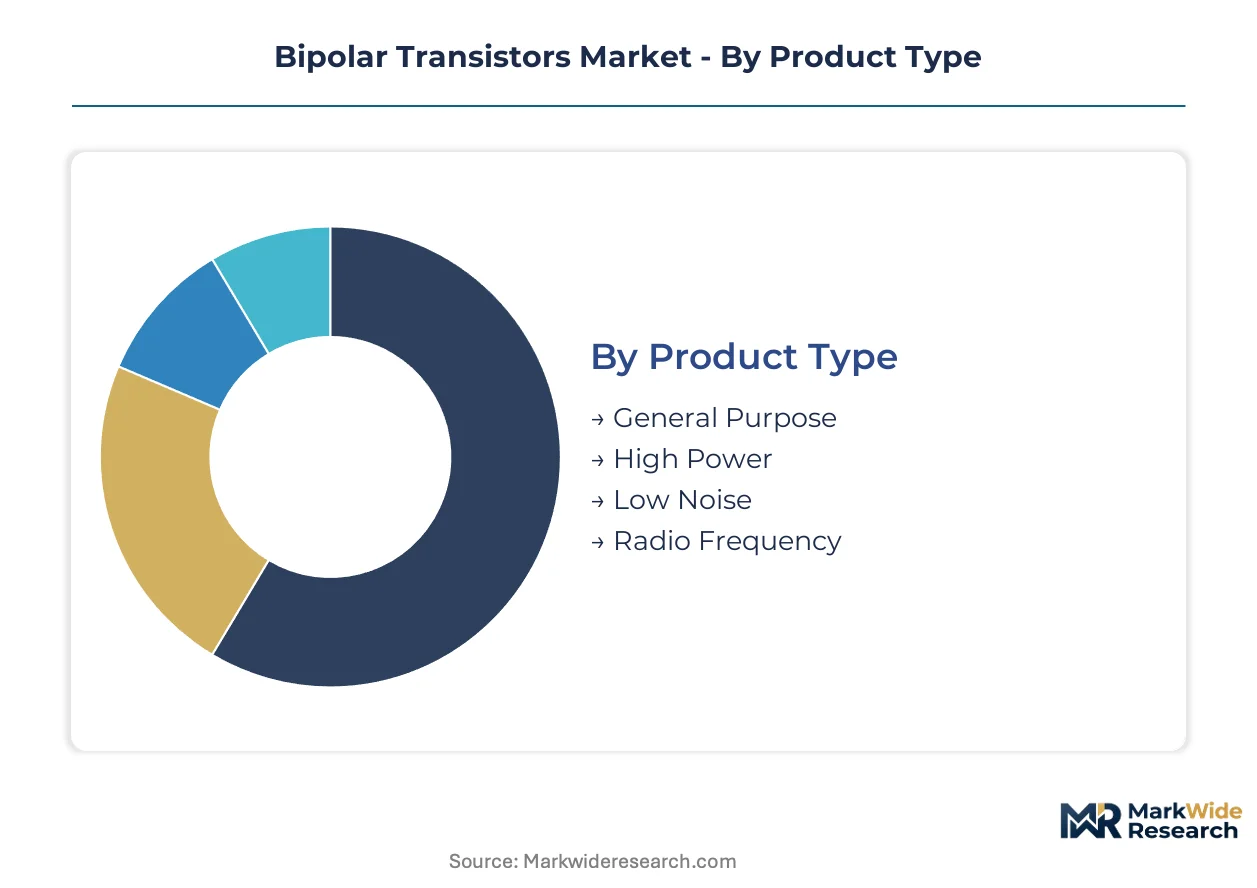
Bipolar transistor segmentation reflects divergent maturity curves across material platforms and end-use requirements. Product differentiation now hinges on thermal performance thresholds and qualification standards rather than universal silicon dominance.
Product Type:
Mature silicon architectures dominate volume production, while emerging RF and low-noise variants capture premium positioning through specialized fabrication.
- General Purpose:Standard NPN and PNP configurations fabricated on bulk silicon epitaxial wafers serve switching and amplification functions in power supplies and consumer appliances. Industrial automation clusters in Germany and Japan sustain procurement volumes for through-hole and surface-mount variants despite gradual module integration.
- High Power:Vertical structures with thick epitaxial layers and optimized doping profiles manage currents exceeding ten amperes in motor drives and welding equipment. China's expanding renewable energy inverter manufacturing concentrates demand for TO-3P and TO-247 packaged devices rated above 400 volts.
- Low Noise:Specialized geometries minimize base resistance and optimize emitter periphery for audio preamplification and sensor interfaces.
- Radio Frequency:Heterojunction bipolar technologies on silicon-germanium substrates deliver gain at microwave frequencies for radar front ends.
General Purpose retains volume leadership; Radio Frequency holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity consumer volumes from automotive-grade qualification premiums.
- Consumer Electronics:High-volume switching applications in power adapters, LED drivers, and small appliances leverage standard silicon bipolar economics. Assembly operations in Vietnam and Mexico source predominantly from Chinese wafer fabs to minimize landed cost.
- Automotive Electronics:AEC-Q101 qualified devices for battery management, engine control, and lighting systems command price premiums reflecting reliability testing investments. German and Japanese Tier-1 suppliers mandate traceable fab sources for power transistor families.
- Telecommunications:Base station power amplifiers and optical transceiver driver stages specify RF-optimized devices with tight gain matching.
- Industrial Equipment:Motor control, uninterruptible power supplies, and process instrumentation tolerate longer lead times for ruggedized packaging.
Consumer Electronics retains volume leadership; Automotive Electronics holds the steepest expansion curve.
Technology:
Application-specific material selection now governs competitive positioning across frequency and thermal operating envelopes.
- Silicon:Mature bipolar junction transistor processes on 150mm and 200mm wafers deliver cost-optimized performance for sub-gigahertz switching and linear amplification. Legacy fab depreciation in Malaysia and the Philippines sustains margin structures for standard-grade devices.
- Silicon Carbide:Wide-bandgap substrates enable junction temperatures exceeding 175 degrees Celsius in electric vehicle traction inverters and renewable energy converters. Automotive qualification timelines under AEC-Q101 compress supplier margins while locking in multi-year supply agreements.
- Gallium Nitride:HEMT and heterojunction bipolar structures capture millimeter-wave radar and 5G infrastructure amplification.
- Organic:Printed semiconductor approaches on flexible substrates enable disposable biosensors and conformable display drivers.
Silicon retains volume leadership; Silicon Carbide holds the steepest expansion curve.
Packaging Type:
Customer type segmentation separates high-reliability military-aerospace procurement from cost-sensitive consumer electronics assembly.
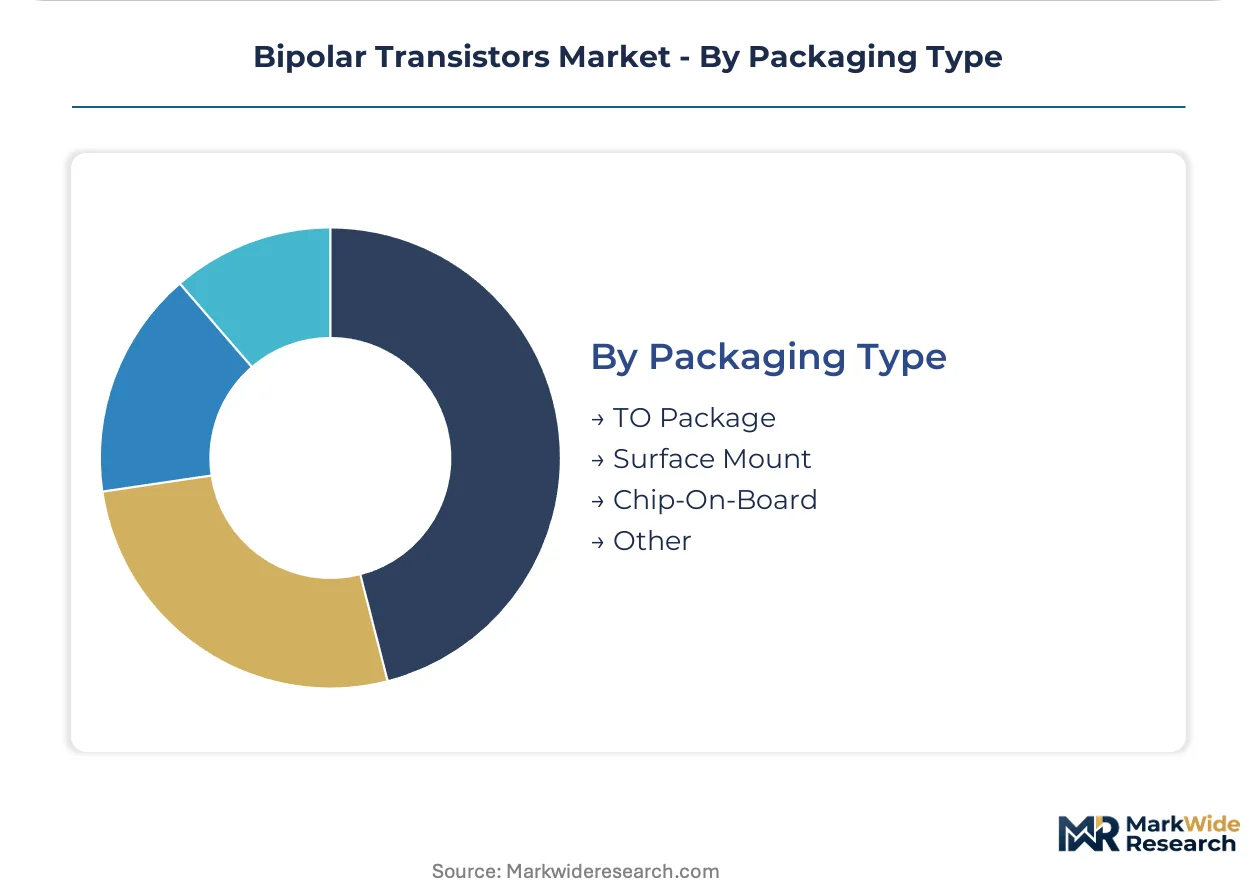
- TO Package:Metal and plastic through-hole housings with threaded mounting bases dissipate heat in industrial motor drives and automotive power modules. German industrial equipment manufacturers specify TO-220 and TO-247 variants for field-repair compatibility across 15-year service lives.
- Surface Mount:SOT-23, SOT-89, and Power-SO8 configurations enable high-density assembly in consumer power management and telecommunications equipment. Contract manufacturers in Taiwan and South Korea optimize pick-and-place throughput for tape-and-reel packaging.
- Chip-On-Board:Bare die attachment with wire bonding minimizes parasitic inductance for RF power amplifiers and millimeter-wave radar.
- Other:Custom ceramic and metal-matrix packages address hermetic sealing requirements for space and downhole applications.
Surface Mount retains volume leadership; Chip-On-Board holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT directives and GB standards anchor procurement specifications in China, the dominant geography where domestic semiconductor fabrication capacity expansion concentrates industrial and consumer bipolar transistor demand. Regional dynamics diverge sharply between automotive-grade qualification hubs in Germany and Japan versus cost-optimized assembly clusters in Southeast Asia and Mexico.
China
Electric vehicle battery management systems and renewable energy inverters drive bipolar transistor consumption as BYD and CATL expand manufacturing. MIIT's GB standards tighten domestic procurement specifications for industrial-grade components, advantaging local foundries. Yangtze River Delta fabrication clusters in Shanghai and Wuxi now supply standard-grade devices that previously required import.
Germany
Tier-1 automotive electronics suppliers mandate AEC-Q101 qualified power transistors for electric powertrain modules and engine control systems. REACH substance disclosure requirements elevate documentation burdens for imported devices, channeling procurement toward EU-originated supply. Bavarian industrial automation clusters around Munich and Nuremberg sustain through-hole bipolar demand for 15-year field-repair compatibility.
United States
Defense radar and telecommunications infrastructure specify RF-optimized bipolar devices for millimeter-wave applications. EPA perfluorinated compound effluent limits tighten fabrication cost structures for domestic manufacturing, compressing returns on mature process nodes. Texas and Arizona semiconductor corridors concentrate advanced packaging operations serving automotive and aerospace customers.
Japan
Industrial equipment and automotive electronics sustain procurement of ruggedized bipolar transistors with traceable fab sources. METI industrial policy supports domestic semiconductor manufacturing capacity preservation for critical component categories. Nagoya automotive electronics clusters and Tokyo-area telecommunications equipment manufacturers anchor premium RF bipolar demand.
India
Industrial automation and renewable energy inverter assembly build regional demand clusters under the PLI scheme for electronics manufacturing. CEA grid standards and BIS certification requirements shape component specifications for power electronics applications. Gujarat and Tamil Nadu manufacturing corridors attract component sourcing for domestic and export-oriented production.
Bipolar Transistors Market Competitive Environment
Integrated device manufacturers and specialized discrete semiconductor suppliers split the market between captive fab capacity and fabless flexibility. Consolidation pressure intensifies as automotive qualification timelines compress and wide-bandgap alternatives capture premium positioning. Three archetypes dominate: diversified analog giants with die-bank inventory programs, power semiconductor specialists with substrate integration, and RF-focused heterojunction bipolar transistor developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification costs escalate.
Among European-integrated suppliers, Infineon Technologies AG and STMicroelectronics exemplify the power semiconductor specialist archetype with captive substrate strategies. Texas Instruments Incorporated represents the diversified analog giant model through broad catalog dominance and inventory programs. ON Semiconductor occupies a position bridging automotive-grade qualification expertise with image-sensor adjacent bipolar lines. These three anchors illustrate how geographic origin and structural positioning shape competitive responses to silicon carbide migration and AEC-Q101 compression.
| Leading Market Players |
|---|
| STMicroelectronics |
| ON Semiconductor |
| Infineon Technologies AG |
| Vishay Intertechnology |
| Diodes Incorporated |
| Toshiba Electronic Devices & Storage Corporation |
| Renesas Electronics Corporation |
| Nexperia |
| Texas Instruments Incorporated |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta fabrication clusters in Shanghai and Wuxi concentrate bipolar transistor capacity for standard-grade devices, compressing pricing power for imported alternatives while elevating premiums for automotive-qualified and wide-bandgap variants. This geographic concentration shapes how procurement officers balance landed cost against qualification timelines across industrial and automotive segments.
Pricing Analysis
Chinese-origin standard-grade bipolar transistors trade at substantial discounts to German and Japanese automotive-qualified equivalents, with AEC-Q101 certification tiers commanding premiums reflecting extended thermal cycling investments. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels separates procurement budgets by end-use reliability requirements. Pricing pressure stems from gallium nitride substitution in RF amplification and silicon carbide migration in power applications, eroding silicon bipolar margins in premium tiers. Automotive electronics buyers exhibit lowest price sensitivity due to traceability mandates, while consumer appliance assemblers in Vietnam and Mexico prioritize landed cost minimization.
Supply Chain Analysis
Polysilicon refining and epitaxial wafer production concentrate in China, South Korea, and Japan, with substrate supply drawing from captive metallurgical-grade silicon and imported electronic-grade feedstocks. Boron and phosphorus dopants, plus gold and platinum metallization for high-reliability devices, rest on concentrated specialty chemical suppliers. Single-source vulnerability in 200mm epitaxial wafer capacity creates exposure to East Asian logistics disruptions and export licensing friction. Distribution runs through authorized distributors for automotive-qualified lines and spot-market brokers for standard-grade industrial volumes, with die-bank programs displacing traditional inventory holding for Tier-1 contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate qualification under automotive-grade frameworks is compressing legacy silicon bipolar margins while opening premium positioning for compliant suppliers. This technological inflection demands strategic repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: Insulate automotive-grade revenue streams through captive silicon carbide substrate capacity and accelerated AEC-Q101 certification pipelines, as gallium nitride RF substitution threatens high-frequency silicon portfolios. Deepen backward integration into epitaxial wafer supply to mitigate polysilicon cost volatility from East Asian concentration. Prioritize die-bank inventory programs for German and Japanese Tier-1 automotive clusters to lock in multi-year supply agreements before qualification timelines extend further. For New Entrants and Emerging Players: India's underpenetrated industrial automation and renewable energy inverter assembly offers white-space positioning under PLI scheme incentives, with CEA grid standards creating procurement specifications favoring local component sourcing. Target chip-on-board packaging miniaturization for defense and telecommunications RF applications where parasitic inductance requirements sustain premium margins. Pursue foundry partnerships with Yangtze River Delta fabs for standard-grade device production to establish cost baselines before automotive qualification investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power semiconductor specialists with captive wide-bandgap substrate strategies over fabless analog competitors exposed to silicon commoditization. Long-term viability across the projection horizon rests on qualification infrastructure depth and automotive customer lock-in rather than volume scale alone. Monitor AEC-Q101 certification timeline compression as the critical inflection signal—suppliers failing concurrent thermal cycling and humidity testing will face extended time-to-revenue penalties. Cross-checking against semiconductor capital equipment order patterns and automotive platform electrification roadmaps is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Integration | Captive SiC wafer supply secures automotive qualification timelines against substrate shortages. |
| AEC-Q101 Acceleration Program | Concurrent thermal cycling and humidity testing compresses time-to-revenue for power transistor families. |
| Die-Bank Inventory Expansion | Wafer bank capacity contracts reduce lead times from 26 weeks to 8 weeks for Tier-1 automotive. |
| Chip-on-Board Packaging Investment | Advanced interconnect geometries capture RF bipolar margin pools in defense and telecommunications. |
| India PLI Manufacturing Footprint | Domestic assembly incentives attract component sourcing for industrial automation and renewable energy. |
Study Parameters
Operator-level perspectives from semiconductor fabrication managers, Tier-1 automotive procurement officers, industrial equipment design engineers, and RF telecommunications equipment manufacturers anchored the qualitative base. Primary interview findings combined with secondary validation from SEC 10-K filings, MIIT directive documentation, EPA effluent compliance records, and AEC-Q101 qualification databases. Bottom-up segment sizing triangulated against top-down semiconductor capital equipment spending patterns to ensure consistency.
Scenario-bracketing around silicon carbide adoption velocity, automotive electrification penetration, and gallium nitide substitution rates bounded volume and value outputs across the analysis window. Segmentation dimensions modeled include product architecture, application end-use, material technology platform, and packaging topology, with regional production cluster dynamics overlaying geographic splits. CAGRs derived from fitted growth curves calibrated to disclosed capacity expansion timelines and customer qualification pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated wide-bandgap specialists or unexpected EPA effluent rule tightening would shift outcomes. Forecasts reflect assumptions about AEC-Q101 timeline stability, polysilicon supply continuity, and REACH substance disclosure propagation without regulatory acceleration. Cross-checking against semiconductor foundry utilization rates and automotive platform electrification roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market