
 SONAR System Market | 2026-2036
SONAR System Market Size, Share, and Industry Trends Forecast 2026-2036
SONAR System Market Intelligence
Market Context
GaN (gallium nitride) power electronics is broadening transmitter efficiency in active sonar arrays while reducing thermal management burdens. Thales Group leverages integrated inertial navigation suites to dominate French and British naval modernization programs. Raytheon Technologies Corporation anchors US surface combatant sonar upgrades through Aegis combat system integration. Kongsberg Gruppen specializes in compact synthetic aperture payloads for autonomous underwater vehicle deployments.
Technical Definition and Segments
A SONAR (Sound Navigation and Ranging) system emits acoustic pulses through water—typically 10 Hz to 2 MHz—and processes returning echoes to detect, classify, and localize submerged objects, map seafloor topography, or enable underwater communication. Active sonar systems generate their own acoustic energy and dominate naval defense budgets due to precision targeting requirements, while passive sonar arrays are capturing maritime research investment as institutions prioritize non-invasive cetacean and ecosystem monitoring. Synthetic aperture sonar is outpacing conventional side-scan systems in offshore exploration contract wins because its along-track resolution remains independent of range and altitude.
Regulatory Environment
The US Navy's Naval Sea Systems Command sets MIL-STD-461 and MIL-STD-810 compliance thresholds for electromagnetic interference and environmental ruggedness, while the International Maritime Organization's revised guidelines for the reduction of underwater noise from commercial shipping create dual-use certification pressure on transducer manufacturers. NATO's Undersea Research Centre coordinates multistatic sonar interoperability standards across allied fleets. Stakeholders must monitor evolving export control classifications under the Wassenaar Arrangement and national defense trade regulations that govern acoustic processing algorithm transfers.
Market Dynamics
GaN transmitter arrays are compressing thermal management costs while NATO's Next-Generation Overmatch program rewrites interoperability specifications for allied fleets, forcing manufacturers to redesign around common data protocols.
Growth Catalysts
- Naval Modernization Mandates:The US Navy's surface combatant upgrade programs are replacing legacy hull-mounted arrays with integrated multi-function systems. French and British procurement through NATO's Undersea Research Centre is accelerating multistatic deployment timelines.
- Autonomous Underwater Vehicle Expansion:Offshore energy operators in Norway and Australia are contracting synthetic aperture payloads for pipeline inspection at depths exceeding diver limits. Compact sonar modules now dominate AUV specification sheets.
- Environmental Monitoring Regulations:The International Maritime Organization's revised underwater noise guidelines are mandating passive acoustic monitoring systems for commercial fleets. Research institutions are prioritizing non-invasive cetacean tracking arrays.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and samarium-cobalt sourcing for high-power transducers remains concentrated in Chinese processing facilities. Western defense contractors face dual-use export control delays under the Wassenaar Arrangement.
- Signal Processing Talent Scarcity:Acoustic algorithm development requires specialized expertise in matched-field processing and beamforming optimization. University programs in underwater acoustics are producing insufficient graduates for defense and commercial demand.
- Deep-Sea Pressure Engineering Costs:Titanium alloy housings and oil-compensated electronics for full-ocean-depth operation multiply unit costs by factors of four to six compared to shallow-water equivalents. Budget-constrained research fleets defer replacement cycles.
Strategic Opportunities
- Arctic Sovereignty Patrol Expansion:Canadian and Danish naval programs are commissioning ice-capable sonar suites for contested Northwest Passage operations. Extended operating temperature ranges and ice-impact hardening represent unmet specification gaps.
- Offshore Wind Foundation Survey:European developers require high-resolution bathymetric mapping for turbine base placement in the North Sea and Baltic. Synthetic aperture systems are displacing conventional multibeam echosounders for sediment penetration accuracy.
- Quantum Sensing Convergence:Atomic interferometry for gravity gradient detection is integrating with acoustic arrays for hybrid submarine localization. Japanese and Australian defense research agencies are funding joint demonstration programs.
Industry Challenges
- MIL-STD-810 Environmental Qualification:Shock and vibration testing for surface ship hull mounting consumes eighteen to twenty-four months and millions in pre-production expenditure. Design iteration cycles compress competitive response windows.
- Legacy System Architecture Integration:New active arrays must interface with analog-era combat management systems aboard mid-life frigates. Protocol translation hardware adds weight, power draw, and failure points.
- Acoustic Signature Database Management:Machine-learning classification requires continuous updating of target echo and radiated noise libraries. Classification authorities restrict cross-border data sharing between allied operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SONAR System Market |
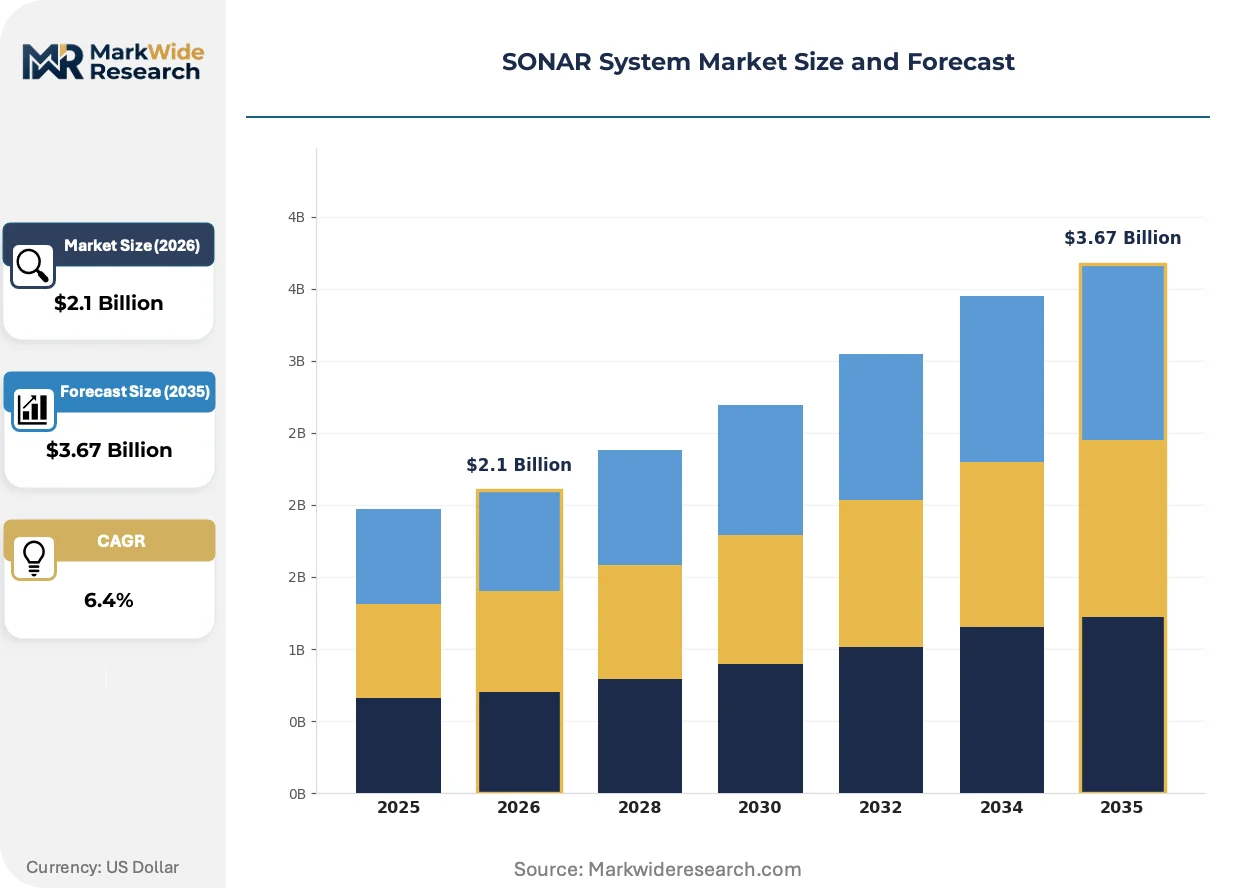
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Active Sonar, Passive Sonar, Synthetic Aperture Sonar, Multistatic Sonar, Interferometric Sonar Frequency Range: Low Frequency, Medium Frequency, High Frequency, Ultrasonic, Broadband Application: Navigation, Underwater Communication, Object Detection, Depth Measurement, Seabed Mapping End User: Naval Defense, Maritime Research Institutions, Commercial Fishing, Offshore Exploration |
| Companies Covered | Thales Group, Raytheon Technologies Corporation, Lockheed Martin Corporation, L3Harris Technologies, Kongsberg Gruppen, Atlas Elektronik, Teledyne Technologies Incorporated, Sonardyne, Ultra Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SONAR System Market Strategic Shifts & Innovations
Acoustic processing architectures are migrating from centralized combat system computers to distributed edge nodes, while regulatory pressure on marine mammal protection is rewriting operational protocols for active transmission.
Software-defined sonar is decentralizing signal generation and beamforming from dedicated hardware to reprogrammable FPGA arrays. Naval operators are adopting open-architecture standards that permit field upgrades without dry-dock replacement. This shift is compressing procurement cycles from platform-locked decades to capability-refresh intervals of three to five years.
The International Maritime Organization's revised guidelines for the reduction of underwater noise from commercial shipping are mandating passive acoustic monitoring on newbuild vessels above defined tonnage thresholds. Shipyards in South Korea and Japan are pre-installing hull-mounted hydrophone arrays to satisfy port state control inspections. Classification societies are developing dual-use certification standards that bridge naval and commercial compliance requirements.
Research institutions are unbundling hardware acquisition from data processing subscriptions, contracting cloud-based target classification and seabed change detection as annual services. The Woods Hole Oceanographic Institution and Scripps Institution of Oceanography have shifted multi-vehicle survey fleet management to platform-as-a-service models. This reconfiguration is most visible in United States and Australian academic and government research fleets where capital budgets face sustained pressure.
SONAR System Market Segmentation
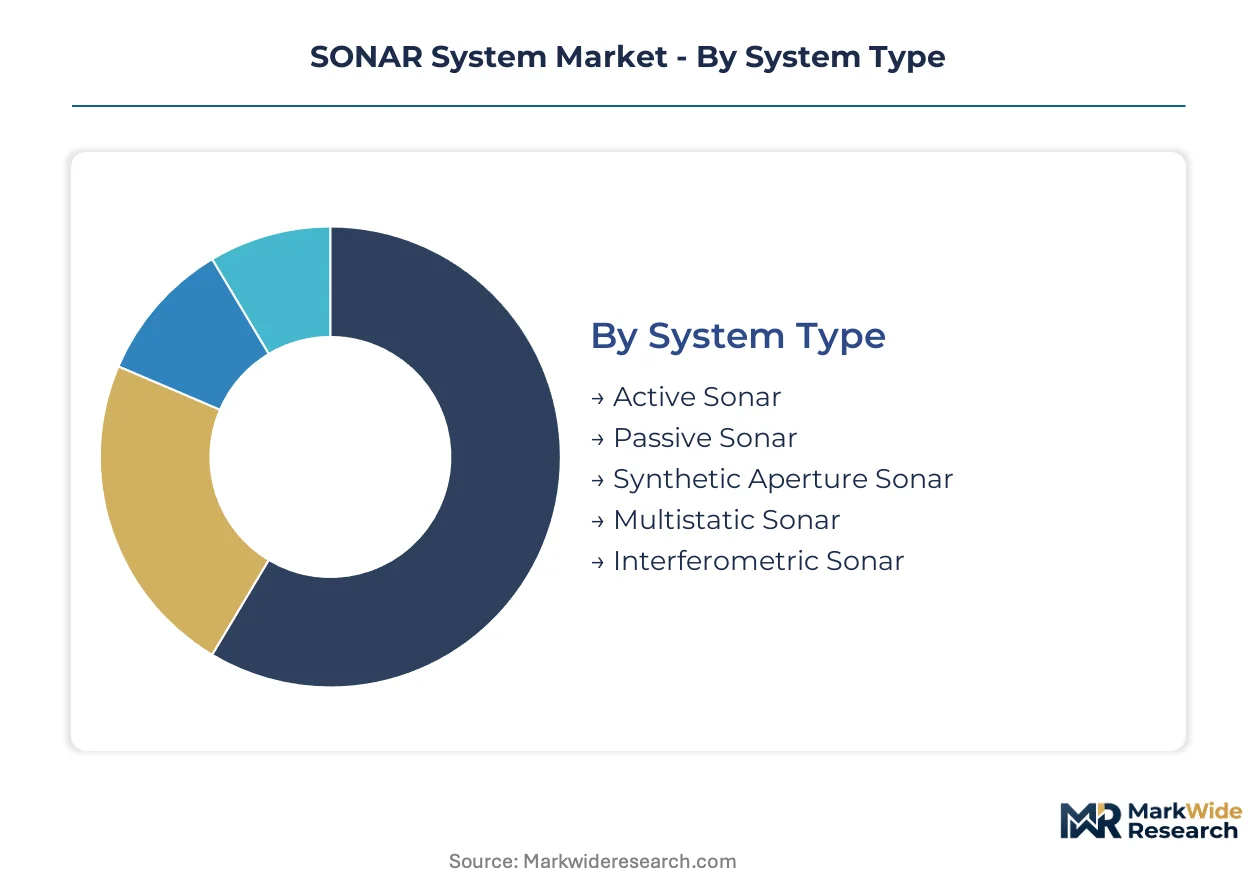
SONAR system procurement decisions pivot on mission profile, acoustic environment, and platform constraints. Segment boundaries blur as multistatic and software-defined architectures enable single hardware suites to serve multiple functions.
System Type:
Transmitter architecture and signal processing topology define operational capability and procurement cost tiers.
- Active Sonar:Systems generate acoustic pulses and analyze returning echoes for precise range and bearing determination. Naval defense budgets concentrate here due to anti-submarine warfare targeting requirements and integration with combat management systems.
- Passive Sonar:Arrays detect radiated noise from vessels and marine life without emitting signals. Research institutions in Norway and Australia prioritize these for non-invasive cetacean monitoring under tightening IMO environmental guidelines.
- Synthetic Aperture Sonar:Motion-compensated signal synthesis achieves along-track resolution independent of range. Offshore pipeline inspectors in the North Sea specify these for sediment penetration accuracy exceeding conventional side-scan systems.
- Multistatic Sonar:Separated transmitter and receiver geometries complicate target countermeasures. NATO's Undersea Research Centre coordinates interoperability standards for allied fleet deployments.
- Interferometric Sonar:Phase-difference processing generates high-resolution bathymetric point clouds. Port authorities in Japan deploy these for dredging volume calculations and obstacle detection.
Active Sonar leads on scale; Synthetic Aperture Sonar leads on momentum.
Frequency Range:
Operating frequency determines detection range, resolution trade-offs, and propagation characteristics in varying water conditions.
- Low Frequency:Signals below 1 kHz propagate over hundreds of kilometers with minimal absorption. Strategic submarine detection systems in the United States and United Kingdom deploy these for open-ocean surveillance.
- Medium Frequency:1-10 kHz balances range and resolution for hull-mounted naval arrays. Surface combatant upgrade programs specify these for torpedo defense and mine avoidance.
- High Frequency:10-100 kHz enables centimeter-scale resolution for short-range applications. Autonomous underwater vehicle manufacturers in Norway integrate compact high-frequency modules for infrastructure inspection.
- Ultrasonic:Above 100 kHz frequencies support precision imaging and underwater communication. Research institutions deploy these for sediment classification and biological sampling.
- Broadband:Frequency-agile waveforms adapt to environmental conditions and target types. Software-defined architectures are displacing fixed-frequency legacy systems in new procurement specifications.
Medium Frequency dominates current procurement volumes; Broadband architectures are climbing the fastest.
Application:
Mission function dictates sensor configuration, processing requirements, and platform integration complexity.
- Navigation:Forward-looking obstacle avoidance and channel-following for surface and subsurface vessels. Commercial shipping operators in Japan pre-install hull-mounted systems to satisfy port state control requirements.
- Underwater Communication:Acoustic modem networks enable data exchange where radio frequencies cannot propagate. Naval forces and offshore operators deploy these for tetherless AUV coordination.
- Object Detection:Submarine, mine, and diver localization for defense and security applications. Active multistatic arrays are gaining share fastest in contested littoral environments.
- Depth Measurement:Precision bathymetry for charting and construction surveys. Echo sounder configurations dominate commercial fleet specifications.
- Seabed Mapping:High-resolution topographic and substrate classification for resource exploration. Synthetic aperture and interferometric systems are displacing conventional multibeam configurations in North Sea wind farm site surveys.
Object Detection commands the largest defense allocation; Seabed Mapping shows the steepest expansion trajectory.
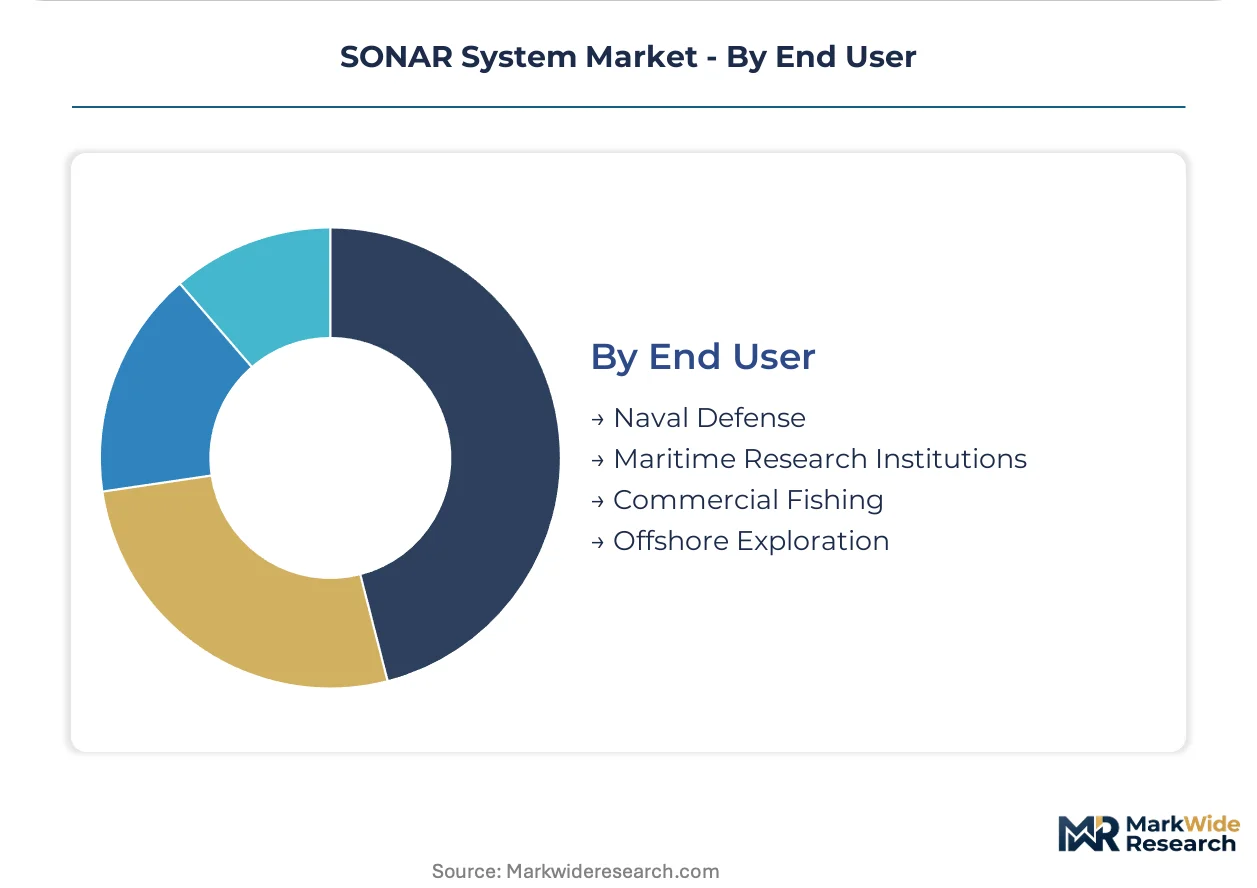
End User:
Customer category determines funding source, certification requirements, and procurement cycle timing.
- Naval Defense:National security procurement with MIL-STD qualification requirements and classified processing algorithms. The US Navy's Next-Generation Overmatch program and NATO modernization initiatives concentrate demand here.
- Maritime Research Institutions:Academic and government science funding with open-data publication mandates. Woods Hole Oceanographic Institution and Scripps Institution of Oceanography are shifting to platform-as-a-service fleet models.
- Commercial Fishing:Fish-finding and net-monitoring systems with cost-sensitive specifications. Operators in Norway and Australia balance catch optimization against regulatory monitoring requirements.
- Offshore Exploration:Oil, gas, and renewable energy site survey and infrastructure inspection. European wind developers in the North Sea and Baltic are accelerating synthetic aperture procurement for foundation placement accuracy.
Naval Defense leads on absolute expenditure; Offshore Exploration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval modernization programs in the United States, United Kingdom, Norway, Japan, and Australia concentrate procurement demand for multistatic and synthetic aperture systems. Each market shapes specifications through distinct defense procurement frameworks and environmental regulatory pressures.
United States
The US Navy's Next-Generation Overmatch program drives integrated multi-function sonar replacements across surface combatants. Naval Sea Systems Command enforces MIL-STD-461 and MIL-STD-810 compliance for electromagnetic interference and environmental ruggedness. Defense contractors in Virginia and Rhode Island coordinate Aegis combat system integration for hull-mounted array upgrades.
United Kingdom
British naval modernization through NATO's Undersea Research Centre accelerates multistatic deployment timelines for anti-submarine warfare. The Ministry of Defence specifies interoperability standards for allied fleet coordination. Industrial clusters in Scotland and southern England focus on synthetic aperture payload development for autonomous underwater vehicle integration.
Norway
Offshore energy operators in the North Sea contract compact synthetic aperture systems for pipeline inspection below diver limits. The Norwegian Maritime Authority implements IMO underwater noise guidelines through port state control inspections. Kongsberg-area manufacturers specialize in high-frequency modules for autonomous underwater vehicle specifications.
Japan
Japanese defense research agencies fund joint quantum sensing demonstration programs with Australian counterparts for hybrid submarine localization. METI coordinates standards for commercial shipping noise reduction technologies. Shipyards in Nagasaki and Kobe pre-install hull-mounted hydrophone arrays to satisfy classification society requirements for newbuild vessels.
Australia
Australian naval programs commission ice-capable sonar suites for contested maritime operations in southern waters. The Department of Defence prioritizes extended operating temperature ranges and ice-impact hardening specifications. Research institutions in Perth and Sydney shift multi-vehicle survey fleet management to platform-as-a-service models under capital budget constraints.
SONAR System Market Key Industry Players
Global majors compete with regional champions across defense procurement and commercial survey segments, creating a tiered structure where scale-driven system integrators coexist with specialized payload developers. Market concentration remains moderate due to divergent certification requirements between naval and commercial applications. Three archetypes dominate: full-spectrum defense contractors with combat system integration capabilities, compact payload specialists serving autonomous vehicle manufacturers, and dual-use providers bridging military and environmental monitoring demand. Competitive moves center on strategic partnerships for interoperability compliance and portfolio diversification into software-defined architectures.
Within the defense-contractor tier, Thales Group and Raytheon Technologies Corporation exemplify full-spectrum integration capabilities spanning inertial navigation suites and Aegis combat system interfaces. Kongsberg Gruppen occupies a distinct position among Nordic specialists, representing the compact payload archetype for autonomous underwater vehicle deployments. These three anchors illustrate how geographic clustering around national procurement programs shapes competitive positioning without requiring uniform global scale.
| Leading Market Players |
|---|
| Thales Group |
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| Kongsberg Gruppen |
| Atlas Elektronik |
| Teledyne Technologies Incorporated |
| Sonardyne |
| Ultra Electronics |
| Others |
Cost & Logistics Intelligence
Neodymium and samarium-cobalt magnet costs cascade from Chinese processing facilities through transducer manufacturing tiers, compressing margins for Western defense contractors while premium naval arrays sustain pricing power through MIL-STD certification barriers.
Pricing Analysis
Input-cost pass-through from rare earth magnet procurement shapes three-tier pricing structure across premium, standard, and economy levels. Premium arrays with full-ocean-depth titanium housings and GaN transmitter modules command substantial premiums over shallow-water commercial equivalents. Price differentiation rests on MIL-STD-810 environmental qualification grade and combat system integration complexity. Pricing pressure stems from university research fleet budget constraints deferring replacement cycles. Commercial fishing operators exhibit highest price sensitivity; naval defense procurement shows lowest.
Supply Chain Analysis
Domestic-content mandates in US and UK naval procurement programs reshape sourcing patterns for acoustic processing hardware and inertial navigation suites. Manufacturing concentrates in the United States, United Kingdom, and Norway for defense-qualified systems, with Japan and South Korea anchoring commercial hydrophone array production. The supply chain draws from Chinese rare earth processing, Malaysian semiconductor packaging, and German precision machining for transducer ceramics. Single-source vulnerability in neodymium oxide refining poses structural risk. Distribution runs through national defense procurement offices and offshore energy operator tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where NATO's Next-Generation Overmatch program and IMO underwater noise regulations concentrate procurement toward certified, interoperable premium systems.
For Market Incumbents: Extend software-defined architecture roadmaps to compress three-to-five-year capability refresh intervals against emerging FPGA-based competitors. Deepen backward integration into GaN transmitter fabrication to secure supply continuity amid rare earth magnet sourcing constraints. Fortify positions in Aegis combat system integration and NATO interoperability certification as defensive moats.
For New Entrants and Emerging Players: Begin with compact synthetic aperture payloads for autonomous underwater vehicle manufacturers in Norway and Australia, where diver-replacement depth requirements outpace incumbent product cycles. Target offshore wind foundation survey contracts in the North Sea and Baltic as the most penetrable application segment. Pursue platform-as-a-service fleet management models to bypass capital-intensive hardware competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined architectures obsolete hardware-locked legacy platforms and acoustic processing talent scarcity constrains organic growth. Long-term viability favors dual-use providers bridging naval defense and environmental monitoring demand with open-architecture compliance. Acquisition target archetype: compact payload specialists with autonomous vehicle integration capabilities. Signal to watch: quantum sensing demonstration program milestones from Japanese and Australian defense research agencies as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Migration | FPGA-based reprogrammable arrays enable field upgrades without dry-dock replacement, compressing procurement cycles. |
| GaN Transmitter Array Integration | Gallium nitride power electronics reduce thermal management burdens while improving active sonar efficiency. |
| Multistatic Interoperability Certification | NATO Undersea Research Centre standards enable allied fleet coordination and lock in platform selection. |
| Quantum-Acoustic Hybrid Sensing | Atomic interferometry integration with acoustic arrays creates next-generation submarine localization capability. |
| Platform-as-a-Service Fleet Models | Cloud-based target classification shifts research institution procurement from capital to operational expenditure. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with naval procurement officers, autonomous vehicle platform engineers, offshore energy survey managers, and acoustic processing algorithm developers. Secondary validation draws from US Naval Sea Systems Command specifications, NATO Undersea Research Centre publications, International Maritime Organization guideline revisions, and customs trade data for transducer component flows. Bottom-up segment sizing and top-down macro constraint triangulation ensure consistency.
Rate-of-change decomposition separates volume drivers from price-mix effects across the analysis window. The analytical framework models system type, frequency architecture, application function, and end-user category with platform constraint overlays. CAGRs derive from segment-level growth trajectory synthesis against defense budget allocation patterns and offshore energy capex cycles. Industry-specific inputs include naval modernization program timelines and synthetic aperture resolution specification trends.
Several conditions sit outside the modeled scope, including classified submarine detection system parameters and acoustic signature database contents restricted by national security classification. Forecasts reflect documented assumptions about NATO interoperability standard adoption rates and IMO guideline enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market