
 Single Function Printer Market | 2026-2036
Single Function Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Single Function Printer Market Insights
Recycled plastics in chassis housings is rebalancing cost structures across the single-function printer supply base. HP Inc. leverages its North American recycling partnerships to secure post-consumer resin streams at scale. Canon Inc. sustains a dedicated polymer research lab in Japan that formulates proprietary composite blends for durability. Brother Industries Ltd. anchors its Southeast Asian assembly network with locally sourced thermoplastic suppliers to compress landed costs.
A single function printer is a dedicated output device engineered solely for document printing, typically achieving resolutions of 600 x 600 dpi to 2400 x 1200 dpi through either thermal inkjet droplet ejection or laser electrophotographic imaging, and serves commercial and institutional users requiring high-volume, reliable hard-copy production without scanning or fax overhead. Laser printers occupy the largest margin pool in enterprise procurement cycles due to lower per-page toner economics over extended duty cycles. Wireless technology segments are gaining share fastest as small office and home office users abandon tethered USB connections for cloud-managed print queues. Entry-level price tiers remain structurally crowded, compressing OEM profitability and channeling volume toward private-label alternatives.
The US EPA Energy Star program and the EU Ecodesign Directive collectively enforce escalating efficiency thresholds for active and standby power draw, compelling manufacturers to redesign power supply architectures and firmware sleep modes. Japan's METI operates a parallel Top Runner program that benchmarks printer energy performance against domestic fleet averages, creating a separate compliance track for products sold in that market. Stakeholders must monitor whether emerging semiconductor export controls disrupt the supply of application-specific integrated circuits that govern print engine controllers and wireless radio modules.
Market Dynamics
The EU Energy-related Products Directive is compressing standby power allowances for imaging equipment, forcing manufacturers to redesign power supply architectures and firmware sleep modes across entire product portfolios. This regulatory pressure is rebalancing competitive positioning toward firms with captive semiconductor design capabilities for print engine controllers.
Growth Catalysts
- Educational Hybrid Learning:Institutions in India are expanding printer deployments to support blended classroom models, sustaining hardware refresh cycles despite broader digitization trends.
- REACH Compliance Materials:EU RoHS and REACH frameworks are accelerating substitution of halogenated flame retardants in chassis plastics, opening specification windows for recycled polymer suppliers.
- Wireless Cloud Integration:Small office and home office users are abandoning tethered USB connections for cloud-managed print queues, expanding addressable market for untethered hardware configurations.
Market Restraints
- Semiconductor Supply Concentration:Application-specific integrated circuits governing print engine controllers and wireless radio modules face disruption risk from export control regimes targeting East Asian foundries.
- Toner Cartridge Substitution:Third-party remanufactured consumables are eroding OEM recurring revenue streams, compressing lifetime value calculations for hardware subsidization models.
- Active Power Efficiency Thresholds:US EPA Energy Star tightening of active-mode wattage limits is extending R&D timelines and validation costs for new product introductions.
Strategic Opportunities
- India Government Digitization:Central and state administrative workflows still rely heavily on hard-copy documentation, creating sustained institutional demand despite national digital initiatives.
- Post-Consumer Resin Integration:North American recycling partnerships are securing certified post-consumer plastic streams at scale, enabling premium positioning for circular-economy-compliant product lines.
- Managed Print Services Convergence:Integration of single-function devices into enterprise IoT monitoring platforms is creating attach-rate opportunities for predictive maintenance subscriptions.
Industry Challenges
- Firmware Security Certification:Common Criteria and FIPS 140-2 validation timelines for government procurement are extending go-to-market schedules by 8-14 months for enterprise-class devices.
- Legacy Fleet Integration:Enterprise IT departments face protocol fragmentation when merging cloud-native print queues with existing on-premise directory services and authentication systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Function Printer Market |
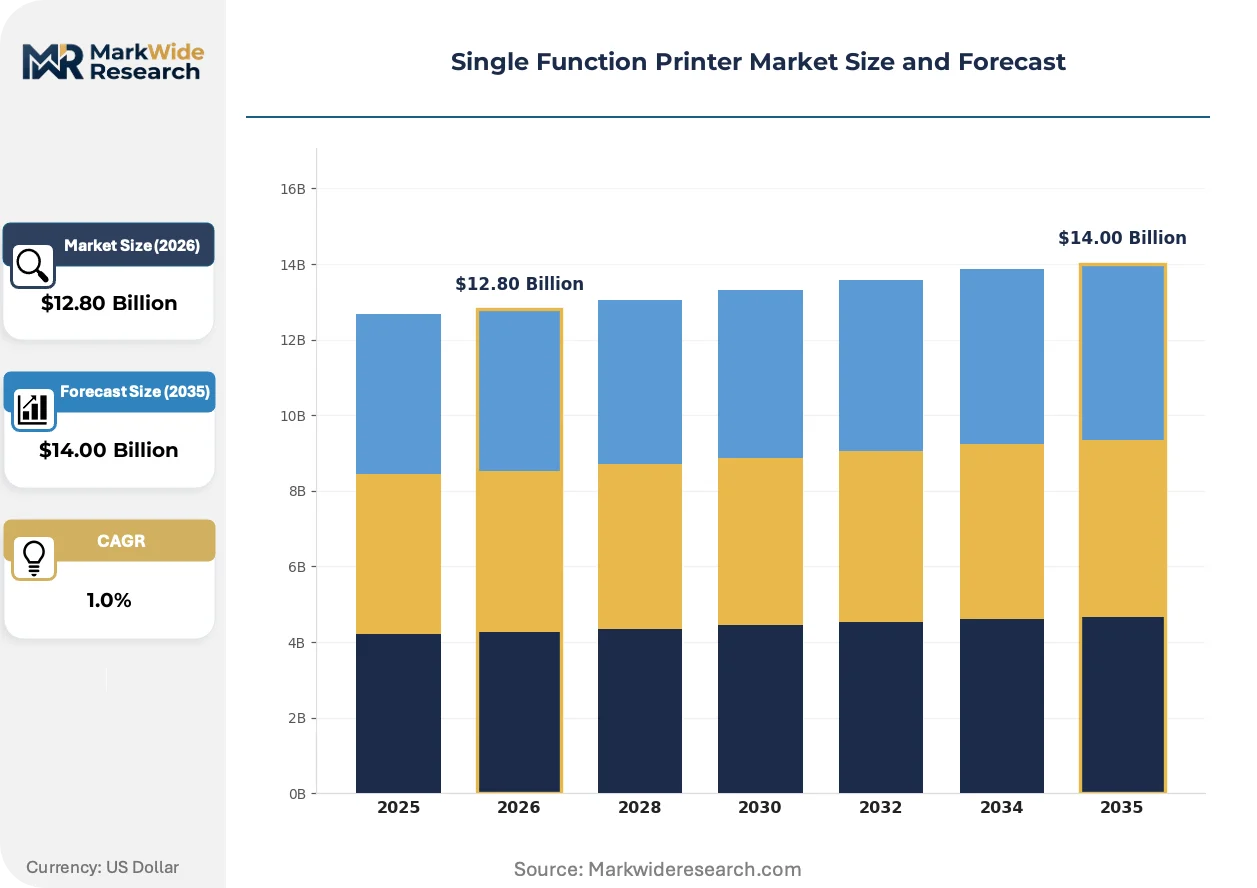
| Market Size in 2026 | $12.80 Billion |
| Market Size in 2035 | $14.00 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Thermal, Dot Matrix End User: Small Office, Home Office, Educational Institution, Large Enterprise Technology: Wireless, USB, Ethernet, Bluetooth Price Tier: Entry-Level, Mid-Range, Premium, Professional |
| Companies Covered | Brother Industries Ltd., Kyocera Corporation, HP Inc., Ninestar Corporation, Ricoh Company Ltd., Canon Inc., Xerox Corporation, Konica Minolta Inc., Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Function Printer Market Trends and Innovations
Wireless connectivity architectures are actively reshaping deployment patterns across commercial and institutional environments. Three developments are compressing traditional hardware refresh cycles and reconfiguring channel economics.
Cloud-native print management software is decentralizing fleet administration away from on-premise print servers toward browser-based dashboards. Mid-sized enterprises with distributed branch networks are adopting these platforms fastest, typically migrating 200-500 device fleets within 18-month windows. This shift is decentralizing procurement authority from centralized IT to individual facility managers, fragmenting vendor consolidation opportunities.
The EU Ecodesign Directive is tightening standby and active power draw thresholds for imaging equipment sold across member states. Manufacturers must now redesign power supply architectures and implement adaptive sleep firmware to maintain market access. Enterprise procurement teams in Germany and France are prioritizing compliant SKUs, creating specification divergence between EU and non-EU product variants.
Small office buyers are unbundling hardware acquisition from consumable supply agreements, treating printers as commodity infrastructure rather than strategic vendor relationships. E-commerce direct channels and office superstore private labels are capturing this volume, displacing traditional VAR-led consultative sales motions. This pattern is most visible in North American sub-50 employee businesses, where switching costs have collapsed and brand loyalty has eroded.
Single Function Printer Market Segmentation
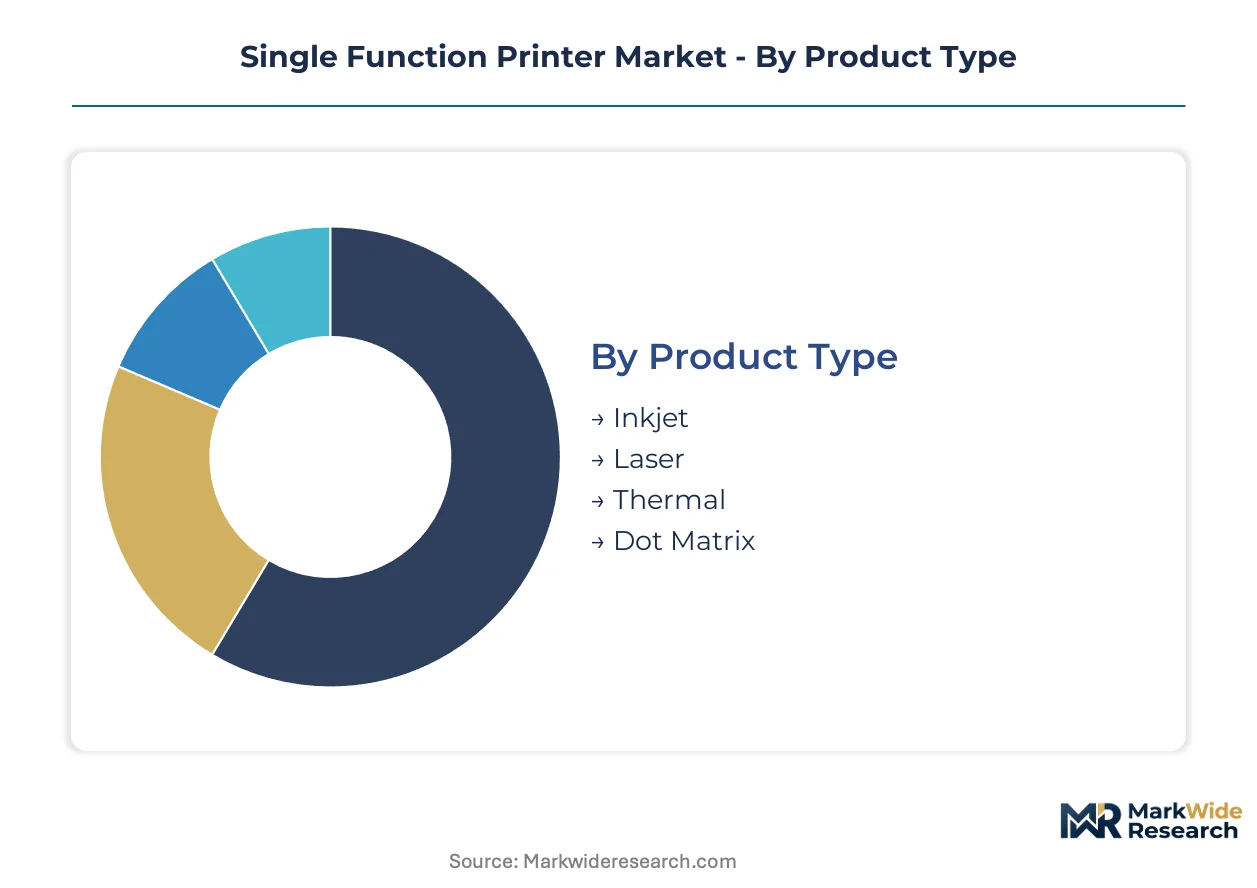
Segmentation in the single function printer market reveals how procurement authority fragments across user profiles and connectivity requirements. Manufacturers must architect product portfolios that span divergent duty cycles, from intermittent home use to continuous enterprise deployment.
Product Type:
Standardization dominates at the low end through thermal and dot matrix architectures, while inkjet and laser technologies diverge on customization axes around resolution, speed, and consumable chemistry.
- Laser:Electrophotographic imaging engines utilizing dry toner fusion achieve 20-50 ppm in monochrome configurations. Demand concentrates in large enterprise procurement cycles across Germany and France, where per-page economics override acquisition cost. EU Ecodesign Directive standby power limits are forcing redesign of fuser unit heating profiles.
- Inkjet:Thermal droplet ejection systems deposit aqueous or pigment-based inks at resolutions up to 2400 x 1200 dpi. Small office and home office users in India drive volume, prioritizing low upfront hardware cost over lifetime consumable expense. Print head longevity remains the critical reliability variable.
- Thermal:Direct thermal imaging without consumable ink or toner, restricted to specialized receipt and label applications. Logistics and retail POS deployments in Japan anchor demand through METI efficiency compliance requirements.
- Dot Matrix:Impact printing via wire pins against ribbon cartridges persists for multi-part carbon forms. Government administrative workflows in India sustain this obsolescing category despite national digitization initiatives.
Leading the category by volume: Inkjet. Growing fastest: Laser.
End User:
Volume scale inversely correlates with customization requirements, as large enterprises demand fleet manageability while home offices prioritize plug-and-play simplicity.
- Large Enterprise:Centralized procurement of 500+ device fleets with mandatory LDAP authentication and pull-printing security. Financial services and healthcare verticals in the United States specify FIPS 140-2 validated firmware, extending vendor qualification timelines.
- Educational Institution:Hybrid learning deployments require ruggedized hardware with high-duty cycle tolerance. Indian state universities are expanding lab and library printer banks to support blended classroom models despite Ministry of Education digitization mandates.
- Small Office:10-50 employee businesses with decentralized purchasing authority and minimal IT support. E-commerce direct channels capture this segment, displacing traditional VAR relationships.
- Home Office:Individual professionals and remote workers prioritizing compact footprints and wireless setup simplicity. North American sub-50 employee businesses exhibit collapsing brand loyalty and minimal switching costs.
Volume leadership: Large Enterprise. Steepest expansion trajectory: Educational Institution.
Technology:
Connectivity architecture determines deployment flexibility and ongoing management overhead, with wireless configurations commanding premium positioning against tethered alternatives.
- Wireless:Wi-Fi and cloud-native print queue integration enabling browser-based fleet administration. Mid-sized enterprises with distributed branch networks migrate 200-500 device fleets within 18-month windows, fragmenting vendor consolidation opportunities.
- Ethernet:Wired LAN connectivity for fixed infrastructure with deterministic bandwidth and security policy enforcement. Large enterprise data centers and call centers in France and Germany specify this architecture for compliance with national data protection frameworks.
- USB:Direct host tethering for single-user configurations with minimal attack surface. Home office and entry-level small office segments in India retain this specification for cost minimization.
- Bluetooth:Short-range pairing for mobile-first workflows and ad-hoc printing from tablets and smartphones. Field service technicians and healthcare mobile units in Japan utilize this for intermittent, proximity-based output.
Deployment share leader: Ethernet. Climbing the fastest: Wireless.
Price Tier:
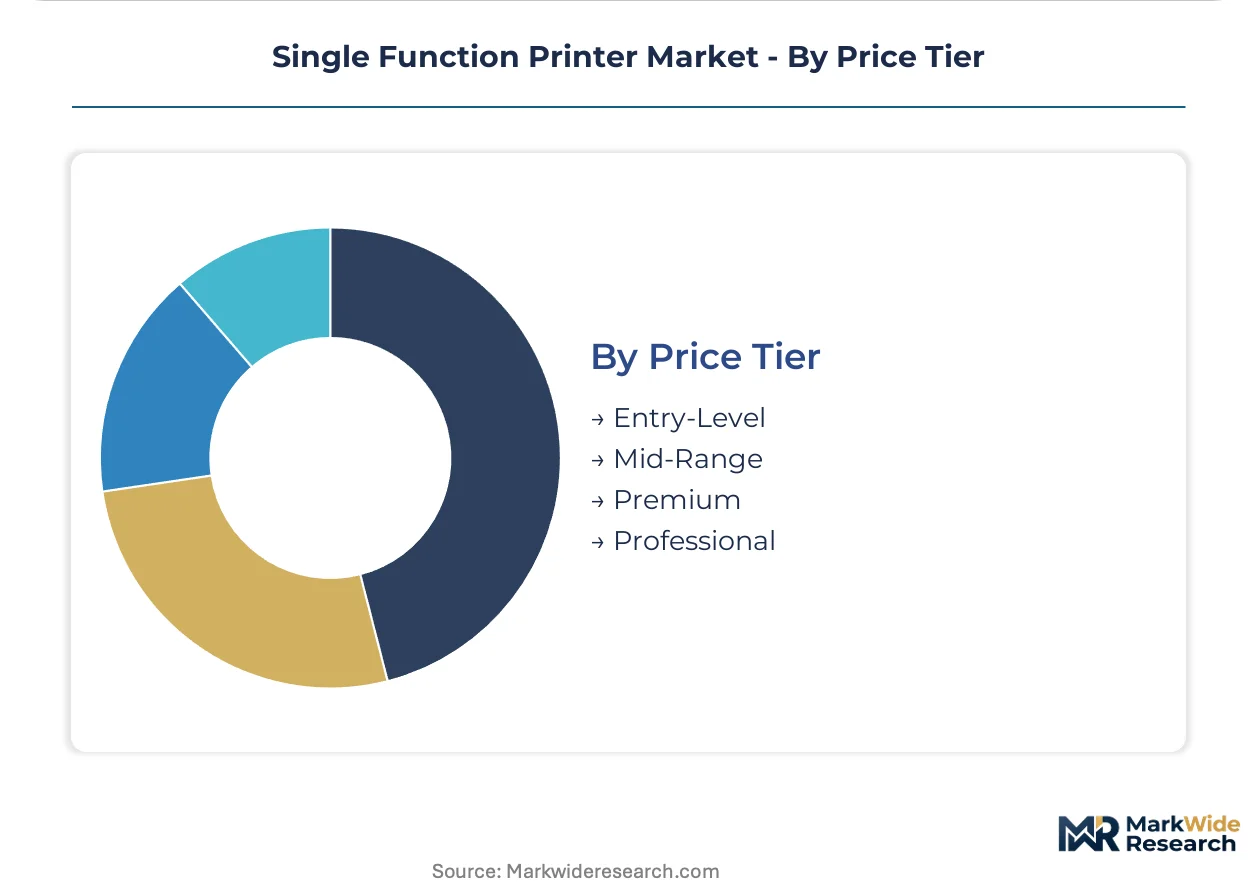
Margin structure stratifies across hardware subsidy models, with professional and premium tiers capturing lifetime consumable value while entry-level segments compress OEM profitability toward private-label displacement.
- Professional:Duty-cycle-optimized hardware with 100,000+ page monthly ratings and on-site service contracts. Large enterprise and government procurement in the United States and Germany concentrate here, with EPA Energy Star and EU Ecodesign compliance as baseline qualifiers.
- Premium:Feature-differentiated models with advanced finishing options and enhanced security modules. Financial services and legal verticals in Japan specify this tier for client-facing document production.
- Mid-Range:Balanced acquisition cost and operating economics for 20-100 employee businesses. Indian small offices and educational institutions drive volume, with Brother Industries and Canon distribution networks competing on total cost of ownership.
- Entry-Level:Sub-100 dollar hardware with minimal feature sets and highest consumable markup. North American office superstore private labels and e-commerce direct channels dominate, eroding OEM brand equity.
Revenue concentration: Professional. Gaining share fastest: Entry-Level.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates single-function printer demand through government digitization programs that retain hard-copy documentation workflows. Germany and France anchor enterprise procurement with strict efficiency mandates. The United States sustains institutional volume through educational hybrid learning deployments. Japan maintains specialized demand for thermal and impact printing architectures.
India
State universities and administrative offices expand printer banks to support blended classroom models and bureaucratic documentation. The Ministry of Electronics and Information Technology operates digitization initiatives that paradoxically sustain hardware refresh cycles. Maharashtra and Karnataka host distribution networks serving educational procurement clusters.
Germany
Large enterprises prioritize per-page toner economics in fleet procurement cycles exceeding 500 devices. The EU Ecodesign Directive enforces standby power limits that force fuser unit redesigns. Industrial procurement concentrated in Baden-Württemberg and Bavaria specifies EPA Energy Star compliance as baseline qualification.
United States
Educational institutions deploy ruggedized hardware for hybrid learning environments across distributed campus networks. The EPA Energy Star program tightens active-mode wattage thresholds for imaging equipment. Texas and California anchor volume through state university system standardization programs.
Japan
METI's Top Runner program benchmarks printer energy performance against domestic fleet averages, creating separate compliance tracks. Thermal imaging for logistics POS and dot matrix for multi-part forms sustain specialized demand. The Kanto region around Tokyo concentrates corporate procurement and polymer research facilities.
France
Enterprise procurement teams prioritize EU Ecodesign Directive compliant SKUs, creating specification divergence from non-EU variants. National data protection frameworks enforce Ethernet connectivity for fixed infrastructure in call centers and data facilities. The Île-de-France region drives financial services and legal vertical demand for premium-tier hardware.
Single Function Printer Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance hardware subsidy models against consumable revenue erosion. The vendor base stratifies across three tiers: diversified imaging conglomerates with captive semiconductor design, specialized printing equipment manufacturers with regional assembly networks, and private-label assemblers serving entry-level price compression. Strategic archetypes include full-stack imaging platforms, component-integrated specialists, and contract manufacturing intermediaries. Competitive moves center on recycled polymer supply chain partnerships and cloud-native print management software integration.
Among diversified imaging conglomerates, HP Inc., Canon Inc., and Brother Industries Ltd. exemplify contrasting geographic and supply chain strategies. HP Inc. anchors North American operations through post-consumer resin partnerships. Canon Inc. maintains captive polymer research capabilities in Japan. Brother Industries Ltd. compresses landed costs through Southeast Asian thermoplastic supplier integration. These three represent the spectrum from recycling-driven circular economy positioning to upstream materials control.
| Leading Market Players |
|---|
| Brother Industries Ltd. |
| Kyocera Corporation |
| HP Inc. |
| Ninestar Corporation |
| Ricoh Company Ltd. |
| Canon Inc. |
| Xerox Corporation |
| Konica Minolta Inc. |
| Seiko Epson Corporation |
| Others |
Pricing and Supply Chain Analysis
Assembly technician clusters in Vietnam and Thailand compress labor-cost differentials, enabling OEMs to maintain three-tier hardware spreads despite resin and semiconductor input volatility.
Pricing Analysis
Volume concentrates in entry-level inkjet tiers where private-label assemblers erode brand premiums, while margin pools concentrate in professional laser configurations with 100,000+ page monthly ratings. Price differentiation hinges on EPA Energy Star certification tier and bundled managed print service contracts. Cost compression in entry-level segments intensifies because e-commerce direct channels collapse switching costs. Educational institutions in India exhibit highest price sensitivity, whereas financial services verticals in Germany prioritize per-page economics over acquisition cost.
Supply Chain Analysis
EU Ecodesign Directive qualification gates access for fuser unit architectures and adaptive sleep firmware modules, forcing redesign cycles before market entry. Manufacturing concentrates in China, Vietnam, and Thailand for final assembly, with Japan and Taiwan supplying print engine controllers and precision stepper motors. The supply chain draws from post-consumer resin streams in North America and halogen-free flame retardant compounds from EU-certified polymer labs. Single-source vulnerability sits with application-specific integrated circuits from East Asian foundries facing export control exposure. Distribution runs through office superstore retail networks and VAR channels for enterprise fleets, with e-commerce direct capture accelerating in sub-50 employee segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless cloud-managed print queues are displacing tethered USB architectures, compressing refresh cycles and fragmenting procurement authority toward facility managers.
For Market Incumbents: Lock in post-consumer resin partnerships to secure circular-economy positioning ahead of EU REACH compliance deadlines. Deepen captive semiconductor design capabilities for print engine controllers to mitigate foundry concentration risk. Consolidate cloud-native print management platforms to capture predictive maintenance subscription attach rates before channel partners disintermediate fleet administration. For New Entrants and Emerging Players: Enter via India's government digitization workflows, where hard-copy documentation sustains institutional demand despite national digital initiatives. Target educational hybrid learning deployments requiring ruggedized hardware with minimal IT support overhead. Pursue private-label assembly contracts with North American office superstore chains to capture entry-level volume without brand equity investment. For Investors and Strategic Acquirers: Re-rating potential sits with managed print services platforms given convergence of single-function devices into enterprise IoT monitoring architectures. Long-term viability favors providers integrating hardware subsidy models with consumable revenue streams and predictive maintenance software. Watch semiconductor export control enforcement against East Asian foundries as inflection indicator for controller supply disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Integration | HP Inc.'s North American recycling partnerships secure certified plastic streams for circular-economy product lines. |
| Cloud-Native Print Management Platform | Browser-based fleet administration fragments vendor consolidation opportunities across mid-sized distributed enterprises. |
| Captive Semiconductor Design Capability | In-house controller development mitigates foundry concentration risk from export control regimes targeting East Asia. |
| Managed Print Services Convergence | IoT monitoring integration creates predictive maintenance subscription attach-rate opportunities in enterprise fleets. |
| EU Ecodesign Compliance Redesign | Fuser unit heating profile adaptation maintains market access as standby power thresholds tighten across member states. |
Research Methodology
Document review covered SEC 10-K filings, EU Ecodesign Directive technical documentation, and METI Top Runner program benchmarks, complemented by interviews with OEM product managers, enterprise IT procurement officers, educational facility directors, and office supply channel distributors. Secondary validation drew from EPA Energy Star certification databases, customs trade data on imaging equipment imports, and GPO contract repositories for government printer fleet acquisitions. Bottom-up device shipment estimates triangulated against top-down consumable revenue analysis across laser toner and inkjet cartridge categories.
Unit shipment and revenue outputs reflect segmentation modeling across product type, end user, connectivity technology, and price tier dimensions, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from historical trajectory analysis adjusted for technology substitution patterns and compliance-driven refresh cycles. Forecast inputs incorporated EU standby power limit phase-in schedules, India government digitization procurement timelines, and semiconductor foundry capacity allocation trends.
Revisions become necessary when semiconductor export controls expand to additional foundry jurisdictions, when EU Ecodesign Directive thresholds accelerate beyond published phase-in schedules, or when India administrative digitization mandates eliminate hard-copy documentation requirements. Forecasts reflect assumptions on resin supply certification availability and wireless protocol adoption curves. A model refresh is warranted upon material change in managed print services platform consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Refurbished Printers Market
Printers
Multi-Functional Printer Market
Printers
Global Printer Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Aerosol Printing and Graphics Market
Printers
Inkjet Printing Market
Printers
Ink Tank Printer Market
Printers
Global Thermal Printing Market
Printers
Dot Matrix Printer Market
Printers
Thermal Inkjet Printer Market
Printers
Laser Printer Market
Printers
Indonesia Thermal Printer Market
Printers
Mobile Photo Printer Market
Printers
India Inkjet Printer Market
Printers
Mobile Printer Market
Printers
Global UV LED Printers Market