
 Global Electrical Insulation Paper Market | 2026-2036
Global Electrical Insulation Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical Insulation Paper Market Intelligence
A scarcity of materials scientists skilled in high-purity cellulose chemistry and dielectric formulation is redrawing competitive positioning. DuPont leverages its long history in polymer science to lead the high-performance aramid paper segment. Weidmann specializes in comprehensive insulation solutions for large power transformers, anchoring its position in the utility sector. 3M competes with a broad portfolio of both paper and synthetic-based insulation products for various electrical equipment.
Electrical insulation paper is a specially manufactured material, often from unbleached sulphate pulp, designed for high dielectric strength and mechanical durability. It serves as the primary insulation barrier between conductive elements in electrical apparatus. While traditional Kraft paper continues to lead the product type segment by volume, synthetic paper technologies are gaining share in demanding applications. Transformers remain the largest application, consuming the majority of insulation paper for winding and layer insulation.
Product specifications are heavily influenced by international and national standards. The IEC 60641 series sets requirements for pressboard and paper, while UL standards are critical for market access in North America. In parallel, China's mandatory GB standards govern the quality and performance of papers used in its domestic power equipment. Equipment manufacturers must navigate these varying requirements to ensure global compliance and product reliability.
Market Dynamics
The market's central dynamic is the tension between accelerating demand for high-thermal-class papers, driven by grid modernization and EV infrastructure, and the constrained supply of specialized knowledge in high-purity cellulose chemistry and dielectric formulation.
Growth Catalysts
- Grid Modernization Programs:Government-led initiatives in the United States and Germany to upgrade aging power grids are accelerating the replacement of old transformers, directly boosting insulation paper consumption.
- Electric Vehicle Infrastructure:China's massive rollout of public and private EV charging stations creates substantial, continuous demand for distribution transformers and their requisite insulation components.
- Renewable Energy Integration:The connection of new wind and solar farms to national grids requires specialized step-up transformers and switchgear that rely on high-performance insulation papers for reliability.
Market Restraints
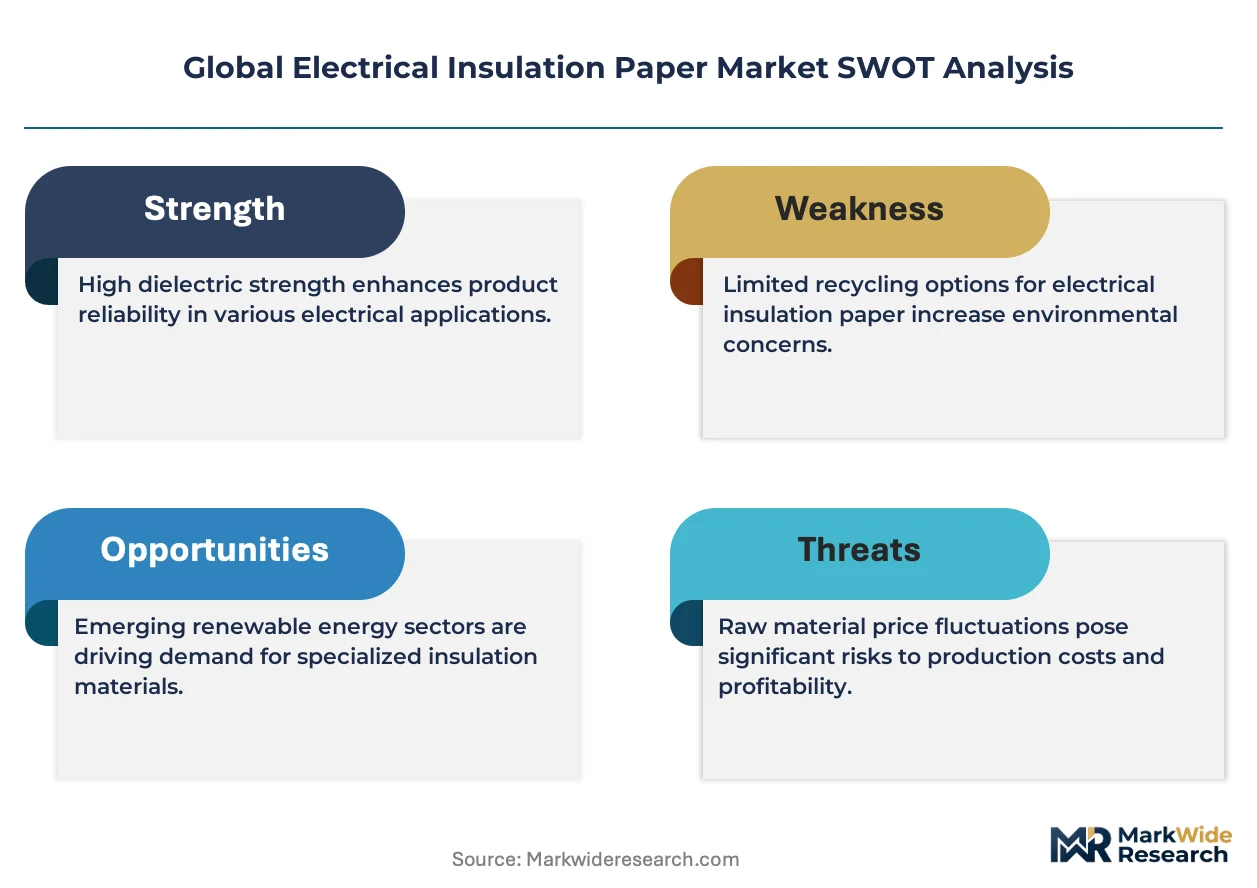
- Raw Material Constraints:The market depends on a limited supply of high-purity unbleached sulphate wood pulp, with prices and availability subject to forestry regulations and logistical disruptions.
- Threat of Substitution:In high-frequency or high-temperature applications, advanced polymer films and new liquid dielectric fluids present a significant substitution threat to traditional paper-based insulation systems.
- Energy-Intensive Manufacturing:Production of pressboard and specialty papers is highly energy-intensive, exposing manufacturers to cost pressures from volatile electricity prices, especially within the European Union.
Strategic Opportunities
- Bio-Based Synthetic Papers:Developing insulation papers from biodegradable polymers offers a path to meet sustainability goals, aligning with frameworks like the EU Green Deal and corporate ESG mandates.
- High-Voltage DC Systems:The expansion of HVDC transmission lines in countries like India and Brazil creates a niche for insulation papers engineered for superior performance under DC electrical stress.
- Data Center Power Infrastructure:Growth in cloud computing and AI drives data center construction, creating a high-value application segment for insulation paper used in uninterruptible power supplies and power distribution units.
Industry Challenges
- Specialized Talent Deficits:A scarcity of material scientists and chemical engineers with deep expertise in cellulose chemistry and dielectric science impedes innovation and new product development cycles.
- Complex Compliance Requirements:Manufacturers must navigate and conform to a fragmented landscape of standards, including IEC 60641, UL certifications, and China's mandatory GB standards, increasing testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical Insulation Paper Market |
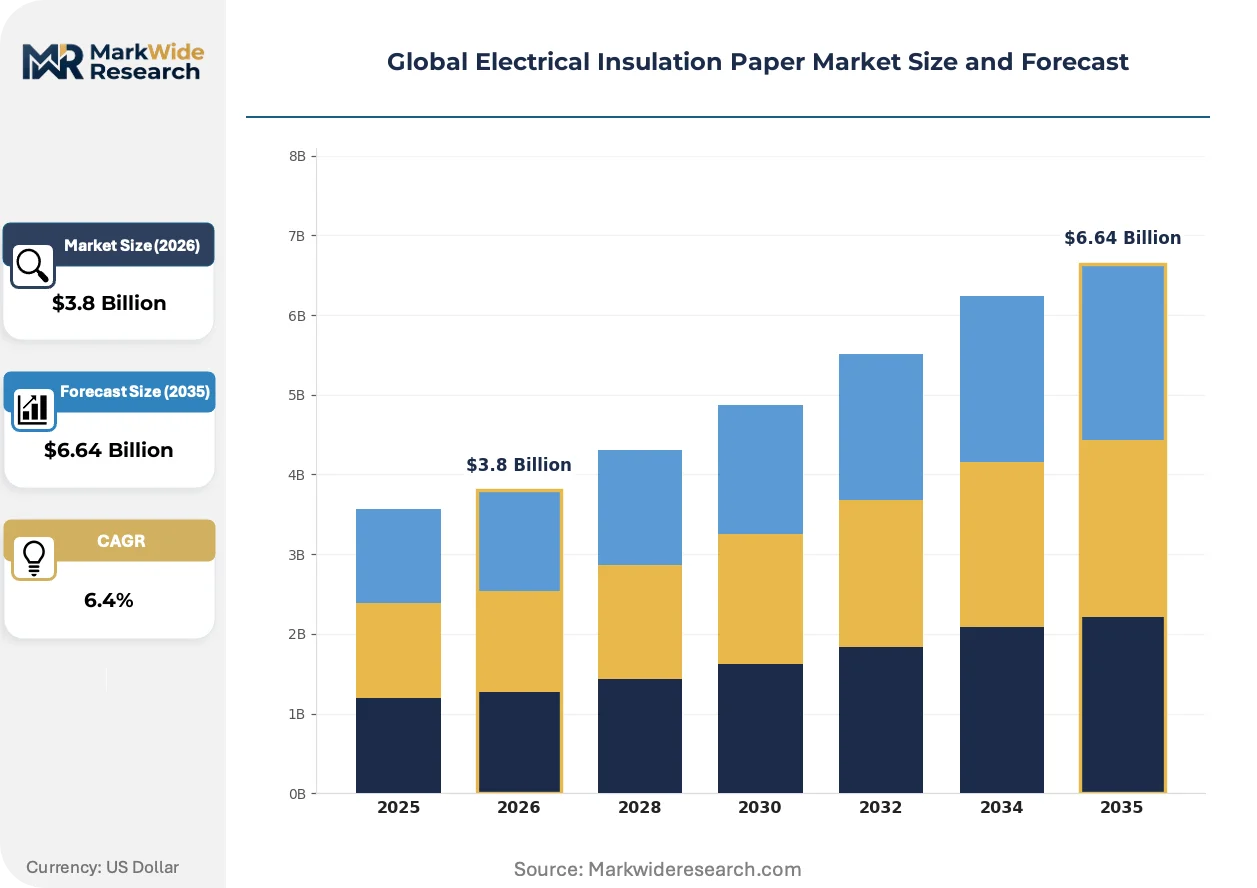
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
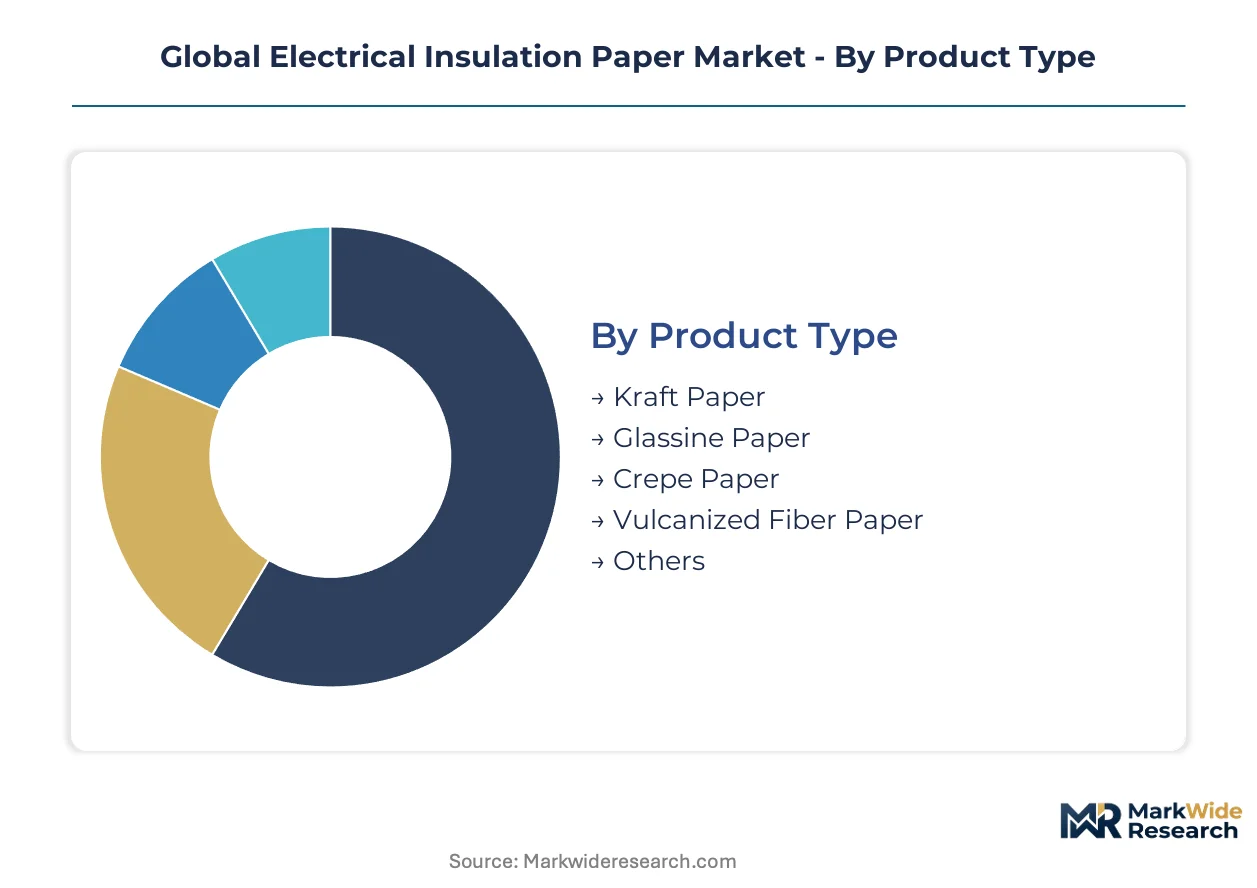
| Segmentation | Product Type: Kraft Paper, Glassine Paper, Crepe Paper, Vulcanized Fiber Paper, Others Application: Transformers, Motors, Switchgears, Capacitors, Generator Units Technology: Oil-Impregnated, Dry-Type, Synthetic Paper, Composite Paper End User: Power Generation Plants, Electrical Equipment Manufacturers, OEMs, Substation Operators |
| Companies Covered | Nitto, VonRoll, DuPont, Delfortgroup AG, Teijin Aramid, 3M, Weidmann, Cottrell Paper Company, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical Insulation Paper Market Strategic Shifts & Innovations
Material science advancements are focused on enhancing thermal endurance and dielectric strength to support the increasing power density of modern electrical equipment. This push for performance is redefining product specifications and creating new value tiers within the market.
Aramid-mica hybrid paper is a key product evolution, offering superior thermal stability and partial discharge resistance compared to traditional Kraft paper. It is rapidly being adopted by manufacturers of traction motors for electric vehicles and converters for renewable energy systems. This technology is miniaturizing critical power components, enabling more compact and energy-efficient designs in demanding automotive and aerospace applications.
The continuous revision of the IEC 60641 series of standards is a significant regulatory driver, pushing thermal class requirements ever higher. This forces insulation paper producers to innovate and validate materials capable of withstanding higher continuous operating temperatures. Transformer manufacturers are most affected, as they must source these advanced papers to design more powerful yet compact equipment compliant with the latest standards.
A notable demand-side shift is the move from buying paper as a discrete component to specifying complete, tested insulation systems. This trend disrupts traditional component-level procurement, favoring suppliers who can offer integrated solutions combining paper, pressboard, and other insulating elements. The shift is most pronounced in the large power transformer segment, where utilities in North America and Europe prioritize system reliability and long-term performance guarantees.
Global Electrical Insulation Paper Market Segmentation
The global electrical insulation paper market's complex structure reflects diverse product types, applications, technologies, and end-user requirements. Understanding these segments is crucial for identifying areas of concentrated demand and emerging growth trajectories across the electrical apparatus industry. Each category reveals unique market dynamics influencing material selection and procurement strategies.
Product Type:
Product type segmentation often reflects the geographical distribution of manufacturing capabilities, with traditional papers having a broader global presence compared to specialized synthetic variants.
- Kraft Paper:This material, typically made from unbleached sulphate pulp, offers high dielectric strength and mechanical durability for general insulation purposes. Demand for Kraft paper remains substantial in large power transformers for grid modernization initiatives across the United States and Germany.
- Synthetic Paper:Engineered from advanced polymers like aramid, synthetic paper provides superior thermal endurance and partial discharge resistance for high-performance applications. Adoption is accelerating in compact electrical designs for electric vehicle traction motors and renewable energy converters, especially in China.
- Glassine Paper:A thin, translucent paper, glassine finds application in smaller electrical components where space is at a premium and moderate insulation is required.
- Crepe Paper:Known for its flexibility and conformability, crepe paper is used for insulation in irregular shapes and winding applications within various electrical apparatus.
- Vulcanized Fiber Paper:This robust, dense material offers excellent mechanical strength and arc resistance, often employed in circuit breakers and fuse tubes.
- Others:This category includes various specialty papers and customized formulations designed for niche electrical insulation requirements.
Kraft Paper holds the largest share; momentum sits with Synthetic Paper.
Application:
The application landscape dictates insulation paper specifications, with high-power equipment demanding more stringent performance characteristics.
- Transformers:These devices represent the largest application segment, consuming insulation paper for winding, layer, and barrier insulation to prevent electrical breakdown. Grid modernization programs in North America and Europe are driving significant demand for advanced insulation papers in new transformer installations.
- Generator Units:Insulation papers in generator units withstand high electrical stresses and temperatures, crucial for maintaining operational efficiency and reliability in power generation facilities. Renewable energy integration, particularly for wind and solar farms, creates a consistent need for robust insulation in step-up transformers and switchgear connected to these units.
- Motors:Electrical motors utilize insulation paper for slot liners, phase insulation, and coil wrapping to ensure safe and efficient operation across industrial and consumer products.
- Switchgears:Insulation paper prevents flashovers and short circuits within switchgear assemblies, critical for power distribution and control in electrical networks.
- Capacitors:Insulation paper acts as a dielectric material in capacitors, enabling energy storage and filtering functions in various electronic and power applications.
Transformers drive the bulk of insulation paper consumption; Generator Units are expanding most quickly.
Technology:
The maturity of insulation technologies influences material selection, balancing performance, cost, and environmental considerations.
- Oil-Impregnated:This traditional technology involves saturating paper with dielectric oil, enhancing its insulating properties and heat dissipation for large power transformers. It remains a foundational technology for high-voltage applications due to its proven reliability.
- Dry-Type:Dry-type insulation systems, often using resin-impregnated paper or synthetic materials, eliminate the need for liquid coolants, making them suitable for indoor or environmentally sensitive installations.
- Synthetic Paper:Utilizing advanced polymers, synthetic papers offer superior thermal performance and partial discharge resistance without liquid impregnation, enabling more compact and higher-power-density designs. This technology is critical for new performance requirements in electric vehicle components.
- Composite Paper:These papers combine different materials, such as aramid and mica, to achieve enhanced properties like improved thermal stability and mechanical strength for demanding electrical equipment.
Oil-Impregnated technology holds substantial market presence; Synthetic Paper is gaining significant traction.
End User:
End-user segments reflect distinct procurement patterns and regulatory compliance needs for electrical insulation papers.
- Power Generation Plants:These facilities require insulation papers for large-scale generators and associated transformers, prioritizing reliability and long-term performance under continuous operation.
- Electrical Equipment Manufacturers:This segment comprises companies that integrate insulation papers into finished electrical products like transformers, motors, and switchgear. They focus on materials that meet specific design requirements and international standards such as IEC 60641 and UL.
- OEMs:Original Equipment Manufacturers procure insulation papers for assembly into their proprietary electrical systems, often requiring custom specifications and consistent material quality.
- Substation Operators:Utilities and grid operators use insulation papers primarily in power and distribution transformers within substations, demanding materials with high dielectric strength and robust mechanical properties for grid stability.
Electrical Equipment Manufacturers represent a primary consumption base; Substation Operators exhibit a steady demand trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global electrical insulation paper market exhibits varying consumption patterns, with certain regions prioritizing advanced synthetic materials while others maintain demand for traditional Kraft paper. China's rapid electric vehicle infrastructure development, for instance, drives demand for high-performance synthetic papers. Meanwhile, grid modernization efforts in Western economies sustain the need for conventional insulation solutions.
China
China's massive rollout of public and private EV charging stations creates substantial demand for distribution transformers. Its mandatory GB standards govern the quality and performance of papers used in domestic power equipment. Industrial clusters in the Pearl River Delta are rapidly integrating synthetic paper technologies into new energy vehicle components.
United States
Government-led initiatives in the United States to upgrade aging power grids accelerate the replacement of old transformers. UL standards are critical for market access and product reliability across North America. Manufacturers in the Midwest are sourcing high-thermal-class papers for new substation projects.
Germany
Germany's significant investment in grid modernization and renewable energy integration drives demand for high-performance insulation papers. The EU Green Deal encourages the development of bio-based synthetic papers. Engineering centers in North Rhine-Westphalia focus on advanced insulation solutions for compact electrical designs.
India
Expansion of High-Voltage DC (HVDC) transmission lines in India creates a niche for insulation papers engineered for superior performance. The Central Electricity Authority (CEA) guidelines emphasize reliable insulation materials for grid stability. Manufacturers in Maharashtra are procuring high-dielectric-strength papers for new power infrastructure.
Japan
Japan's focus on advanced electronics and compact electrical equipment necessitates insulation papers with enhanced thermal endurance. JIS standards are crucial for quality and performance in domestic electrical apparatus manufacturing. Industrial areas around Osaka are adopting aramid-mica hybrid papers for traction motors.
Global Electrical Insulation Paper Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the global electrical insulation paper market. This structure reflects the diverse material science requirements, ranging from high-volume Kraft paper to niche synthetic variants. Companies often specialize by product type or application, creating distinct competitive segments. Portfolio diversification and strategic partnerships are common competitive moves to access specialized knowledge and expand into new application areas like electric vehicles.
Among the established players, DuPont leverages its long history in polymer science, exemplifying leadership in the high-performance aramid paper segment. Weidmann, a Swiss-based firm, anchors its position by specializing in comprehensive insulation solutions for large power transformers, particularly in the utility sector. Furthermore, 3M, a diversified American manufacturer, occupies a strong position with a broad portfolio of both paper and synthetic-based insulation products for various electrical equipment applications. These companies represent different strategic approaches to market penetration and technology leadership, addressing diverse performance requirements and end-user needs.
| Leading Market Players |
|---|
| Nitto |
| VonRoll |
| DuPont |
| Delfortgroup AG |
| Teijin Aramid |
| 3M |
| Weidmann |
| Cottrell Paper Company |
| ABB |
| Others |
Cost & Logistics Intelligence
Extended lead times for high-thermal-class synthetic papers directly influence pricing power for specialized manufacturers, shaping procurement strategies across the global electrical insulation paper market.
Pricing Analysis
Long-term contract-based pricing dominates for traditional Kraft paper, reflecting stable demand from grid modernization projects. Price differentiation stems from material grade, such as aramid-mica hybrid papers, and UL/IEC certification levels for specialized applications. Pricing pressure stems from volatile raw material costs, particularly high-purity unbleached sulphate pulp, affecting manufacturers globally. Electrical Equipment Manufacturers are highly price-sensitive for standard grades, while Substation Operators prioritize reliability over cost for advanced insulation systems.
Supply Chain Analysis
Strategic stockpiling is common for high-purity unbleached sulphate pulp, mitigating supply disruptions and price volatility. Supply concentration for specialized synthetic papers centers in China and Germany, driven by advanced manufacturing capabilities. The market depends on a limited supply of high-purity cellulose and specialized polymer resins. Single-source vulnerability for niche dielectric formulations presents a significant supply chain risk. Distribution runs through specialized industrial distributors and direct sales channels to large electrical equipment OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story for incumbents, primarily due to the high switching costs associated with re-certifying insulation materials in critical electrical infrastructure. Reliability requirements and stringent international standards create significant barriers to entry.
For Market Incumbents: Secure long-term contracts with major utility providers and expand R&D into bio-based synthetic papers to counter substitution threats from advanced polymer films. Invest in capacity additions for high-thermal-class materials in key growth regions like China and India. Deepen vertical integration into specialized cellulose processing to control raw material quality and mitigate supply volatility.
For New Entrants and Emerging Players: UL certification fast-tracks for compact electrical designs offer a compelling entry point into the North American market. Target niche applications in electric vehicle traction motors and renewable energy converters, particularly in China's rapidly expanding EV infrastructure. Focus on developing high-performance, sustainable insulation solutions through direct sales to agile equipment manufacturers.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure play because grid modernization and EV buildouts create sustained, non-discretionary demand for insulation components. Seek acquisition targets among specialized material science firms with expertise in high-purity cellulose chemistry or advanced dielectric formulations. The signal to watch is the increasing adoption rate of aramid-mica hybrid papers in new energy applications, indicating a market shift towards performance-tier materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-Based Synthetic Papers | Aligns with EU Green Deal mandates and offers sustainable alternatives for electrical equipment manufacturers. |
| Invest in High-Thermal-Class R&D | Supports compact electrical designs and meets rising performance specifications for power transformers. |
| Expand Production in China | Addresses substantial demand from China's electric vehicle infrastructure and power equipment manufacturing. |
| Acquire Dielectric Formulation Expertise | Mitigates specialized talent deficits and accelerates innovation in advanced insulation systems. |
| Pursue IEC 60641 Compliance | Ensures market access and product reliability for transformer manufacturers in European and global markets. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data anchors the qualitative findings of this analysis. Interviews included electrical equipment procurement managers, material scientists specializing in cellulose chemistry, and utility substation operators. Secondary validation drew from IEC 60641 standards, UL certifications, and national energy grid reports. A bottom-up approach integrated with top-down triangulation ensured robust market sizing and forecasting.
Sensitivity analysis on key growth drivers informed the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, technology, end-user, and thermal class requirements. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected infrastructure spending. Inputs included global grid modernization investments and electric vehicle production forecasts.
Decision-makers should treat outputs as directional under current grid modernization and EV infrastructure buildout assumptions; material deviation would warrant model refresh. Forecasts reflect a stable regulatory environment and consistent raw material supply. Revision becomes warranted when significant shifts in global trade policies or energy transition timelines cross defined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Machinery Market
Paper Products
Thin Printing Paper Market
Paper Products
North America Coated Paper Market
Paper Products
Fluff Pulp Market
Paper Products
Global Paperboard Market
Paper Products
Compressed Fiberboard Market
Paper Products
Tissue Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Thermal Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Synthetic Paper Market
Paper Products
Chemical Cellulose Market