
 Global Paper Chemical Market | 2026-2036
Global Paper Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper Chemical Market Foresight
Packaging manufacturers are bifurcating from printing houses as the dominant procurement archetype in the paper chemical value chain. Kemira Oyj anchors its position through captive R&D in bio-based sizing agents for containerboard. BASF SE leverages its polymer backbone to dominate coating binder supply for kraft liner producers. Solenis competes on service intensity, embedding field technicians directly inside specialty paper mills to optimize wet-end chemistry.
Paper chemicals encompass functional additives and process aids used to modify pulp fiber bonding, surface properties, and machine runnability, including starch derivatives, synthetic polymers, and biocides with specified charge densities and molecular weights. Sizing agents and coating binders command the largest revenue pools due to their irreplaceable role in liquid barrier performance and print receptivity. Dry strength additives represent the fastest-growing product category as recycled fiber content rises and virgin pulp substitution intensifies. Wet end additives as an application segment concentrates margin pools where real-time process control integration creates switching costs for paper mills.
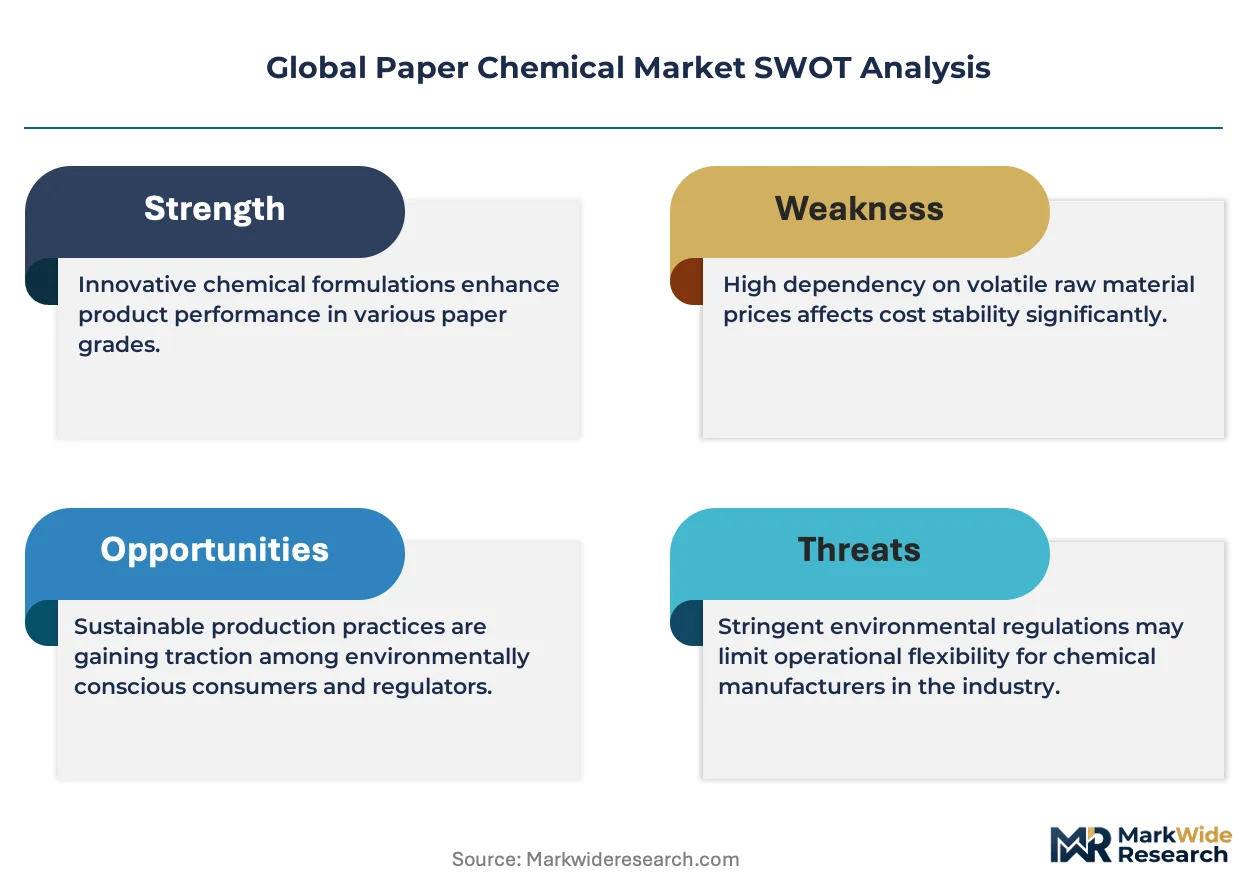
EPA effluent limitation guidelines in the United States, REACH registration requirements under ECHA in Europe, and China's GB standards under MEE collectively constrain biocide formulations and effluent chemistry across the supply chain. These frameworks elevate compliance costs for imported formulations while creating preferential market access for locally registered products. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and regional sourcing reconfigurations.
Market Dynamics
State-led capacity consolidation in China's paper mill sector is concentrating procurement power toward integrated chemical suppliers, compressing margins for fragmented specialty additive producers while rewarding scale players with captive technical service capabilities.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightening discharge standards for pulp mills in the United States are forcing reformulation of wet-end additives, creating replacement demand for compliant biocide and retention aid chemistries.
- Recycled fiber substitution:Rising post-consumer fiber content in containerboard production is accelerating consumption of dry strength additives to compensate for diminished virgin pulp bonding properties.
- Food-grade paperboard expansion:Packaging manufacturers in Germany and Italy are expanding chemical procurement for liquid barrier coatings in direct-contact food applications.
Market Restraints
- Petrochemical feedstock volatility:Synthetic polymer binders and sizing agents remain exposed to ethylene and propylene price swings, compressing formulation margins during upstream spikes.
- REACH registration burden:ECHA compliance costs for imported biocide actives into the European Union create preferential access for locally registered suppliers, fragmenting competitive access.
- Functional starch substitution:Native and modified starches from agricultural suppliers are displacing synthetic dry strength additives in cost-sensitive kraft paper grades.
Strategic Opportunities
- Bio-based sizing agent penetration:Underdeveloped adoption of AKD alternatives derived from plant-based feedstocks in India's packaging sector offers first-mover positioning ahead of BIS sustainability mandates.
- Wet-end automation integration:Real-time charge and consistency sensors from METI-supported Japanese automation vendors are creating attach opportunities for chemical suppliers with digital dosing platforms.
- China GB standard alignment:MEE enforcement of stricter effluent chemistry standards is opening contracts for registered local biocide formulators with integrated mill service networks.
Industry Challenges
- Process control engineering scarcity:Paper mills face acute shortages of wet-end chemists capable of optimizing retention, drainage, and formation chemistry simultaneously across high-speed machines.
- Legacy DCS integration friction:Chemical dosing automation from newer vendors encounters interoperability barriers with existing distributed control systems from established mill equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper Chemical Market |
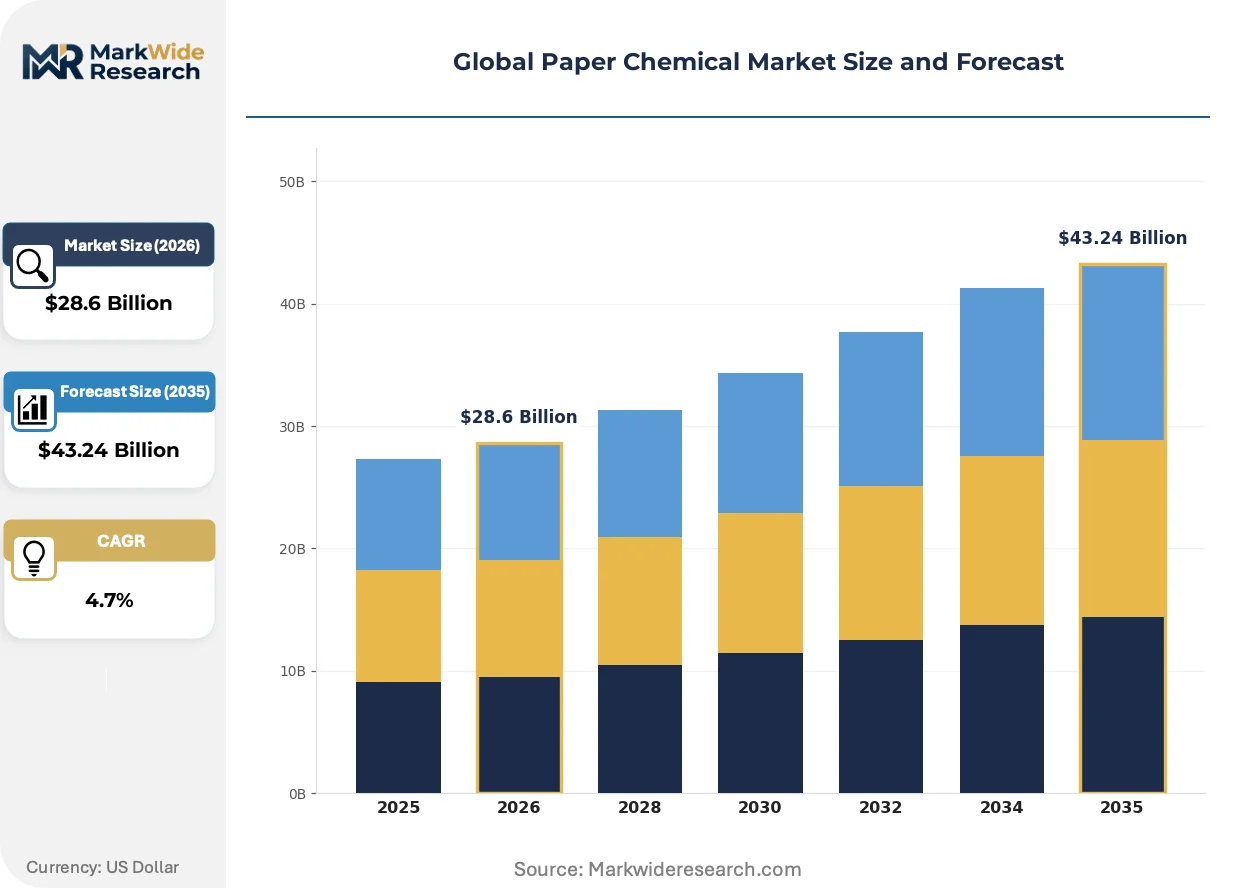
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sizing Agents, Coating Binders, Retention Aids, Biocides, Dry Strength Additives, Fillers Application: Pulp Preparation, Paper Coating, Paper Sizing, Wet End Additives End User: Packaging Manufacturers, Printing Houses, Stationery Producers, Specialty Paper Mills Packaging Type: Drums, Bulk Bags, Intermediate Bulk Containers, Carboys |
| Companies Covered | BASF SE, Kemira Oyj, Solenis, Akzo Nobel N.V., Ecolab, Ashland, Archroma, Buckman, Harima Chemicals Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper Chemical Market Shifts & Advancements
Digital process control systems and bio-based chemistries are converging to reshape how paper mills specify and consume functional additives, shifting value capture toward suppliers with embedded technical service rather than commodity formulation alone.
Enzymatic fiber modification technology is decomposing traditional mechanical refining energy requirements in recycled containerboard mills. European packaging producers are piloting cellulase and xylanase treatments at commercial scale to reduce specific energy consumption per ton. This enzymatic approach is decomposing the historical link between refining intensity and fiber bonding development, enabling lower basis weight grades without strength penalties.
REACH registration requirements under ECHA are tightening biocide active substance approvals for paper machine slimicide applications. The industrial consequence is forced reformulation toward approved actives with higher minimum effective concentrations. Specialty paper mills in Finland and Sweden are most affected, accelerating qualification of peracetic acid and chlorine dioxide alternatives ahead of 2025 authorization deadlines.
Buyer concentration among integrated packaging conglomerates is compressing chemical supplier negotiation leverage and extending contract durations. Long-term supply agreements with fixed pricing clauses are displacing spot procurement for core wet-end chemistries. This pattern is most visible in Germany's corrugated board sector, where top five producers now control over sixty percent of chemical purchasing volume.
Global Paper Chemical Market Segmentation
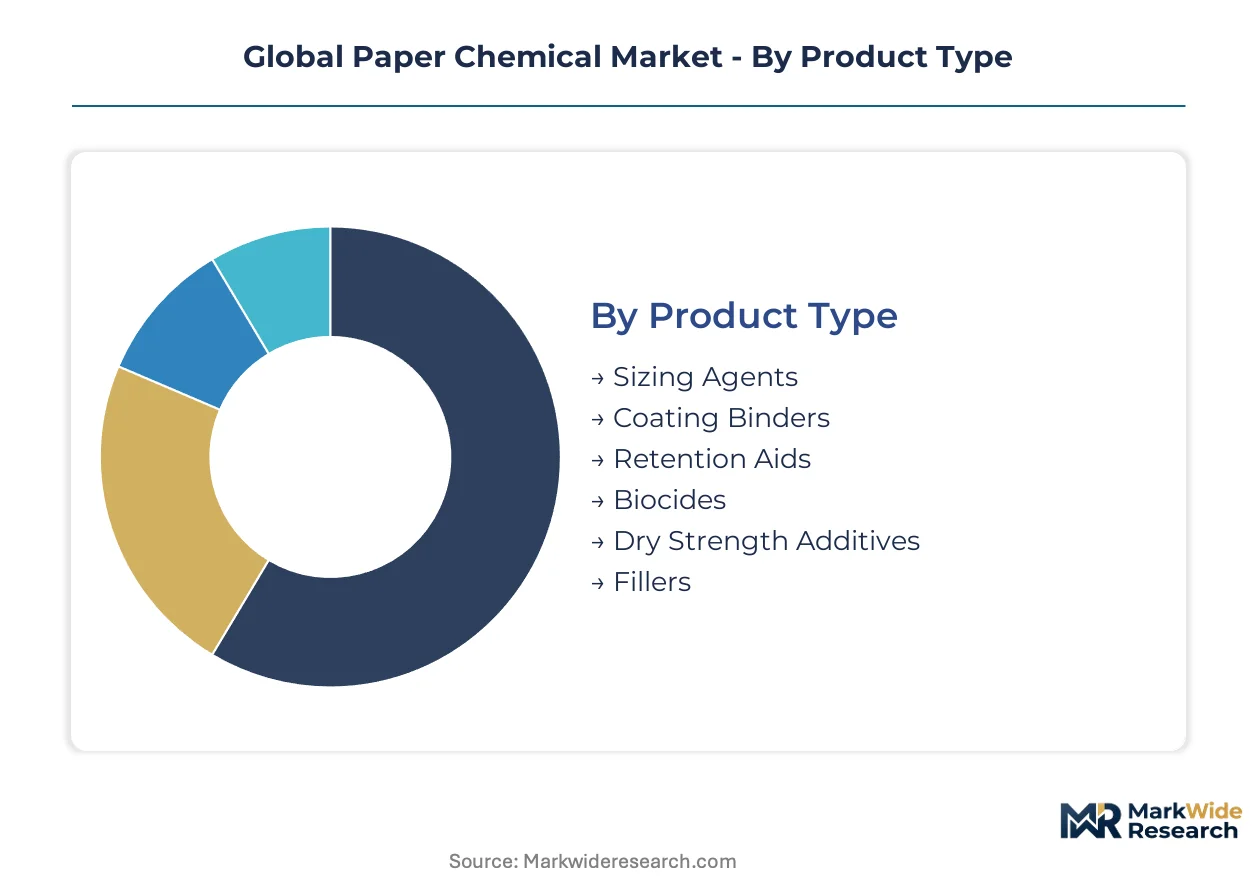
Segmentation in the paper chemical market reveals how procurement power concentrates across functional categories and end-use applications. Manufacturers configure product portfolios around specific machine positions and fiber types, creating distinct margin profiles and technical service requirements.
Product Type:
Domestic consumption dominates sizing agents and coating binders in North American and European markets, while biocides and dry strength additives see heavier export flows into Asian packaging hubs.
- Sizing Agents:Alkyl ketene dimer and rosin-based formulations create liquid barrier properties in containerboard and food-grade paperboard. German and Italian packaging manufacturers are expanding procurement for direct-contact food applications. This segment commands the established base.
- Coating Binders:Synthetic polymer backbones, primarily styrene-butadiene and polyvinyl acetate emulsions, anchor print receptivity on kraft liner surfaces. Kraft liner producers in Finland and Sweden drive specification standards for high-speed coating machines.
- Retention Aids:Cationic polyacrylamide and polyethyleneimine chemistries fix fines and fillers to fiber matrices during sheet formation.
- Biocides:Slimicide actives including isothiazolinones and peracetic acid alternatives face forced reformulation under REACH authorization deadlines.
- Dry Strength Additives:Polyacrylamide and glyoxalated polyacrylamide derivatives compensate for diminished bonding in recycled fiber furnishes. The steepest expansion runs through this segment.
- Fillers:Precipitated calcium carbonate and kaolin clay extend fiber furnish and improve optical properties in printing and writing grades.
Sizing agents and coating binders absorb the majority of procurement spend. Dry strength additives are gaining share fastest as recycled fiber substitution accelerates.
Application:
Cost tiering separates premium wet-end formulations with real-time process control from standard pulp preparation chemistries sold on specification alone.
- Pulp Preparation:Deinking surfactants, bleaching agents, and stock preparation additives condition recycled fiber before sheet formation. Mills in China are consolidating procurement toward integrated suppliers with captive technical service.
- Paper Coating:Binder-pigment combinations and rheology modifiers create smooth, printable surfaces on board and paper. High-speed coater operations in Germany's corrugated sector demand consistent viscosity control and minimal coating defects.
- Paper Sizing:Internal and surface sizing chemistries control liquid penetration and edge wicking. This segment holds the mature revenue position.
- Wet End Additives:Retention, drainage, and formation chemistries optimize machine runnability and sheet uniformity. Real-time charge and consistency sensors from METI-supported Japanese automation vendors are creating attach opportunities for digital dosing platforms here, where the most rapid technology uptake is occurring.
Paper sizing maintains the largest installed base. Wet end additives are climbing the fastest as automation integration creates switching costs.
End User:
Volume concentration favors packaging manufacturers, whose procurement now exceeds printing houses as the dominant value chain archetype.
- Packaging Manufacturers:Containerboard and corrugated board producers specify sizing agents, dry strength additives, and coating binders for liquid barrier and print performance. Germany's top five corrugated producers now control over sixty percent of chemical purchasing volume in that market.
- Printing Houses:Commercial printers and publication gravure operations consume coating additives and surface treatments for image fidelity. This category has ceded procurement dominance to packaging converters.
- Stationery Producers:Writing paper and office paper manufacturers specify optical brighteners and surface sizing for handwriting and inkjet compatibility.
- Specialty Paper Mills:Filter paper, thermal paper, and release liner producers demand precision-controlled functional additives with tight specification windows. Solenis embeds field technicians directly inside these mills to optimize wet-end chemistry, reflecting the highest service intensity tier.
Packaging manufacturers anchor the demand base. Specialty paper mills are expanding fastest as technical service integration creates premium pricing power.
Packaging Type:
Supply concentration in intermediate bulk containers reflects chemical supplier consolidation, while drums and carboys serve fragmented specialty additive producers.
- Drums:Standard 200-liter steel and polyethylene drums handle liquid biocides and emulsion products for regional distribution.
- Bulk Bags:Flexible intermediate bulk containers carry powdered dry strength additives and fillers to high-volume board mills.
- Intermediate Bulk Containers:Reusable totes and rigid IBCs dominate coating binder and sizing agent logistics for integrated packaging conglomerates with long-term supply agreements.
- Carboys:Smaller-volume polyethylene containers serve laboratory-scale trials and specialty paper mill qualification batches.
Intermediate bulk containers command the logistics base. Bulk bags are gaining share fastest as China's state-led mill consolidation drives toward bulk chemical contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging manufacturers concentrate procurement power in Germany, China, and the United States, where integrated conglomerates now dictate specification standards for wet-end chemistries across containerboard and food-grade applications.
United States
Corrugated board producers in the Southeast and Midwest drive sizing agent consumption for e-commerce packaging. EPA effluent limitation guidelines tighten discharge standards for pulp mills, forcing reformulation of biocide chemistries. Wisconsin and Georgia host the densest clusters of specialty paper mills qualifying peracetic acid alternatives ahead of compliance deadlines.
Germany
Food-grade paperboard expansion in Bavaria and North Rhine-Westphalia accelerates procurement for liquid barrier coatings. REACH registration requirements under ECHA constrain imported biocide actives, fragmenting competitive access. The Ruhr industrial corridor anchors coating binder demand from kraft liner producers operating high-speed machines.
China
State-led capacity consolidation concentrates procurement toward integrated chemical suppliers with captive technical service. MEE enforcement of stricter GB standards for effluent chemistry opens contracts for registered local biocide formulators. Shandong and Guangdong provinces lead bulk chemical contracting as mill integration accelerates.
Japan
METI-supported automation vendors supply real-time charge and consistency sensors, creating attach opportunities for chemical suppliers with digital dosing platforms. The Kanto region around Tokyo hosts precision-controlled specialty paper production demanding embedded technical service. Wet-end automation integration climbs fastest here as paper mills modernize distributed control systems.
India
Underdeveloped adoption of bio-based sizing agents in packaging offers first-mover positioning ahead of BIS sustainability mandates. Maharashtra and Gujarat containerboard mills seek AKD alternatives derived from plant-based feedstocks. Cost-sensitive kraft grades see native starch displacement of synthetic dry strength additives.
Global Paper Chemical Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with polymer backbone capabilities and specialty service integrators. Consolidation concentrates margin pools among scale players with captive R&D and field-embedded technical teams. Three archetypes dominate: integrated polymer suppliers leveraging raw material integration, specialty service providers optimizing mill-specific wet-end chemistry, and regional formulators capturing share through local registration advantages. Competitive moves center on bio-based formulation pipelines and digital dosing platform development.
Among European-headquartered conglomerates, BASF SE and Akzo Nobel N.V. occupy positions anchored by synthetic polymer expertise, while Kemira Oyj exemplifies the technical service archetype through captive R&D investment. Solenis represents the embedded-service model, with field technicians deployed directly inside specialty paper mills. These three entities illustrate how competitive positioning separates commodity formulation from value-captured process optimization.
| Leading Market Players |
|---|
| BASF SE |
| Kemira Oyj |
| Solenis |
| Akzo Nobel N.V. |
| Ecolab |
| Ashland |
| Archroma |
| Buckman |
| Harima Chemicals Group |
| Others |
Supply & Pricing Matrix
Long-term supply agreements with fixed pricing clauses lock in both supply access and price visibility for integrated packaging conglomerates, compressing spot market liquidity while extending contract durations across Germany's corrugated sector where top five producers now control over sixty percent of chemical purchasing volume.
Pricing Analysis
Cost-plus contracts indexed to ethylene and propylene benchmarks dominate synthetic polymer binder procurement, with price differentiation resting on volume scale and REACH registration status. Margins are tightening due to petrochemical feedstock volatility, while cost-sensitive kraft paper grades in India show highest price sensitivity as native starches displace synthetic dry strength additives.
Supply Chain Analysis
Strait of Malacca transit underwrites bulk chemical flows into Asian packaging hubs, with supply concentration in China, Germany, and the United States for wet-end additive manufacturing. Formulation draws from ethylene, propylene, and agricultural starch feedstocks, facing tariff exposure on imported biocide actives into the European Union. Distribution runs through intermediate bulk containers for integrated conglomerates and bulk bags for China's consolidating mill sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper chemical demand sits in early-cycle expansion as enzymatic fiber modification technology penetrates recycled containerboard mills, decomposing historical links between refining intensity and fiber bonding development while opening attach opportunities for digital dosing platforms.
For Market Incumbents: Consolidate technical service capabilities around wet-end automation integration to defend against specialty service integrators embedding field technicians directly inside mills. Deepen backward integration into bio-based sizing agent feedstocks ahead of BIS sustainability mandates in India. Scale captive R&D in peracetic acid alternatives to capture reformulation demand from REACH authorization deadlines.
For New Entrants and Emerging Players: Anchor in India's underdeveloped bio-based AKD alternative segment where plant-derived sizing agents await first-mover positioning. Target Maharashtra and Gujarat containerboard mills with cost-competitive glyoxalated polyacrylamide formulations. Pursue METI-supported automation vendor partnerships to attach digital dosing platforms to real-time sensor deployments.
For Investors and Strategic Acquirers: Regional formulators with local biocide registrations in China offer the most compelling acquisition profile, given MEE enforcement of stricter GB standards creating preferential contract access. Long-term viability hinges on backward integration into polymer backbones and embedded service capabilities. Watch enzymatic fiber modification adoption rates as the inflection signal for dry strength additive demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captive supply of plant-derived AKD alternatives hedges petrochemical volatility ahead of BIS mandates. |
| Digital Dosing Platform Development | Integration with METI-supported Japanese automation vendors creates switching costs in wet-end chemistry. |
| Local Biocide Registration in China | MEE GB standard alignment opens bulk contracts from state-consolidated Shandong and Guangdong mills. |
| Enzymatic Fiber Modification Partnerships | Cellulase and xylanase alliances reduce specific energy consumption for European packaging producers. |
| Long-term Supply Agreement Expansion | Fixed-price clauses with Germany's top five corrugated producers compress spot market liquidity. |
Research Methodology
A spread of perspectives from paper mill procurement directors, wet-end chemists, chemical supplier technical service teams, and packaging manufacturer operations managers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs and trade data, SEC filings, ACC and Cefic industry reports, and pulp and paper capacity databases. Bottom-up volume builds across product types and applications triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include functional additive category, machine position application, fiber type served, and end-user procurement archetype across the projection horizon. CAGRs were derived from regression analysis of historical consumption intensity ratios against paper and board production forecasts, incorporating recycled fiber substitution rates and regulatory reformulation timelines as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained packaging demand growth and incremental REACH biocide authorization deadlines; material deviation in petrochemical feedstock pricing or Chinese mill consolidation pace would warrant model refresh. Practitioners should keep alternative scenarios live as enzymatic fiber modification adoption and wet-end automation integration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
GCC Paper Products Market
Paper Products
Ceramic Paper Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Chemical Pulp Market
Paper Products
Photographic Paper Market
Paper Products
Hardwood Pulp Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Europe Coated Paper Market
Paper Products
Paper Machinery Market
Paper Products
Acrylic Paper Market
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
North America Specialty Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Paper Pigment Market
Paper Products
Leatheroid Paper Market
Paper Products
Dissolving Pulp Market