
 Thin Printing Paper Market | 2026-2036
Thin Printing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Printing Paper Market Analytics
Buyer concentration among publishing houses is rebalancing as regional magazine groups merge print procurement while direct-to-consumer brands fragment into short-run digital orders. Mondi Group leverages its integrated pulp-to-paper network across Central European mills to serve consolidated buyers with volume stability. International Paper anchors North American lightweight coated production through its Tennessee and Louisiana facilities. Stora Enso differentiates via certified renewable fiber sourcing that meets tightening corporate sustainability mandates from multinational publishers.
Thin printing paper denotes calendered woodfree or mechanical sheets typically manufactured below 60 grams per square meter, engineered for high ink holdout and minimal bulk in rotary offset or heatset web presses. Uncoated grades dominate transactional and educational volumes where opacity and writability outweigh gloss, while coated paper captures advertising inserts and luxury packaging applications where image reproduction fidelity commands price premiums. Specialty paper represents the fastest-expanding segment as security-printing and pharmaceutical leaflet specifications tighten substrate tolerances. Lightweight classifications under 45 gsm are displacing mediumweight stocks in direct mail as postal rate structures reward gram-per-page reductions.
EPA effluent guidelines constrain bleached kraft mill discharge in the United States, raising capital requirements for chlorine-free process conversions. REACH chemical registration and the EU Timber Regulation jointly enforce fiber chain-of-custody documentation that gates market access for non-compliant imports. ISO 9706 permanence standards for archival paper influence library and legal-sector procurement specifications across OECD markets. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America that will transfer end-of-life collection costs upstream to manufacturers.
Market Dynamics
Postal rate structures in major economies are compressing basis weight specifications, forcing mills to reformulate calendered sheets below 45 gsm while maintaining opacity and runnability on high-speed web presses.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandatory fiber provenance verification is redirecting procurement toward certified supply chains, creating premium positioning for compliant mills.
- Direct mail volume consolidation:Catalog publishers in the United States are consolidating print procurement into fewer, larger contracts that reward suppliers with volume stability.
- Heatset web press technology:Improved drying efficiency on modern rotary presses is expanding the addressable substrate range for ultra-lightweight coated stocks.
Market Restraints
- Bleached kraft pulp cost volatility:Hardwood fiber prices fluctuate with Latin American supply disruptions, squeezing margin predictability for uncoated grade producers.
- Mill concentration in Nordic regions:A limited number of integrated pulp-to-paper facilities control specialty lightweight capacity, creating supply vulnerability during maintenance cycles.
- Digital substitution in transactional printing:Electronic billing and statement delivery is eroding volume in traditional uncoated woodfree segments.
Strategic Opportunities
- Pharmaceutical insert specifications:Tighter tolerance requirements for patient information leaflets in Germany are creating demand for ultra-thin coated grades with certified dimensional stability.
- Extended producer responsibility frameworks:France and Germany are advancing collection-cost transfer mechanisms that favor domestic mills with established recycling partnerships.
- Security printing convergence:Integration of micro-optic features with thin substrates is opening specialized applications in government document and banknote adjacent segments.
Industry Challenges
- ISO 9706 archival certification timelines:Permanence testing protocols require extended accelerated aging studies that delay new product qualification by 12-18 months.
- Chlorine-free process conversion capex:EPA effluent guideline compliance demands precipitate reactor and bleach plant investments that strain mid-capitalization mill balance sheets.
- Chain-of-custody documentation complexity:REACH chemical registration combined with EU Timber Regulation requirements necessitate dedicated compliance personnel that smaller mills struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Printing Paper Market |
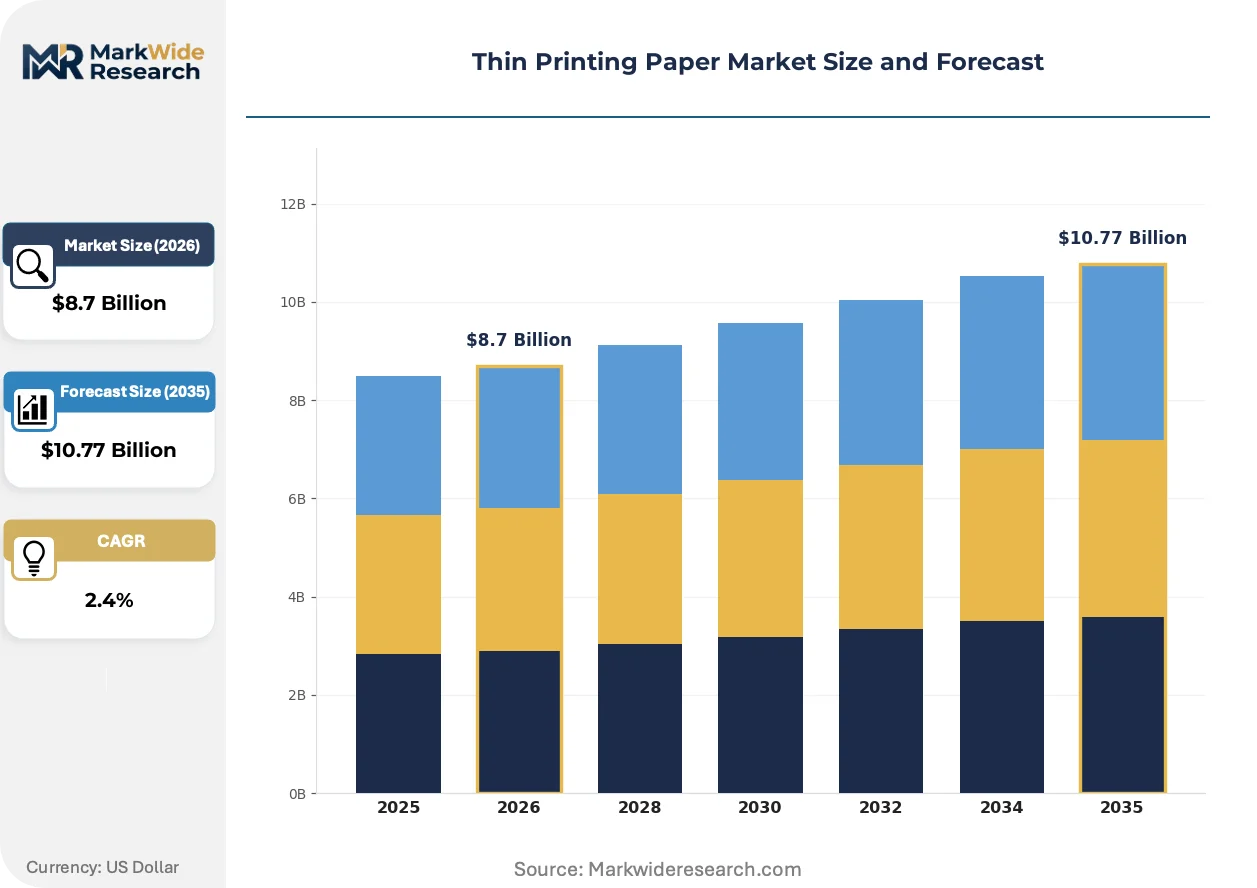
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Recycled Paper, Specialty Paper End User: Publishing, Advertising, Packaging, Stationery Weight Category: Lightweight, Mediumweight, Heavyweight, Ultra-Lightweight Application: Brochures, Flyers, Business Cards, Booklets |
| Companies Covered | Mondi Group, International Paper, Stora Enso, Sappi Limited, Nippon Paper Industries, Oji Holdings Corporation, Smurfit Kappa, WestRock Company, Domtar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Printing Paper Market Evolving Landscape
Automation of quality control and fiber tracking systems is compressing specification variance while regulatory documentation requirements intensify across OECD markets.
Machine vision inspection systems are automating real-time basis weight and caliper monitoring on paper machines, enabling tighter tolerance control. Magazine publishers with consolidated North American procurement are adopting these specifications for volume contracts. The technology is automating manual laboratory testing workflows and reducing off-specification reel waste.
EPA effluent guidelines are tightening discharge limits for adsorbable organic halogens from bleached kraft mills, forcing capital deployment toward oxygen delignification and ozone bleaching sequences. Tennessee and Louisiana facilities face accelerated compliance timelines relative to Canadian counterparts. Lightweight coated producers are responding by qualifying alternative fiber blends that reduce chlorine dioxide demand.
Catalog buyers are consolidating print procurement into centralized category management functions that bypass traditional merchant intermediaries. Regional publishing groups in the United States are negotiating direct mill contracts with volume commitments and sustainability scorecards. This concentration is most visible in the Midwest and Southeast, where postal logistics optimization drives gram-per-page reduction mandates.
Thin Printing Paper Market Segmentation
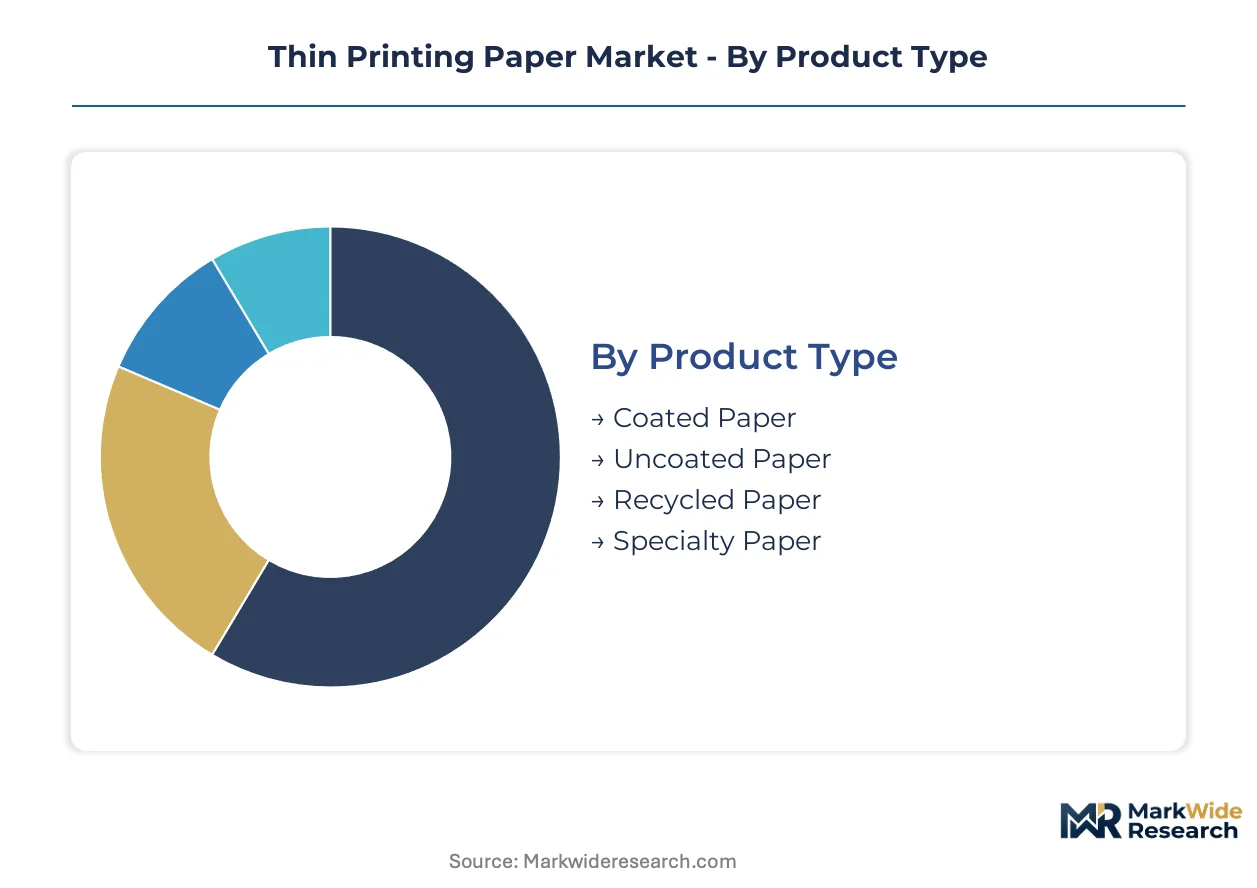
Segmentation in thin printing paper reveals how postal economics, sustainability mandates, and press technology reshape procurement priorities. Buyers sort grades by basis weight tolerances, coating requirements, and fiber certification status rather than commodity specifications alone.
Product Type:
Buyers prioritize coating performance and postal gram-per-page economics when selecting substrate categories.
- Coated Paper:Calendered sheets with mineral surface treatments deliver high ink holdout and gloss uniformity for heatset web presses. Magazine publishers in the United States consolidate procurement around lightweight coated stocks below 45 gsm to exploit postal rate discounts.
- Uncoated Paper:Woodfree or mechanical sheets without surface finishing emphasize opacity and writability over image reproduction. Transactional printers face volume erosion as electronic billing displaces statement mailings.
- Recycled Paper:Post-consumer fiber content meets corporate sustainability procurement scorecards.
- Specialty Paper:Substrates engineered for pharmaceutical inserts and security applications command premium positioning.
Coated paper leads on scale; specialty paper leads on momentum.
End User:
Volume concentration varies sharply by sector procurement centralization and digital substitution exposure.
- Publishing:Magazine and catalog houses consolidate print runs while shifting basis weight specifications downward. North American regional groups negotiate direct mill contracts that bypass traditional merchant channels.
- Advertising:Direct mail agencies fragment into short-run digital orders alongside retained high-volume catalog work. Postal logistics optimization drives gram-per-page reduction mandates across Midwest and Southeast operations.
- Packaging:Luxury brand applications demand coated stocks with dimensional stability for folding carton conversion.
- Stationery:Corporate and educational procurement emphasizes ISO 9706 permanence certification for archival requirements.
Publishing commands absolute volume; advertising shows steepest expansion trajectory in specialized lightweight grades.
Weight Category:
Postal rate structures compress specifications toward lower basis weights without sacrificing runnability.
- Ultra-Lightweight:Calendered sheets below 45 gsm displace mediumweight stocks in direct mail applications. Modern heatset web press drying efficiency expands the addressable substrate range for these grades.
- Lightweight:Specifications between 45-60 gsm balance postal cost reduction with opacity and stiffness requirements.
- Mediumweight:Traditional 60-80 gsm stocks face displacement pressure from ultra-lightweight alternatives.
- Heavyweight:Premium applications in packaging and specialty publishing retain demand for bulk and tactile properties.
Lightweight maintains installed base dominance; ultra-lightweight gains share fastest as press technology advances.
Application:
Format specifications determine coating requirements, folding tolerance, and fiber blend optimization.
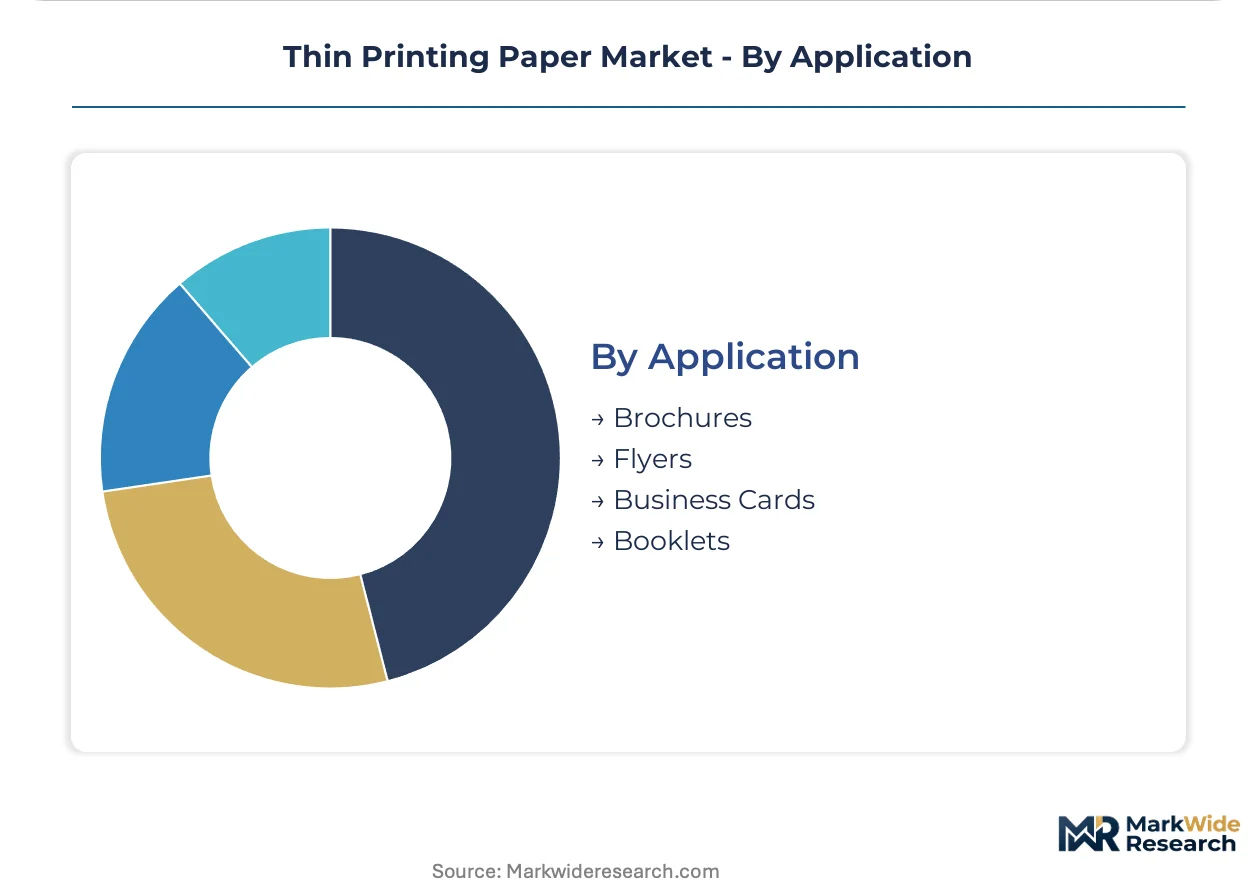
- Brochures:Multi-page formats require coated stocks with cross-grain dimensional stability for accurate folding.
- Flyers:Single-sheet advertising distribution concentrates in ultra-lightweight uncoated grades for cost-sensitive campaigns.
- Business Cards:Premium coated stocks with high stiffness and surface uniformity support offset and digital printing.
- Booklets:Saddle-stitched and perfect-bound formats demand specific grain direction and bulk characteristics for lay-flat performance.
Booklets lead on volume concentration; brochures lead on specification complexity and margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning for pharmaceutical insert specifications while the United States drives volume consolidation in magazine and catalog publishing. Postal rate structures and fiber certification mandates are diverging regulatory pathways across major producing regions.
United States
Catalog publishers consolidate print procurement into centralized category management functions that bypass traditional merchant intermediaries. EPA effluent guidelines tighten discharge limits for adsorbable organic halogens from bleached kraft mills in Tennessee and Louisiana. Midwest and Southeast operations drive gram-per-page reduction mandates as postal logistics optimization reshapes lightweight coated demand.
Germany
Specialized coated grades for pharmaceutical inserts command premium positioning as patient information leaflet specifications tighten substrate tolerances. EU Ecodesign for Sustainable Products Regulation mandates fiber provenance verification that redirects procurement toward certified supply chains. Mills in North Rhine-Westphalia and Bavaria leverage integrated pulp-to-paper networks to serve consolidated buyers with volume stability.
Japan
Heatset web press technology advances expand the addressable substrate range for ultra-lightweight coated stocks below 45 gsm. METI standards and JIS certification requirements influence procurement specifications for archival and security-printing applications. Industrial clusters in the Kanto and Kansai regions concentrate specialty lightweight capacity for export markets.
China
Domestic magazine publishers adopt lighter basis weights to reduce distribution costs amid expanding heatset web press installations. MEE environmental standards and dual carbon goals pressure mills toward oxygen delignification and alternative fiber blends. Yangtze River Delta and Pearl River Delta facilities balance export demand with growing domestic consumption of coated woodfree grades.
Sweden
Certified renewable fiber sourcing meets tightening corporate sustainability mandates from multinational publishers across Nordic markets. REACH chemical registration combined with EU Timber Regulation enforces fiber chain-of-custody documentation. Stora Enso's integrated operations exemplify compliance architecture that gates market access for non-compliant imports.
Thin Printing Paper Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Integrated pulp-to-paper networks anchor volume stability for consolidated buyers while merchant-dependent converters fragment into short-run digital orders. Strategic archetypes span captive fiber producers, merchant converters, and specialty substrate engineers. Competitive moves concentrate on direct mill contracting bypassing traditional distribution and sustainability certification investments that qualify for premium procurement scorecards.
Within the integrated producer tier, Mondi Group leverages its Central European mill network to anchor supply security for consolidated publishing houses. International Paper occupies a position representing North American lightweight coated production scale through Tennessee and Louisiana facilities. Stora Enso exemplifies the certified renewable fiber archetype that meets tightening multinational publisher mandates. These three entities represent divergent strategic postures: geographic network density, continental production anchoring, and sustainability certification leadership.
| Leading Market Players |
|---|
| Mondi Group |
| International Paper |
| Stora Enso |
| Sappi Limited |
| Nippon Paper Industries |
| Oji Holdings Corporation |
| Smurfit Kappa |
| WestRock Company |
| Domtar Corporation |
| Others |
Value Network & Pricing Analysis
Hardwood pulp price indices from Latin American suppliers cascade through thin printing paper supply chains, compressing margins for uncoated grade producers while coated specialty mills pass fiber cost volatility through long-term contracts with consolidated publishing houses.
Pricing Analysis
Capacity additions in Nordic regions are reshaping price floors for ultra-lightweight coated stocks as Stora Enso and Mondi Group expand qualified substrate ranges. Three-tier pricing structure across pharmaceutical-grade certified, standard commercial, and economy transactional levels stratifies buyer segments. Cost compression in uncoated woodfree grades is intensifying because electronic billing displacement erodes volume leverage. Direct mail agencies show highest price sensitivity; pharmaceutical insert buyers accept premiums for dimensional stability certification.
Supply Chain Analysis
Dual-sourcing requirements from consolidated North American publishing houses mandate multi-supplier qualification across Nordic, German, and Japanese mill networks. Geographic supply concentration centers on Sweden, Finland, and Germany for integrated pulp-to-paper capacity. Raw material dependencies draw from Latin American hardwood pulp, Nordic softwood fiber, and mineral coating additives. Single-source vulnerability during Nordic maintenance cycles threatens supply continuity. Distribution runs through direct mill contracts bypassing traditional merchant intermediaries in Midwest and Southeast publishing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin printing paper functions as a late-cycle quality story where pharmaceutical insert specifications and security-printing substrates command sustainable premiums against commoditized transactional grades.
For Market Incumbents: Anticipate chlorine-free process conversion capex demands from EPA effluent guidelines by pre-qualifying alternative fiber blends at Tennessee and Louisiana facilities. Consolidate procurement relationships with Midwest publishing groups before regional category management functions mature. Anchor volume stability through integrated pulp-to-paper networks that merchant-dependent converters cannot replicate.
For New Entrants and Emerging Players: Capture white-space in pharmaceutical insert substrates where German tolerance specifications create barrier-to-entry premiums. Target security-printing convergence applications integrating micro-optic features with thin substrates. Pursue direct-to-consumer brand short-run digital orders that fragment away from consolidated catalog procurement.
For Investors and Strategic Acquirers: Asymmetric upside sits with certified renewable fiber specialists meeting EU Ecodesign verification mandates. Five-to-ten year viability favors mills with established recycling partnerships under extended producer responsibility frameworks. Monitor REACH chemical registration compliance timelines as inflection indicator for smaller mill distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Chlorine-Free Process Conversion | EPA effluent guideline compliance in Tennessee and Louisiana facilities gates North American market access. |
| Pharmaceutical Grade Certification | German patient information leaflet specifications create premium positioning for dimensional stability-qualified substrates. |
| Direct Mill Contracting | Bypassing merchant intermediaries captures margin from consolidated Midwest and Southeast publishing procurement. |
| Security Feature Integration | Micro-optic substrate convergence opens government document and banknote-adjacent specialty applications. |
| Recycling Partnership Anchoring | France and Germany extended producer responsibility frameworks transfer collection-cost advantage to domestic mills. |
Research Methodology
Bottom-up publishing and pharmaceutical modeling reconciled against top-down pulp-to-paper capacity tracking forms the analytical core of this study. Primary interviews with magazine procurement directors, pharmaceutical packaging engineers, mill operations managers, and merchant distribution heads combined with secondary validation from customs trade data, EPA discharge filings, EU Timber Regulation documentation, and SEC mill financial disclosures. Triangulation between fiber supply chain documentation and end-use demand specifications ensures specification-grade segmentation accuracy.
Historical trendline analysis of basis weight reduction patterns and postal rate elasticity established projection parameters across the analysis window. Segmentation dimensions modeled include coating category, end-use sector, weight classification, and regional regulatory cluster. CAGRs derive from installed press technology diffusion curves and fiber cost pass-through coefficients. Heatset web press drying efficiency improvements and EU Ecodesign compliance timelines serve as industry-specific forecast inputs.
Latin American hardwood pulp supply disruptions, Nordic mill maintenance cycle clustering, and digital substitution acceleration in transactional printing are the dominant revision risks. Deviation in pharmaceutical insert specification tightening velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Acrylic Paper Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Clay Coated Paper Market
Paper Products
Compressed Fiberboard Market
Paper Products
Paper and Board Technologies Market
Paper Products
Printing and Writing Papers Market
Paper Products
Pulp and Paper Market
Paper Products
White Top Testliner Market
Paper Products
Thermal Paper Market
Paper Products
Greaseproof Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Recording Chart Paper Market
Paper Products
Pulp Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Sanitary Paper Products Market