
 Functional and Barrier Coatings for Paper Market | 2026-2036
Functional and Barrier Coatings for Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Functional and Barrier Coatings for Paper Market Analysis
Multi-source procurement of barrier chemistries is expanding as converters reduce dependency on single polymer suppliers. BASF SE leverages its aqueous polymer portfolio to serve folding carton makers across Europe. Michelman, Inc. specializes in water-based surface modifiers that improve grease resistance for food-contact applications. Dow Inc. competes through integrated polyethylene supply chains that anchor its coating resin business in North America.
Functional and barrier coatings for paper comprise formulated surface treatments applied via roll coating, extrusion, or spray deposition to impart moisture resistance, oxygen barrier, heat sealability, or grease resistance to cellulosic substrates. These coatings typically range from 5 to 30 grams per square meter in dry coat weight and serve to replace multi-material laminated structures with recyclable paper-based alternatives. Barrier coatings currently lead value generation due to their critical role in food packaging shelf-life extension, while aqueous formulations represent the fastest-expanding technology segment as converters phase out solvent-based systems under emissions regulations. Bioplastics within the material category command premium positioning where compostability certification determines market access for quick-service restaurant packaging.
The FDA regulates direct food-contact coatings through 21 CFR compliance pathways, while the EU Green Deal and REACH restrict perfluorinated chemistries in paperboard barriers. ECHA's evolving restrictions on persistent organic pollutants are forcing reformulation of oil-and-grease-resistant coatings toward plant-derived alternatives. Stakeholders must monitor regulatory divergence between US and European frameworks when scaling unified product platforms across Atlantic supply chains.
Market Dynamics
Single-use plastic bans across the EU and North America are forcing food packaging converters to abandon multi-material laminates in favor of recyclable paper structures with functional barrier coatings. This regulatory compression is accelerating capital deployment toward aqueous coating lines and integrated extrusion-coating systems.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are compelling fresh produce tray manufacturers to substitute polyethylene laminates with cellulose-starch barrier formulations.
- Quick-service restaurant packaging:Compostability certification requirements from municipal waste authorities are expanding demand for bioplastic-coated paperboard in burger boxes and fry cartons.
- Germany's integrated coating investments:Paperboard producers in Baden-Württemberg and Bavaria are installing inline barrier coating systems to serve centralized European fresh produce distribution networks.
Market Restraints
- Petrochemical resin volatility:Polyethylene and polypropylene price swings directly compress coating margins for extrusion-based barrier suppliers dependent on spot market feedstock.
- Fluorinated chemistry substitution timeline:ECHA restrictions on persistent organic pollutants are forcing oil-and-grease-resistant coating reformulations with 18-24 month validation cycles.
- Performance gap in high-moisture applications:Aqueous barrier coatings still exhibit 30-40% higher water vapor transmission rates versus legacy polyethylene extrusion coatings in frozen food applications.
Strategic Opportunities
- India's food delivery expansion:Quick-commerce platforms in Mumbai and Bangalore are creating first-mover advantage for grease-resistant molded fiber tray suppliers with localized coating operations.
- Heat-sealable aqueous coatings:Convergence of water-based polymer chemistry with ultrasonic sealing technology is enabling replacement of hot-melt adhesives in folding carton assembly.
- Extended Producer Responsibility frameworks:France's AGEC law and Italy's plastic tax are creating regulatory tailwinds for recyclable mono-material paper packaging with certified barrier performance.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in waterborne polymer rheology and substrate adhesion science remains concentrated among retiring technical staff at legacy coating houses.
- Migration testing timelines:FDA 21 CFR and EU 10/2011 compliance for direct food-contact coatings requires 12-18 month analytical validation, delaying product launches.
- Legacy equipment retrofit costs:Converting solvent-based coating lines to aqueous systems demands capital expenditure for infrared drying zones and humidity-controlled web handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional and Barrier Coatings for Paper Market |
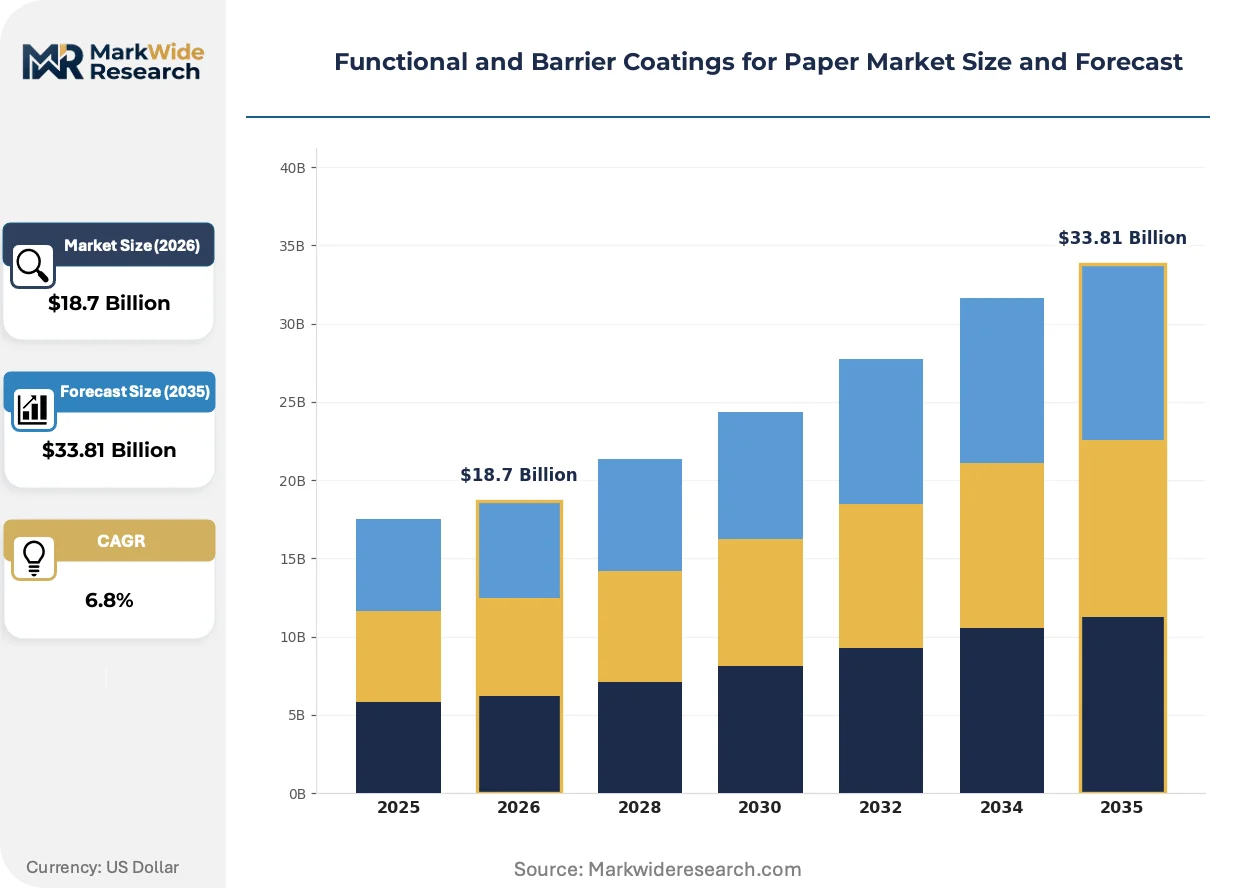
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Functional Coatings, Barrier Coatings, Aqueous Coatings, Solvent-Based Coatings Application: Food Packaging, Beverage Containers, Foldable Cartons, Hygiene Products Material: Polyethylene, Bioplastics, Cellulose, Starch End User: Converters, Brand Owners, Retailers, Consumers |
| Companies Covered | International Paper, Michelman, Inc., BASF SE, Akzo Nobel N.V., Dow Inc., Stora Enso Oyj, Sonoco Products Company, UPM-Kymmene Corporation, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional and Barrier Coatings for Paper Market Emerging Trajectories
Coating technology is fragmenting into application-specific modular platforms rather than universal barrier solutions. This specialization is compressing development cycles while expanding the addressable substrate range.
Multilayer aqueous coating systems is modularizing barrier functionality into discrete deposition stages—primer, active barrier, and heat-seal layers—each optimized separately. Folding carton converters in the Netherlands and Belgium are adopting these stackable formulations to replace solvent-based lacquers within existing roll-coating infrastructure. The technology is modularizing what were previously integrated extrusion-lamination supply chains into separable coating and converting operations.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluorinated chemistries from oil-and-grease-resistant paperboard by 2025. Industrial consequence includes forced migration toward plant-derived waxes and nanocellulose composites with inferior performance at equivalent coat weights. Quick-service restaurant packaging in Germany and France faces the steepest compliance curve, with chains accelerating supplier audits to secure reformulated grease barriers ahead of enforcement deadlines.
Specification consolidation among multinational food brands is compressing approved supplier lists from twelve to three coating vendors per substrate category. This buyer concentration is displacing regional coating houses in favor of integrated polymer suppliers with in-house analytical laboratories and pan-European technical service networks. The shift is most visible in fresh produce packaging, where retailers in Spain and Italy now mandate unified barrier specifications across their private-label suppliers.
Functional and Barrier Coatings for Paper Market Segmentation
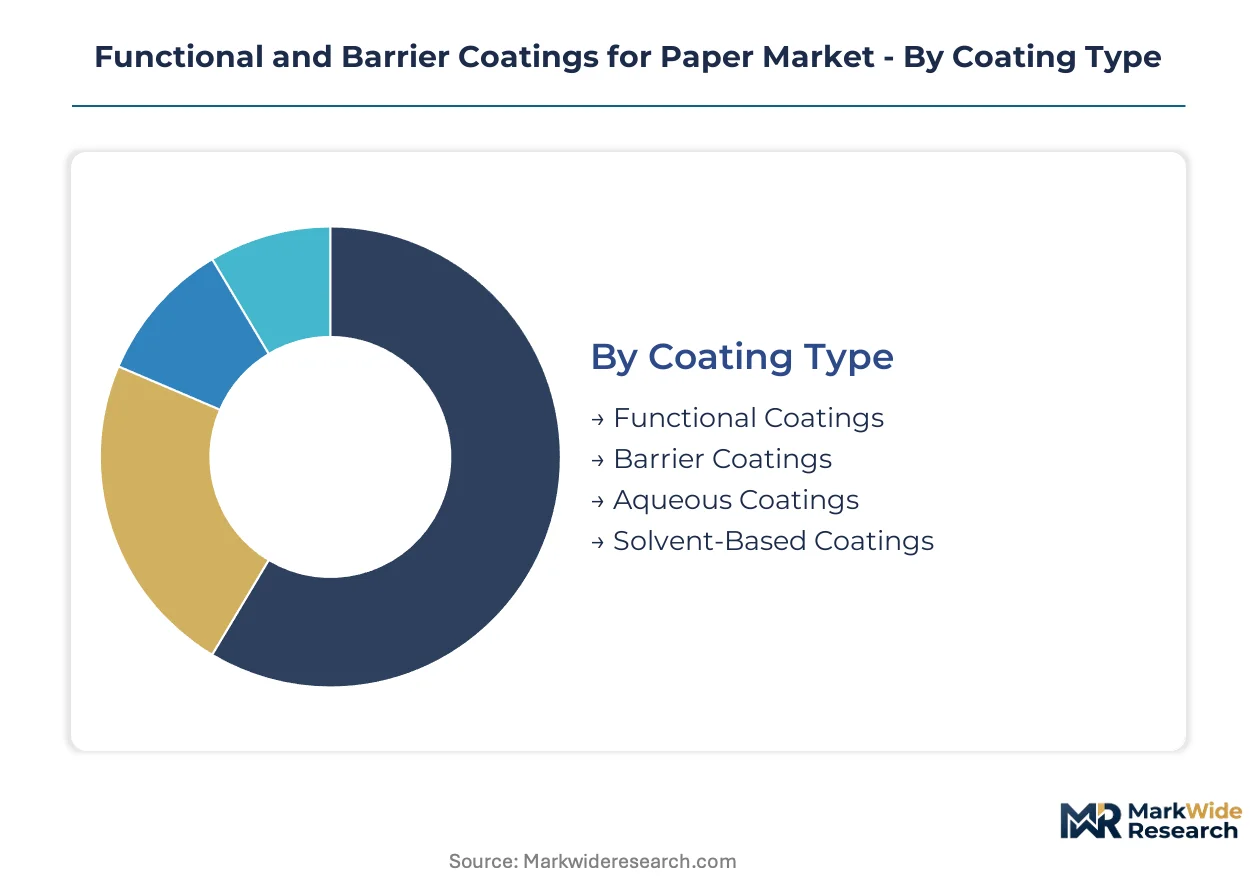
Segmentation in this market tracks how coating chemistry, substrate compatibility, and regulatory compliance intersect to determine procurement decisions. Buyers prioritize moisture barrier performance, recyclability certification, and line-speed compatibility when selecting formulations.
Coating Type:
Converters differentiate procurement by drying energy requirements, emissions compliance burden, and substrate adhesion chemistry.
- Barrier Coatings:These formulations incorporate polyethylene, wax, or biopolymer layers to block moisture and oxygen transmission. Fresh produce tray manufacturers in Germany specify these coatings to meet EU recyclability mandates while maintaining shelf-life performance.
- Aqueous Coatings:Water-based polymer dispersions cure through infrared or convection drying without solvent emissions. Folding carton converters across the Netherlands and Belgium are phasing these in to replace solvent-based lacquers under REACH air quality regulations.
- Functional Coatings:Surface modifiers impart heat sealability, print receptivity, or anti-static properties to paper substrates.
- Solvent-Based Coatings:Organic solvent carriers deliver high-performance barriers but face regulatory phase-out in food-contact applications.
Barrier Coatings lead volumes today; Aqueous Coatings is gaining share fastest.
Application:
End-use selection hinges on moisture exposure severity, temperature cycling requirements, and direct food-contact regulatory pathways.
- Food Packaging:Grease-resistant and oxygen-barrier coatings protect dry goods, frozen foods, and fresh produce in paperboard structures. Quick-service restaurant chains in France and Germany demand compostable-certified barriers for burger boxes and fry cartons.
- Beverage Containers:Liquid-tight coatings prevent leakage in paper cups and cartons while maintaining fiber recyclability. Cup manufacturers face EFSA migration limits for direct liquid contact.
- Foldable Cartons:Heat-sealable aqueous coatings enable carton assembly without hot-melt adhesives.
- Hygiene Products:Moisture barriers protect absorbent cores in diaper and feminine hygiene packaging.
Food Packaging dominates current procurement; Beverage Containers shows the steepest expansion trajectory.
Material:
Material choice reflects tension between petrochemical cost volatility and compostability certification premiums.
- Polyethylene:Extrusion-coated or aqueous-dispersed polyethylene delivers benchmark moisture barrier at lowest unit cost. Frozen food applications still specify this despite recyclability challenges.
- Bioplastics:PLA and PHA formulations achieve industrial compostability certification for quick-service packaging. Municipal waste authorities in France and Italy mandate these for public procurement contracts.
- Cellulose:Nanocellulose and regenerated cellulose barriers provide oil resistance without fluorinated chemistries.
- Starch:Thermoplastic starch blends offer cost-competitive barriers where moisture sensitivity permits.
Polyethylene retains volume leadership; Bioplastics climbs fastest on regulatory tailwinds.
End User:
Stakeholder position in the value chain determines specification authority and technical service intensity requirements.
- Converters:Roll-coating and extrusion-lamination specialists select formulations based on line speed, drying capacity, and substrate inventory. Integrated coating investments in Baden-Württemberg concentrate demand among large-scale folding carton producers.
- Brand Owners:Multinational food and beverage companies consolidate approved supplier lists and mandate unified barrier specifications across private-label portfolios.
- Retailers:Supermarket chains in Spain and Italy specify certified recyclable packaging for fresh produce private labels.
- Consumers:End-user preference for compostable packaging influences municipal procurement and extended producer responsibility frameworks.
Converters command current procurement volumes; Brand Owners are consolidating specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with streamlined compostability certification pathways, as coating manufacturers arbitrage the eighteen-month approval gap between EU member states and North American jurisdictions.
Germany
Fresh produce tray demand concentrates in Baden-Württemberg and Bavaria, where paperboard manufacturers deploy integrated coating lines for centralized European distribution. The EU Packaging and Packaging Waste Regulation mandates recyclability targets that favor cellulose-starch barrier formulations. Stuttgart-based converters anchor supply chains serving French and Italian retail networks.
United States
Frozen food packaging retains polyethylene specifications despite recyclability pressures, sustaining demand for extrusion-coated barriers in the Upper Midwest. FDA 21 CFR compliance pathways govern direct food-contact approvals, with migration testing timelines extending twelve to eighteen months. Wisconsin and Michigan house legacy coating operations supplying quick-service restaurant chains.
France
AGEC law enforcement accelerates substitution of multi-material laminates in quick-service packaging for burger boxes and fry cartons. Municipal waste authorities mandate compostability certification for public procurement contracts. Lyon and Paris basin converters consolidate supplier lists to three coating vendors per substrate category.
Netherlands
Folding carton manufacturers in the Randstad region adopt multilayer aqueous coating systems to replace solvent-based lacquers under REACH air quality regulations. Modular primer-barrier-heat-seal formulations enable retrofit of existing roll-coating infrastructure. Eindhoven-area technical service networks support specification consolidation among multinational food brands.
India
Quick-commerce expansion in Mumbai and Bangalore generates first-mover opportunity for grease-resistant molded fiber tray suppliers. BIS standards for food-contact materials remain less stringent than EU frameworks, attracting pilot coating operations. Localized production avoids import duty exposure on finished barrier formulations.
Functional and Barrier Coatings for Paper Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bioplastic certification niches and regional quick-commerce partnerships. The vendor base stratifies around three archetypes: integrated paperboard-coating conglomerates, aqueous polymer specialists, and petrochemical resin suppliers with captive coating divisions. Consolidation pressures concentrate specification authority among multinational food brands, compressing approved supplier lists. Dominant competitive moves include backward integration into polymer production and technology licensing for aqueous formulation platforms.
Within the integrated conglomerate tier, International Paper and Stora Enso Oyj represent paperboard manufacturers with captive coating capabilities that control substrate-barrier integration. Among aqueous polymer specialists, Michelman, Inc. and BASF SE exemplify formulation houses competing on regulatory compliance breadth and technical service density. Dow Inc. anchors the petrochemical-supplier archetype with integrated polyethylene supply chains supporting extrusion-based barrier operations in North America.
| Leading Market Players |
|---|
| International Paper |
| Michelman, Inc. |
| BASF SE |
| Akzo Nobel N.V. |
| Dow Inc. |
| Stora Enso Oyj |
| Sonoco Products Company |
| UPM-Kymmene Corporation |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between compostable bioplastic barriers and commodity polyethylene coatings manifests in both margin structures and procurement channel configurations, with EU Green Deal compliance costs concentrating premium-tier supply among integrated polymer houses while spot-market resin dependence fragments economy-tier sourcing across trading distributors in Germany and the Netherlands.
Pricing Analysis
Distributor margins absorb regulatory compliance burdens as coating formulators pass ECHA certification costs downstream to folding carton converters. Pricing stratifies across premium, standard, and economy tiers based on compostability certification status and volume commitment scale. Cost compression in aqueous barrier formulations is intensifying because petrochemical resin volatility squeezes extrusion-based suppliers dependent on spot polyethylene markets. Quick-service restaurant chains exhibit highest price sensitivity due to municipal procurement mandates, while pharmaceutical packaging buyers tolerate premium positioning for FDA-validated direct food-contact grades.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fresh produce tray demand from Baden-Württemberg paperboard manufacturers, while specialty distributors serve mid-tier folding carton converters across the Benelux region. Supply concentrates in Germany, the United States, and India, with coating formulation expertise anchored in legacy European technical service networks. Raw material flows draw from polyethylene resin producers, nanocellulose pulp suppliers, and thermoplastic starch compounders. Single-source vulnerability persists for fluorinated chemistry alternatives facing ECHA substitution timelines. Distribution runs through integrated paperboard-coating conglomerates with captive polymer production and technical validation laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eighteen-month approval gaps between EU member states and Indian jurisdictions create arbitrage windows for coating manufacturers willing to front-run BIS standardization with pilot aqueous formulation facilities near Mumbai and Bangalore quick-commerce clusters.
For Market Incumbents: Lock in specification authority with multinational food brands by consolidating approved supplier lists ahead of REACH perfluorinated chemistry deadlines. Backward integration into nanocellulose pulp production secures margin control against commodity resin volatility. Capacity addition in Bavaria serves centralized European fresh produce distribution networks while technical service density displaces regional coating houses in Spain and Italy.
For New Entrants and Emerging Players: Capture first-mover positioning in India's quick-commerce molded fiber tray segment where localized coating operations avoid import duty exposure on finished barrier formulations. White-space concentration appears in grease-resistant aqueous systems for Bangalore and Mumbai delivery platforms. Partner with municipal waste authorities to secure compostability certification ahead of national standardization.
For Investors and Strategic Acquirers: Consolidation pressure builds where specification authority concentrates among multinational food brands compressing approved supplier lists from twelve to three vendors per substrate category. Five-to-ten-year viability favors aqueous polymer specialists with in-house analytical laboratories and pan-European technical service networks. Watch ECHA enforcement timelines for perfluorinated chemistry restrictions as inflection signals for plant-derived barrier formulation valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanocellulose Production | Captures margin from ECHA-driven fluorinated chemistry substitution in German quick-service packaging. |
| Localized Coating Facility in India | Exploits BIS regulatory lag to establish aqueous barrier production for Mumbai quick-commerce platforms. |
| Compostability Certification Investment | Secures municipal procurement contracts under France's AGEC law for burger box and fry carton supply. |
| Multilayer Aqueous Formulation Platform | Enables Dutch folding carton converters to retrofit solvent-based lacquer lines under REACH air quality rules. |
| Technical Service Network Expansion | Supports specification consolidation among Spanish and Italian retailers mandating unified barrier standards. |
Methodological Framework
Multiple input streams — primary interviews with coating formulation chemists, folding carton procurement directors, and ECHA regulatory affairs specialists; secondary validation through EU Packaging and Packaging Waste Regulation filings, SEC 10-K disclosures from integrated paperboard manufacturers, and customs trade data for polyethylene resin flows — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from technical directors at aqueous polymer specialists to model expansion across coating type, application severity, material chemistry, and end-user specification authority segments. CAGRs were derived from regression analysis of capital deployment patterns in integrated coating lines. Forecast inputs included EU recyclability mandate compliance timelines and quick-commerce platform expansion rates in Indian metropolitan clusters.
Underlying measurement precision varies by segment; aqueous coating technology trajectories carry tighter precision than bioplastic certification pathways given regulatory uncertainty. Forecasts reflect assumptions about ECHA enforcement consistency and municipal compostability mandate adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Organic Tissue Paper Market
Paper Products
Europe Paper Market
Paper Products
Recording Chart Paper Market
Paper Products
Writing Paper Market
Paper Products
Metallized Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Base Paper Market
Paper Products
Photographic Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Dissolving Pulp Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Specialty Paper Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Global Electrical Insulation Paper Market