
 Chemical Cellulose Market | 2026-2036
Chemical Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Cellulose Market Analysis
Synthetic polymer substitution in tablet binders is hardening as pharmaceutical manufacturers pivot toward plant-derived excipients for improved compressibility and regulatory acceptance. Ashland leverages its integrated supply chain to dominate high-purity cellulose ether production for ophthalmic and topical formulations. Daicel Corporation anchors Asian supply through specialized manufacturing of pharmaceutical-grade microcrystalline cellulose. Borregaard competes in sustainable cellulose fibril derivatives, extending its forestry-to-chemicals integration across European and North American markets.
Chemical cellulose comprises purified polysaccharide chains derived from wood pulp or cotton linters, typically exhibiting degrees of polymerization from 100 to 3,000 depending on intended function, and serves primarily as a rheology modifier, binder, or film-forming agent across industrial and consumer formulations. The product type landscape shows microcrystalline cellulose commanding the largest revenue pool due to its dominance in direct-compression tablet manufacturing, while cellulose ether variants generate premium margins in construction and personal care applications where viscosity stability and water retention prove critical. Hydroxypropyl methylcellulose segments are gaining fastest in edible film coatings and controlled-release drug matrices as manufacturers seek alternatives to gelatin and synthetic polymers.
EPA standards govern volatile organic compound thresholds in cellulose-based paint and coating additives, while REACH registration requirements in Europe restrict certain cellulose ether chemistries in consumer-facing products. FDA excipient guidelines and USP-NF monographs further delineate purity grades acceptable for pharmaceutical and food applications, creating tiered market access barriers that favor producers with validated manufacturing protocols. Stakeholders must monitor regulatory divergence between jurisdictions as biobased certification schemes and green chemistry preferences reshape procurement criteria across end-use sectors.
Market Dynamics
Pharmaceutical manufacturers are consolidating excipient sourcing around plant-derived alternatives, compressing supplier margins while elevating purity validation requirements across cellulose ether and microcrystalline cellulose grades.
Growth Catalysts
- Direct-compression tablet demand:Pharmaceutical formulators are expanding microcrystalline cellulose use as a binder in high-speed tableting lines, displacing wet granulation processes and reducing manufacturing cycle times.
- REACH purity mandates:ECHA registration requirements for cellulose ethers used in food contact applications are filtering out low-grade suppliers and consolidating volume with validated European producers.
- China's pharmaceutical-grade scaling:Domestic Chinese manufacturers are expanding output to serve export markets, creating new supply alternatives for formulators seeking dual-source security.
Market Restraints
- Dissolving pulp price volatility:Raw material costs for wood-derived cellulose fluctuate with forestry harvest cycles and energy-intensive processing, compressing margins for non-integrated producers.
- Specialized equipment barriers:Pharmaceutical-grade microcrystalline cellulose requires spray-drying and micronization assets that carry high capital intensity, limiting new entrant capacity.
- Synthetic polymer substitution in coatings:Polyvinyl alcohol and acrylic alternatives compete in edible film applications where moisture resistance exceeds cellulose performance.
Strategic Opportunities
- Controlled-release drug matrices:Hydroxypropyl methylcellulose variants are penetrating oral solid dosage forms as manufacturers seek alternatives to gelatin capsules and synthetic polymer matrices.
- Biobased certification tailwinds:EU Green Deal procurement criteria and USDA BioPreferred labeling are creating preference premiums for certified-sustainable cellulose derivatives in consumer products.
- Ophthalmic formulation expansion:High-purity cellulose ethers are entering eye drop and gel formulations where viscosity stability and biocompatibility command technical specification premiums.
Industry Challenges
- Cross-jurisdictional compliance complexity:Manufacturers must maintain parallel validation protocols for FDA excipient guidelines, USP-NF monographs, and REACH dossiers, extending certification timelines.
- Specialized process engineering scarcity:Qualified technical personnel for pharmaceutical-grade cellulose production—particularly spray-drying optimization and particle size engineering—remain concentrated among incumbent producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Cellulose Market |
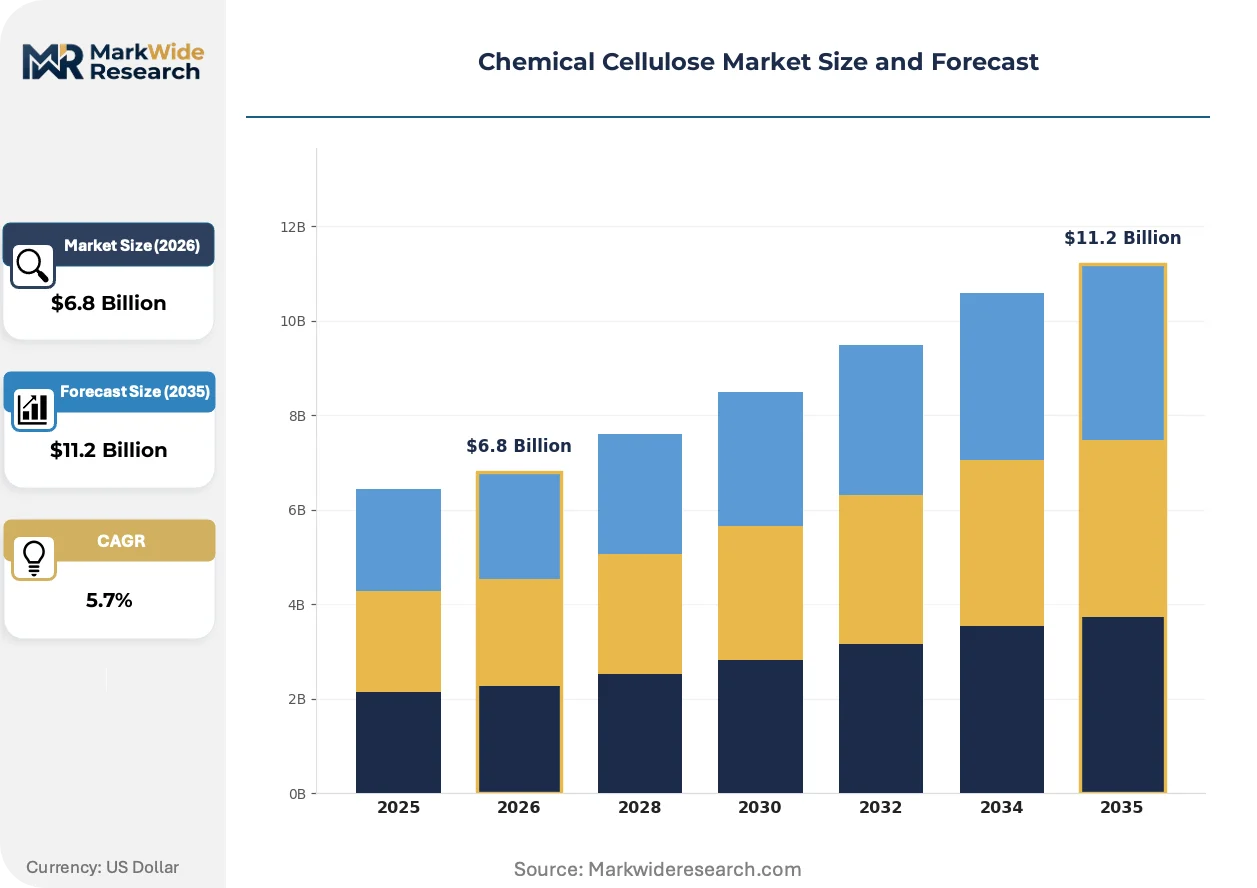
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcrystalline Cellulose, Carboxymethyl Cellulose, Hydroxypropyl Methylcellulose, Cellulose Ether End Use Industry: Food & Beverage, Pharmaceutical, Cosmetics, Paints & Coatings Application: Thickening Agent, Emulsifier, Stabilizer, Film Former Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | Ashland, Shin-Etsu Chemical, Dow, Daicel Corporation, Celanese Corporation, Eastman Chemical Company, CP Kelco, Borregaard, LOTTE Fine Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Cellulose Market Emerging Trajectories
Continuous processing technologies and regulatory harmonization efforts are compressing development cycles while fragmenting the supplier base between integrated specialists and commodity traders.
Microcrystalline cellulose production is modularizing through integrated reactor-to-dryer systems that eliminate intermediate handling stages. Contract manufacturers serving generic pharmaceutical houses are adopting these compact lines to reduce batch-to-batch variability. This technology is modularizing quality assurance workflows, allowing mid-scale producers to match the consistency metrics previously exclusive to large integrated facilities.
REACH registration deadlines for cellulose ether derivatives are tightening impurity disclosure thresholds for food-contact and drug-delivery applications. European formulators are now demanding full supply-chain substance dossiers from Asian suppliers. Cosmetic and personal care segments are absorbing the highest compliance costs, with several mid-tier distributors exiting the European market rather than funding registration updates.
Formulators are consolidating excipient suppliers to reduce audit burden and secure volume commitments. Large pharmaceutical manufacturers are moving from multi-source spot purchasing toward sole-source technical partnerships with validated cellulose producers. This concentration is most visible in North American generic drug manufacturing, where procurement teams prioritize suppliers offering integrated regulatory documentation packages over price competition.
Chemical Cellulose Market Segmentation
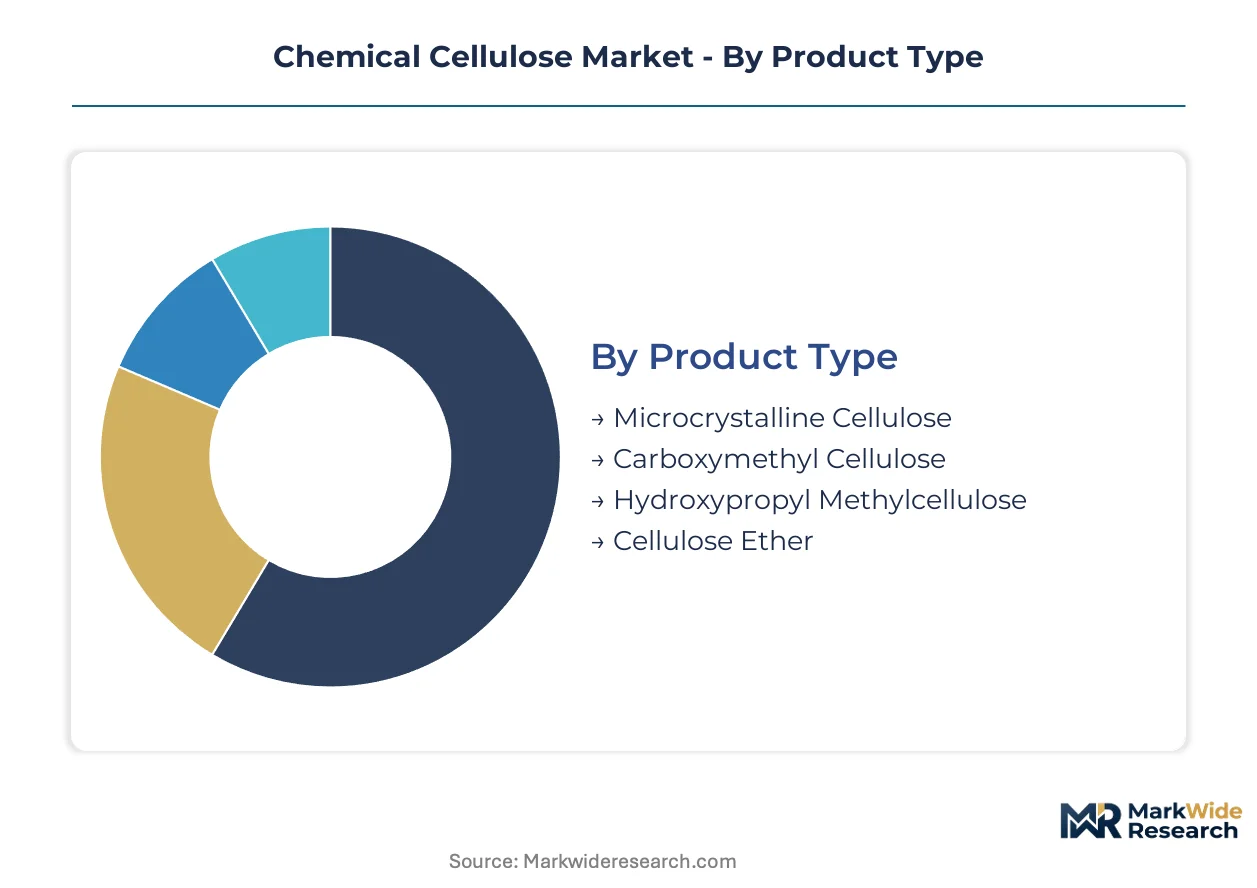
Chemical cellulose markets fragment across functional chemistry, regulatory-grade purity, and formulation integration depth. Understanding where segments sit in standalone commodity trade versus embedded pharmaceutical systems shapes procurement strategy and margin capture.
Product Type:
Integration depth varies sharply: microcrystalline cellulose functions as a standalone excipient requiring direct pharmaceutical validation, while cellulose ethers embed into multi-component formulations with less visible supplier branding.
- Microcrystalline Cellulose:Purified crystalline cellulose with degrees of polymerization below 350, produced through controlled acid hydrolysis of wood pulp. Demand concentrates in high-speed direct-compression tableting lines across US and European generic pharmaceutical manufacturing, where FDA excipient validation and USP-NF monograph compliance create tiered supplier access. REACH purity mandates are filtering European volume toward validated producers with full substance dossiers.
- Hydroxypropyl Methylcellulose:Semi-synthetic ether derivative with methoxyl and hydroxypropoxyl substitution ratios tailored to viscosity and thermal gelation requirements. Expansion concentrates in controlled-release oral solid dosage forms and edible film coatings, displacing gelatin in vegetarian capsule formulations. China's NMPA-grade manufacturers are scaling export capacity to serve dual-source security needs.
- Carboxymethyl Cellulose:Anionic water-soluble ether with carboxymethyl substitution, valued for rheology control and water retention in food and industrial applications.
- Cellulose Ether:Broad etherification category encompassing ethyl, methyl, and hydroxyethyl variants serving construction, personal care, and paint additive markets.
Volume placements concentrate in microcrystalline cellulose; the faster expansion belongs to hydroxypropyl methylcellulose.
End Use Industry:
Cost tier stratification separates pharmaceutical-grade validation investments from food and industrial applications where specification breadth permits commodity sourcing.
- Pharmaceutical:Highest purity tier requiring USP-NF monograph compliance, FDA drug master file support, and excipient GMP certification. Microcrystalline cellulose dominates tablet binder applications; hydroxypropyl methylcellulose penetrates controlled-release matrices and ophthalmic viscosifiers. Procurement consolidation around sole-source technical partnerships is compressing supplier margins while elevating documentation requirements.
- Food & Beverage:Intermediate specification tier governed by FDA food additive regulations and EFSA purity criteria. Carboxymethyl cellulose serves as thickener and stabilizer in processed foods; cellulose ethers function as film formers in edible coatings. REACH food-contact registration deadlines are forcing supply chain substance disclosure from Asian producers.
- Cosmetics:Personal care applications absorb REACH compliance costs most acutely, with several mid-tier distributors exiting European markets rather than funding registration updates for cellulose ether derivatives.
- Paints & Coatings:Industrial tier subject to EPA volatile organic compound thresholds in cellulose-based paint additives, where cost competition from synthetic thickeners limits margin expansion.
Revenue margins peak in pharmaceutical; cosmetics faces the steepest compliance cost compression.
Application:
Functional role determines supply chain position: thickening agents and stabilizers compete as commodity inputs, while film formers and specialized emulsifiers command specification premiums.
- Thickening Agent:Largest volume application spanning food, cosmetics, and industrial formulations. Carboxymethyl cellulose and cellulose ethers compete with xanthan gum and synthetic polymers; price sensitivity limits differentiation. EPA-regulated paint applications face VOC threshold compliance costs.
- Film Former:Technical specification tier where hydroxypropyl methylcellulose displaces gelatin in edible coatings and enteric drug delivery systems. EU Green Deal biobased procurement criteria create preference premiums for certified-sustainable cellulose derivatives in consumer-facing products.
- Emulsifier:Interface-stabilizing function in food and cosmetic emulsions, typically requiring lower substitution-grade cellulose ethers.
- Stabilizer:Freeze-thaw and syneresis control in processed foods, where carboxymethyl cellulose competes on cost against modified starches and gums.
Volume concentration sits with thickening agents; film formers generate the steepest specification premiums.
Packaging Type:
Customer scale and handling automation requirements segment packaging from manual sachet operations to integrated bulk pneumatic systems.
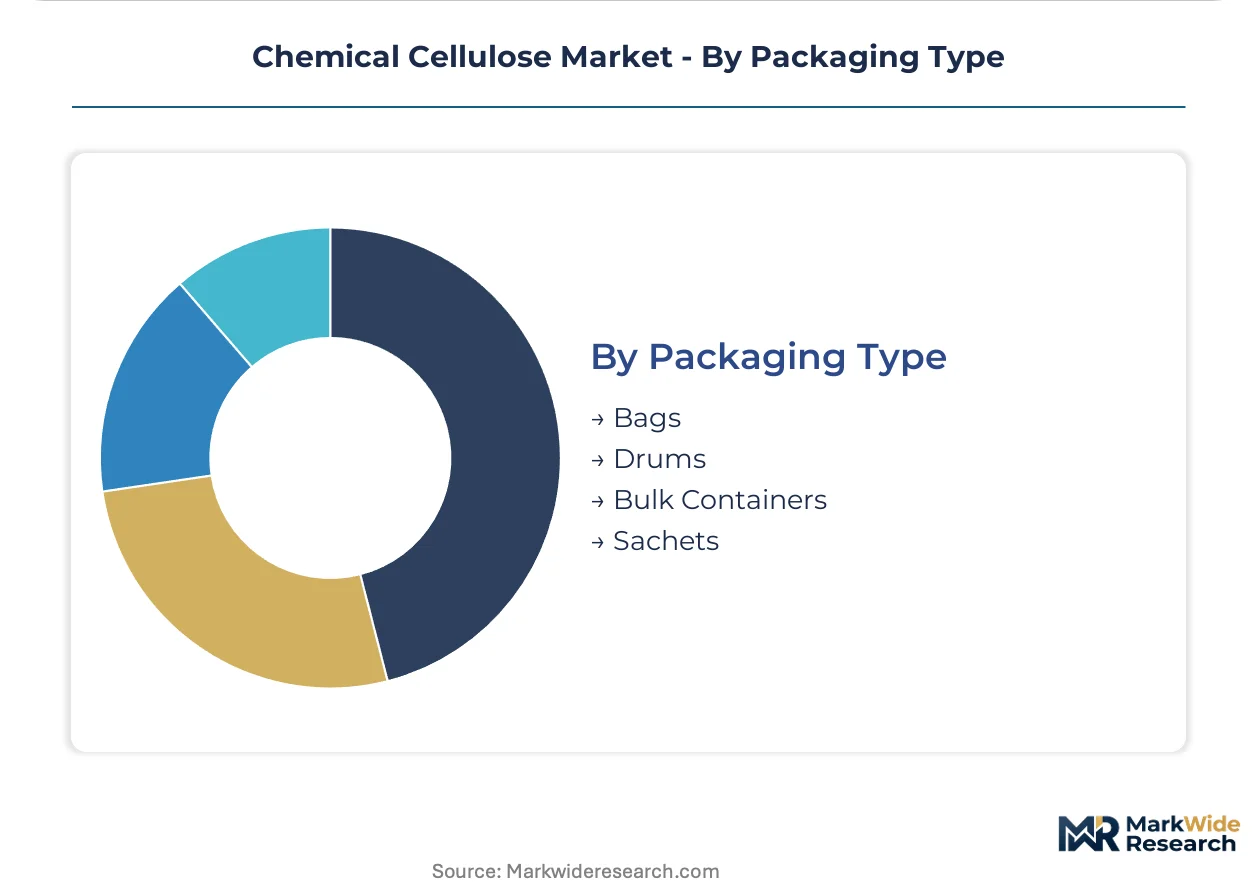
- Bulk Containers:Industrial-scale pharmaceutical and food manufacturing receiving pneumatic-conveyed powder in flexible intermediate bulk containers. Reduces handling stages and contamination risk for high-volume excipient consumers.
- Drums:Standard pharmaceutical-grade packaging for validated microcrystalline cellulose and cellulose ether shipments, with lot traceability and tamper-evident sealing requirements.
- Bags:Multi-wall paper or polyethylene sacks serving mid-scale food and industrial compounders with fork-lift handling.
- Sachets:Pre-measured unit doses for laboratory-scale pharmaceutical development and specialty cosmetic formulation work.
Procurement automation favors bulk containers; sachets retain niche positioning in R&D and specialty compounding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate pharmaceutical-grade cellulose ether capacity serving both domestic formulators and export markets. Tax incentives for biobased chemical manufacturing in Jiangsu and Zhejiang provinces accelerate capital deployment toward USP-NF compliant facilities.
United States
Generic pharmaceutical manufacturers in New Jersey and Pennsylvania drive microcrystalline cellulose consumption for high-speed direct-compression tableting. FDA excipient validation requirements and USP-NF monograph compliance create tiered supplier access that favors producers with integrated regulatory documentation. The Mid-Atlantic pharmaceutical corridor concentrates procurement decisions among three major generic houses seeking dual-source security.
Germany
REACH registration deadlines for cellulose ether derivatives force supply chain substance disclosure from Asian suppliers. ECHA purity mandates filter food-contact volume toward validated European producers with full substance dossiers. The Rhine-Ruhr industrial cluster hosts specialized cellulose ether manufacturing serving construction and personal care sectors where viscosity stability commands specification premiums.
China
NMPA-grade manufacturers scale pharmaceutical-grade microcrystalline cellulose output to serve export markets seeking alternatives to Western supply. Domestic formulators in Shanghai and Suzhou absorb expanding local capacity for tablet binder applications. MIIT industrial policy prioritizes biobased chemical self-sufficiency, directing state-backed financing toward integrated pulp-to-ether facilities.
India
CDSCO excipient guidelines align with USP-NF standards, enabling export-oriented pharmaceutical manufacturing in Hyderabad and Ahmedabad to source validated cellulose grades. The government's PLI scheme for active pharmaceutical ingredients extends to critical excipients, incentivizing domestic microcrystalline cellulose production. Maharashtra's pharmaceutical belt concentrates formulation activity driving binder demand.
Japan
PMDA ophthalmic formulation standards elevate purity requirements for cellulose ethers entering eye drop and gel applications. METI biobased procurement criteria create preference premiums for certified-sustainable derivatives in consumer-facing products. The Kansai chemical corridor maintains specialized capacity for high-viscosity grades serving technical specification markets.
Chemical Cellulose Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding pharmaceutical-grade premiums while toll processors serve industrial applications. The supplier base concentrates around three tiers: multinational chemical houses with pulp-to-ether integration, regional specialists with validated pharmaceutical protocols, and commodity traders serving construction and food sectors. Dominant competitive moves include backward integration into dissolving pulp supply and strategic partnerships with generic pharmaceutical houses seeking sole-source technical relationships.
Among North American integrated producers, Ashland and Eastman Chemical Company exemplify the multinational chemical house archetype with forestry-to-chemicals integration spanning multiple regulatory jurisdictions. Daicel Corporation anchors Asian supply representation for pharmaceutical-grade specialization. These three occupy positions that reflect divergent strategic emphases: North American players leverage regulatory documentation depth, while Japanese specialists concentrate technical specification leadership in ophthalmic and controlled-release applications.
| Leading Market Players |
|---|
| Ashland |
| Shin-Etsu Chemical |
| Dow |
| Daicel Corporation |
| Celanese Corporation |
| Eastman Chemical Company |
| CP Kelco |
| Borregaard |
| LOTTE Fine Chemical |
| Others |
Supply Flow & Price Mechanics
Dissolving pulp costs cascade through three pricing tiers as wood-derived cellulose feeds pharmaceutical-grade microcrystalline cellulose production in the United States, Germany, and China. Energy-intensive spray-drying and micronization assets concentrate margin capture with integrated producers while spot purchasers absorb volatility from forestry harvest cycles.
Pricing Analysis
Lead-time premiums reward validated suppliers holding pharmaceutical-grade inventory for immediate excipient delivery, while spot discounts attract industrial buyers with flexible formulation schedules. Three-tier pricing structure across premium, standard, and economy levels separates USP-NF compliant pharmaceutical grades from food-contact cellulose ethers and industrial thickeners. Cost compression in standard-tier cellulose ethers intensifies because Chinese NMPA-grade manufacturers are scaling export capacity. Generic pharmaceutical houses exhibit lowest price sensitivity, prioritizing regulatory documentation packages over unit economics.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle validated microcrystalline cellulose volumes for FDA-compliant generic drug production. Supply concentrates in China, the United States, and Germany, with Yangtze River Delta special economic zones anchoring Asian pharmaceutical-grade ether capacity. Raw material dependencies center on dissolving pulp from forestry operations, sulfuric acid for controlled hydrolysis, and methyl chloride for etherification chemistry. Single-source vulnerability persists in pharmaceutical-grade spray-drying equipment, where qualified technical personnel remain concentrated among incumbent producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical cellulose sector is accelerating into a vertical-integration race as producers pursue captive dissolving pulp supply to insulate margins from forestry harvest volatility.
For Market Incumbents: Cement regulatory documentation depth as the primary defensive moat by expanding FDA drug master file portfolios and REACH substance dossiers ahead of ECHA purity mandate deadlines. Backward integration into dissolving pulp production in the southeastern United States or Nordic forestry regions secures raw material cost predictability against Asian spot market fluctuations. For New Entrants and Emerging Players: The gap between premium pharmaceutical-grade pricing and economy industrial-tier quotations creates entry space for mid-scale contract manufacturers serving generic pharmaceutical houses seeking dual-source security. Target India's PLI-incentivized excipient production corridor, where CDSCO-aligned validation protocols enable export-oriented manufacturing with lower capital intensity than European or North American facilities. For Investors and Strategic Acquirers: Consolidation of pharmaceutical procurement around sole-source technical partnerships is the leading indicator that validated manufacturing protocols command acquisition premiums over commodity capacity. Mid-cap specialists with integrated pulp-to-ether facilities and existing USP-NF monograph coverage represent the most defensible target archetype. Watch for REACH registration deadline extensions as a signal of compliance cost barriers filtering marginal competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive forestry supply insulates margin from raw material volatility in Nordic and southeastern US harvest regions. |
| REACH Substance Dossier Expansion | Full supply-chain disclosure meets ECHA purity mandates for food-contact cellulose ether derivatives in European markets. |
| Continuous Processing Technology Adoption | Modular reactor-to-dryer systems reduce batch-to-batch variability for mid-scale pharmaceutical contract manufacturers. |
| Dual-Source Security Partnerships | Sole-source technical relationships with generic drug houses secure volume commitments against spot purchasing volatility. |
| Biobased Certification Program | EU Green Deal and USDA BioPreferred labeling create preference premiums for certified-sustainable cellulose derivatives. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with pharmaceutical procurement directors, cellulose ether plant managers, regulatory affairs specialists at excipient manufacturers, and distribution channel partners. FDA drug master file repositories, ECHA registration dossiers, USP-NF monograph databases, and import-export trade statistics provided validation layers. Bottom-up excipient demand modeling triangulated against top-down chemical cellulose production capacity assessments.
Segment-level granularity modeled product type distinctions between microcrystalline cellulose and cellulose ether variants, purity grade tiers from pharmaceutical to industrial specifications, end-use industry applications across drug formulation and food processing, and regional production hub concentrations. CAGRs were derived from volume trajectory analysis across the projection horizon, incorporating pharmaceutical tablet production forecasts, construction sector rheology modifier demand, and edible film coating penetration rates.
Inputs from FDA and ECHA regulatory databases were available through the study window; gaps in real-time dissolving pulp inventory data from private forestry operators introduce uncertainty bands around raw material cost assumptions. Forecasts reflect assumptions regarding REACH implementation timelines, pharmaceutical outsourcing trends, and Chinese export capacity expansion. Periodic stress-testing of base assumptions against regulatory deadline shifts and pulp price volatility events is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Liquid Paperboard Market
Paper Products
Paper Making Machine Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Europe Paper Market
Paper Products
North America Decor Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Insulation Paper Market
Paper Products
Graphic Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Recovered Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Paper Pigment Market
Paper Products
Duplex Paper and Board Market
Paper Products
North America Specialty Paper Market