
 Fluff Pulp Market | 2026-2036
Fluff Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Fluff Pulp Market Analysis
Modular absorbent core designs are shifting buyer procurement patterns, allowing diaper and hygiene manufacturers to mix fluff pulp grades with superabsorbent polymers in configurable ratios. Suzano leverages its South American hardwood fiber base to anchor long-term supply contracts with global personal care brands. Georgia-Pacific competes through integrated pulp-to-tissue operations across the US Gulf Coast. International Paper sustains scale advantages in bleached softwood kraft output for premium hygiene applications.
Fluff pulp consists of specially treated, bleached softwood Kraft fibers with high bulk and absorbency, typically achieving 18-22 grams per gram fluid retention capacity, engineered for disposable absorbent products. The product type landscape shows natural fluff pulp occupying the dominant volume position, while biodegradable fluff variants are capturing margin pools as brand owners pursue plastic-reduction pledges. Application demand concentrates in personal care products, where medical supplies represent a faster-growing but smaller segment driven by surgical and wound-care consumption.
The US EPA enforces effluent limitations under the Cluster Rule that shape bleaching chemistry choices and capital allocation at Kraft mills. ECHA's REACH framework governs chemical inputs in European fluff pulp supply chains, affecting export competitiveness for non-compliant producers. China's MEE applies dual carbon goals that constrain expansion of virgin pulp capacity, redirecting investment toward efficiency retrofits. Stakeholders must monitor how regulatory divergence on biodegradability certification reshapes cross-border sourcing strategies and product qualification timelines.
Market Dynamics
Modular absorbent core architectures are fragmenting traditional grade specifications, forcing fluff pulp suppliers to engineer fiber blends that perform across variable SAP ratios rather than fixed formulations.
Growth Catalysts
- EU Green Deal fiber transparency mandates:Brand owners under CSRD disclosure rules are demanding chain-of-custody documentation that rewards certified sustainable sourcing.
- Adult incontinence product demand:Aging demographics in Germany, Japan, and the United States are expanding orders for high-bulk, low-density fluff grades optimized for overnight absorbency.
- Biodegradable fluff variants:Plastic-reduction pledges by personal care multinationals are opening specification slots for compostable fiber alternatives in premium diaper lines.
Market Restraints
- Bleached softwood Kraft supply concentration:Integrated producers in the US Southeast control over half of export-grade fluff pulp capacity, creating bottleneck risk during hurricane seasons.
- Energy cost volatility at Kraft mills:Natural gas and electricity input swings compress operating margins for mechanical drying operations at non-integrated facilities.
- Air-laid nonwoven substitution:Synthetic fiber webs are capturing share in lighter-weight hygiene applications where fluid retention requirements fall below 15 grams per gram.
Strategic Opportunities
- Brazilian hardwood fiber expansion:Eucalyptus plantations in Mato Grosso and São Paulo states offer faster rotation cycles than Nordic softwood, enabling cost-competitive biodegradable grade production.
- Wound care medical applications:Surgical dressing manufacturers are specifying fluff pulp with enhanced purity certifications for post-operative absorption layers.
- Direct mill-to-converter partnerships:Diaper manufacturers in the US Gulf Coast are bypassing merchant distributors to secure volume commitments with pulp producers holding FSC chain-of-custody.
Industry Challenges
- Biodegradability certification timelines:TÜV OK Compost and BPI qualification protocols for novel fluff grades extend product launch cycles by 18-24 months.
- Legacy air-forming line retrofit costs:Converting equipment designed for homogeneous fiber feeds requires capital-intensive modification to handle variable SAP-fluff ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluff Pulp Market |
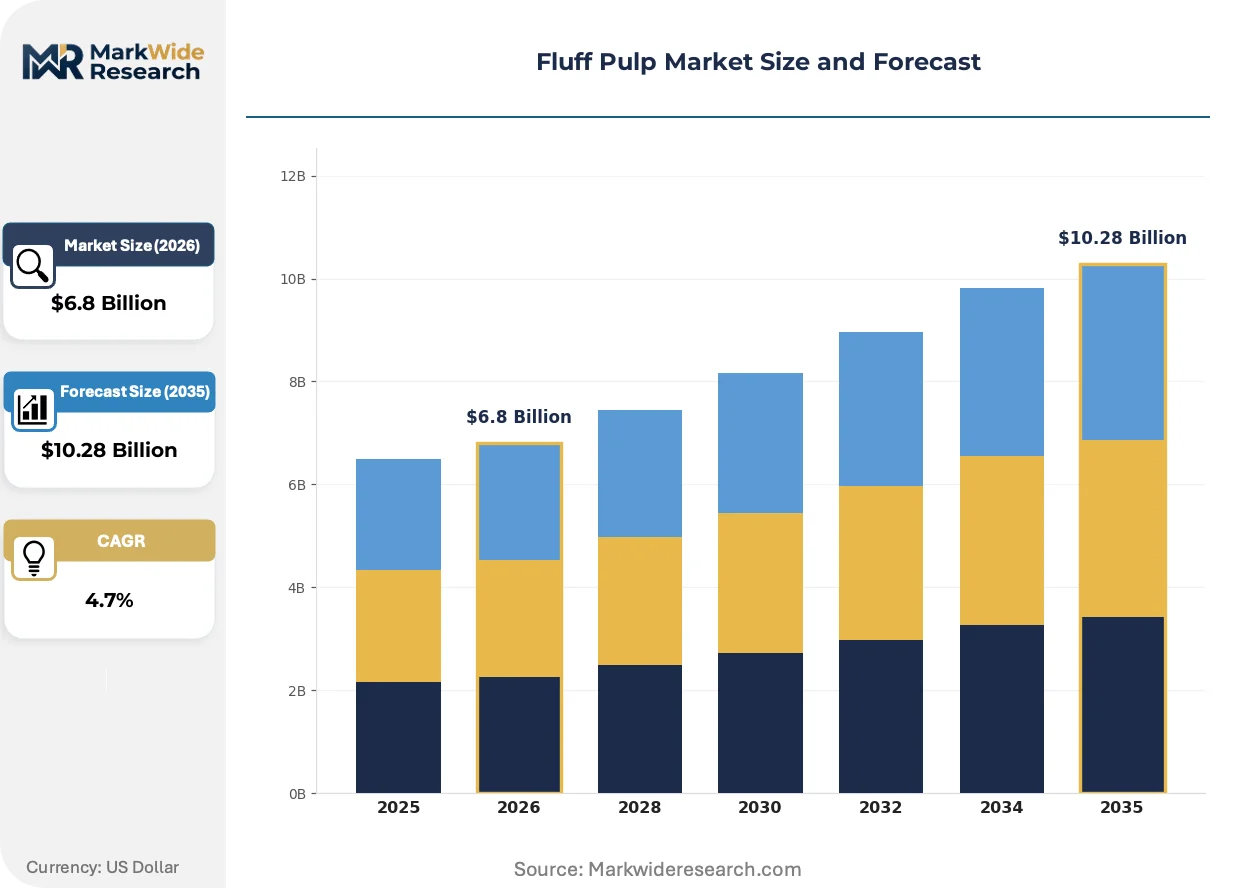
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fluff, Synthetic Fluff, Biodegradable Fluff, Superabsorbent Fluff Application: Personal Care Products, Medical Supplies, Household Items, Industrial Absorbents End User: Manufacturers, Retailers, Healthcare Providers, Consumers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | International Paper, Domtar, Suzano, Weyerhaeuser Company, UPM-Kymmene Corporation, Georgia-Pacific, ARAUCO, Klabin, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluff Pulp Market Emerging Trajectories
Digital process control systems and sustainability certification protocols are redefining how fluff pulp quality is specified, verified, and priced across absorbent product supply chains.
Cellulose nanofibril reinforcement is converging with traditional fluff pulp webs to enhance wet integrity without density penalties. Premium diaper manufacturers in Scandinavia are piloting these hybrid cores for toddler overnight segments. The technology is converging with superabsorbent polymer distribution patterns to enable thinner core designs that maintain fluid retention benchmarks.
REACH chemical authorization requirements are restricting certain bleaching aids and process chemicals in European fluff pulp production. Kraft mills serving EU personal care brands are reformulating their fiber treatment sequences to maintain export eligibility. Medical-grade fluff applications face the steepest compliance burden under ECHA's updated substance evaluation timelines.
Specification-driven vendor consolidation is compressing the supplier base for global personal care brands. Buyers are reducing qualified fluff pulp sources from six-plus merchants to two or three integrated producers with certified sustainability credentials. This concentration is most visible in North American supply chains, where diaper manufacturers prioritize suppliers with captive softwood fiber and on-site bleaching capacity.
Fluff Pulp Market Segmentation
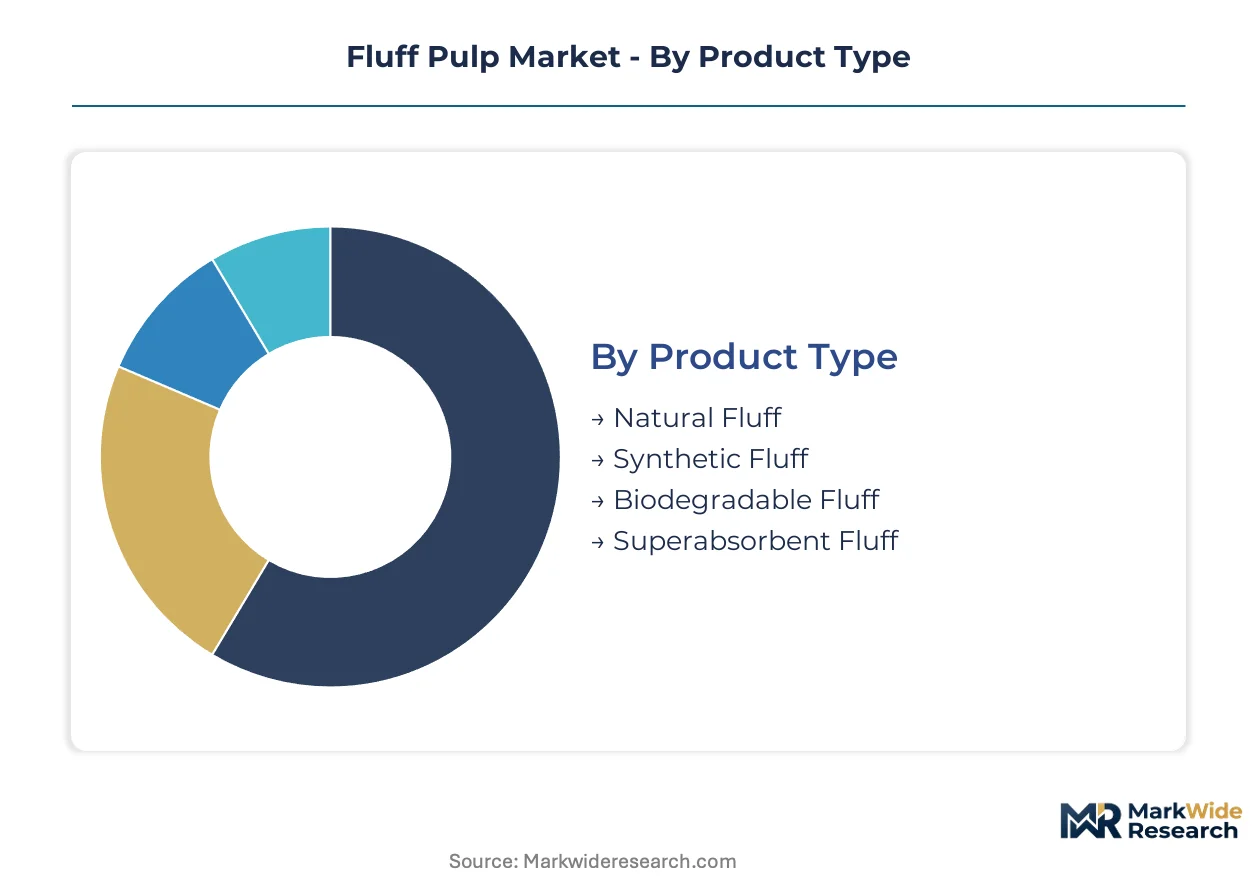
Segmentation in the fluff pulp market reveals how fiber specifications align with divergent performance requirements across hygiene and medical end-uses. Procurement patterns vary sharply between commodity-grade volume buyers and specification-driven medical purchasers.
Product Type:
Supply concentration in bleached softwood Kraft capacity shapes competitive dynamics across fiber grades.
- Natural Fluff:Standard bleached softwood Kraft fibers with 18-22 grams per gram fluid retention capacity dominate diaper and feminine hygiene applications. Demand concentrates in the southeastern United States, where integrated pulp-to-diaper supply chains cluster around Georgia-Pacific and International Paper facilities serving Procter & Gamble and Kimberly-Clark converting plants.
- Biodegradable Fluff:Compostable fiber alternatives engineered from eucalyptus hardwood achieve comparable absorbency with faster biodegradation timelines. European personal care brands under CSRD disclosure rules are sourcing certified grades from Suzano's Brazilian operations to meet plastic-reduction pledges.
- Synthetic Fluff:Man-made fiber webs offering consistent denier and controlled pore structures for specialized industrial applications.
- Superabsorbent Fluff:Fiber grades pre-blended with SAP particles to simplify converting line operations for mid-tier diaper manufacturers.
Natural fluff absorbs the bulk of installed capacity; biodegradable fluff is expanding most quickly.
Application:
End-use performance thresholds determine fiber purity requirements and certification burdens.
- Personal Care Products:Diapers, adult incontinence pads, and feminine hygiene items consume high-bulk, low-density fluff grades optimized for overnight absorbency. Aging demographics in Germany, Japan, and the United States are expanding orders for premium overnight segments requiring 20+ grams per gram retention.
- Medical Supplies:Surgical dressings and wound-care layers demand enhanced purity certifications under FDA and EMA medical device regulations. Post-operative absorption specifications are climbing fastest as ambulatory surgical centers multiply across North America and Western Europe.
- Household Items:Cleaning wipes and absorbent towels utilize lower-specification fiber grades where cost minimization dominates purchasing criteria.
- Industrial Absorbents:Spill-control pads and oil-cleanup materials employ densified fluff webs with chemical treatment for hydrocarbon retention.
Personal care products command the majority of fiber volume; medical supplies are climbing the fastest.
End User:
Customer scale and integration level determine pricing leverage and contract structures.
- Manufacturers:Integrated diaper and hygiene producers with captive converting capacity negotiate multi-year supply agreements. Direct mill-to-converter partnerships in the US Gulf Coast are bypassing merchant distributors to secure FSC chain-of-custody documentation.
- Healthcare Providers:Hospital systems and surgical centers specify medical-grade fluff with lot traceability and sterilization compatibility.
- Retailers:Private-label hygiene brands procure through merchant distributors lacking direct mill relationships.
- Consumers:Small-scale purchasers of specialty absorbent products represent minimal fiber volume.
Manufacturers capture the largest share of direct supply relationships; healthcare providers are gaining specification influence fastest.
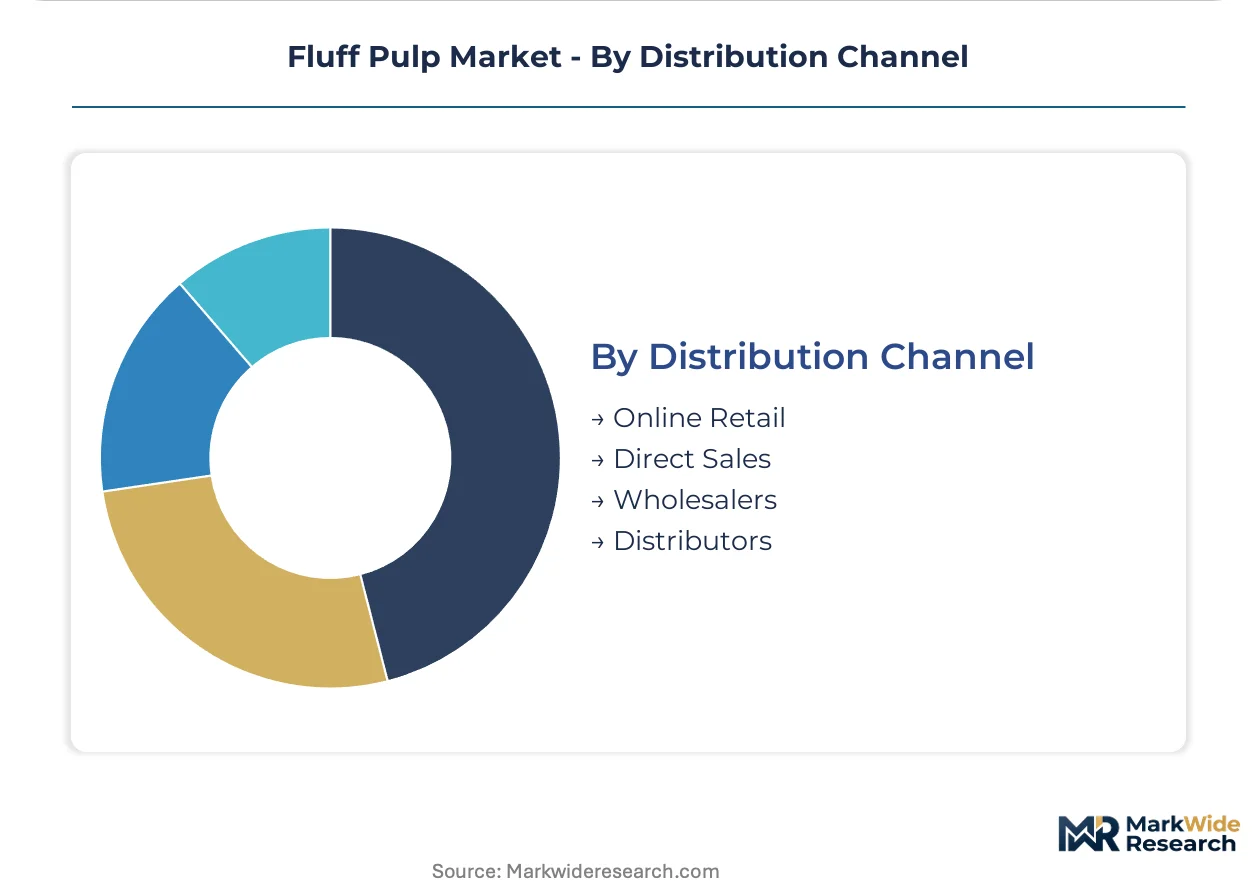
Distribution Channel:
Channel selection reflects order scale, certification requirements, and geographic proximity to production.
- Direct Sales:Volume commitments between pulp producers and multinational personal care brands eliminate intermediary margins. Suzano and Georgia-Pacific sustain dedicated account teams for global hygiene manufacturers requiring chain-of-custody documentation.
- Distributors:Regional merchants serve mid-tier converters lacking scale for direct mill negotiations.
- Online Retail:E-commerce platforms handle small-lot specialty grades for research and prototype applications.
- Wholesalers:Bulk handlers move commodity fluff pulp to non-integrated tissue converters.
Direct sales absorb the majority of high-volume transactions; distributor relationships are expanding most quickly among emerging regional converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the southeastern United States and Brazil, while consumption concentrates in Germany, Japan, and China where aging populations and hygiene product manufacturing drive fiber demand. This geographic split shapes trade flows and contract negotiation leverage across the value chain.
United States
Adult incontinence product manufacturers in the US Southeast are expanding orders for high-bulk fluff grades as Medicare coverage broadens for home healthcare supplies. EPA effluent limitations under the Cluster Rule govern bleaching chemistry at Kraft mills in Georgia and Alabama. Integrated pulp-to-diaper supply chains cluster around converting facilities in Augusta, Georgia and Mobile, Alabama serving major personal care brands.
Brazil
Eucalyptus hardwood plantations in Mato Grosso and São Paulo states enable cost-competitive biodegradable fluff production for European brand owners. ANVISA, the national health regulatory agency, oversees medical-grade fiber purity certifications for export eligibility. Suzano anchors long-term supply contracts from its integrated operations in the interior São Paulo region.
Germany
Aging demographics are expanding orders for premium overnight adult incontinence segments requiring 20+ grams per gram fluid retention. ECHA's REACH framework restricts certain bleaching aids in fiber treatment sequences for EU market access. Industrial buyers in the Rhine-Ruhr corridor are consolidating qualified suppliers under CSRD disclosure rules.
China
Domestic diaper manufacturers are redirecting procurement toward certified sustainable grades as consumer preferences shift. MEE dual carbon goals constrain expansion of virgin pulp capacity, redirecting investment toward efficiency retrofits at existing mills. Converting facilities in the Yangtze River Delta face fiber cost volatility from import dependency.
Japan
Super-aging population dynamics are accelerating adult incontinence product demand faster than any other developed economy. METI industrial standards govern absorbent product safety and fiber purity thresholds for domestic market placement. Manufacturing clusters in the Kansai region around Osaka maintain just-in-time relationships with Southeast Asian fiber suppliers.
Fluff Pulp Market Vendor Landscape
The competitive structure tilts toward integrated producers with captive softwood fiber and on-site bleaching capacity. Merchant distributors are losing share as direct mill-to-converter partnerships eliminate intermediary margins. Three archetypes dominate: North American integrated pulp-to-tissue operators, South American hardwood fiber specialists, and Nordic sustainability-certified producers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure volume commitments with global personal care brands.
Within the integrated producer tier, International Paper and Georgia-Pacific exemplify the North American archetype with southeastern US mill networks, while Suzano anchors the South American hardwood fiber position. These three companies represent the supplier consolidation trend as buyers reduce qualified sources from six-plus merchants to two or three integrated producers with certified sustainability credentials.
| Leading Market Players |
|---|
| International Paper |
| Domtar |
| Suzano |
| Weyerhaeuser Company |
| UPM-Kymmene Corporation |
| Georgia-Pacific |
| ARAUCO |
| Klabin |
| Stora Enso |
| Others |
Supply Flow & Price Mechanics
Integrated diaper manufacturers in the US Southeast wield outsized pricing leverage through multi-year volume commitments, anchoring contract-based long-term offtake structures that compress margins for non-integrated merchant distributors. This buyer concentration forces suppliers to absorb energy cost volatility while competing on FSC chain-of-custody certification tiers.
Pricing Analysis
Margin tightening in biodegradable fluff grades reflects eucalyptus fiber premium differentials and extended TÜV OK Compost certification timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity certification and volume scale, with medical-grade specifications commanding the widest spreads. Cost-down pressure on commodity natural fluff accelerates because air-laid nonwoven substitutes are capturing lighter-weight hygiene applications. Private-label retailers exhibit the highest price sensitivity, while multinational personal care brands prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Augusta, Georgia and Mobile, Alabama anchor hub-and-spoke patterns serving converting facilities along the US Gulf Coast. Production concentrates in the United States, Brazil, and Nordic countries, with Brazilian eucalyptus plantations feeding European biodegradable demand. Raw material dependencies center on bleached softwood Kraft chips, chlorine dioxide for elemental chlorine-free bleaching, and superabsorbent polymer inputs. Single-source vulnerability intensifies during hurricane seasons when southeastern US mill networks face disruption. Distribution runs through direct mill-to-converter partnerships that bypass traditional merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluff pulp is consolidating toward integrated producers with captive fiber and certified sustainability credentials, as CSRD disclosure rules and plastic-reduction pledges squeeze merchant distributors without chain-of-custody documentation.
For Market Incumbents: Deepen backward integration into eucalyptus plantation assets in Mato Grosso to secure cost-competitive biodegradable grade feedstock. Expand on-site bleaching capacity at southeastern US mills to capture medical-grade specification premiums. Air-laid nonwoven substitution in sub-15 grams per gram applications threatens volume retention in commodity segments.
For New Entrants and Emerging Players: EU Green Deal fiber transparency mandates in Germany open a window for certified sustainable sourcing specialists serving mid-tier converters lacking direct mill relationships. Target wound care medical applications where FDA purity certifications create specification barriers for commodity suppliers. Pursue direct partnerships with ambulatory surgical centers bypassing hospital GPO contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor non-integrated merchant distributors in the US Southeast facing margin compression from energy cost volatility. Long-term viability hinges on captive softwood fiber access and on-site chlorine dioxide bleaching infrastructure. Monitor biodegradable fluff certification backlog timelines as inflection indicator for premium grade capacity shortages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Suzano's Mato Grosso eucalyptus holdings anchor cost-competitive biodegradable grade supply. |
| Medical-Grade Certification Investment | FDA and EMA purity standards unlock surgical dressing specifications with premium pricing power. |
| Direct Mill-to-Converter Partnership | Georgia-Pacific's Augusta facility bypasses merchant channels to serve Procter & Gamble converting plants. |
| Sustainability Repositioning | FSC chain-of-custody documentation satisfies CSRD disclosure rules for European personal care brands. |
| Capacity Expansion in Biodegradable Grades | TÜV OK Compost qualification protocols extend launch cycles but capture plastic-reduction pledge demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pulp mill operations directors, diaper manufacturer procurement leads, hygiene product R&D heads, and sustainability certification auditors. Secondary sources included EPA effluent discharge reports, ECHA REACH substance evaluations, FSC chain-of-custody databases, and US Census Bureau trade statistics. Bottom-up fiber demand modeling triangulated against top-down personal care product production estimates.
Segment-level granularity modeled product type splits across natural, biodegradable, synthetic, and superabsorbent fluff grades; application demand across personal care, medical, household, and industrial end-uses; and regional production-consumption imbalances. CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Forecast inputs incorporated SAP-fluff ratio trends in modular core designs and EU Green Deal compliance cost assumptions.
The model assumes a particular technology adoption path; alternative pathways for cellulose nanofibril reinforcement would alter the outlook for wet integrity specifications in premium overnight segments. Forecasts reflect assumptions around certification timeline standardization and energy cost normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Europe Paper Market
Paper Products
Metallized Paper Market
Paper Products
Cheque Paper Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Sanitary Paper Products Market
Paper Products
Medical Grade Paper Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
White Line Chipboard Market
Paper Products
Liquid Paperboard Market
Paper Products
Recording Chart Paper Market
Paper Products
Thermal Paper Market