
 Global High Performance Polyamides Market | 2026-2036
Global High Performance Polyamides Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Polyamides Market Intelligence
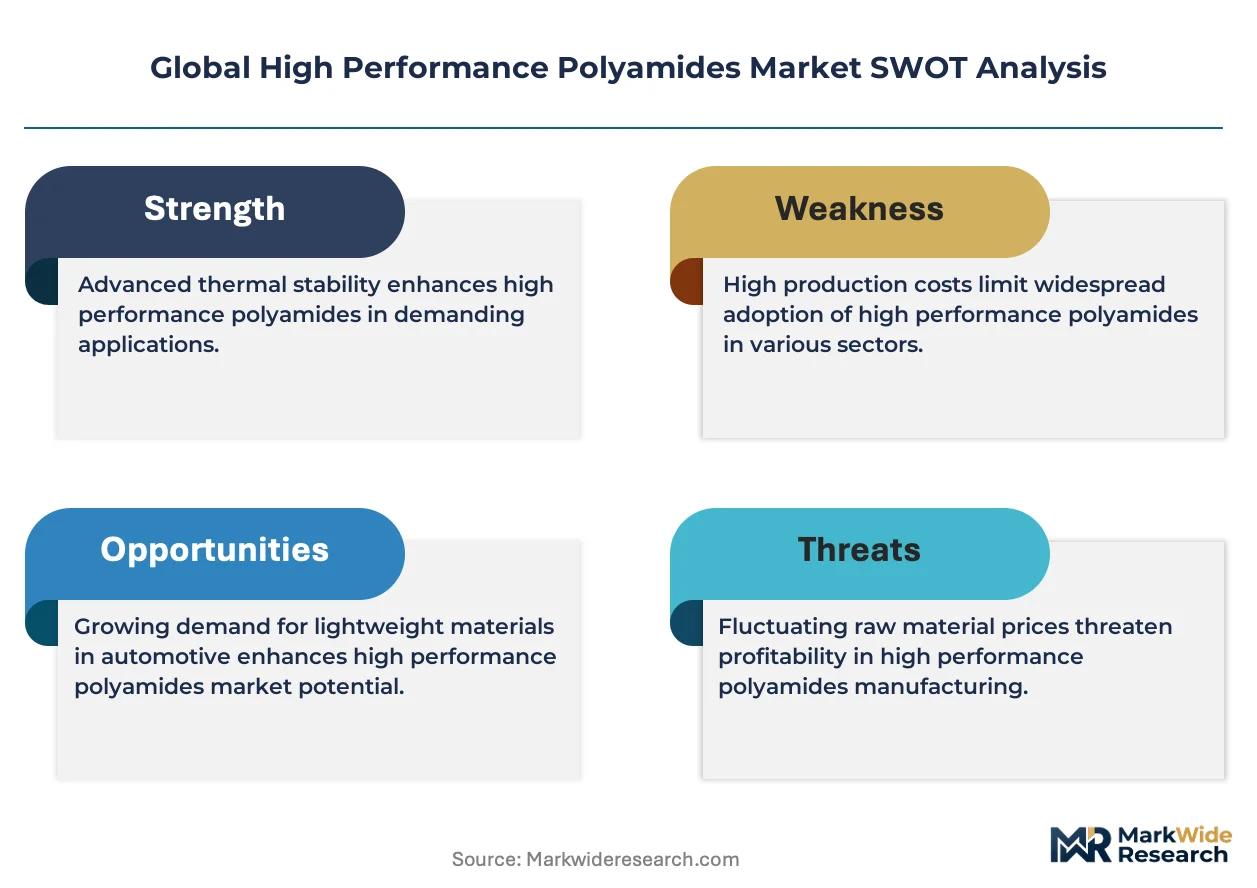
European specialty chemical production capacity for key polyamide precursors is hardening due to elevated energy costs and feedstock volatility. This environment benefits diversified producers like BASF, which leverages its integrated Verbund system for cost control. Arkema S.A. differentiates through its focus on bio-based and high-performance specialty polymers. Celanese Corporation competes on the strength of its engineered materials portfolio for automotive and electronics applications.
High performance polyamides are a class of semi-crystalline thermoplastics characterized by superior thermal stability and chemical resistance compared to standard polyamides. Their primary function is to replace metal and other materials in high-temperature or mechanically stressful environments. Within the product landscape, PA 46 and PA 12 command premium pricing due to their specialized properties. The automotive segment remains the largest end-user, but the electrical and electronics application area represents the fastest-growing source of new demand.
Material selection is influenced by a complex web of international regulations, including Europe's REACH framework for chemical safety and the US EPA's Toxic Substances Control Act. Additionally, standards like ISO 10993 for biocompatibility and specific automotive OEM material approvals dictate market access. Navigating these divergent standards while ensuring supply chain stability for critical precursors is the central strategic challenge for manufacturers.
Market Dynamics
The central force shaping the market is the accelerated substitution of metals in automotive applications, driven by stringent emissions regulations in the EU and China. This pressure compels a fundamental shift toward lightweighting in electric vehicle platforms, creating concentrated demand for high performance polyamides.
Growth Catalysts
- Automotive Lightweighting:Demand for lighter components to extend electric vehicle range and improve efficiency drives adoption in structural parts and battery enclosures.
- Electronics Miniaturization:The electrical and electronics segment requires materials with high thermal stability for smaller, more powerful components like connectors and sockets.
- EU CO2 Standards:Regulations mandating lower fleet-wide emissions force automakers to use high performance polyamides to reduce vehicle weight, creating a direct regulatory pull.
Market Restraints
- Feedstock Volatility:Unpredictable pricing and availability of key precursors, particularly in Europe due to energy costs, create margin pressure and supply instability.
- Substitution by Alternatives:In certain applications, materials like PEEK, PPS, or advanced carbon composites offer superior performance, limiting the addressable market for HPPAs.
- Processing Complexity:Compared to standard engineering plastics, HPPAs often require higher processing temperatures and specialized equipment, increasing manufacturing costs for end-users.
Strategic Opportunities
- Bio-Based Polyamides:Growing demand for sustainable materials opens a significant opportunity for bio-derived HPPAs, especially in consumer goods and automotive interiors.
- Hydrogen Economy Components:The emerging hydrogen fuel cell market requires chemically resistant materials for seals, gaskets, and tank liners, representing new application white space.
- Medical Device Expansion:Materials meeting ISO 10993 for biocompatibility can penetrate high-value applications in surgical instruments and durable medical equipment.
Industry Challenges
- Regulatory Compliance Burden:Navigating the divergent requirements of chemical safety regulations like Europe's REACH and the US EPA's TSCA complicates global product launches.
- Precursor Supply Chain Security:Securing a stable, long-term supply of critical chemical intermediates from a limited number of global sources remains a central operational hurdle for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Polyamides Market |
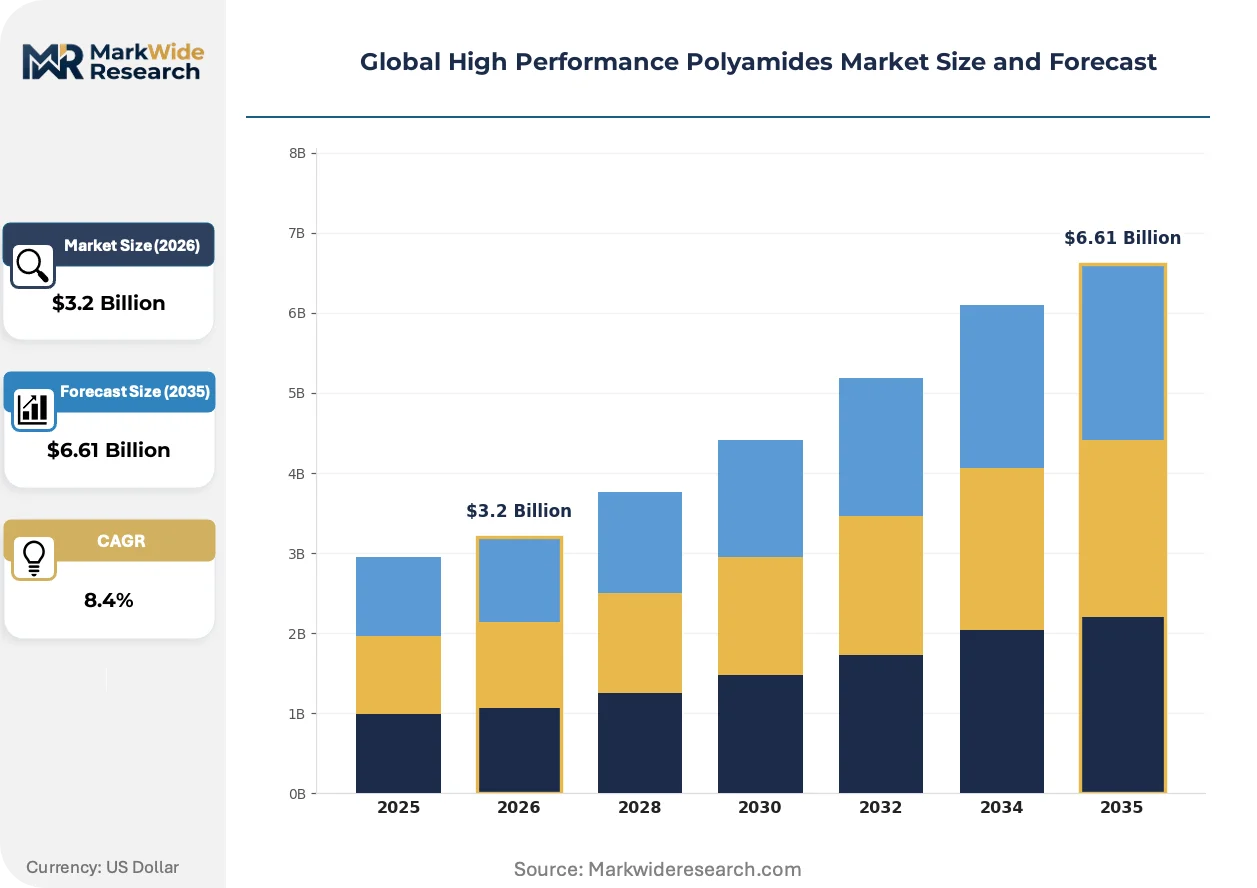
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.61 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 12, PA 46 End User: Aerospace, Automotive, Electrical, Consumer Goods Form: Granules, Films, Fibers, Sheets Application: Filtration, Coatings, Electronics, High-Performance Textiles |
| Companies Covered | Celanese Corporation, BASF, Arkema S.A., Evonik Industries, SABIC, Syensqo, EMS-CHEMIE HOLDINGS AG, Mitsubishi Chemical Group Corporation, Kuraray Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Polyamides Market Strategic Shifts & Innovations
Material science converges with sustainability mandates, compelling a shift toward circularity and application-specific polymer design. This evolution prioritizes lifecycle performance over simple material cost, altering supplier-OEM relationships.
Bio-based polyamides offer a reduced carbon footprint compared to fossil-fuel-based versions. Automotive and electronics OEMs are specifying these materials to meet corporate sustainability goals. This shift is integrating circular economy principles directly into the polymer design and selection process for high-stress applications.
Europe's REACH framework scrutinizes chemical substances, including some polyamide precursors and additives. This forces ongoing reformulation and extensive documentation, adding cost and complexity. Producers exporting to the EU are most affected, investing in testing to ensure compliance and maintain market access.
A demand-side shift is occurring from transactional sales toward collaborative, application-specific material development. This model disrupts traditional channels, favoring suppliers with advanced simulation and engineering capabilities. The trend is most prominent within the electric vehicle sector for battery thermal management and high-voltage systems.
Global High Performance Polyamides Market Segmentation
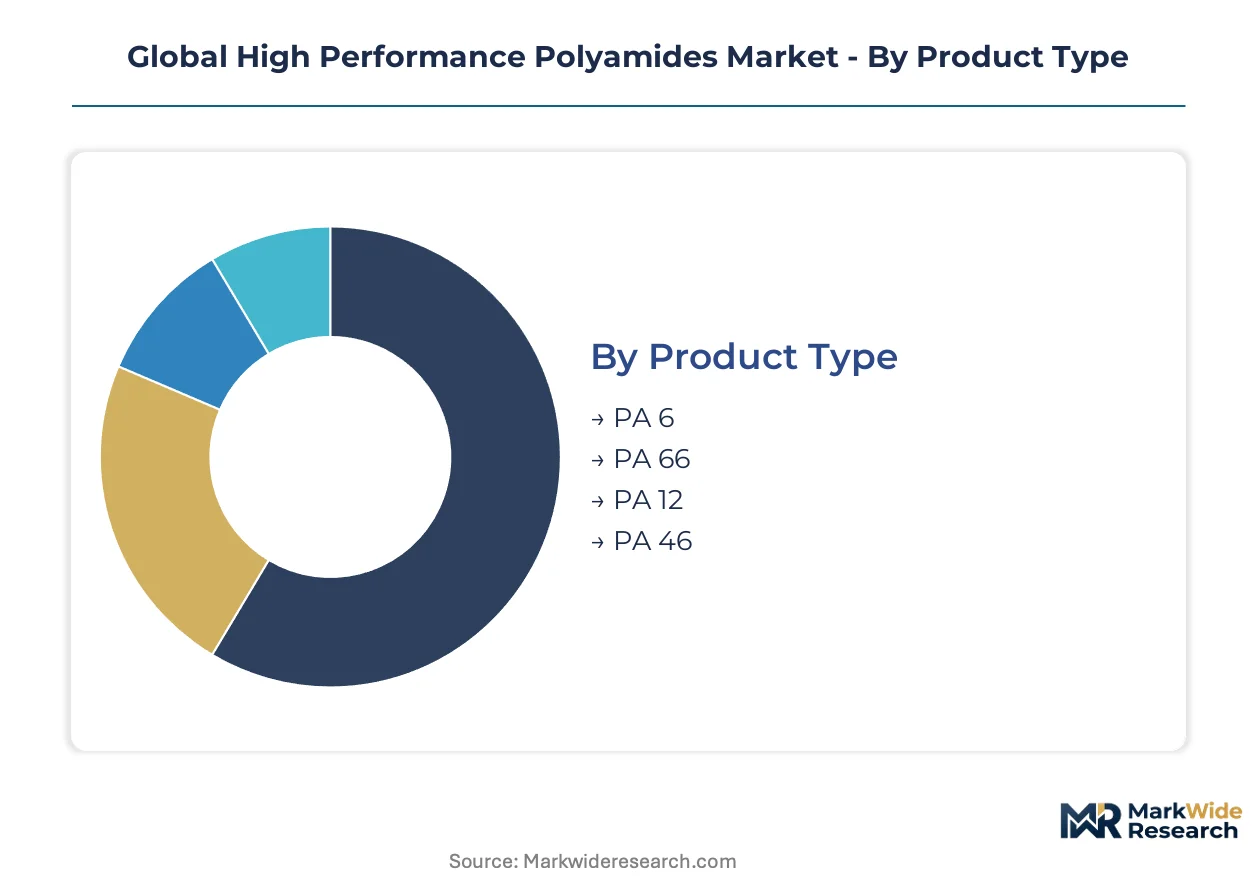
Understanding the market's segmentation by product type, end user, form, and application provides a granular view of demand drivers and competitive dynamics. This detailed breakdown highlights specific growth pockets and areas requiring tailored material solutions across diverse industries.
Product Type:
The product type segmentation reveals the spectrum from standardized, high-volume polyamides to highly customized, specialty grades designed for extreme conditions.
- PA 6:A widely used semi-crystalline polyamide known for its mechanical strength and processability, often employed in automotive components and industrial films where cost-effectiveness is a primary concern.
- PA 66:Characterized by high stiffness, good abrasion resistance, and a relatively high melting point, this grade finds extensive use in automotive engine parts and electrical connectors.
- PA 12:This high-performance polyamide offers excellent chemical resistance, low moisture absorption, and good dimensional stability, making it suitable for fuel lines in automotive systems and medical devices meeting ISO 10993 standards. Demand for PA 12 is concentrating in Europe for specialized tubing and precision parts.
- PA 46:Exhibiting superior heat resistance and stiffness compared to other polyamides, PA 46 is engineered for high-temperature automotive applications like under-the-hood components and power transmission belts, particularly in Germany's stringent automotive sector.
Leading the category by volume: PA 6. Growing fastest: PA 12.
End User:
The end-user landscape reflects varying degrees of material specification complexity and regulatory oversight, influencing material selection and supplier engagement.
- Aerospace:This segment demands materials with exceptional strength-to-weight ratios, flame retardancy, and resistance to extreme temperatures, primarily for interior components and structural elements.
- Automotive:As the largest consumer, this sector requires high performance polyamides for lightweighting initiatives in electric vehicles, including battery enclosures and structural parts, driven by EU CO2 standards and China's dual carbon goals. Demand is particularly strong in automotive manufacturing hubs like Germany and Japan.
- Electrical:This segment represents the fastest-growing source of new demand, requiring high-temperature resistant and electrically insulating materials for connectors, circuit breakers, and miniaturized electronic components, especially in consumer electronics and industrial control systems.
- Consumer Goods:Polyamides in this sector are selected for their durability, aesthetic appeal, and processing ease in applications ranging from sports equipment to household appliances.
Automotive applications command the largest market share, with the Electrical segment gaining share fastest.
Form:
The physical form of high-performance polyamides determines their processing methods and suitability for diverse manufacturing techniques, impacting material handling and end-product properties.
- Granules:The most common form, granules are used in injection molding, extrusion, and compounding processes to produce a wide array of components for automotive, electrical, and industrial applications.
- Films:Offering excellent barrier properties and mechanical strength, polyamide films are critical in packaging, electrical insulation, and specialized industrial membranes.
- Fibers:High-performance polyamide fibers provide superior tensile strength and abrasion resistance, finding use in technical textiles, industrial ropes, and tire cords.
- Sheets:Polyamide sheets are utilized in thermoforming and machining processes to create durable parts for industrial equipment, protective coverings, and specific automotive components.
Granules represent the most mature form factor, while Films are expanding most quickly due to specialized applications.
Application:
Application areas highlight the functional roles of high-performance polyamides, ranging from protective barriers to structural components, each with distinct performance requirements.
- Filtration:Polyamides are used in filtration media due to their chemical resistance and mechanical stability, particularly in industrial and automotive fluid management systems.
- Coatings:Polyamide coatings offer enhanced abrasion resistance, chemical protection, and aesthetic properties for metal parts, industrial equipment, and wiring.
- Electronics:This application area requires materials with high dielectric strength, thermal stability, and flame retardancy for connectors, housings, and insulation in miniaturized devices and high-voltage systems. The segment is expanding rapidly in Asia-Pacific.
- High-Performance Textiles:Used in demanding textile applications such as airbags, protective clothing, and industrial fabrics, these polyamides offer durability and specific functional properties.
Electronics applications demonstrate the steepest expansion trajectory, with Coatings maintaining a significant market presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European precursor manufacturing regions face rising energy costs, impacting global high performance polyamide supply chains. This pressure influences material sourcing decisions for automotive and electronics manufacturers worldwide. Demand for these advanced polymers concentrates in key industrial hubs across multiple continents.
Germany
Germany's automotive sector drives significant demand for high performance polyamides, particularly PA 46 for under-the-hood components. EU CO2 standards compel automakers to adopt lightweight materials for electric vehicle platforms. Production and application development concentrate within automotive manufacturing clusters in Bavaria and Baden-Württemberg.
Japan
Japan's automotive industry requires high performance polyamides for electric vehicle battery enclosures and structural parts. METI supports advanced material development to enhance industrial competitiveness and sustainability. Major automotive manufacturing in Aichi Prefecture and electronics production in the Kanto region drive material innovation.
United States
The United States automotive sector, alongside aerospace and electronics, demands high performance polyamides for lightweighting and thermal management. US EPA regulations, including TSCA, influence material selection and chemical safety compliance for domestic producers. Automotive manufacturing in Michigan and advanced electronics in California demonstrate concentrated material usage.
China
China's rapid electric vehicle production and expanding electronics sector fuel substantial high performance polyamide consumption. The nation's dual carbon goals accelerate material substitution from metals to lighter polymers. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta lead in adopting these advanced materials.
South Korea
South Korea's advanced electronics and automotive industries increasingly specify high performance polyamides for critical components. MIIT standards guide the development and application of innovative industrial materials for domestic manufacturers. Electronics production in the Seoul Capital Area and automotive manufacturing in Ulsan represent key demand centers.
Global High Performance Polyamides Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue bio-based polyamides and specialized applications. The market exhibits a tiered structure, from large diversified chemical companies to focused engineered materials specialists. Strategic archetypes include integrated chemical companies leveraging feedstock advantages and innovation-driven firms targeting niche high-performance segments. Companies pursue portfolio diversification and technology licensing to expand their market reach.
Within the integrated chemical giants, BASF exemplifies a producer leveraging its Verbund system for cost-controlled precursor supply across various polyamide grades. Arkema S.A., a French-based specialty materials company, occupies a position focused on bio-based and high-performance polymers, differentiating its portfolio. Celanese Corporation, a US-based chemical and advanced materials company, anchors its competitive offering on an engineered materials portfolio for demanding automotive and electronics applications. These firms collectively represent the strategic approaches to high performance polyamide market development and innovation.
| Leading Market Players |
|---|
| Celanese Corporation |
| BASF |
| Arkema S.A. |
| Evonik Industries |
| SABIC |
| Syensqo |
| EMS-CHEMIE HOLDINGS AG |
| Mitsubishi Chemical Group Corporation |
| Kuraray Co., Ltd |
| Others |
Cost & Logistics Intelligence
Automotive OEMs in Germany and Japan, with their substantial procurement volumes, drive the market's dominant contract-based long-term offtake pricing model for high performance polyamides.
Pricing Analysis
After-sales technical support and application engineering are often bundled into long-term contracts, differentiating supplier offerings beyond material cost. Pricing stratifies across premium, standard, and economy tiers, influenced by quality grade, such as ISO 10993 certification, and the sheer volume scale of purchase agreements. Pricing softness reflects intense competition and feedstock volatility from European energy costs. Consumer goods manufacturers exhibit the highest price sensitivity, while aerospace and medical device OEMs are least sensitive to material cost fluctuations.
Supply Chain Analysis
REACH compliance and stringent automotive OEM material approvals gate supplier entry, creating a high barrier to participation in the high performance polyamides supply chain. Geographic supply concentrates in Germany, China, and the United States, reflecting major production and consumption hubs. The industry relies heavily on key chemical intermediates like adiponitrile, caprolactam, and dodecanedioic acid. Feedstock price volatility, particularly in Europe due to elevated energy costs, remains a significant structural risk. Distribution runs through direct sales channels, with technical support teams often embedded with OEM engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance polyamides market presents a cost-of-compliance story, where Europe's REACH framework creates a significant barrier-to-entry moat for compliant players.
For Market Incumbents: Deepen R&D into bio-based polyamides to meet evolving sustainability mandates and mitigate feedstock volatility risks. Acquire specialized bio-polymer startups to accelerate portfolio diversification and secure intellectual property. Invest in advanced simulation and engineering capabilities to develop application-specific solutions for electric vehicle thermal management, countering substitution by alternative materials. Leverage integrated Verbund systems for superior cost control and supply chain resilience.
For New Entrants and Emerging Players: Specialized processing techniques for complex geometries offer a technology-first wedge into niche, high-value applications. Target the emerging hydrogen economy components market, including seals and gaskets, and medical device expansion requiring ISO 10993 compliant materials. The electrical and electronics segment in Asia-Pacific represents the most penetrable market for new material innovations. A collaborative application-specific material development approach with OEMs will establish early market traction.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers with deep material science expertise and a long-term view of advanced polymer markets. This market maintains strong growth potential over the next decade, driven by material substitution trends. Target niche players with proprietary bio-based material platforms or specialized processing intellectual property. Increased M&A activity in the bio-polymer segment serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meeting rising automotive and electronics demand requires strategic production increases. |
| Green Manufacturing Transition | Aligning with EU CO2 standards and corporate sustainability goals is critical for market access. |
| Long-term Supply Agreement | Securing stable precursor supply amidst volatility enhances operational resilience for producers. |
| Joint Venture | Co-developing application-specific solutions with OEMs accelerates market adoption and innovation. |
| Technology Licensing | Accelerating market penetration in new application areas leverages existing intellectual property. |
Research Approach
Document review covered company annual reports, industry association publications, and regulatory filings, complemented by interviews with procurement leads at automotive OEMs, R&D directors at chemical companies, and material engineers in electronics. Secondary data sources included EU REACH documentation, US EPA TSCA records, and ISO standards databases. This approach enabled comprehensive bottom-up data collection from production figures and top-down market sizing for triangulation.
Granular market values and volume projections were produced across the analysis window, utilizing a robust analytical framework. The model segmented the market by product type, end-user, application, and regional demand clusters. CAGRs were derived from historical growth trends and future demand drivers, with electric vehicle production forecasts and electronics miniaturization trends serving as critical industry-specific inputs.
Several conditions sit outside the modeled scope, including short-term geopolitical events and unforeseen natural disasters. Forecasts reflect assumptions regarding stable regulatory environments and sustained economic growth, acknowledging that sudden shifts in energy prices or major policy changes could revise projections. A model refresh is warranted upon material change in global trade policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
Chemical Feed Systems Market
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Mecoprop Market
Performance Chemicals
High Performance Epoxy Market
Performance Chemicals
Global High Performance Polymers Market
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
Global Reflective Materials Market