
 Europe Decor Paper Market | 2026-2036
Europe Decor Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Decor Paper Market Foresight
Decor paper engineering talent is rotating from traditional coated-paper mills toward digital press operators and specialty chemistry labs across Central Europe. Koehler Paper leverages its Black Forest manufacturing base to sustain premium-grade output for laminate producers. Ahlstrom-Munksjö anchors Nordic supply chains with integrated pulp-to-paper operations. Schattdecor competes through design-house partnerships that control pattern libraries for flooring OEMs.
Decor paper comprises base papers weighing 60–130 gsm, impregnated with melamine, urea, or acrylic resins to create heat- and scratch-resistant surfaces for laminates and furniture overlays. Manufacturers produce these papers through controlled porosity forming and tailored resin absorption profiles to ensure uniform thermal bonding during hot-press lamination. Woodfree grades dominate volume demand from laminate flooring plants, while specialty papers command margin pools in high-end furniture and architectural surface applications. Digital print technology segments are expanding fastest as short-run customization replaces long-offset campaigns for boutique interior brands.
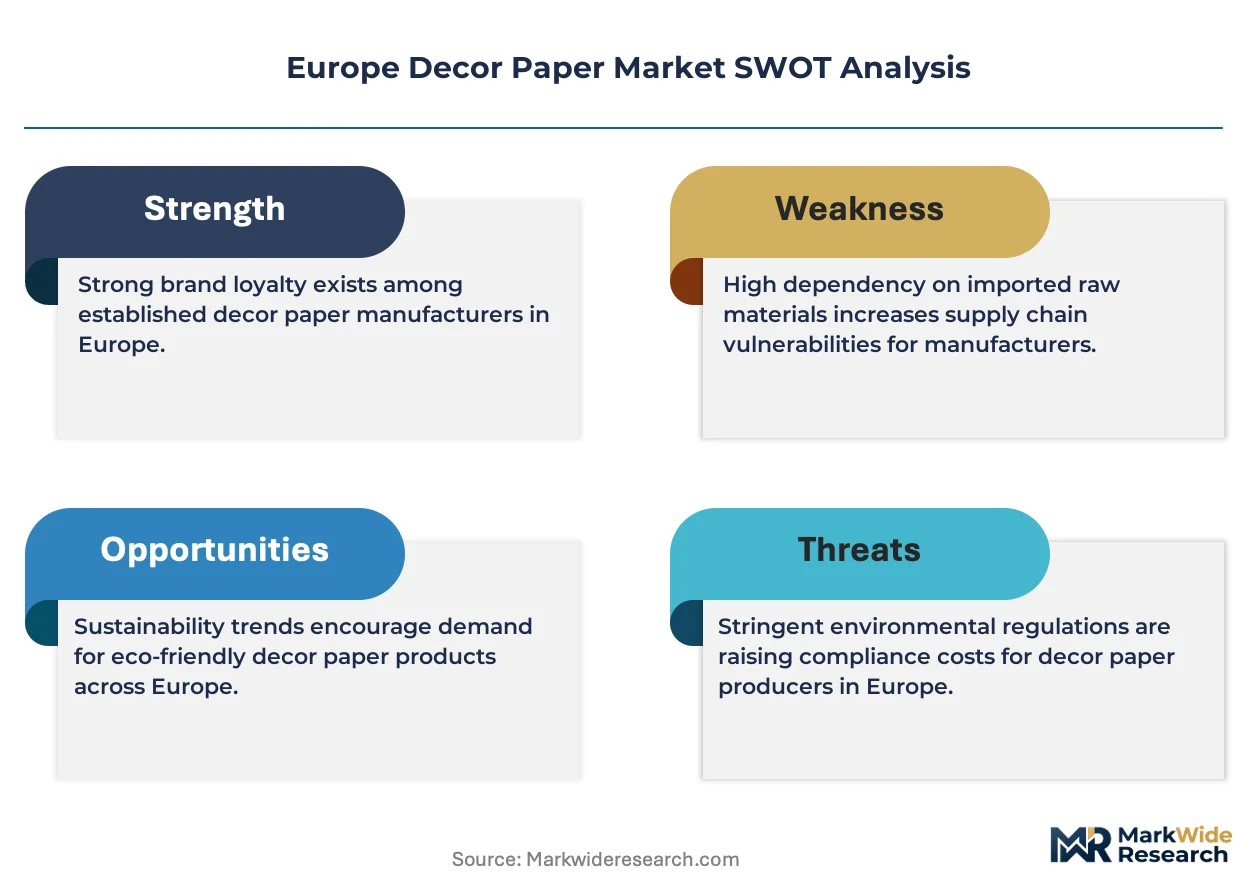
REACH and the EU Green Deal shape chemical compliance burdens across German, Italian, and Spanish mill networks, restricting formaldehyde-based resin systems and mandating recycled content traceability. ECHA substance evaluations now target melamine derivatives used in impregnation baths, forcing reformulation investments. FSC chain-of-custody certification has become a de facto market-access requirement for supply into Scandinavian retail channels. Stakeholders must monitor pending CSRD disclosure rules that will expose Scope 3 paper sourcing emissions across European laminate value chains.
Market Dynamics
Digital printing adoption is fragmenting traditional decor paper procurement cycles across European laminate flooring and furniture clusters, compressing minimum order quantities while multiplying SKU complexity for mill scheduling systems.
Growth Catalysts
- REACH chemical reformulation mandates:ECHA substance evaluations targeting melamine derivatives are accelerating water-based resin adoption, creating upgrade demand across German and Italian impregnation lines.
- Residential renovation intensity:Housing stock refurbishment in Poland and the Czech Republic is pulling decor paper volumes toward laminate flooring OEMs serving Central European retail channels.
- FSC chain-of-custody certification:Scandinavian retail procurement policies now require certified pulp sourcing, locking in premium positioning for compliant Nordic and Baltic mills.
Market Restraints
- Pulp cost volatility:Hardwood and softwood fiber prices fluctuate with Nordic forestry harvest cycles, squeezing margin predictability for non-integrated decor paper producers.
- Resin chemistry lock-in:Existing melamine-impregnation asset bases in Rhineland-Palatinate create technical path dependency that slows water-based system transitions.
- Regional press line concentration:Hot-press capacity clusters in Germany and Austria create geographic demand concentration risk for peripheral mills.
Strategic Opportunities
- CSRD Scope 3 disclosure preparation:Upcoming EU corporate sustainability reporting rules will expose paper sourcing emissions, creating audit and certification service demand across laminate value chains.
- Short-run digital customization:Boutique interior brands in France and Italy are adopting inkjet-printed decor papers for limited-edition surface collections.
- Eastern European capacity expansion:Underpenetrated furniture manufacturing zones in Romania and Bulgaria offer greenfield mill locations with lower energy costs than Western European sites.
Industry Challenges
- Resin formulation chemistry expertise:Water-based acrylic and polyurethane impregnation specialists remain scarce across Central European paper engineering labor pools.
- Hot-press integration complexity: Digital print decor papers require modified thermal bonding profiles, demanding retrofit coordination with legacy laminate press lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Decor Paper Market |
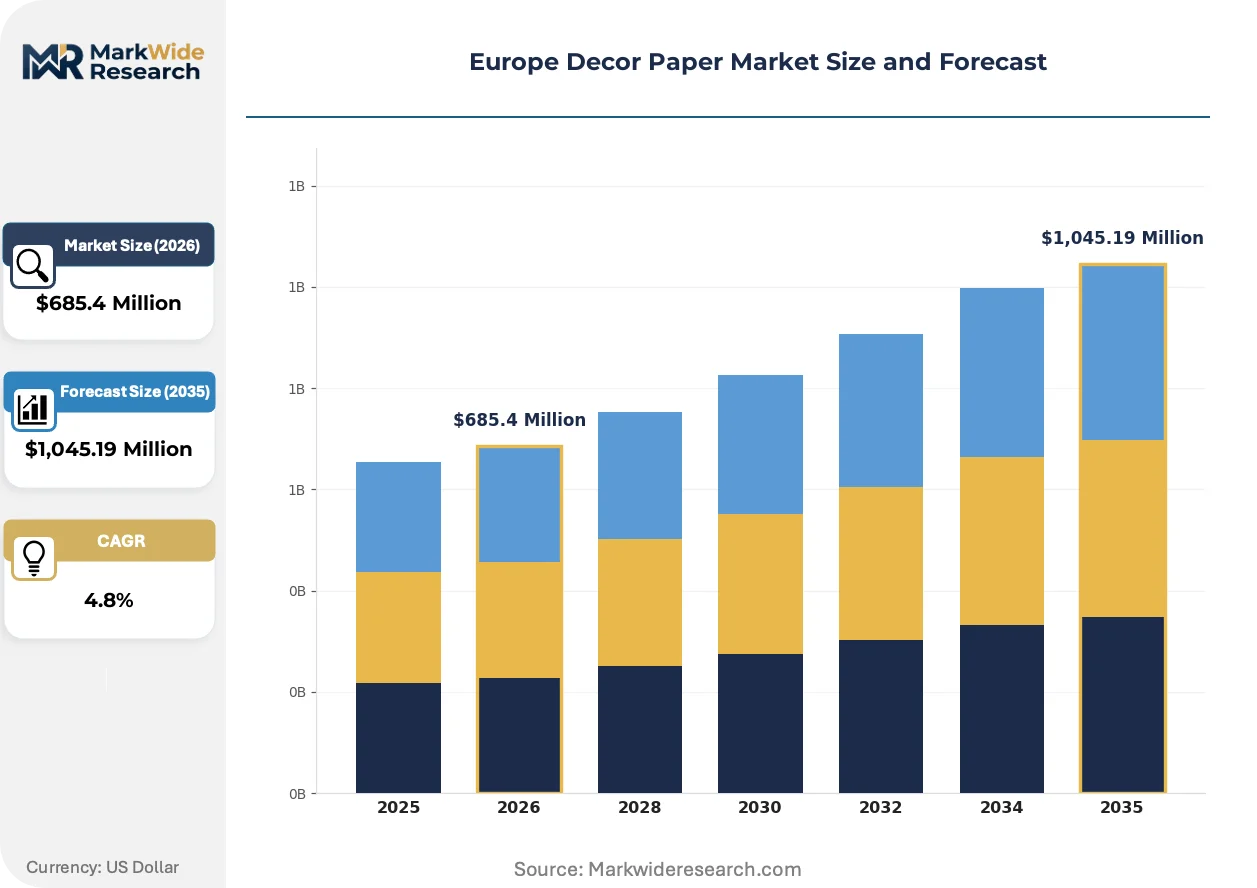
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Woodfree, Coated, Uncoated, Specialty End Use: Packaging, Stationery, Wallpaper, Crafting Thickness: Thin, Medium, Heavy, Extra Heavy Print Technology: Flexography, Offset, Digital, Screen |
| Companies Covered | Surteco Group, Koehler Paper, Ahlstrom-Munksjö, Neodécortech, Impress Surfaces, Felix Schoeller Group, Interprint, Lamigraf, Schattdecor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Decor Paper Market Shifts & Advancements
Surface customization requirements are compressing production batch sizes across European decor paper mills, forcing capital redeployment toward modular digital assets and away from long-run offset cylinders.
Water-based inkjet printing systems are bifurcating the decor paper market between high-volume offset laminate producers and agile digital specialists serving furniture OEMs. Flooring manufacturers in Germany and Poland are piloting inkjet lines for wood-grain pattern libraries, enabling rapid style rotation without cylinder engraving lead times. This technology compression is eroding the traditional volume-moat advantage of established offset mills while fragmenting design ownership toward brand-side creative teams.
EU Green Deal chemical footprint requirements are restricting formaldehyde-based resin systems across Italian and Spanish mill networks. ECHA substance evaluations now target melamine derivatives in impregnation baths, forcing reformulation investments before 2027 compliance deadlines. Decorative surface producers serving Scandinavian retail channels are responding with accelerated FSC certification timelines and pilot acrylic resin trials.
Buyer concentration among pan-European laminate flooring groups is consolidating procurement decisions toward centralized technical specifications. Regional distributors in France and Benelux are losing specification influence as direct mill-OEM relationships tighten around volume commitments and joint design development programs. This channel compression is most visible in Germany's North Rhine-Westphalia furniture cluster, where major press line operators now negotiate resin-absorption profiles directly with Black Forest and Nordic paper engineers.
Europe Decor Paper Market Segmentation
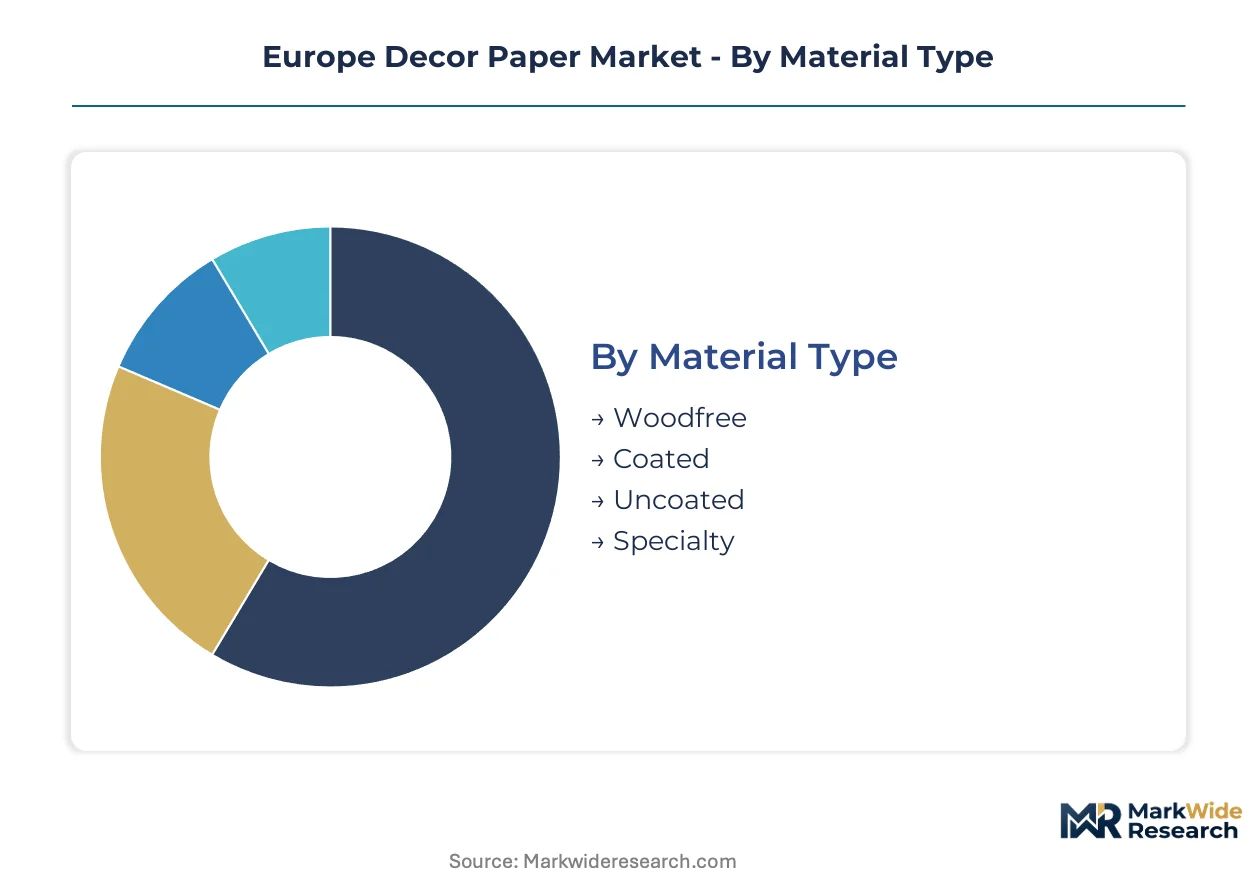
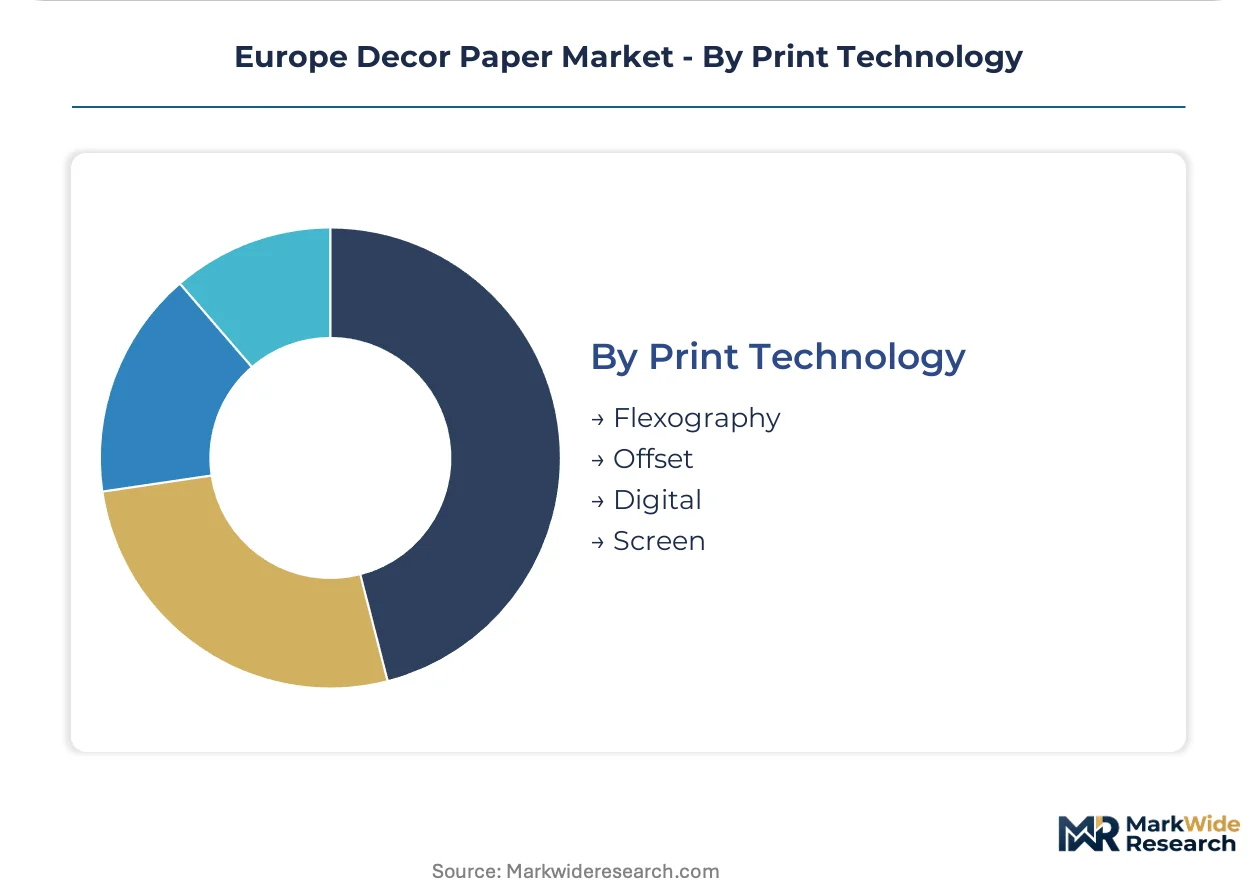
Material composition and print technology choices determine resin absorption profiles and thermal bonding performance across European laminate flooring and furniture applications. Procurement specifications increasingly tie segment selection to REACH compliance timelines and FSC certification requirements.
Material Type:
Substitution pressure from digital-ready substrates is fragmenting traditional woodfree dominance as mills reformulate for water-based ink compatibility.
- Woodfree:Alpha-cellulose base papers with controlled porosity deliver uniform melamine resin saturation for high-pressure laminate flooring. German and Polish laminate OEMs concentrate procurement here due to established hot-press calibration profiles and predictable thermal bonding behavior.
- Coated:Surface-sized formulations with mineral pigments enable sharper offset print reproduction for premium furniture overlays. Scandinavian retail channels pull coated volumes toward FSC-certified Nordic mills serving architectural surface specifications.
- Uncoated:Raw stock grades absorb higher resin loads for economy laminate applications.
- Specialty:Acrylic-impregnated papers target heat-resistant commercial surface segments.
Woodfree retains volume leadership; Specialty holds the steepest expansion curve.
End Use:
Cost tier stratification separates commodity laminate flooring from margin-rich architectural and boutique furniture applications.
- Packaging:Decorative linerboard for premium consumer goods cases requires moisture-resistant resin barriers and scratch-resistant surface treatments. French and Italian luxury packaging houses source small-batch decor papers with custom embossed textures.
- Stationery:High-end notebook covers and desk accessories utilize decor paper overlays for tactile surface differentiation. German stationery distributors specify FSC chain-of-custody documentation for corporate gift channel compliance.
- Wallpaper:Vinyl-compatible decor paper backings serve residential and commercial wallcovering segments.
- Crafting:Scrapbooking and hobbyist applications drive short-run digital print demand.
Packaging commands premium pricing; Crafting gains share fastest through digital enablement.
Thickness:
Application-specific caliper requirements dictate press line compatibility and resin saturation economics across Central European manufacturing clusters.
- Thin:60–80 gsm stocks optimize resin efficiency for economy laminate flooring where cost-per-square-meter drives procurement. Czech and Polish flooring plants specify thin grades for residential renovation volume plays.
- Medium:80–110 gsm papers balance durability and material cost for standard furniture overlays. Austrian press line operators prefer medium calipers for multi-layer lamination stability.
- Heavy:110–130 gsm constructions absorb higher resin loads for commercial-grade wear resistance.
- Extra Heavy:Above-130 gsm specialty grades target architectural panel and countertop segments.
Medium calipers dominate procurement volume; Extra Heavy climbs the fastest on commercial surface demand.
Print Technology:
Customer type fragmentation—mass laminate producers versus boutique furniture OEMs—drives diverging technology investments across mill networks.
- Flexography:Rotary letterpress systems with photopolymer plates enable mid-volume production of wood-grain and stone-pattern decor papers. Italian mills deploy flexography for furniture OEMs requiring rapid design rotation without cylinder engraving capital.
- Offset:Long-run gravure and lithographic systems sustain cost leadership for high-volume laminate flooring producers. German Black Forest mills anchor offset capacity for Rhineland-Palatinate press line clusters.
- Digital:Inkjet systems compress minimum order quantities for limited-edition surface collections.
- Screen:Stencil-based methods serve thick-ink specialty textures and metallic effects.
Offset maintains volume leadership; Digital posts the steepest expansion trajectory on customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laminate flooring OEMs consume decor paper at higher resin-saturation grades than Polish furniture manufacturers, who prioritize thinner calipers for cost-sensitive residential renovation cycles. This consumption-mix differential fragments procurement specifications across Central European press line clusters.
Germany
Rhineland-Palatinate and North Rhine-Westphalia press line operators drive demand for medium-to-heavy caliper woodfree grades with established melamine absorption profiles. ECHA substance evaluations under REACH now target formaldehyde-based resin systems, forcing Black Forest mills toward water-based acrylic reformulations. Koehler Paper anchors premium-grade output from its Black Forest manufacturing base for direct OEM supply relationships.
Poland
Residential renovation intensity in Warsaw and Kraków metropolitan zones pulls thin-grade decor paper volumes toward laminate flooring plants serving Central European retail channels. The country's national environmental regulator enforces EU Green Deal chemical footprint requirements through accelerated compliance timelines for imported resin systems. Łódź furniture clusters concentrate procurement decisions around FSC-certified Nordic supply chains.
Italy
Furniture OEMs in Lombardy and Veneto specify coated decor papers for premium architectural surface applications with sharp offset reproduction requirements. ANSM chemical safety evaluations align with ECHA melamine derivative restrictions, pushing mills toward pilot polyurethane impregnation trials. Milan design houses fragment SKU complexity through boutique short-run digital print collections.
Spain
Economy laminate producers in Catalonia and Valencia absorb uncoated raw stock grades for cost-tier flooring serving Southern European renovation markets. The country's national environmental agency implements REACH-compliant water-based ink mandates ahead of 2027 deadlines. Barcelona press line operators negotiate resin-absorption profiles directly with regional paper engineers.
France
Luxury packaging houses in Paris and Lyon source small-batch decor papers with custom embossed textures for premium consumer goods cases. CNIL data governance frameworks intersect with CSRD disclosure preparation for Scope 3 paper sourcing emissions. Île-de-France creative agencies control pattern libraries for limited-edition inkjet-printed surface collections.
Europe Decor Paper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pulp-to-paper operations commanding premium positioning through FSC chain-of-custody certification. The vendor base separates between scale-driven offset producers serving high-volume laminate OEMs and agile digital specialists capturing boutique furniture customization. Three archetypes dominate: integrated Nordic mills with captive fiber supply, German Black Forest premium-grade specialists, and Italian design-house partners controlling pattern libraries. Competitive moves concentrate on water-based resin reformulation investments and direct mill-OEM technical specification partnerships.
Within the integrated mill tier, Ahlstrom-Munksjö and Koehler Paper exemplify divergent geographic anchoring strategies. Ahlstrom-Munksjö occupies a position representing Nordic pulp-to-paper integration with chain-of-custody certification depth. Koehler Paper exemplifies the Black Forest premium-grade specialist archetype, leveraging regional manufacturing concentration for Rhineland-Palatinate press line supply. Schattdecor sits within the design-control tier, representing pattern library ownership models that displace traditional distributor influence.
| Leading Market Players |
|---|
| Surteco Group |
| Koehler Paper |
| Ahlstrom-Munksjö |
| Neodécortech |
| Impress Surfaces |
| Felix Schoeller Group |
| Interprint |
| Lamigraf |
| Schattdecor |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Black Forest mills and Rhineland-Palatinate laminate OEMs lock in resin-grade specifications while buffering Nordic pulp cost swings. These agreements concentrate procurement power among integrated producers holding FSC chain-of-custody certification, squeezing spot-market flexibility for peripheral mills.
Pricing Analysis
Contract-based long-term offtake structures dominate volume procurement, with price differentiation driven by FSC certification tier and resin absorption grade. Premium woodfree grades command positioning through established hot-press calibration profiles, while economy uncoated stocks face cost compression from thin-grade substitution in Polish renovation markets. Flooring OEMs exhibit highest price sensitivity on resin-saturated volumes, whereas Milan design houses tolerate premium spreads for short-run digital customization.
Supply Chain Analysis
Nordic hardwood pulp supply from Sweden and Finland anchors European decor paper production, with German Black Forest and Italian Lombardy mills drawing from these fiber streams. Melamine resin chemistry, water-based ink formulations, and FSC-certified pulp constitute critical input dependencies. Single-source vulnerability concentrates in Nordic pulp-to-paper integration, where harvest cycle disruptions ripple through laminate flooring supply chains. Distribution runs through direct mill-OEM technical partnerships, displacing traditional French and Benelux distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's decor paper market sits in early-cycle expansion as digital printing adoption penetrates boutique furniture segments previously locked into long-run offset economics. Residential renovation intensity across Central Europe sustains volume pull through laminate flooring OEMs.
For Market Incumbents: Consolidate resin formulation expertise through captive water-based chemistry labs, defending against design-house disintermediation of pattern library control. Secure FSC certification depth ahead of CSRD Scope 3 disclosure mandates. Anchor capacity in Rhineland-Palatinate press line clusters to tighten direct OEM specification relationships. For New Entrants and Emerging Players: Differentiate on digital print agility for limited-edition surface collections targeting Milan and Paris boutique interior brands. Penetrate Romanian and Bulgarian furniture manufacturing zones where greenfield mill economics undercut Western European energy costs. Pursue pilot partnerships with Scandinavian retail channels demanding certified pulp traceability. For Investors and Strategic Acquirers: Capital is best deployed toward integrated Nordic mills with captive fiber supply and established chain-of-custody certification. Long-term viability over a five-to-ten-year window hinges on water-based resin transition completion and digital asset modularization. Monitor ECHA substance evaluation timelines as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Resin Reformulation | REACH compliance deadlines force melamine-to-acrylic transitions across German and Italian impregnation lines. |
| Digital Print Asset Deployment | Inkjet modularization captures boutique furniture customization demand fragmenting from offset volume moats. |
| FSC Certification Acceleration | Chain-of-custody documentation becomes market-access gate for Scandinavian retail procurement channels. |
| Direct Mill-OEM Partnership | Technical specification integration with Rhineland-Palatinate press operators displaces distributor influence. |
| Eastern European Capacity Expansion | Romania and Bulgaria offer greenfield locations with lower energy costs than Western European mill sites. |
Research Methodology
The analysis maps woodfree, coated, uncoated, and specialty material sub-sectors, each validated through procurement directors at laminate flooring OEMs, technical directors at impregnation line operators, sustainability officers at retail channels, and design leads at furniture houses. Primary interview findings triangulate against secondary sources including ECHA substance evaluation databases, EU Green Deal implementation timelines, FSC chain-of-custody registries, and customs trade flows for decor paper grades. Bottom-up volume modeling reconciles with top-down market sizing across material type, end use, thickness, and print technology dimensions.
Consistency checks validate volume and value outputs against Nordic pulp production statistics, regional press line capacity utilization surveys, and laminate flooring installation rate indices. The analytical framework segments by material composition, print technology adoption curve, resin chemistry transition stage, and geographic manufacturing cluster across the projection horizon. CAGRs derive from regression analysis of historical procurement volumes correlated with residential renovation cycle intensity and regulatory compliance investment schedules. Modeled inputs include digital press line installation rates and water-based resin formulation penetration curves.
The analysis sits within stated boundaries; outcomes outside current REACH enforcement trajectories and EU Green Deal chemical footprint timelines would require recalibration. Forecasts reflect assumptions about ECHA substance evaluation completion, FSC certification adoption rates, and Nordic forestry harvest stability. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and digital print technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Duplex Paper and Board Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Softwood Pulp Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Europe Coated Paper Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Glassine Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Paper Machine Systems Market
Paper Products
Digital Printing Paper Market
Paper Products
Aramid Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
Fluff Pulp Market