
 Insulation Paper Market | 2026-2036
Insulation Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Paper Market Foresight
REACH compliance is expanding the cost-of-entry calculus for insulation paper suppliers seeking European market access. DuPont leverages its materials science heritage to sustain premium positioning in high-voltage electrical grades. Weidmann Electrical Technology anchors transformer supply chains through captive pulp sourcing and specialized calendering expertise. Nitto Denko competes in thin-film electrical insulation with precision coating capabilities.
Insulation paper is a dielectric material manufactured from refined cellulose pulp, synthetic fibers, or hybrid blends, typically calendered to precise thickness tolerances between 0.05 mm and 0.50 mm to achieve controlled porosity and oil absorption for electrical and thermal barrier applications. Electrical insulation grades dominate volume consumption in power transformers and rotating machinery, where oil-impregnated cellulose structures manage dielectric stress across winding layers. Thermal insulation applications in building envelopes and industrial equipment represent a mature, price-sensitive segment where fiberglass-reinforced papers compete with foam alternatives. Acoustic insulation demand concentrates in automotive NVH packages, where lightweight, multi-layer paper composites displace heavier mat solutions in electric vehicle architectures.
EMA's MDR framework and EPA chemical safety reviews shape material substitution timelines across medical and industrial insulation applications, pressuring suppliers to validate bio-based alternatives. China's GB standards and India's BIS certification requirements create parallel compliance tracks for exporters serving Asia-Pacific grid expansion programs. Stakeholders must calibrate R&D portfolios against diverging regional toxicity thresholds and recyclability mandates rather than optimizing for a single global specification.
Market Dynamics
Asia-Pacific power transformer demand is compressing supply chains as utilities in India and China execute grid modernization programs under stricter fire-safety mandates. Cellulose-based insulation formulations are capturing share from synthetic alternatives as procurement specifications harden around bio-based dielectric performance.
Growth Catalysts
- India's PLI scheme for electrical equipment:Domestic manufacturing incentives accelerate captive insulation paper capacity expansion for transformer OEMs serving renewable integration projects.
- REACH chemical restrictions:European ECHA substance evaluations are redirecting formulation R&D toward halogen-free cellulose derivatives that maintain dielectric strength.
- Ultra-high voltage transmission buildouts:China State Grid's 800kV+ line investments require specialized oil-impregnated paper grades with enhanced thermal cycling endurance.
Market Restraints
- Pulp input cost volatility:Dissolving wood pulp prices fluctuate with Nordic forestry harvest cycles and energy-intensive chemical processing costs.
- Calendering equipment concentration:Precision thickness control machinery is concentrated among German and Swiss specialist engineering firms, creating procurement bottlenecks.
- Aramid paper substitution:Nomex and similar meta-aramid structures penetrate aerospace and premium motor applications where temperature ratings exceed 220°C.
Strategic Opportunities
- Indonesia's archipelago grid extension:PLN's rural electrification program creates demand for compact distribution transformers using lightweight insulation systems.
- Recyclability mandates:EU Green Deal circular economy requirements favor single-material cellulose constructions over multi-layer synthetic composites in end-of-life processing.
- Digital twin integration:Dielectric monitoring sensors embedded in transformer windings require insulation papers with controlled porosity for oil permeability and sensor compatibility.
Industry Challenges
- Specialized papermaking expertise:Few technicians possess combined knowledge of cellulose chemistry, calendering mechanics, and electrical testing protocols.
- Dual certification timelines:Simultaneous GB standard validation for China and IEC compliance for export markets extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Paper Market |
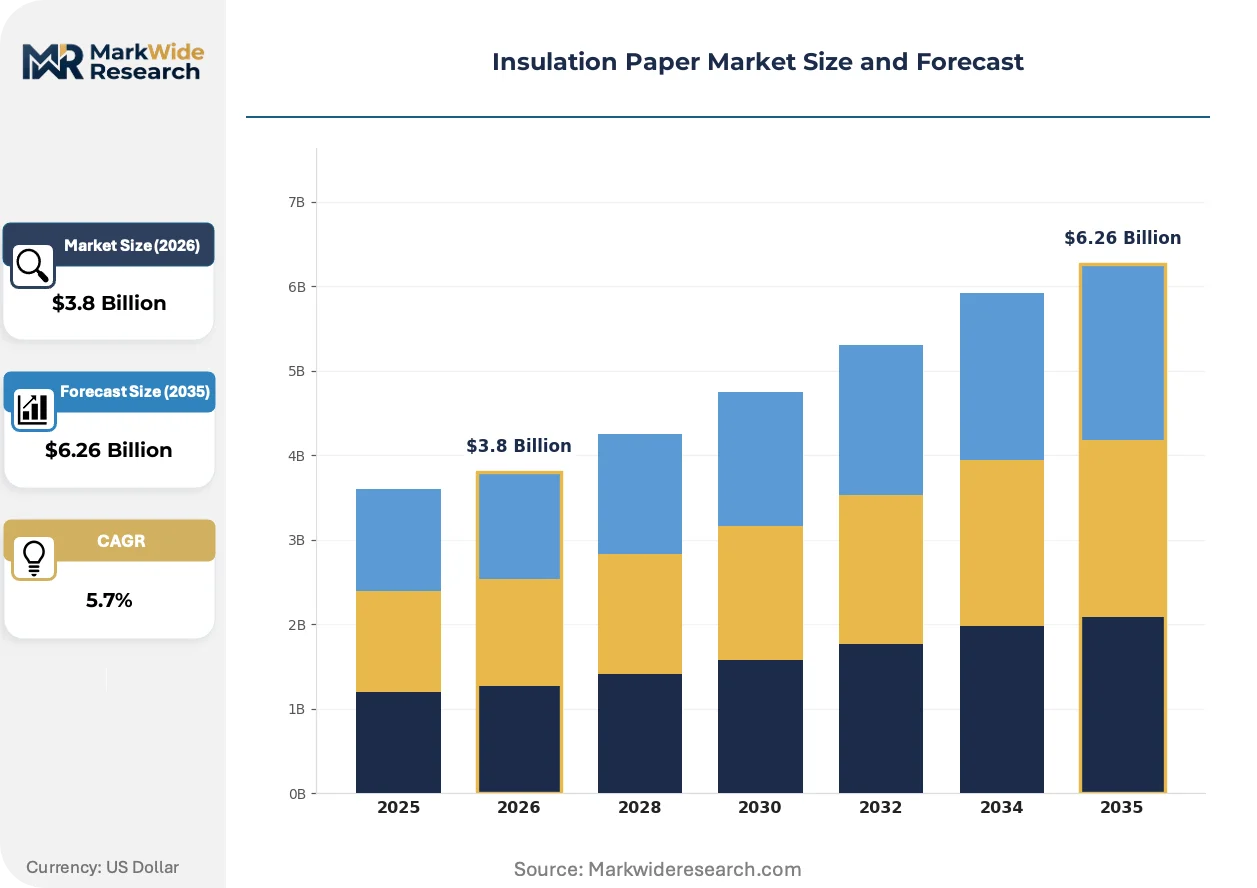
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Insulation, Electrical Insulation, Acoustic Insulation, Fire-resistant Insulation Material: Pulp, Polyester, Cellulose, Fiberglass Application: Building, Automotive, Aerospace, Electronics End User: Manufacturers, Contractors, Architects, Homeowners |
| Companies Covered | DuPont, Weidmann Electrical Technology, 3M, Nitto Denko, Von Roll, Delfort, Yantai Metastar Special Paper, Ahlstrom, Cottrell Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Paper Market Shifts & Advancements
Material science convergence with electrical engineering is redefining performance benchmarks across transformer and rotating machinery applications. Three developments are compressing traditional supply relationships and opening new specification categories.
Nanocellulose-reinforced insulation papers are overtaking conventional kraft grades in high-stress winding applications. These fibrillated structures deliver 15-40% improved dielectric breakdown strength while maintaining oil absorption kinetics. European transformer OEMs are qualifying nanocellulose hybrids for 400kV+ applications where reduced insulation thickness enables compact core designs. The technology is compressing demand for mica-based composites in premium motor segments.
REACH authorization procedures for persistent organic pollutants are forcing reformulation of synthetic binder systems used in hybrid insulation papers. ECHA's 2023-2025 substance evaluation roadmap targets chlorinated flame retardants and certain phthalate plasticizers common in electrical grades. Suppliers serving medical device and food-contact adjacent applications face the most compressed substitution timelines as downstream customers demand pre-certified material streams.
Long-term service contracts with integrated material lifecycle management are displacing spot purchasing in utility procurement. State-owned grid operators in China and India now specify 25-40 year transformer operational life with guaranteed insulation performance, shifting risk to paper suppliers. This restructuring concentrates contract awards among vertically integrated manufacturers with in-house pulp-to-finished-paper capabilities and established field service networks.
Insulation Paper Market Segmentation
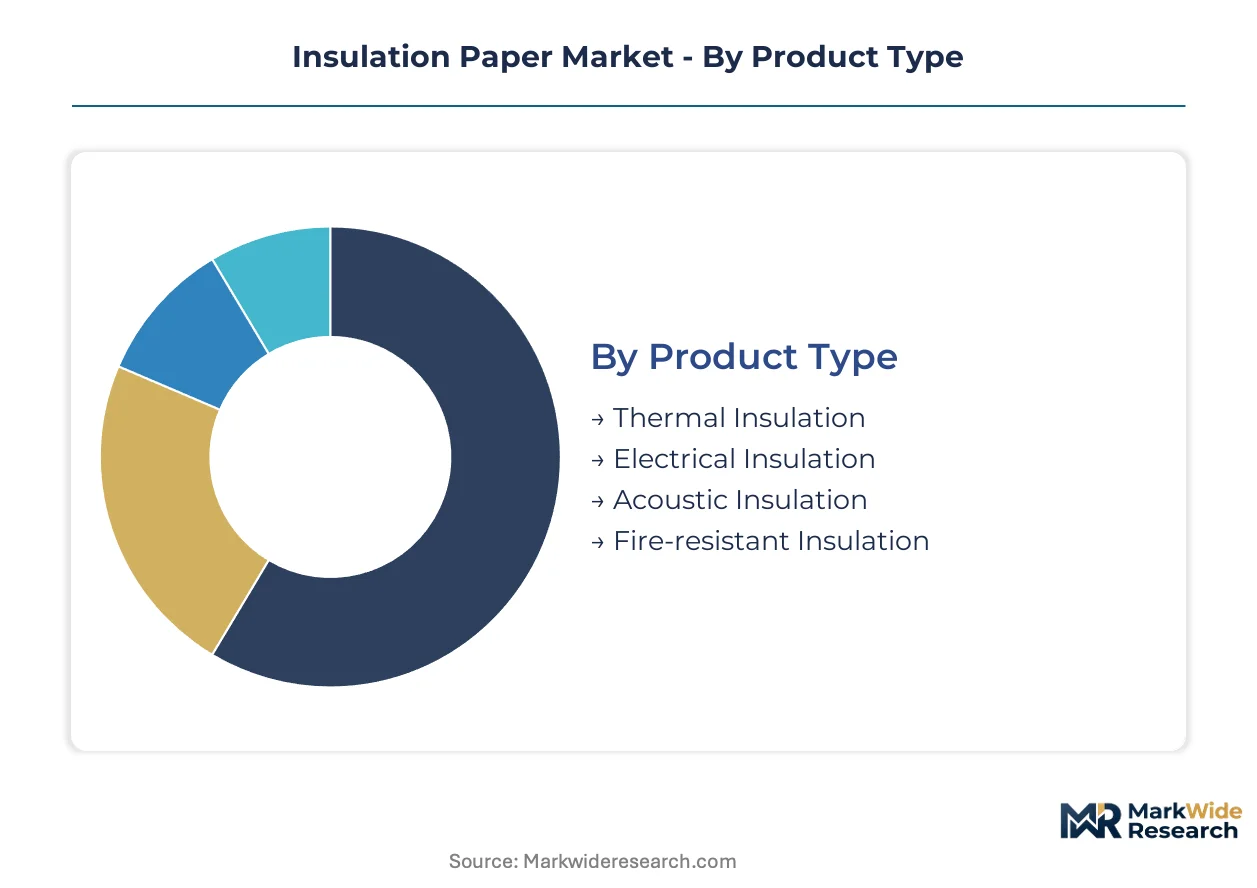
Segmentation in insulation paper markets tracks divergent technical specifications across electrical and thermal applications. Procurement patterns split between utilities demanding 40-year transformer life guarantees and construction contractors prioritizing code-compliant R-value performance at lowest installed cost.
Product Type:
Transformer OEMs and building contractors select product types based on dielectric stress tolerance versus thermal resistance requirements, with regulatory fire-safety mandates compressing substitution timelines.
- Electrical Insulation:Oil-impregnated cellulose structures calendered to 0.05-0.50 mm thickness manage dielectric stress across power transformer winding layers. State Grid's 800kV+ transmission buildouts in China and India's renewable integration projects under PLI schemes concentrate demand for enhanced thermal cycling endurance grades.
- Thermal Insulation:Fiberglass-reinforced papers and hybrid composites deliver controlled thermal resistance in building envelopes and industrial equipment. EU Green Deal circular economy requirements favor single-material cellulose constructions over multi-layer synthetic composites in European retrofit markets.
- Acoustic Insulation:Lightweight multi-layer paper composites displace heavier mat solutions in electric vehicle NVH packages across automotive platforms.
- Fire-resistant Insulation:Halogen-free formulations meeting ECHA substance evaluations maintain dielectric strength while satisfying REACH chemical restrictions in medical-adjacent applications.
Electrical Insulation leads on scale; Fire-resistant Insulation leads on momentum.
Material:
Raw material selection hinges on pulp cost volatility against synthetic fiber temperature performance, with sustainability credentials increasingly gating European utility procurement.
- Cellulose:Refined kraft pulp delivers controlled porosity and oil absorption kinetics essential for transformer impregnation. Nanocellulose-reinforced hybrids are capturing share in 400kV+ applications where reduced insulation thickness enables compact core designs for European OEMs.
- Pulp:Dissolving wood pulp prices fluctuate with Nordic forestry harvest cycles, compressing margin structures for non-integrated manufacturers serving price-sensitive building markets.
- Polyester:Synthetic fiber grades offer moisture resistance in outdoor electrical applications where cellulose degradation risks exceed tolerance thresholds.
- Fiberglass:Glass fiber reinforcement extends temperature ratings beyond 180°C in industrial thermal barrier applications competing with foam alternatives.
Cellulose dominates volume share; nanocellulose variants are climbing the fastest.
Application:
Application selection tracks voltage class requirements in electrical segments against weight reduction imperatives in mobility sectors.
- Building:Mature demand concentrates in envelope insulation where R-value per dollar drives contractor specification, with EU member states enforcing stricter thermal performance codes in renovation waves.
- Automotive:Electric vehicle architectures prioritize lightweight acoustic and thermal management solutions, with OEMs specifying multi-layer paper composites to offset battery pack mass.
- Aerospace:Meta-aramid structures penetrate segments where temperature ratings exceed 220°C and flame-smoke-toxicity certification gates material selection.
- Electronics:Thin-film electrical insulation with precision coating capabilities serves high-density motor and generator applications in industrial automation.
Building anchors volume consumption; Automotive is gaining share fastest.
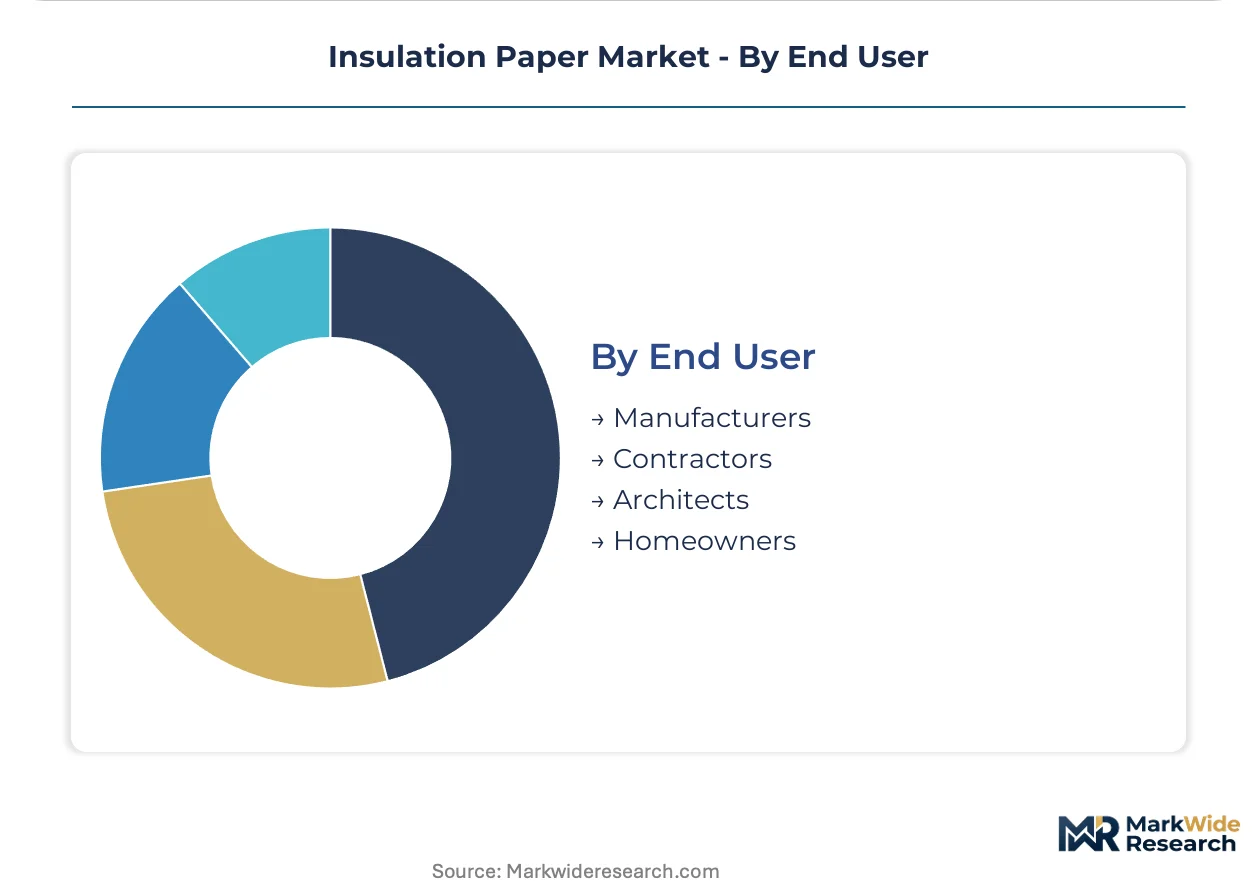
End User:
End-user procurement sophistication varies from integrated transformer OEMs with captive pulp operations to fragmented homeowner retail channels.
- Manufacturers:Vertically integrated transformer OEMs with in-house pulp-to-finished-paper capabilities and field service networks capture long-term service contracts from State Grid and Indian utilities specifying 25-40 year operational life.
- Contractors:Price-sensitive procurement in building thermal insulation segments favors distributors stocking standardized R-value grades with rapid availability.
- Architects:Specification influence concentrates in premium commercial and institutional projects where fire-safety certification and sustainability credentials drive material selection.
- Homeowners:Retail channel demand tracks DIY renovation cycles and energy rebate program availability in residential markets.
Manufacturers lead on contract value; Contractors lead on transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp-to-paper technical specialists concentrate in Nordic forestry regions and German industrial corridors, anchoring supply-side capability for transformer-grade insulation manufacturing.
China
State Grid's 800kV+ ultra-high voltage transmission buildouts drive specialized oil-impregnated paper demand. GB standards certification creates parallel compliance tracks for domestic and export markets. Transformer manufacturing clusters in Shenyang and Xi'an absorb enhanced thermal cycling endurance grades from regional suppliers.
Germany
Precision calendering equipment engineering from Swiss and German specialist firms creates procurement bottlenecks for thickness-controlled paper. REACH chemical restrictions redirect formulation R&D toward halogen-free cellulose derivatives. Industrial automation corridors in Baden-Württemberg host transformer OEMs qualifying nanocellulose hybrids for compact core designs.
India
PLI scheme incentives for electrical equipment accelerate captive insulation paper capacity expansion for transformer OEMs. BIS certification requirements create compliance tracks for renewable integration projects. Manufacturing corridors in Gujarat and Maharashtra concentrate domestic winding material production for grid modernization programs.
United States
EPA chemical safety reviews shape material substitution timelines for industrial insulation applications. FERC grid reliability standards compress transformer replacement cycles in aging infrastructure zones. Great Lakes pulp processing regions supply refined kraft grades for domestic electrical insulation demand.
Japan
METI energy efficiency mandates drive demand for compact distribution transformers using lightweight insulation systems. JIS standards govern dielectric performance specifications for high-density motor applications. Precision coating capabilities in Kansai industrial zones serve thin-film electrical insulation for automotive and electronics segments.
Insulation Paper Market Competitive Landscape
The competitive structure tilts toward vertically integrated pulp-to-paper manufacturers with captive forestry resources and in-house calendering capabilities. Three archetypes dominate: Nordic pulp-integrated specialists controlling raw material cost structures, Asian scale players serving domestic grid expansion programs, and precision coating technologists targeting thin-film electrical segments. Capacity expansion and strategic partnerships with transformer OEMs represent the dominant competitive moves as long-term service contracts displace spot purchasing.
Among heritage materials science conglomerates, DuPont exemplifies premium-tier positioning through materials science heritage in high-voltage electrical grades. Weidmann Electrical Technology occupies a position among European-integrated specialists with captive pulp sourcing and specialized calendering expertise. Nitto Denko represents precision coating capability in thin-film electrical insulation segments. These three anchors illustrate divergent strategic postures across the value chain.
| Leading Market Players |
|---|
| DuPont |
| Weidmann Electrical Technology |
| 3M |
| Nitto Denko |
| Von Roll |
| Delfort |
| Yantai Metastar Special Paper |
| Ahlstrom |
| Cottrell Paper Company |
| Others |
Supply & Pricing Matrix
Specialized papermaking technicians concentrated in Nordic forestry regions and German industrial corridors command wage premiums that compress margin structures for non-integrated manufacturers, widening spreads between premium transformer-grade insulation and economy thermal barrier products.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes contract structures in this market. Long-term service contracts with guaranteed 25-40 year insulation performance bundle material supply with field monitoring and replacement warranties, commanding substantial premiums over spot-transactional procurement in building thermal segments. Price differentiation hinges on certification tier—GB standard validation for China versus IEC compliance for export markets—and captive pulp integration. Pricing pressure stems from dissolving wood pulp cost volatility tied to Nordic forestry harvest cycles, compressing margins for non-integrated suppliers. Transformer OEMs with in-house pulp-to-paper capabilities exhibit lowest price sensitivity; fragmented construction contractors in building retrofit markets exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from State Grid and Indian utilities mandate multi-supplier qualification for critical winding materials, forcing transformer OEMs to maintain relationships with at least two qualified insulation paper manufacturers per voltage class. Geographic supply concentration centers on Sweden, Finland, and Germany for refined kraft pulp and precision calendering equipment; China and India for domestic transformer-grade production. Raw material dependencies draw from dissolving wood pulp, specialized chemical additives for oil-impregnation compatibility, and precision-engineered calendering rolls. Single-source vulnerability concentrates in German and Swiss specialist engineering firms controlling thickness-control machinery. Distribution runs through direct long-term contracts to integrated transformer OEMs and industrial distributors serving fragmented building markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
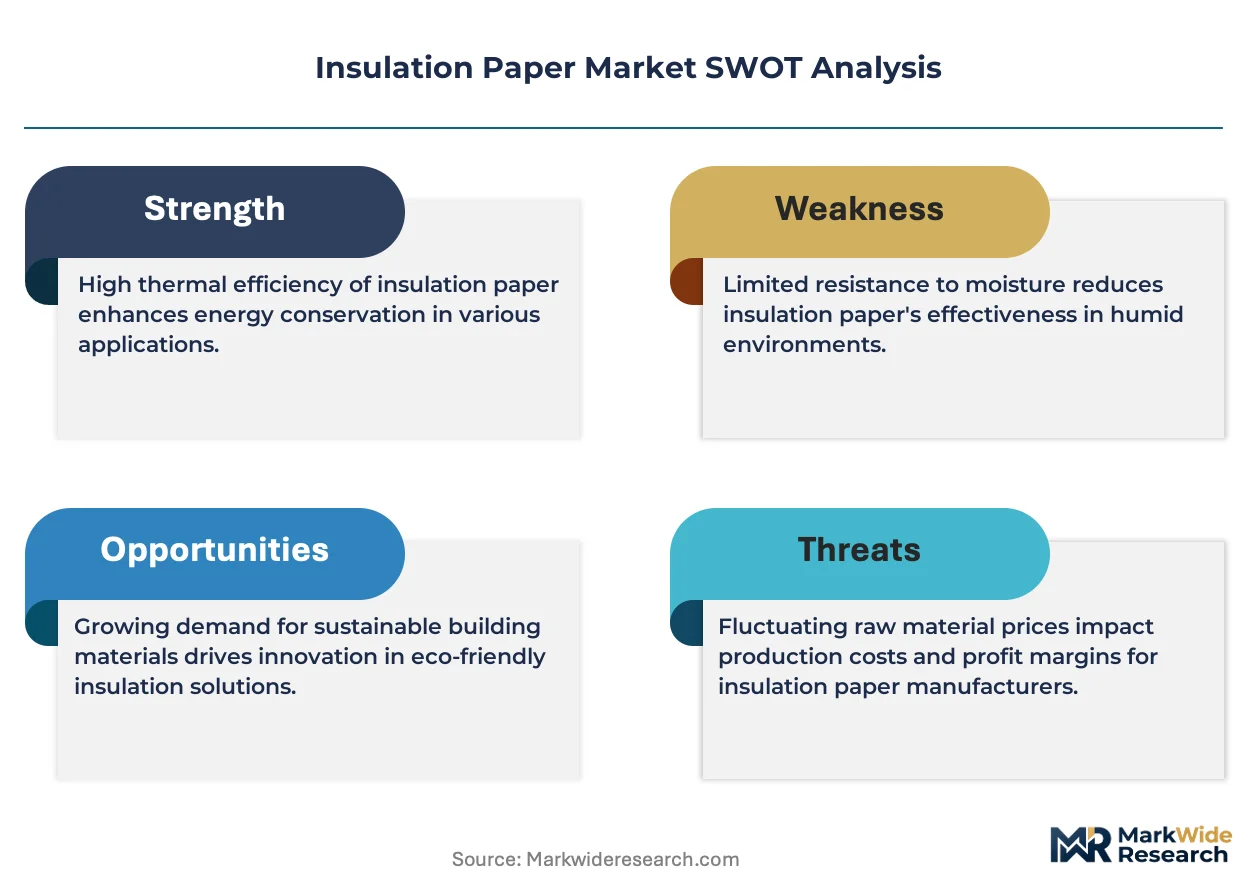
This market offers margin-expansion potential through nanocellulose hybrid adoption, where European OEMs pay premiums for reduced insulation thickness enabling compact core designs.
For Market Incumbents: Deploy captive pulp sourcing as the defensive anchor. Weidmann Electrical Technology and Nordic-integrated specialists should expand calendering capacity in Germany to capture State Grid and Indian utility contracts specifying enhanced thermal cycling endurance. Simultaneously, accelerate REACH-compliant halogen-free formulation R&D to preempt ECHA substance evaluation deadlines. Aramid paper substitution in aerospace and premium motor segments above 220°C ratings threatens cellulose share; defend through nanocellulose qualification in 400kV+ applications. For New Entrants and Emerging Players: Launch via technical partnership with precision calendering equipment suppliers rather than capital-intensive greenfield mills. Indonesia's archipelago grid extension under PLN's rural electrification program presents the most penetrable geography, with demand for compact distribution transformers using lightweight insulation systems underserved by established Asian scale players. Target thin-film electrical insulation for automotive NVH and electronics segments where Nitto Denko's precision coating capabilities demonstrate viable entry archetypes. For Investors and Strategic Acquirers: Transformer OEMs with captive insulation paper operations are the most active acquirer in this space, seeking to secure supply certainty for 25-40 year service contracts. Long-term viability over a 5-10 year horizon rests on vertical integration depth and field service network reach. Acquisition target archetype: mid-cap European specialists with GB standard certification and established relationships with Shenyang or Xi'an transformer clusters. Watch nanocellulose qualification timelines at 400kV+ as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive kraft pulp production insulates Weidmann and Nordic specialists from Nordic forestry harvest cycle volatility. |
| REACH-Compliant Formulation Transition | Halogen-free cellulose derivatives preempt ECHA 2023-2025 substance evaluation deadlines for chlorinated flame retardants. |
| Long-Term Service Contract Expansion | 25-40 year operational life guarantees with State Grid and Indian utilities shift performance risk to paper suppliers. |
| Nanocellulose Hybrid Qualification | 15-40% improved dielectric breakdown strength captures 400kV+ compact core designs from European transformer OEMs. |
| Precision Calendering Capacity Addition | German and Swiss equipment engineering bottlenecks create procurement leverage for integrated manufacturers with in-house capability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged transformer OEM procurement directors, utility planning officers at State Grid and Indian state electricity boards, pulp mill operations managers in Sweden and Finland, and precision calendering equipment engineers in Germany and Switzerland. Secondary validation drew from IEC and GB standard documentation, ECHA substance evaluation roadmaps, SEC filings of listed materials companies, and customs trade data for dissolving wood pulp flows. Bottom-up volume modeling across electrical, thermal, acoustic, and fire-resistant insulation grades triangulated against top-down transformer installation forecasts.
Comparable-period anchoring aligned the projection horizon against historical reference periods spanning pre-pandemic baselines, supply disruption intervals, and post-normalization recovery phases. Segmentation dimensions modeled included product type, material composition, application voltage class, and end-user procurement sophistication. CAGRs derived from regression analysis of transformer installation cycles, renewable integration project pipelines, and regulatory compliance timeline compression. Industry-specific forecast inputs incorporated PLI scheme disbursement schedules for Indian electrical equipment manufacturing and China State Grid ultra-high voltage transmission buildout cadence.
Several conditions sit outside the modeled scope, including abrupt pulp input cost spikes from Nordic forestry disease or trade restriction, and accelerated aramid paper substitution in temperature-critical applications. Forecasts reflect assumptions regarding sustained grid modernization investment in India and China, continued REACH enforcement trajectory, and stable calendering equipment supply from German and Swiss engineering specialists. Deviation in ECHA substance evaluation acceleration or China dual carbon policy stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pharma Grade Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Carbonless Paper Market
Paper Products
Filtration Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
NCR Laser Paper Market
Paper Products
Paper Machinery Market
Paper Products
Paper Based Laminates Market
Paper Products
North America Thermal Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Abaca Pulp Market
Paper Products
Digital Printing Paper Market
Paper Products
Uncoated Fine Paper Market