
 Paper Machinery Market | 2026-2036
Paper Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Machinery Market Analytics
Modular rebuild packages are shifting buyer choice away from greenfield investments toward section-by-section upgrades. Valmet leverages its broad service footprint to capture recurring rebuild revenue across aging European and North American installed bases. Voith Group anchors its competitive position through deep vertical integration in hydraulic and control systems for paper machines. Andritz competes aggressively in tissue and board segments with standardized platform designs that reduce engineering lead times.
Paper machinery encompasses the specialized equipment used to convert wood pulp or recycled fiber into finished paper, board, or tissue products, operating at speeds exceeding 2,000 meters per minute on modern linerboard machines and requiring precise control over moisture, caliper, and tensile strength to meet end-use specifications. The equipment serves as the capital backbone of pulp-to-paper conversion across packaging, printing, and hygiene supply chains. Paper making machines represent the mature revenue core where replacement demand and energy-efficiency retrofits sustain steady aftermarket flows. Corrugated machinery occupies the fastest expansion trajectory as e-commerce fulfillment networks require higher-output, quick-change flexo folder-gluer lines. Eco-friendly technologies concentrate emerging margin pools as mills face carbon accounting requirements and seek heat-recovery and closed-loop water systems to comply with tightening effluent standards.
The EU Green Deal and F-Gas Regulation shape equipment specifications by mandating heat pump integration and low-global-warming-potential refrigerants in drying sections, while China's MEE enforces wastewater discharge limits that drive adoption of advanced water treatment modules. ISO 14001 environmental management certification has become a de facto market access requirement for suppliers bidding on mill expansion projects in regulated jurisdictions. Stakeholders must monitor how carbon border adjustment mechanisms reshape the geographic competitiveness of machine sourcing decisions.
Market Dynamics
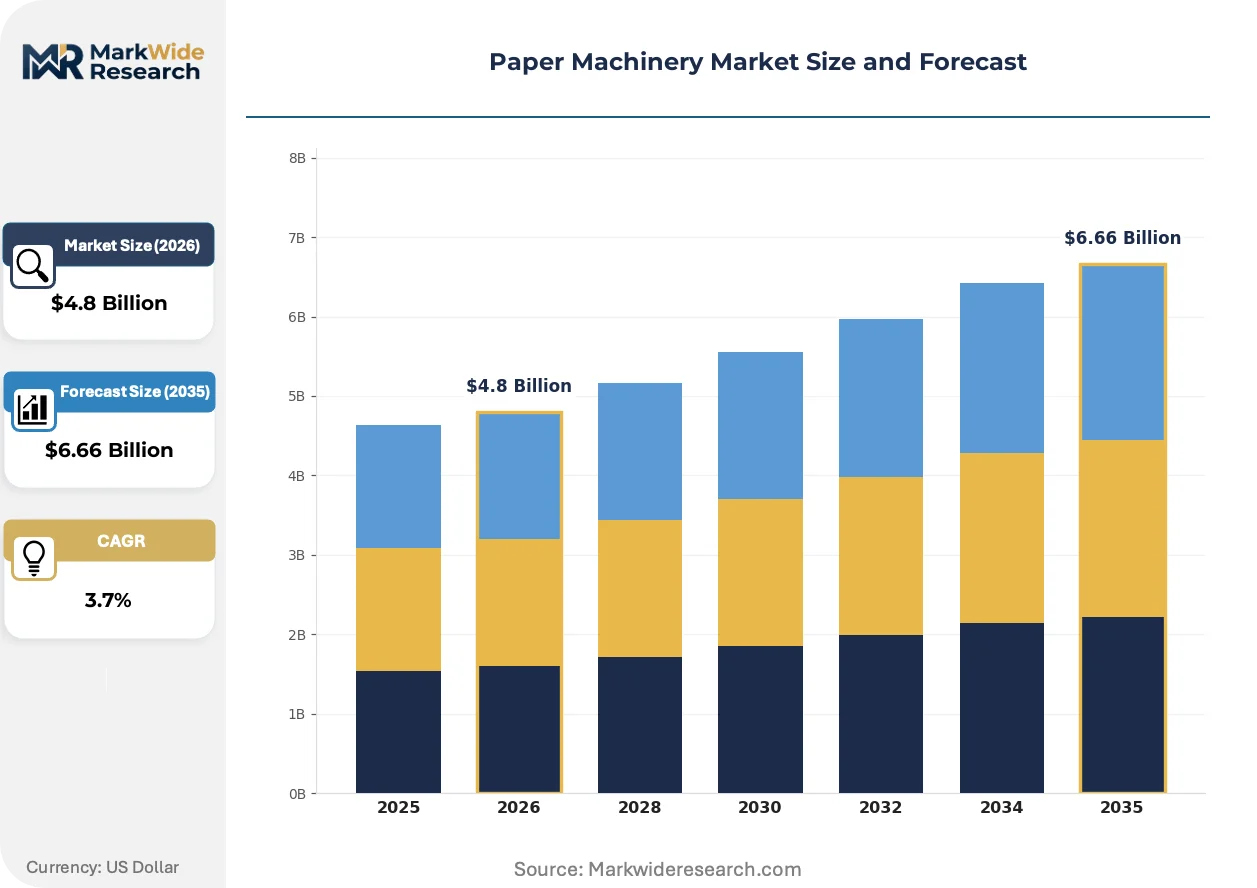
Modular rebuild packages are displacing greenfield capital commitments as mills prioritize section-by-section upgrades over full machine replacements. E-commerce fulfillment networks compress replacement cycles for corrugated converting equipment while carbon accounting mandates force thermal efficiency retrofits.
Growth Catalysts
- EU Ecodesign standards:The F-Gas Regulation and heat pump integration mandates drive energy-efficient drying section rebuilds across European linerboard mills.
- Southeast Asia paperboard capacity:Regional mill expansions in Vietnam and Indonesia concentrate demand for new forming and press sections.
- Closed-loop water systems:China's MEE wastewater discharge limits accelerate adoption of advanced water treatment modules in pulp-to-paper conversion lines.
Market Restraints
- Specialized steel alloy supply:Rolls and dryer cylinders depend on nickel-chromium-molybdenum alloys concentrated in select European and Japanese foundries.
- High-precision hydraulic component lead times:Extended delivery schedules for custom servo-valves and actuators delay machine commissioning.
- Skilled commissioning engineer scarcity:Experienced start-up specialists for high-speed tissue machines command premium contracting rates.
Strategic Opportunities
- India packaging board modernization:Underpenetrated domestic kraft liner capacity creates demand for rebuilt Fourdrinier and gap former installations.
- Heat recovery technology convergence:Organic Rankine cycle systems paired with machine ventilation exhaust capture emerging margin pools.
- Digital twin remote diagnostics:Subscription-based predictive maintenance platforms unbundle traditional service contracts.
Industry Challenges
- Legacy DCS integration complexity:Newer machine sections must interface with decades-old distributed control architectures without full rip-and-replace.
- ISO 14001 certification timelines:Environmental management documentation requirements extend bid-to-award cycles for regulated jurisdiction projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Machinery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Making Machines, Corrugated Machinery, Coating Machines, Finishing Equipment End User: Pulp Mills, Paper Manufacturers, Packaging Companies, Print Service Providers Technology: Automation Solutions, Robotics, Digital Printing, Eco-friendly Technologies Application: Packaging, Printing, Stationery, Tissue Production |
| Companies Covered | Valmet, Voith Group, Andritz, Mitsubishi Heavy Industries, BHS Corrugated, Fosber Group, Metso, Toscotec, Bellmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Machinery Market Evolving Landscape
Machine intelligence and thermal efficiency technologies are compressing operating cost structures while regulatory frameworks rewrite equipment specifications. Three developments are restructuring competitive positioning.
Model-predictive control systems for moisture and caliper profiles are converging with edge computing architectures to enable real-time machine direction adjustments. Board and packaging mills with thin profit margins adopt these systems fastest. The technology is converging with legacy quality control loops to reduce broke generation and energy consumption simultaneously.
China's dual carbon goals enforce specific thermal efficiency benchmarks for new and rebuilt paper machines. The policy compresses allowable specific steam consumption figures for drying sections. Tissue producers in Shandong and Guangdong provinces respond by prioritizing heat recovery rebuilds over capacity expansions.
Buyer concentration among integrated corrugated box producers alters sourcing patterns for flexo folder-gluer lines. Large fulfillment network operators now demand quick-changeover specifications and bundled maintenance agreements. This pattern is most visible in Germany and the Netherlands where e-commerce packaging volume concentrates.
Paper Machinery Market Segmentation
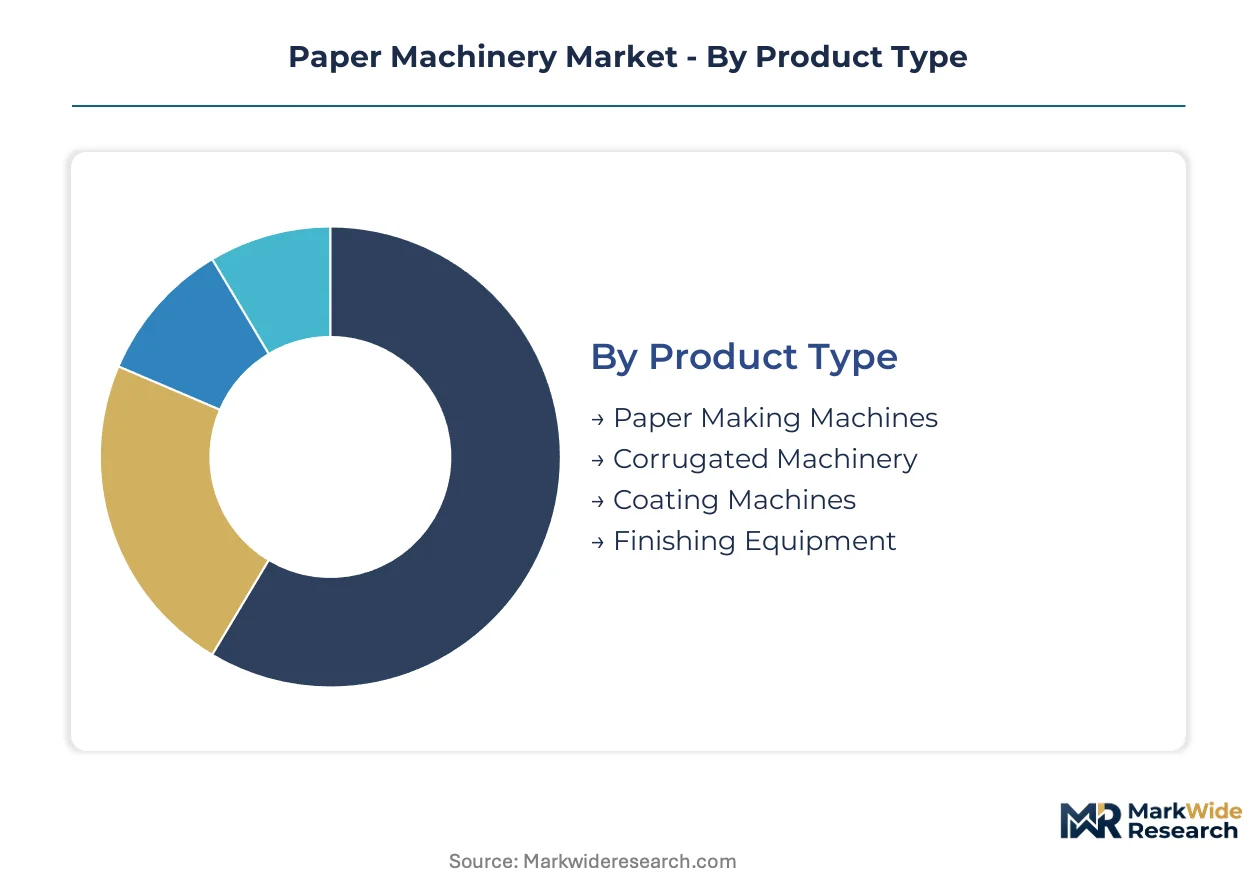
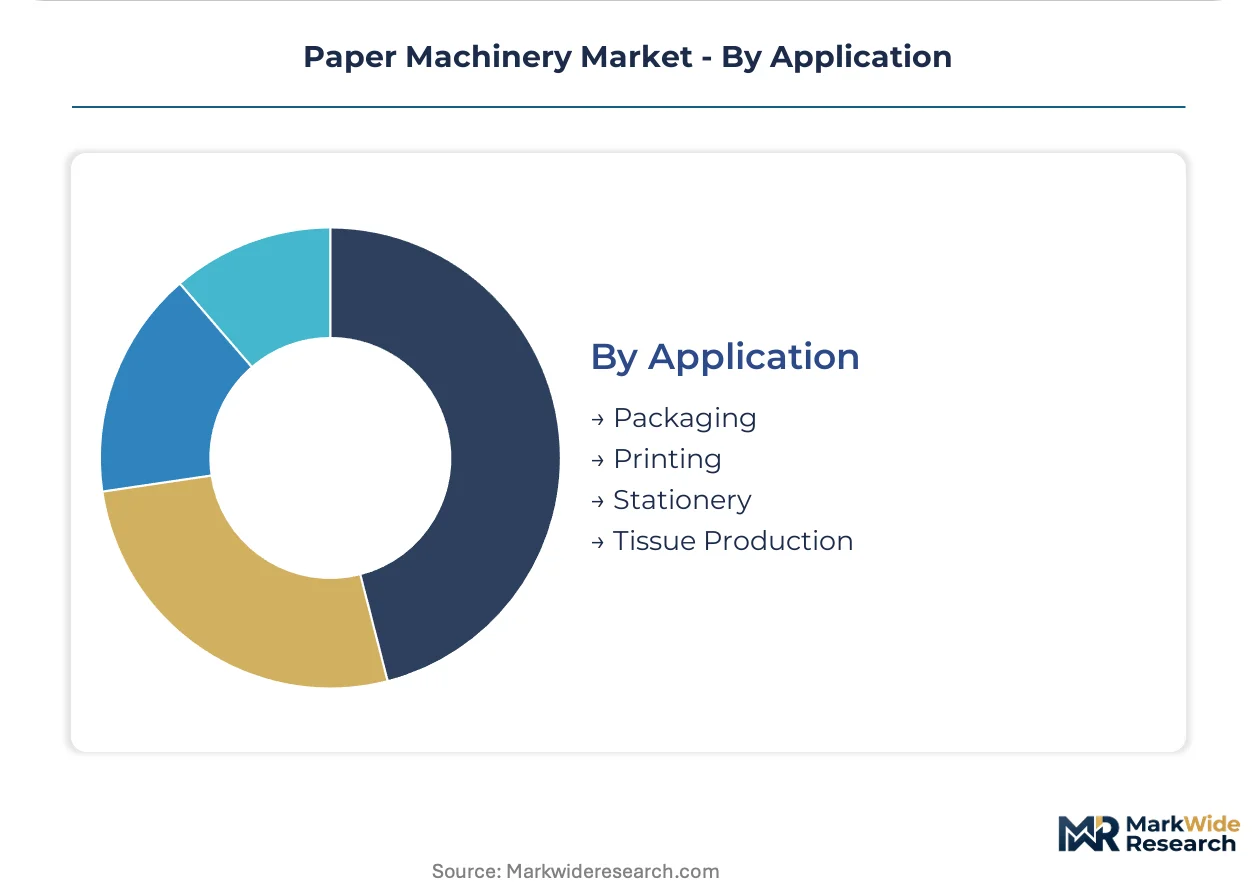
Paper machinery procurement patterns diverge sharply across product categories and end-use verticals. Certification requirements from EU Ecodesign and China's MEE reshape equipment specifications differently for each segment, forcing suppliers to maintain parallel compliance portfolios.
Product Type:
ISO 14001 certification serves as baseline market access for all four product categories, though EU F-Gas Regulation compliance concentrates disproportionately in coating and drying-intensive segments. CE marking requirements escalate with machine complexity and thermal load.
- Paper Making Machines:Continuous web-forming equipment operating at speeds exceeding 2,000 meters per minute on modern linerboard configurations. Demand concentrates in Southeast Asia where Vietnam and Indonesia expand regional paperboard capacity; MEE wastewater discharge limits in China accelerate heat-recovery rebuilds over greenfield investments. Leading the category by volume: Paper Making Machines. Growing fastest: Corrugated Machinery.
- Corrugated Machinery:Flexo folder-gluer lines and converting equipment optimized for quick-changeover e-commerce packaging specifications. German and Dutch fulfillment network operators now mandate bundled maintenance agreements alongside machine procurement.
- Coating Machines:Surface treatment systems applying barrier coatings for food-contact board grades. REACH compliance for chemical handling modules extends engineering lead times for European installations.
- Finishing Equipment:Sheeters, rewinders, and calendering systems completing final dimensional and surface quality specifications.
Margin structures favor equipment with embedded digital control architectures over mechanically intensive legacy designs.
End User:
Customer scale determines service contract bundling patterns and rebuild versus replacement preferences.
- Pulp Mills:Integrated fiber-to-paper operations requiring full-line coordination from stock preparation through reel-up. Water treatment module adoption climbs fastest here as MEE enforcement tightens in Shandong and Guangdong provinces.
- Paper Manufacturers:Dedicated tissue and printing paper producers pursuing specific steam consumption benchmarks under China's dual carbon goals. Heat pump integration mandates from the EU Green Deal concentrate procurement attention on drying section retrofits.
- Packaging Companies:Corrugated box producers driving replacement cycle compression through e-commerce volume pressure. Largest operators demand quick-changeover specifications and predictive maintenance subscriptions.
- Print Service Providers:Commercial printing operations with smaller installed bases and higher price sensitivity for finishing equipment.
Procurement concentration: Packaging Companies command the steepest volume growth. Rebuild preference: Pulp Mills and Paper Manufacturers favor section-by-section upgrades.
Technology:
Technology selection correlates with labor cost structures and carbon accounting stringency in end-user jurisdictions.
- Automation Solutions:Model-predictive control systems for moisture and caliper profiles converging with edge computing architectures. Board mills with thin profit margins adopt these systems fastest to reduce broke generation and energy consumption simultaneously.
- Robotics:Automated reel handling and packaging systems reducing manual intervention at machine speeds where human response times prove insufficient.
- Digital Printing:Inkjet and toner-based systems for short-run corrugated and label applications bypassing conventional plate-making.
- Eco-friendly Technologies:Organic Rankine cycle heat recovery and closed-loop water treatment modules capturing emerging margin pools as carbon border adjustments reshape geographic competitiveness.
Adoption velocity: Eco-friendly Technologies accelerate most quickly under regulatory pressure. Maturity advantage: Automation Solutions retain the largest installed base.
Application:
End-use specifications dictate machine speed, width, and control precision requirements.
- Packaging:Linerboard and corrugated medium production dominating capital deployment. E-commerce fulfillment networks in Germany and the Netherlands compress equipment replacement cycles for flexo folder-gluer lines.
- Printing:Newsprint and magazine paper grades facing demand pressure from digital media substitution; investment concentrates in specialty coated papers.
- Stationery:Fine paper grades requiring superior formation and surface smoothness specifications.
- Tissue Production:Consumer and away-from-home towel and tissue grades with distinct softness and absorbency targets; producers in China's coastal provinces prioritize heat recovery rebuilds.
Revenue weighting: Packaging commands the dominant share. Technology intensity: Tissue Production requires the most precise moisture control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures more paper machinery than it consumes, while Germany and the United States rely on imports for advanced drying sections and control systems. Southeast Asian mills now source forming and press equipment from regional fabricators to bypass European lead times.
Germany
Corrugated box producers in the Rhine-Ruhr cluster demand quick-changeover flexo folder-gluer lines for e-commerce fulfillment networks. The EU F-Gas Regulation mandates heat pump integration in drying section rebuilds, forcing mills toward Voith Group and Andritz for compliant retrofits. Bavarian engineering centers develop model-predictive control systems for moisture profile optimization.
China
Shandong and Guangdong tissue producers prioritize heat-recovery rebuilds over capacity expansions under dual carbon goals enforced by MEE. The MIIT promotes domestic fabrication of high-precision hydraulic components to reduce import dependence for servo-valves. Yangtze River Delta foundries supply nickel-chromium-molybdenum alloy rolls to regional linerboard mills.
United States
Packaging board modernization concentrates in the Midwest and Southeast where aging Fourdrinier machines require section-by-section upgrades. EPA effluent guidelines drive closed-loop water system adoption in Wisconsin and Georgia pulp mills. Pacific Northwest integrated producers source eco-friendly technologies to meet corporate carbon accounting requirements.
Vietnam
Regional paperboard capacity expansion in Binh Duong and Dong Nai provinces concentrates demand for new forming and press sections. The Ministry of Industry and Trade incentivizes energy-efficient machinery imports through preferential tariff structures. Japanese and European suppliers establish local service subsidiaries to capture recurring maintenance revenue.
India
Underpenetrated domestic kraft liner capacity in Gujarat and Maharashtra creates demand for rebuilt gap former installations. BIS certification requirements extend equipment qualification timelines for imported drying sections. Tamil Nadu packaging converters adopt automation solutions to reduce labor intensity in corrugated converting lines.
Paper Machinery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment categories, creating a tiered structure where scale-driven rebuild service networks face agile regional fabricators. The vendor base clusters around three archetypes: full-line system integrators with captive hydraulic and control capabilities, modular section specialists targeting energy-efficiency retrofits, and corrugated converting equipment pure-plays serving e-commerce packaging demand. Competitive moves concentrate on geographic service footprint expansion and technology licensing partnerships for heat recovery systems.
Among European full-line integrators, Valmet anchors the premium service tier through its broad installed base coverage, while Voith Group exemplifies deep backward integration into hydraulic and control systems. Andritz occupies a position within the modular specialist archetype, competing aggressively in tissue and board segments where standardized platform designs reduce engineering lead times. These three companies represent distinct strategic postures: service-network scale, upstream component control, and platform standardization velocity.
| Leading Market Players |
|---|
| Valmet |
| Voith Group |
| Andritz |
| Mitsubishi Heavy Industries |
| BHS Corrugated |
| Fosber Group |
| Metso |
| Toscotec |
| Bellmer |
| Others |
Value Network & Pricing Analysis
E-commerce fulfillment networks demanding quick-changeover specifications and bundled maintenance agreements are compressing procurement timelines and forcing suppliers to absorb customization costs upfront, which squeezes margin structures across equipment tiers while rewarding vendors with captive service networks.
Pricing Analysis
Margin tightening in mid-tier equipment reflects carbon accounting mandates that require heat pump integration and closed-loop water systems as baseline specifications rather than premium add-ons. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with ISO 14001 and EU F-Gas Regulation compliance commanding measurable premiums. Cost-down pressure on standard-tier machinery accelerates because Southeast Asian mills prioritize section-by-section rebuilds over greenfield investments. Packaging companies with thin margins exhibit the highest price sensitivity, while integrated pulp mills with captive maintenance capabilities tolerate premium positioning for energy-efficiency retrofits.
Supply Chain Analysis
Nickel-chromium-molybdenum alloy rolls rest on foundry capacity concentrated in Germany, Japan, and select Yangtze River Delta producers. High-precision hydraulic servo-valves and custom actuators draw from captive in-house production at Voith Group and specialized European component houses. Single-source vulnerability around heat pump compressors compliant with EU F-Gas Regulation creates procurement chokepoints for drying section rebuilds. Distribution runs through mill-direct commissioning contracts with embedded service agreements rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with installed base coverage and energy-efficiency retrofit expertise, as carbon border adjustments and MEE enforcement in China force smaller fabricators without compliance documentation out of bidding pools for regulated jurisdiction projects.
For Market Incumbents: Cement service network density in Vietnam and Indonesia where regional paperboard capacity expansion concentrates demand for forming and press sections. Deepen backward integration into heat recovery system components to capture margin pools from organic Rankine cycle retrofits driven by China's dual carbon goals. Lock in multi-year predictive maintenance subscriptions with German and Dutch corrugated box producers before emerging automation specialists displace traditional service contracts. For New Entrants and Emerging Players: Regional fabricators in Southeast Asia offer the most penetrable channel partner type for new forming and press section suppliers seeking to bypass European lead times. Target India's underpenetrated kraft liner capacity in Gujarat and Maharashtra with rebuilt gap former installations priced below greenfield alternatives. Lead with digital twin remote diagnostics platforms that unbundle traditional service contracts and capture recurring revenue without heavy field engineering investment. For Investors and Strategic Acquirers: The window for entry favors modular section specialists with standardized platform designs that reduce engineering lead times for tissue and board retrofits. Five-to-ten year viability hinges on heat recovery technology portfolios and MEE compliance documentation for Chinese market access. Watch for carbon border adjustment mechanism implementation timelines as the inflection signal that reshapes geographic competitiveness of machine sourcing decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Recovery Components | Captures margin pools from organic Rankine cycle systems mandated by EU Green Deal thermal efficiency benchmarks. |
| Digital Twin Remote Diagnostics Platform Launch | Unbundles traditional service contracts with German and Dutch corrugated producers demanding predictive maintenance subscriptions. |
| Local Service Subsidiary Establishment in Vietnam | Captures recurring maintenance revenue from Binh Duong and Dong Nai paperboard capacity expansions. |
| Standardized Platform Design Investment | Reduces engineering lead times for tissue and board segments where Andritz currently competes aggressively. |
| ISO 14001 Certification Acceleration Program | Shortens bid-to-award cycles for regulated jurisdiction projects where environmental management documentation is mandatory. |
Research Methodology
Trade association filings, customs and import-export records, and equipment registration databases formed the secondary backbone for this analysis. Primary interviews with maintenance directors at linerboard mills, aftermarket service heads at European full-line integrators, and procurement leads at Southeast Asian paperboard producers validated demand-side assumptions. Bottom-up and top-down triangulation reconciled machine shipment data with capacity expansion announcements across Vietnam, Indonesia, and China's coastal provinces.
Bottom-up modeling aggregated segment-level equipment demand across paper making machines, corrugated machinery, coating machines, and finishing equipment, while top-down validation checked aggregate figures against regional pulp-to-paper conversion capacity trends. Segmentation dimensions included product type, end user category, technology tier, and application vertical, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs were derived from replacement cycle compression analysis and energy-efficiency retrofit penetration curves, incorporating China's MEE wastewater discharge limits and EU F-Gas Regulation compliance timelines as structural demand drivers.
Caveats apply where carbon border adjustment mechanism implementation timelines or sudden shifts in China's dual carbon goal enforcement intensity could materially shift the outlook for regional equipment sourcing competitiveness. Forecasts reflect assumptions about sustained e-commerce packaging volume growth and continued nickel-chromium-molybdenum alloy supply concentration. A small set of named triggers—tariff restructuring on precision hydraulic components, MIIT domestic fabrication incentives for servo-valves, and EPA effluent guideline revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pulp and Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
North America Thermal Paper Market
Paper Products
Plywood Market
Paper Products
Sanitary Paper Products Market
Paper Products
Metallized Paper Market
Paper Products
Greaseproof Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Sawn Wood Market
Paper Products
White Top Testliner Market
Paper Products
Glassine Paper Market
Paper Products
Decor Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Specialty Paper Market
Paper Products
North America Coated Paper Market
Paper Products
Leatheroid Paper Market