
 Synthetic Paper Market | 2026-2036
Synthetic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Paper Market Intelligence
Specialty paper distribution is reconfiguring around regional converter networks that bypass traditional merchant channels. Yupo Corporation leverages its integrated biaxial orientation lines to control substrate quality from resin pellet to finished roll. DuPont anchors North American supply through its fluoropolymer-coated grades that sustain premium positioning in chemical-resistant tag applications. PPG Industries competes via coating technology leadership, extending its reach into durable printing substrates for outdoor signage.
Synthetic paper denotes a polymeric film engineered to emulate conventional paper surface characteristics, typically manufactured through biaxial orientation of polypropylene or polyester resins to achieve tear resistance, dimensional stability, and moisture impermeability for demanding print and labeling environments. Extrusion-based polypropylene grades dominate volume production due to favorable cost structures and broad compatibility with flexographic and thermal transfer printing systems, while coating technology segments capture disproportionate margin pools where UV-curable or solvent-resistant surface treatments command specification-driven premiums in identification card and map applications. Lamination processes occupy a specialized niche for outdoor signage requiring multi-layer barrier performance against UV degradation and thermal cycling.
REACH substance restrictions in the European Union and FDA food-contact notification requirements in the United States constrain resin additive packages and migration testing protocols, directly elevating compliance costs for suppliers serving cross-border label and packaging converters. China's GB standards for plastic food-contact materials, administered by SAMR, impose parallel testing regimes that shape export-oriented formulation decisions. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation investments and qualify alternative substrate chemistries before specification lock-in.
Market Dynamics
Biaxial orientation capacity concentration in China and Japan is restructuring supply geography, while REACH and FDA food-contact mandates force simultaneous reformulation across export-oriented converter networks.
Growth Catalysts
- Food-contact compliance mandates:FDA notification requirements for polypropylene resins used in beverage labels are accelerating substrate qualification cycles among North American converters.
- Moisture-resistant labeling demand:Beverage and personal care brands specify synthetic paper for refrigerated supply chains where cellulose substrates fail.
- Extrusion scale-up:Chinese domestic converters are expanding biaxial orientation line capacity to serve Asia-Pacific flexible packaging demand.
Market Restraints
- Resin cost volatility:Polypropylene feedstock prices track propylene monomer fluctuations, compressing margin stability for non-integrated producers.
- Converter concentration risk:Specialty substrate supply chains depend on a limited set of Japanese and Korean biaxial orientation specialists.
- Cellulose substrate competition:Wet-strength paper and glassine alternatives retain cost advantage in non-critical labeling applications.
Strategic Opportunities
- India packaging penetration:Domestic label converters in Maharashtra and Gujarat are qualifying synthetic substrates for pharmaceutical export packaging.
- RFID inlay integration:Convergence of thermal transfer printable synthetics with NFC antenna substrates opens asset-tracking applications.
- EU Green Deal alignment:Recyclable mono-material PP grades position suppliers for packaging circularity mandates under revised Extended Producer Responsibility frameworks.
Industry Challenges
- Migration testing timelines:FDA and EFSA food-contact certification cycles extend 18-24 months, delaying new resin formulation commercialization.
- Biaxial orientation technician scarcity:Specialized extrusion and stretching process engineering expertise concentrates among aging workforces in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Paper Market |
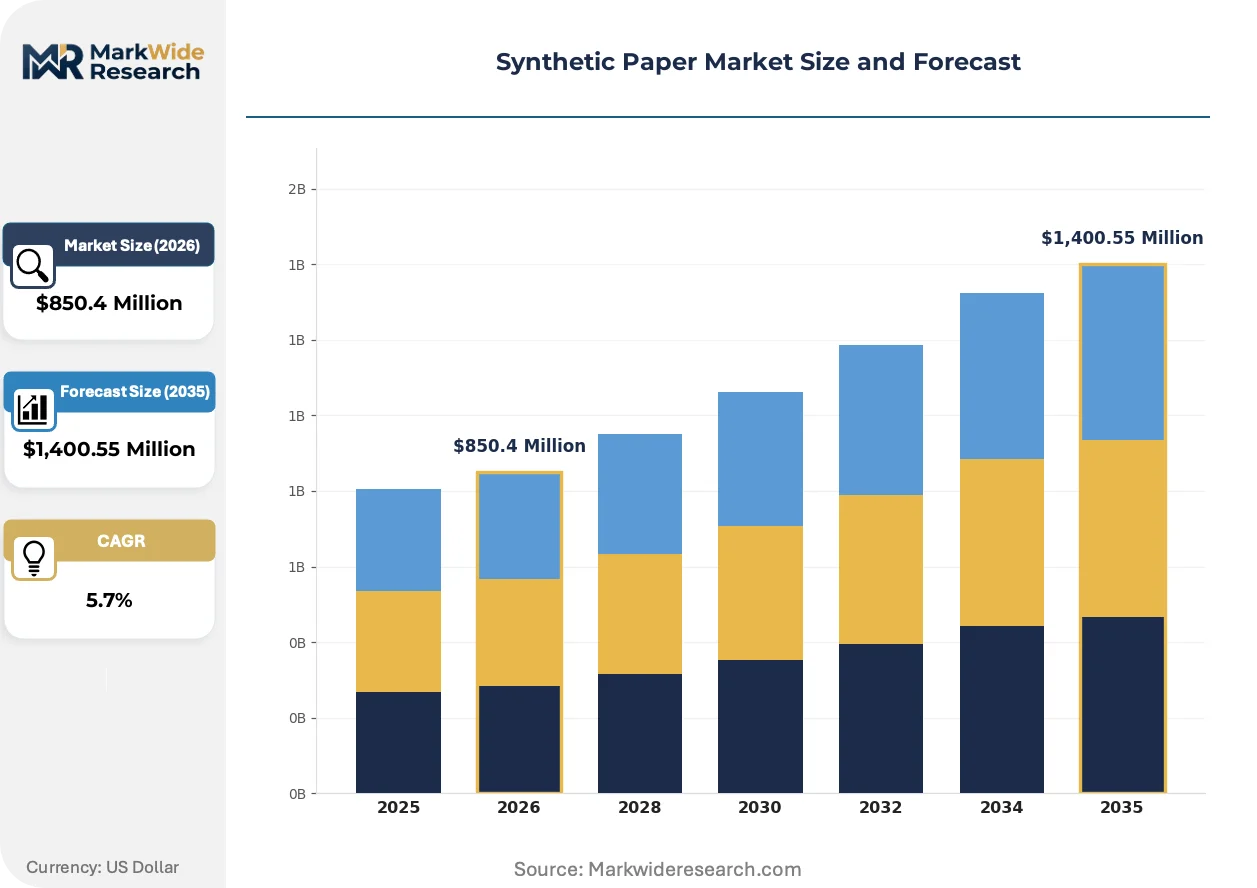
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,400.55 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, PVC, Others End User: Packaging, Labels, Printing, Stationery Technology: Extrusion, Coating, Lamination, Others Application: Outdoor Signage, Tags, Identification Cards, Maps |
| Companies Covered | PPG Industries, Yupo Corporation, Seiko Epson Corporation, Agfa-Gevaert Group, DuPont, Cosmo Films, Formosa Plastics Group, Arjobex SAS, American Profol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Paper Market Strategic Shifts & Innovations
Surface engineering and substrate architecture are converging to address simultaneous demands for print durability, regulatory compliance, and end-of-life recyclability in premium labeling applications.
Water-based barrier coatings are migrating from niche map and chart applications to mainstream food packaging labels as brand owners eliminate perfluorinated substances. European converters adopting these formulations report comparable grease resistance to legacy fluoropolymer treatments. The technology is migrating from specialty grades to volume production tiers, compressing the premium-to-standard price spread.
REACH substance restrictions on intentionally added microplastics are forcing reformulation of surface additives used in synthetic paper coatings. ECHA evaluation criteria now cover slip agents and anti-static compounds previously exempt from scrutiny. Label converters serving EU food exports are accelerating qualification of additive-free substrate grades to preempt supply disruption.
Direct-to-shape digital printing adoption among craft beverage brands is shortening label procurement cycles from quarterly to weekly replenishment. Brand owners bypass traditional merchant distributors to contract directly with substrate converters offering just-in-time slitting and die-cutting. This pattern is most visible among California and Pacific Northwest wineries and breweries where SKU proliferation outpaces conventional label inventory models.
Synthetic Paper Market Segmentation

Synthetic paper segmentation reflects divergent cost structures, performance requirements, and regulatory compliance burdens across substrate chemistries and conversion technologies. Understanding these divides enables suppliers to align capacity investments with margin pools and qualification timelines.
Product Type:
Cost tier stratification separates commodity-grade extrusion feedstocks from specialty resins commanding specification premiums in regulated end-uses.
- Polypropylene:Biaxially oriented polypropylene dominates volume production through favorable melt-flow characteristics and broad flexographic compatibility. Chinese extrusion lines in Zhejiang and Guangdong provinces scale capacity to serve Asia-Pacific label converters seeking moisture-resistant beverage packaging substrates.
- Polyester:Higher glass-transition temperature delivers dimensional stability for thermal transfer printing and outdoor durability specifications. Demand concentrates in Japanese and Korean manufacturing clusters supplying identification card laminates and chemical-resistant tag stock.
- PVC:Legacy formulation retains niche presence in rigid card applications where embossing performance outweighs environmental scrutiny.
- Others:Polystyrene and polyethylene grades address price-sensitive stationery and short-life promotional printing segments.
Polypropylene holds installed capacity. Polyester is rotating up the share rankings.
End User:
Application maturity determines whether converters prioritize unit economics or qualification depth in substrate procurement.
- Packaging:Food-contact notification requirements from FDA and parallel EFSA protocols extend resin qualification cycles to 18-24 months. Beverage brands specify synthetic substrates for refrigerated supply chains where cellulose alternatives absorb moisture and fail.
- Labels:Direct-to-shape digital printing adoption among craft beverage producers compresses procurement cycles from quarterly to weekly replenishment. California and Pacific Northwest wineries contract directly with slitters offering just-in-time die-cutting.
- Printing:Map and chart publishers migrate from solvent-based to water-based barrier coatings as REACH restrictions eliminate perfluorinated substances.
- Stationery:Cost-sensitive segment retains cellulose competition in non-critical applications.
Labels command the steepest expansion trajectory. Packaging maintains qualification barriers that protect incumbent positions.
Technology:
Process complexity separates integrated producers controlling resin-to-roll quality from merchant converters dependent on external substrate supply.
- Extrusion:Biaxial orientation of polypropylene pellets achieves tear resistance and moisture impermeability through machine-direction and transverse-direction stretching. Japanese and Korean specialists concentrate process engineering expertise among aging workforces.
- Coating:UV-curable and solvent-resistant surface treatments command specification-driven premiums in identification card and chemical-tag applications. PPG Industries extends technology leadership into durable outdoor signage substrates.
- Lamination:Multi-layer barrier construction addresses UV degradation and thermal cycling in extended-life outdoor graphics.
- Others:Cast film and calendering processes serve cost-minimized promotional printing tiers.
Extrusion anchors volume throughput. Coating is climbing the fastest as water-based formulations displace fluoropolymer treatments.
Application:
Environmental exposure severity dictates substrate architecture and surface engineering investment.
- Outdoor Signage:Lamination and coating technologies converge to deliver multi-layer UV barrier performance. EU Green Deal circularity mandates under revised Extended Producer Responsibility frameworks favor recyclable mono-material PP grades.
- Tags:Chemical-resistant specifications sustain premium positioning for fluoropolymer-coated substrates in industrial asset tracking.
- Identification Cards:Thermal transfer printability and embossing compatibility drive polyester and PVC specification.
- Maps:Water-based barrier coatings migrate from specialty grades to volume production as ECHA microplastic restrictions force additive reformulation.
Outdoor signage absorbs capital-intensive lamination capacity. Tags defend margin through specification stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and Korean producers command 15-20% price premiums over Chinese extrusion output, while North American converters absorb elevated landed costs for FDA-compliant food-contact grades. This asymmetry structures procurement decisions across label and packaging supply chains.
United States
Beverage brands in California and the Pacific Northwest specify synthetic substrates for refrigerated supply chains where cellulose alternatives fail. FDA food-contact notification requirements for polypropylene resins extend qualification cycles to 18-24 months. Midwest converters in Illinois and Ohio are scaling thermal transfer printing capacity to serve pharmaceutical label demand.
China
Domestic converters in Zhejiang and Guangdong provinces are expanding biaxial orientation line capacity to serve Asia-Pacific flexible packaging buyers. SAMR-administered GB standards for plastic food-contact materials impose parallel testing regimes that shape export-oriented formulation decisions. Shanghai-based extrusion specialists are capturing share in moisture-resistant beverage label substrates.
Japan
Identification card laminates and chemical-resistant tag stock sustain demand for higher glass-transition polyester grades. METI oversees industrial standards alignment with international certification protocols. Process engineering expertise for biaxial orientation concentrates among aging workforces in the Kanto and Kansai manufacturing clusters.
Germany
Map and chart publishers migrate from solvent-based to water-based barrier coatings as ECHA microplastic restrictions force additive reformulation. REACH substance restrictions on intentionally added microplastics constrain surface additive packages. Industrial converters in Bavaria and North Rhine-Westphalia are qualifying recyclable mono-material PP grades for EU Green Deal circularity mandates.
India
Domestic label converters in Maharashtra and Gujarat are qualifying synthetic substrates for pharmaceutical export packaging. BIS standards for plastic materials shape import substitution strategies. Mumbai-Ahmedabad industrial corridor specialists are building slitting and die-cutting capacity to bypass traditional merchant distribution channels.
Synthetic Paper Market Key Industry Players
Integrated resin-to-roll producers and coating-technology specialists split the market into margin-protected and volume-driven tiers. Japanese and Korean groups anchor supply through captive biaxial orientation capacity, while North American and European competitors differentiate via surface engineering and regulatory qualification depth. Three archetypes dominate: integrated extrusion houses controlling substrate quality from pellet to roll, coating-technology leaders commanding specification premiums, and regional converters scaling just-in-time slitting capacity. Capacity expansion and direct-to-brand converter relationships constitute the dominant competitive moves.
Among integrated extrusion specialists, Yupo Corporation exemplifies the resin-to-roll archetype through its biaxial orientation line control. PPG Industries occupies a position within the coating-technology tier, extending surface treatment leadership into durable printing substrates. DuPont anchors North American supply through fluoropolymer-coated grades serving chemical-resistant tag applications. These three represent distinct strategic positions rather than comparable scale metrics.
| Leading Market Players |
|---|
| PPG Industries |
| Yupo Corporation |
| Seiko Epson Corporation |
| Agfa-Gevaert Group |
| DuPont |
| Cosmo Films |
| Formosa Plastics Group |
| Arjobex SAS |
| American Profol |
| Others |
Cost & Logistics Intelligence
Biaxial orientation capacity concentration in Zhejiang and Guangdong provinces directly determines where margin pools accumulate downstream, with Japanese and Korean specialists commanding 15-20% premiums over Chinese extrusion output while North American converters absorb elevated landed costs for FDA-compliant food-contact grades.
Pricing Analysis
The customization-premium spread separates configured-to-order substrate pricing from standard roll stock, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and volume scale. Price differentiation hinges on FDA food-contact notification status and biaxial orientation line integration, with margins tightening in commodity polypropylene grades as Chinese capacity expansion intensifies cost competition. Pharmaceutical label converters exhibit lowest price sensitivity due to qualification barriers, while promotional printing buyers drive aggressive standard-tier negotiation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for North American converters sourcing moisture-resistant beverage label substrates. Production gravity centers on China, Japan, and South Korea, with propylene monomer feedstock and specialized coating chemicals drawing from regional petrochemical clusters. Single-source vulnerability concentrates in biaxial orientation technician expertise anchored in aging Japanese and German workforces. Distribution runs through regional converter networks that bypass traditional merchant channels for direct-to-brand relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic paper is experiencing high-growth disruption as REACH microplastic restrictions and FDA food-contact mandates simultaneously force reformulation across export-oriented converter networks, creating structural openings for qualified suppliers.
For Market Incumbents: Pre-empt additive-free substrate qualification to capture EU Green Deal circularity mandates before specification lock-in hardens. Deepen backward integration into biaxial orientation capacity in Zhejiang or Guangdong to offset Japanese-Korean premium positioning. Secure FDA notification depth for polypropylene resins to defend pharmaceutical label share against emerging Chinese exporters. For New Entrants and Emerging Players: Mid-market pharmaceutical export packaging in Maharashtra and Gujarat represents the most penetrable entry point given BIS standard alignment gaps and slitting capacity buildouts along the Mumbai-Ahmedabad corridor. Water-based barrier coating technology for map and chart publishers migrating from fluoropolymer treatments offers specification-driven margin capture. Direct converter relationships with California craft beverage brands bypass entrenched merchant distribution. For Investors and Strategic Acquirers: Capital is best deployed toward coating-technology specialists with REACH-compliant formulation pipelines and established EFSA certification track records. The 5-10 year viability window favors suppliers controlling surface engineering IP as water-based treatments displace legacy fluoropolymer grades. Monitor ECHA evaluation criteria expansion for slip agents and anti-static compounds as the inflection signal for additive-free substrate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biaxial Orientation | Yupo Corporation's resin-to-roll control demonstrates margin protection against Chinese volume competition. |
| REACH-Compliant Coating Reformulation | PPG Industries' water-based barrier leadership positions for EFSA food-contact specification premiums. |
| FDA Food-Contact Notification Investment | DuPont's fluoropolymer-coated grade qualification sustains chemical-resistant tag positioning. |
| Direct-to-Brand Converter Relationships | California winery just-in-time procurement patterns compress inventory cycles and bypass merchant channels. |
| RFID Inlay Substrate Integration | Thermal transfer printable synthetics with NFC antenna convergence open asset-tracking application expansion. |
Research Approach
The analysis maps extrusion-based polypropylene, coating-technology polyester, and lamination-process PVC segments, each validated through converter procurement directors, biaxial orientation plant engineers, brand owner packaging specification leads, and regulatory affairs managers at resin suppliers. Primary interview findings triangulated against secondary sources including FDA food-contact notification databases, ECHA REACH substance restriction updates, SAMR GB standard filings, and customs trade flow records. Bottom-up capacity assessments and top-down end-use demand modeling were reconciled across the analytical framework.
Assumptions held fixed include REACH substance restriction timelines and FDA notification protocol stability, while propylene monomer price volatility and Chinese capacity expansion rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass substrate chemistry, conversion technology, end-use application, and regional regulatory cluster. CAGRs were derived from installed capacity utilization rates and qualification cycle timelines. Industry-specific forecast inputs incorporated biaxial orientation line commissioning schedules and EFSA additive evaluation progressions.
Stress conditions across propylene feedstock price bands, REACH restriction acceleration scenarios, and Chinese export subsidy regimes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and converter qualification capacity. Specific risk factors that could revise projections include ECHA microplastic restriction scope expansion beyond intentionally added substances and abrupt FDA food-contact protocol modifications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Softwood Pulp Market
Paper Products
Photographic Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Pp Synthetic Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
Metallized Paper Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
White Top Testliner Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Inlay Paper Market
Paper Products
Global Electrical Insulation Paper Market