
 Global Direct Thermal Ticket Paper Market | 2026-2036
Global Direct Thermal Ticket Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Direct Thermal Ticket Paper Market Intelligence
Expertise in thermal coating chemistry and process engineering is reorganizing the supply landscape for direct thermal ticket paper. This shift places a premium on specialized R&D talent capable of developing compliant and high-performance formulations. Koehler Paper Group specializes in advanced phenol-free thermal paper technologies, securing a position in health-conscious markets. Nippon Paper Industries Co., Ltd. leverages its large-scale pulp manufacturing, while Oji Holdings Corporation competes on a global scale with a diverse product portfolio.
Direct thermal ticket paper is a specialty media coated with a solid-state mixture of a leuco dye and a developer. Heat from a thermal printer head causes the chemicals to react, creating a high-contrast image without requiring ink or ribbons. Among applications, event ticketing and public transit fare segments command significant and consistent volume. Roll ticket paper remains the dominant product type, reflecting its direct compatibility with the vast installed base of kiosk and point-of-sale printers.
Regulatory frameworks directly influence material composition and market access for thermal paper products. The European Chemicals Agency's (ECHA) REACH regulation restricts bisphenols like BPA, while US FDA rules govern materials for food-contact receipts. In parallel, China's GB standards mandate specific quality and safety benchmarks for products sold domestically. Manufacturers consequently face a strategic choice between investing in compliant, higher-cost formulations or competing in less-regulated market segments.
Market Dynamics
The primary force shaping the direct thermal ticket paper market is regulatory pressure on material safety, compelling a widespread and capital-intensive shift away from bisphenol-based chemistries toward compliant, phenol-free alternatives.
Growth Catalysts
- Public Transit Expansion:The modernization and expansion of automated fare collection systems within public transportation networks, particularly across China and India, creates consistent, high-volume demand for ticket paper.
- Event and Venue Management:A persistent need for physical tickets, wristbands, and credentials in the global events and entertainment industry provides a stable demand base, especially for customized media with security features.
- Regulatory Compliance:Mandates from bodies like the European Chemicals Agency (ECHA) under REACH accelerate the market's transition to safer, bisphenol-free thermal papers, creating a premium segment for compliant products.
Market Restraints
- Higher Formulation Costs:The increased production cost associated with alternative phenol-free developer chemistries, which require more complex synthesis processes, compresses manufacturer margins or translates to higher end-user prices.
- Digital Substitution:The proliferation of digital ticketing via smartphones and mobile applications presents a direct substitution threat, steadily eroding the demand for physical tickets in public transit and event segments.
- Raw Material Concentration:A dependence on a limited number of global suppliers for critical raw materials, including specialized leuco dyes and developers, creates potential supply chain bottlenecks and price volatility.
Strategic Opportunities
- Adjacent Application Development:Adapting thermal paper technology for adjacent applications like on-demand logistics labels, cold-chain tracking, and medical wristbands opens new revenue streams beyond traditional ticketing.
- Enhanced Durability Formulations:Developing thermal papers with superior resistance to environmental factors like UV light, water, and abrasion can unlock use cases in outdoor venues, multi-day festivals, and parking management.
- Sustainable and Recyclable Media:Creating fully recyclable or compostable thermal paper formulations caters to increasing corporate sustainability goals and appeals to environmentally conscious venues, brands, and municipalities.
Industry Challenges
- Specialized Talent Scarcity:A shortage of R&D talent with deep expertise in thermal coating chemistry and process engineering constrains the pace of innovation for new, high-performance, and compliant paper formulations.
- Legacy System Compatibility:Ensuring consistent image quality and printhead longevity when using new paper types with the vast installed base of older thermal printers presents a significant technical and support challenge.
- Divergent Global Standards:Navigating disparate and evolving safety regulations, such as US FDA food-contact rules versus China's GB standards, complicates product development and global distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Direct Thermal Ticket Paper Market |
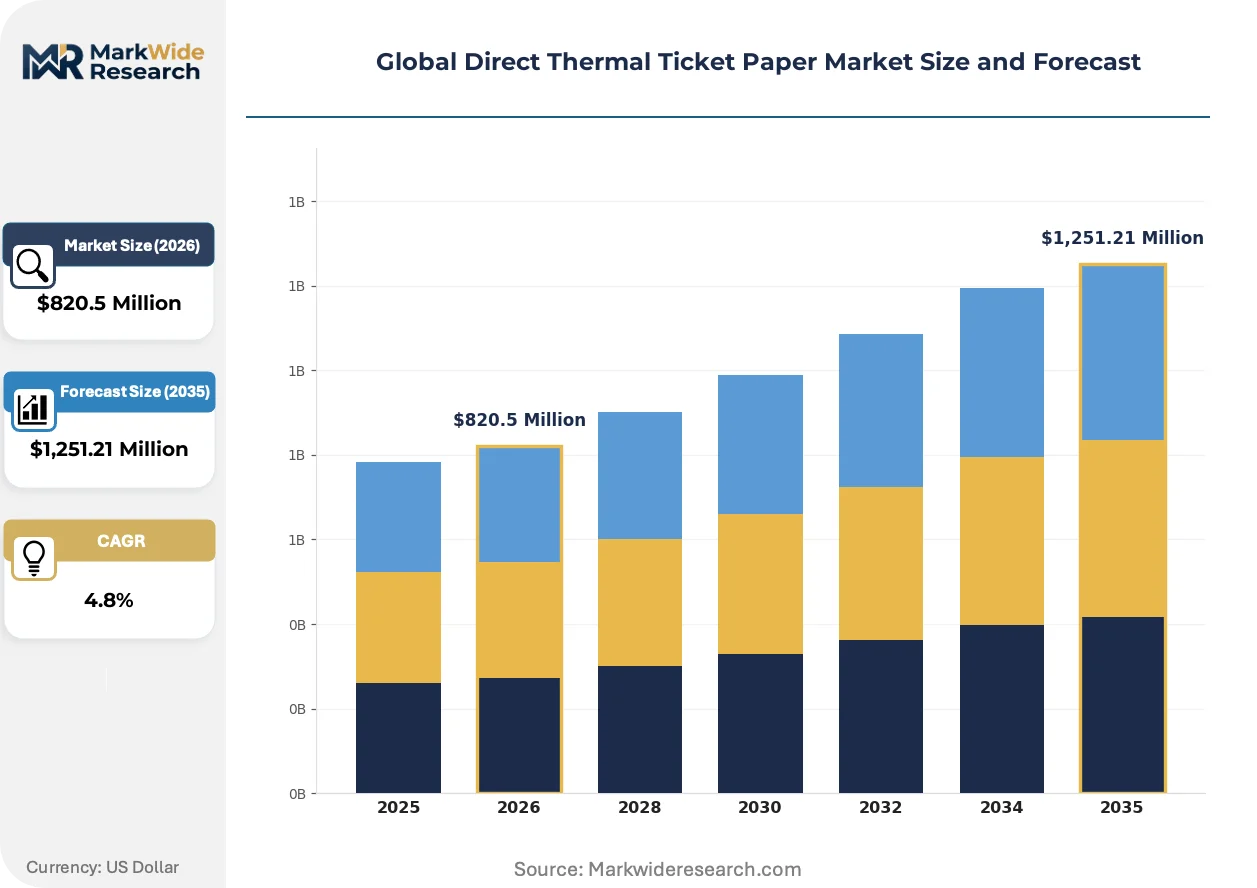
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,251.21 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll Ticket Paper, Fan-Fold Ticket Paper, Label Ticket Paper, Adhesive Ticket Paper, Continuous Ticket Paper Application: Parking Ticketing, Event Ticketing, Public Transit Fare, Retail Receipting, Access Control End User: Transportation Agencies, Entertainment Venues, Public Transport Operators, Retail Outlets, Access Management Firms Distribution Channel: Direct Sales, Online Stores, Distributors, Wholesale Traders, OEM Partners |
| Companies Covered | Nippon Paper Industries Co., Ltd., Hansol Paper Co. Ltd., Ahlstrom-Munksjö Oyj, Koehler Paper Group, Ricoh Company, Ltd., UPM-Kymmene Oyj, Domtar Corporation, Henan Province JiangHe Paper Co., Ltd., Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Direct Thermal Ticket Paper Market Strategic Shifts & Innovations
Material science innovation and evolving end-user behavior are creating a dual-track market. One track focuses on advanced, compliant chemistries driven by health and safety regulations, while the other confronts the steady encroachment of digital alternatives that threaten core applications.
Phenol-free developer chemistry, utilizing compounds like urea derivatives, is a key product evolution designed to create images without bisphenols. Major end-users in public-facing sectors like retail and transit are adopting these papers to mitigate health concerns. This advanced material science is supplanting traditional BPA and BPS formulations, particularly in markets with stringent chemical regulations like the European Union.
Europe's REACH regulation, enforced by the ECHA, continues to tighten restrictions on bisphenols in thermal paper, effectively setting a global benchmark for material safety. This rule mandates a shift to alternative developers, rendering non-compliant paper ineligible for the large EU market. This directly affects point-of-sale receipt and label segments, compelling a supply chain-wide reformulation effort to maintain market access.
Consumer preference for digital convenience is driving a clear shift toward mobile ticketing solutions that use QR codes and NFC technology. This behavioral change directly disrupts the physical ticket model in high-volume applications like urban mass transit and major sporting events. The trend is most visible in technologically advanced urban centers in North America and Asia, reducing the addressable market for paper-based tickets.
Global Direct Thermal Ticket Paper Market Segmentation
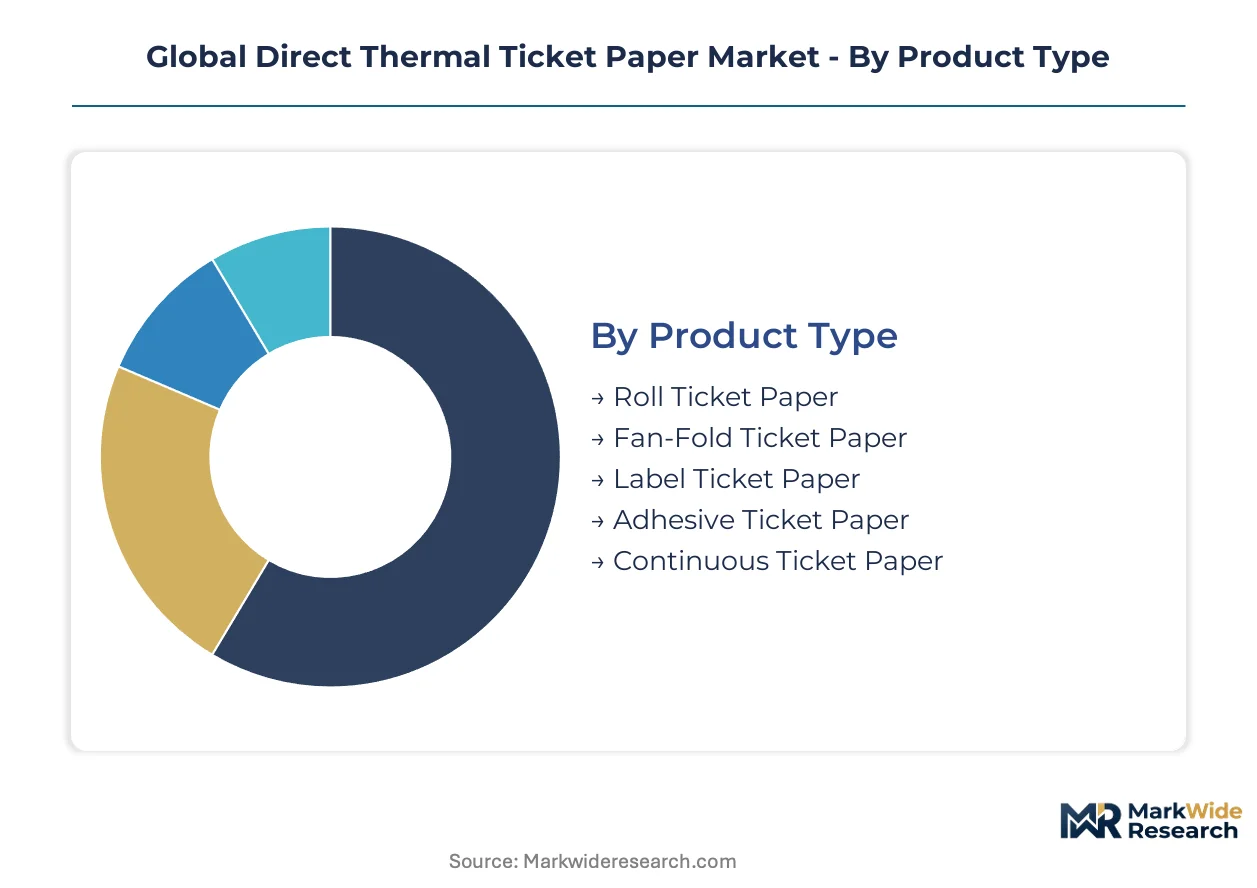
The direct thermal ticket paper market segments by product characteristics, application scenarios, end-user types, and distribution pathways. Understanding these distinct segments provides insights into demand drivers and competitive dynamics across the global landscape. Each category reflects unique operational requirements and regulatory influences shaping product development.
Product Type:
Regulatory frameworks such as Europe's REACH regulation influence the material composition of various product types, driving innovation towards compliant formulations across the market.
- Roll Ticket Paper:This format comprises continuous paper wound into rolls, designed for high-volume thermal printers in kiosks and point-of-sale systems. Its compatibility with existing infrastructure ensures consistent demand from public transit and retail operations globally.
- Label Ticket Paper:This product incorporates an adhesive backing, enabling its use for wristbands, baggage tags, and logistics labels. Demand for this type concentrates in specialized access control and supply chain applications.
- Fan-Fold Ticket Paper:This paper type features perforations, suitable for batch printing in event management.
- Adhesive Ticket Paper:These papers feature a full adhesive layer, used for temporary identification in venues.
- Continuous Ticket Paper:This format consists of an uninterrupted web, supporting high-speed printing for large-scale operations.
Established volume favors Roll Ticket Paper; emerging adoption favors Label Ticket Paper.
Application:
The market for direct thermal ticket paper is shaped by the specific functional requirements of diverse end-use applications, each demanding distinct material properties.
- Public Transit Fare:This application involves high-volume usage in automated fare collection systems for buses, trains, and subways. Modernization of urban transport networks, particularly in China and India, drives consistent demand.
- Event Ticketing:This segment utilizes thermal paper for admission tickets, credentials, and wristbands at concerts, sports events, and festivals. Customization and security features are often critical for venues.
- Parking Ticketing:These applications require durable paper resistant to environmental factors for outdoor use.
- Retail Receipting:Thermal paper serves as the primary medium for transaction receipts in retail stores.
- Access Control:This application uses thermal paper for temporary passes and visitor badges in corporate buildings.
Volume demand is strongest in Public Transit Fare, while Event Ticketing maintains a stable, specialized requirement.
End User:
End-user segments define specific purchasing behaviors and operational scales, influencing product specifications and procurement strategies for thermal ticket paper.
- Public Transport Operators:These organizations directly manage transit services and are major consumers of thermal paper for automated fare collection systems. Their demand is consistent and volume-intensive in urban centers.
- Retail Outlets:This broad segment encompasses supermarkets and department stores using thermal paper for sales receipts. Digital alternatives present a significant competitive pressure.
- Transportation Agencies:These entities manage public transportation infrastructure, procuring paper for various ticketing needs.
- Entertainment Venues:This segment includes stadiums and theaters, requiring customized tickets and wristbands with security features.
- Access Management Firms:These companies specialize in security and entry systems, utilizing thermal paper for temporary passes.
Public Transport Operators represent a primary, high-volume consumer, while Retail Outlets face the most significant digital substitution pressures.
Distribution Channel:
The distribution pathways for thermal ticket paper vary based on customer size, geographic reach, and the complexity of required product customization and support services.
- Direct Sales:Manufacturers engage directly with large-volume end-users, such as major public transit authorities or large event organizers, allowing for customized orders and direct technical support. This channel enables closer client relationships.
- Distributors:These intermediaries purchase in bulk from manufacturers and resell to a fragmented base of smaller end-users across various industries and geographies. They provide logistical and localized support.
- Online Stores:E-commerce platforms facilitate purchases for small to medium-sized businesses, offering convenience and selection.
- Wholesale Traders:Wholesalers supply other resellers or very large enterprises with bulk quantities of standard thermal paper.
- OEM Partners:Thermal printer manufacturers often bundle or recommend specific thermal paper types, creating an indirect sales channel.
Direct Sales dominates for large-scale procurement, while Distributors ensure broad market penetration for smaller clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Chemicals Agency's (ECHA) REACH regulation significantly influences the direct thermal ticket paper market across Europe, driving the adoption of bisphenol-free formulations. This regulatory pressure creates a premium segment for compliant products, impacting manufacturers' strategic choices. Meanwhile, rapid public transit expansion in countries like China and India fuels consistent, high-volume demand for physical ticketing solutions.
Germany
Demand for direct thermal ticket paper in Germany stems from modernized public transit systems and a robust event management sector. The ECHA's REACH regulation heavily influences material composition, mandating a transition to phenol-free alternatives. Industrial clusters in the Rhine-Ruhr region and major cities like Berlin are actively integrating these compliant papers into their ticketing infrastructure.
United States
The United States market sees steady demand from event ticketing, venue management, and a growing need for specialty labels in logistics. US FDA rules governing food-contact receipts indirectly influence broader thermal paper material standards. Major urban centers like New York City and Los Angeles drive significant volume for physical tickets and access credentials.
China
China's extensive public transportation infrastructure development and modernization projects generate substantial, consistent demand for direct thermal ticket paper. The country's GB standards mandate specific quality and safety benchmarks for domestically sold products. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta regions are key production and consumption centers.
India
Public transit expansion across India, particularly in its rapidly urbanizing cities, creates a strong and sustained demand for thermal ticket paper. The Bureau of Indian Standards (BIS) influences general quality and safety protocols for various paper products. Major metropolitan areas such as Mumbai and Delhi-NCR are primary consumers for automated fare collection systems.
Japan
Japan's highly efficient public transit networks and sophisticated event industry maintain a consistent requirement for direct thermal ticket paper. The Ministry of Economy, Trade and Industry (METI) guides industrial standards and environmental policies impacting paper manufacturing. The Tokyo metropolitan area and Kansai region represent significant centers for both demand and technological adoption.
Global Direct Thermal Ticket Paper Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the direct thermal ticket paper market. This structure reflects a blend of large-scale pulp and paper manufacturers alongside specialized chemical coating companies. Strategic archetypes include global material suppliers, regional specialty producers, and niche innovators focusing on compliant formulations. Dominant competitive moves involve capacity expansion for phenol-free papers and strategic partnerships to integrate advanced coating technologies.
At the scale-driven end, Nippon Paper Industries Co., Ltd. and Oji Holdings Corporation, both Japan-based, exemplify global players leveraging extensive pulp manufacturing capabilities. Koehler Paper Group, a German entity, represents a specialist archetype, focusing on advanced phenol-free thermal paper technologies to secure positions in health-conscious markets. These companies anchor industry-level innovation in material science and process engineering across various global regions.
| Leading Market Players |
|---|
| Nippon Paper Industries Co., Ltd. |
| Hansol Paper Co. Ltd. |
| Ahlstrom-Munksjö Oyj |
| Koehler Paper Group |
| Ricoh Company, Ltd. |
| UPM-Kymmene Oyj |
| Domtar Corporation |
| Henan Province JiangHe Paper Co., Ltd. |
| Oji Holdings Corporation |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing of direct thermal ticket paper creates significant scale economies, driving supply concentration in key regions and establishing competitive price floors for standard formulations.
Pricing Analysis
Geographic price spreads for direct thermal ticket paper reflect regional regulatory compliance costs and local market demand dynamics. The market primarily uses a per-unit transactional pricing model. Price differentiation stems from phenol-free certification levels and customization for security features. Pricing pressure intensifies from digital ticketing solutions. Retail outlets exhibit the highest price sensitivity among end-users.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized chemical components, influence the global supply chain for direct thermal ticket paper. Supply concentration centers in China, Japan, and Germany for base paper and advanced coatings. The market relies on a limited number of global suppliers for leuco dyes and developers. Raw material concentration presents a structural supply chain risk. Distribution runs through direct sales for large operators and distributors for fragmented smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The direct thermal ticket paper market requires a robust substitution defense strategy, primarily against the pervasive threat of digital ticketing solutions.
For Market Incumbents:
Fortify core market positions by investing heavily in advanced phenol-free R&D and expanding production capacity for compliant formulations. This strategy mitigates regulatory threats like Europe's REACH and counters the erosion from digital substitution. Companies should also pursue certification investments for new chemistries. Strong R&D in coating chemistry is a critical lever.
For New Entrants and Emerging Players:
Lead with innovative, sustainable product offerings to penetrate niche applications such as medical wristbands and cold-chain logistics labels. The most penetrable segment lies within specialty adhesive label papers. A focused go-to-market angle involves developing fully recyclable or compostable thermal paper formulations.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among specialized coating companies offering proprietary phenol-free technologies with long-term contracts. Long-term viability rests on securing intellectual property in advanced material science over the next decade. Acquisition targets include mid-sized firms with strong R&D capabilities. The signal to watch is the expansion of stringent bisphenol regulations into emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Phenol-Free Paper | Increases supply of compliant products, meeting regulatory demand and securing market share. |
| R&D in Sustainable Formulations | Develops environmentally friendly options, appealing to eco-conscious consumers and venues. |
| Strategic Partnerships with Chemical Suppliers | Ensures stable access to critical leuco dyes and developers, mitigating supply chain risks. |
| Diversification into Adjacent Label Applications | Opens new revenue streams beyond traditional ticketing, leveraging existing thermal paper expertise. |
| Investment in Digital-Physical Hybrid Solutions | Integrates physical tickets with digital features, enhancing user experience and security for events. |
Research Approach
Operator-level perspectives from Public Transport Operators, Event Managers, Thermal Paper Manufacturers, and Chemical Suppliers anchored the qualitative base of this study. This primary intelligence, gathered through in-depth interviews, was triangulated with extensive secondary validation. Secondary sources included ECHA reports, industry association publications, company financial filings, and China's GB standards documents. A bottom-up and top-down approach ensured comprehensive data synthesis.
Sensitivity analysis informed the development of the forecast framework, accounting for various market scenarios across the analysis window. The model segmented demand by Product Type, Application, End User, Distribution Channel, and Regional Regulatory Regimes. Compound Annual Growth Rates were derived from historical market trends and projected shifts in end-user behavior. Key forecast inputs included public transit infrastructure investment rates and digital ticketing penetration rates.
Forecasts assume regulatory continuity in European and Chinese regimes; material policy shifts would require re-modeling. These projections reflect current market dynamics and known technological trajectories. Unforeseen global health crises or accelerated digital substitution represent significant risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
White Line Chipboard Market
Paper Products
Printing Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Duplex Paper and Board Market
Paper Products
Europe Coated Paper Market
Paper Products
Global Paperboard Market
Paper Products
Global Wood Pulp Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Africa Tissue Paper Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Greaseproof Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Metallized Paper Market
Paper Products
Woodfree Paper Market