

Super Calendered Glassine Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Super Calendered Glassine Paper Market Insights
The EU Green Deal and its packaging waste reduction targets is pivoting converter procurement toward certified renewable substrates. UPM-Kymmene leverages integrated pulp assets across Finnish mills to secure cost-advantaged feedstock for glassine grades. Sappi anchors its position through specialty cellulose expertise and controlled transparency in calendering operations. Mondi competes via geographic reach across Central European converting corridors.
Super calendered glassine paper is a dense, translucent sheet produced from refined chemical pulp subjected to intensive calendering, yielding a smooth surface with air permeability below 10 Gurley seconds and oil resistance critical for barrier applications. Its primary purpose centers on providing non-stick, greaseproof interfaces for food contact and pressure-sensitive adhesive systems. Silicone coated variants command premium positioning as release liner substrates for medical and industrial tape markets, while food wrapping applications sustain volume throughput across European converting lines. Reels dominate packaging type logistics due to continuous-web efficiency in high-speed coating and printing operations.
FDA food contact regulations and EU REACH compliance frameworks govern raw material purity and migration limits for glassine grades destined for edible product contact. ECHA substance restrictions and evolving PFAS thresholds in the European framework directly shape silicone formulation choices and release chemistry investments. Stakeholders must monitor regulatory tightening on fluorinated chemistries while calibrating capital allocation between barrier coating innovation and substrate lightweighting programs.
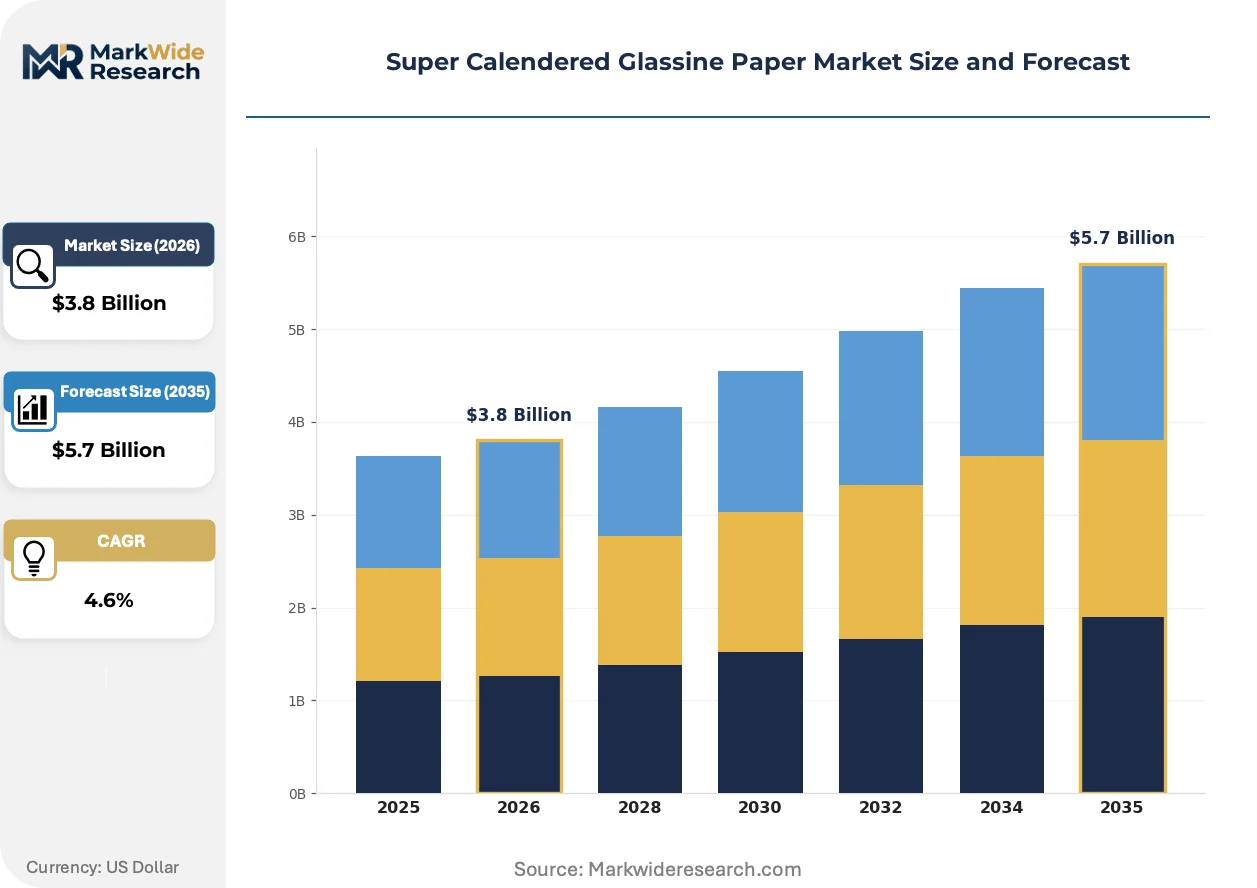
Market Dynamics
The EU Green Deal's packaging waste reduction mandates are forcing converters to abandon plastic films for certified renewable paper substrates, compressing qualification timelines and reshaping supplier certification hierarchies across European converting corridors.
Growth Catalysts
- EU Green Deal packaging directives:Mandatory plastic reduction targets in food contact applications are accelerating substrate substitution toward grease-resistant glassine grades. Finland and Austria lead implementation velocity.
- Silicone-coated release liners:Medical tape and industrial adhesive manufacturers are expanding specification of super calendered glassine for non-stick carrier applications. Demand concentrates in German automotive supply chains.
- Chemical pulp refining advances:Enhanced fiber homogenization processes are enabling sub-10 Gurley second air permeability without synthetic barrier coatings. Integrated Finnish mills capture process efficiency gains.
Market Restraints
- Softwood pulp price volatility:Nordic kraft pulp contracts exhibit cyclical swings that compress glassine producer margins during supply tightness. Long-term fiber hedging remains underutilized.
- PFAS regulatory friction:ECHA substance restrictions on fluorinated chemistries are forcing reformulation of legacy silicone release systems. Compliance timelines outpace R&D cycles.
- Plastic film residual cost advantage:Oriented polypropylene retains price competitiveness in non-food wrapping segments. Downgauging innovations in synthetic films delay paper substitution.
Strategic Opportunities
- Central European converting corridor expansion:Poland and Czech Republic packaging clusters lack indigenous glassine supply. Austrian and German producers can establish toll-coating partnerships.
- Pharmaceutical blister pack liners:Moisture-sensitive drug packaging represents an emerging specification avenue. EU MDR device traceability requirements favor certified substrate documentation.
- Digital print compatibility:Inkjet and toner adhesion on super calendered surfaces enables short-run customized food wrapping. Converters in Netherlands pilot variable-data premium chocolate packaging.
Industry Challenges
- Calendering operator skill scarcity:Intensive super calendering demands experienced roll-handling technicians. German and Austrian mills face retirement-driven knowledge gaps.
- Multi-jurisdiction certification complexity:Simultaneous FDA food contact and EU REACH compliance requires dual-track testing protocols. Smaller converters lack in-house regulatory affairs capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Calendered Glassine Paper Market Trends and Innovations
Water-based barrier coatings are displacing solvent systems across European converting lines, while digital workflow integration compresses proof-to-production cycles. These shifts are reconfiguring capital allocation between coating equipment and data infrastructure.
Water-based acrylic barrier formulations are overtaking solvent-borne polyethylene dispersions in food-grade glassine applications. German and Austrian packaging converters are adopting these systems to meet EU VOC emission thresholds. The transition is compressing incumbent coating suppliers' installed base value while opening specification windows for integrated pulp-to-paper producers with captive emulsion capabilities.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing silicone release chemistry reformulation across medical and industrial tape liner segments. ECHA consultation timelines are compressing supplier qualification windows to eighteen months. Finnish glassine producers with in-house polymer laboratories are accelerating PFAS-free adhesive validation ahead of enforcement dates.
Converter procurement patterns are consolidating toward direct mill relationships, bypassing traditional merchant distributors in high-volume food wrapping segments. Large German bakery and confectionery chains are mandating chain-of-custody documentation that distributors cannot economically provide. This disintermediation concentrates volume with integrated producers possessing FSC and PEFC certification depth.
Super Calendered Glassine Paper Market Segmentation
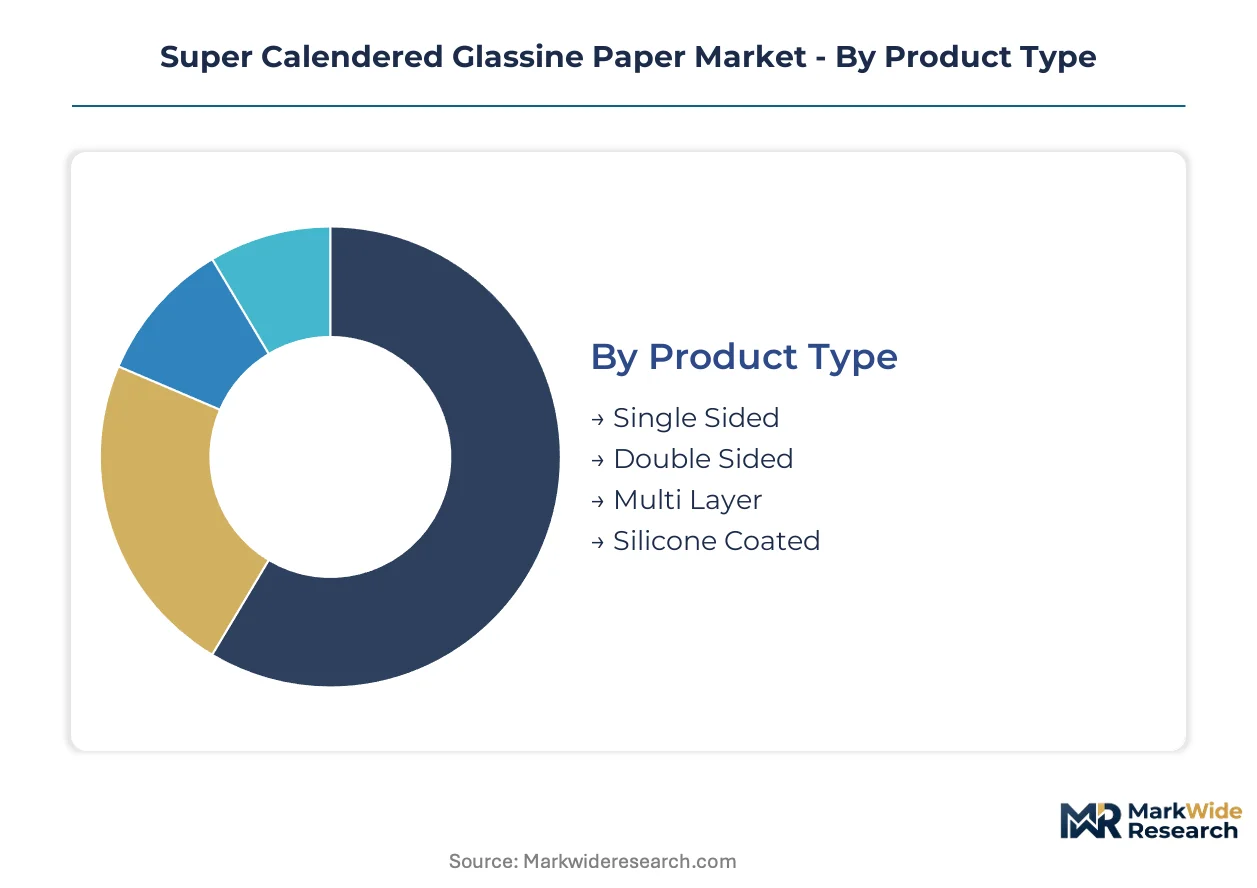
Super calendered glassine paper segmentation reveals how certification requirements, barrier specifications, and converting equipment compatibility fragment procurement patterns across European supply chains. Each dimension carries distinct regulatory burdens and margin profiles that reshape supplier-customer relationships.
Product Type:
Certification intensity varies sharply by coating complexity: uncoated grades navigate FDA food contact and EU REACH baseline compliance, while silicone-coated variants trigger additional ECHA substance restrictions and PFAS scrutiny.
- Silicone Coated:Calendered substrate receives platinum-catalyzed or tin-catalyzed silicone release layers for pressure-sensitive adhesive applications. German automotive tape manufacturers and Dutch medical device suppliers drive specification, though ECHA PFAS timelines compress reformulation windows to eighteen months.
- Single Sided:One-face smoothness enables grease-resistant food wrapping with controlled cost positioning. Austrian confectionery converters favor this grade for chocolate and bakery interleaving where barrier performance must balance against unit economics.
- Double Sided:Dual-face calendering delivers uniform translucency and release properties for label backing applications. Finnish integrated mills exploit captive pulp refining to achieve sub-10 Gurley second air permeability.
- Multi Layer:Laminated constructions combine glassine with wax or polymer barriers for extended moisture protection. Limited penetration outside pharmaceutical blister pack trials in Switzerland and Belgium.
Leading the category by volume: Single Sided. Growing fastest: Silicone Coated.
Application:
End-use segmentation tracks directly to converter capital equipment and line speed requirements, with food contact applications demanding the most intensive documentation chains.
- Food Wrapping:Greaseproof barrier for bakery, confectionery, and deli products requiring FDA and EU food contact compliance. German bakery chains now mandate FSC chain-of-custody documentation that disintermediates traditional distributors.
- Release Liners:Non-stick carrier substrates for industrial and medical adhesive tapes. Demand concentrates in German automotive supply chains where silicone-coated glassine displaces polyethylene film for temperature resistance.
- Label Backing:Smooth release surface for pressure-sensitive label stock. Dutch and Belgian label converters specify double-sided grades for high-speed die-cutting operations.
- Packaging Interleaving:Protective sheet separation for polished metals, glass, and electronics. Austrian specialty paper merchants serve Central European machinery exporters.
- Electrical Insulation:Dielectric barrier applications in transformers and capacitors. Niche specification governed by IEC standards, with Swiss electrical manufacturers representing primary European demand.
Dominant by throughput: Food Wrapping. Steepest expansion trajectory: Release Liners.
End User Industry:
Customer type determines order pattern economics, with integrated packaging manufacturers capturing scale advantages while specialized confectionery producers prioritize flexibility and short runs.
- Packaging Manufacturers:High-volume converters operating continuous-web coating and printing lines. Polish and Czech Republic clusters lack indigenous glassine supply, creating toll-coating partnership opportunities for Austrian and German producers.
- Confectionery Producers:Premium chocolate and bakery brands requiring customized wrapping with variable-data print compatibility. Netherlands pilots digital inkjet adhesion on super calendered surfaces for short-run premium packaging.
- Printing Houses:Commercial printers expanding into food-grade flexible packaging. EU VOC emission thresholds drive water-based acrylic barrier adoption over solvent systems.
- Electrical Manufacturers:Transformer and capacitor producers specifying dielectric-grade glassine. Swiss and German industrial electrical equipment makers maintain tight qualification protocols.
Volume leadership: Packaging Manufacturers. Fastest share gain: Confectionery Producers.
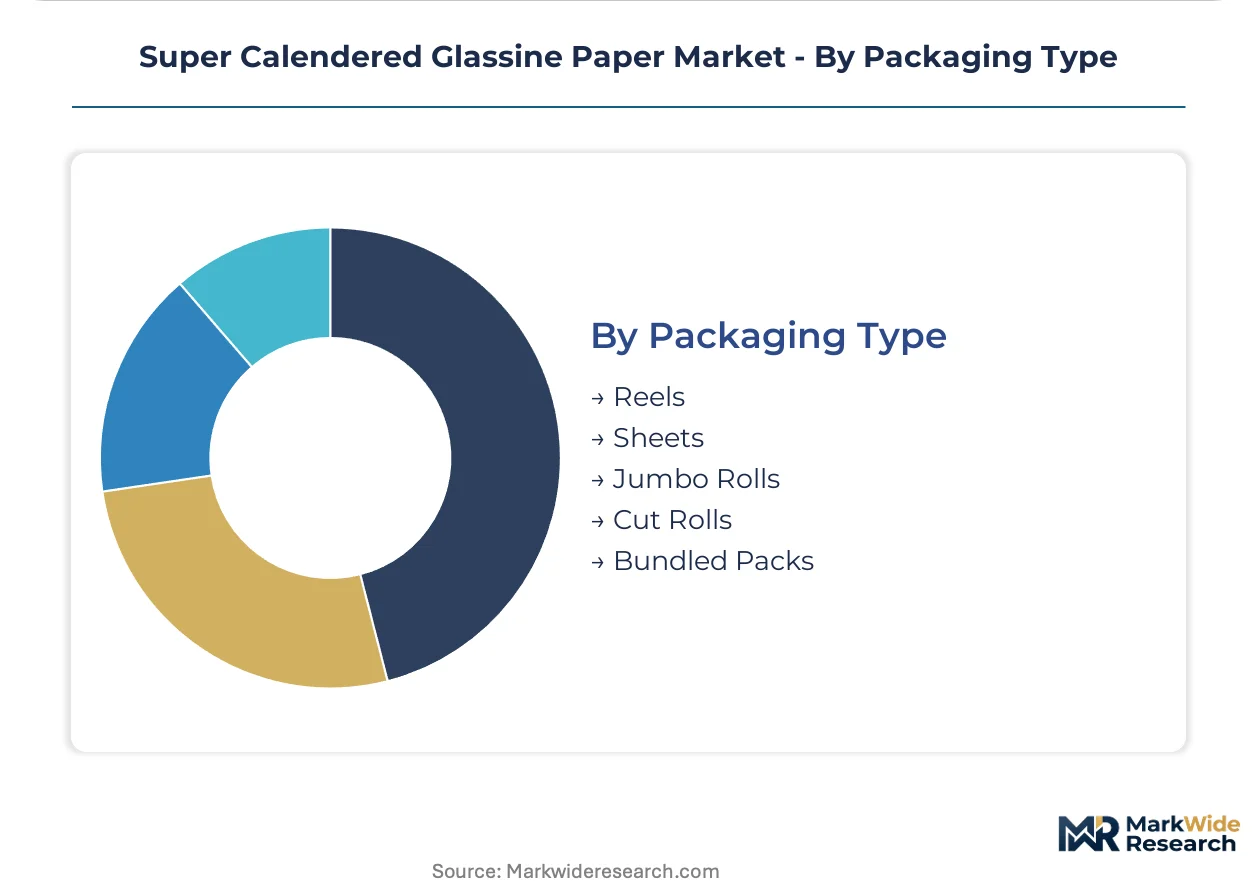
Packaging Type:
Logistics configuration aligns with converter equipment and inventory velocity, with reel formats dominating high-speed operations while sheet formats serve job-shop flexibility requirements.
- Reels:Continuous-web supply for high-speed coating, printing, and converting lines. Standard format across German and Austrian integrated pulp-to-paper producer deliveries.
- Jumbo Rolls:Large-diameter supply for toll coaters and major converting facilities. Enables efficient slitting operations at Central European packaging clusters.
- Sheets:Cut-to-size supply for job-shop printers and small-batch food processors. Higher unit cost offset by reduced waste for short-run applications.
- Cut Rolls:Narrow-width supply for specialized tape manufacturers and label converters. Common format for medical device release liner specifications.
- Bundled Packs:Pre-packaged sheet quantities for artisanal food producers and small printing operations. Limited penetration outside direct-to-craft market channels.
Primary volume: Reels. Fastest logistics innovation: Jumbo Rolls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland and Germany host the bulk of super calendered glassine paper production capacity, while converter demand concentrates in Central European packaging corridors stretching from Austria through Poland.
Germany
Automotive tape manufacturers and bakery chains drive specification of silicone-coated and food-grade glassine. EU REACH Annex XVII restrictions on PFAS substances compress reformulation timelines for release chemistry suppliers. The Rhine-Ruhr packaging cluster anchors converter demand, with major toll-coating facilities processing Finnish and Austrian mill supply.
Finland
Integrated pulp-to-paper producers leverage captive softwood kraft refining for sub-10 Gurley second air permeability grades. The EU Green Deal packaging waste directives accelerate domestic qualification of barrier-coated glassine for export markets. Tampere and Jämsänkoski mill complexes supply Central European converting lines with FSC-certified reels.
Austria
Confectionery interleaving applications sustain volume throughput for single-sided grades serving premium chocolate brands. ECHA consultation timelines on fluorinated chemistries force silicone formulation shifts ahead of enforcement dates. The Upper Austrian packaging corridor links Vienna-headquartered converters to German automotive supply chains.
Poland
Packaging clusters around Warsaw and Łódź lack indigenous glassine production, creating toll-coating partnership opportunities for Austrian and German mills. EU VOC emission thresholds drive water-based acrylic barrier adoption over solvent systems. The Central European converting corridor expansion concentrates demand for jumbo roll supply.
Switzerland
Pharmaceutical blister pack trials and electrical insulation specifications represent niche demand avenues. Swissmedic device traceability requirements favor certified substrate documentation for moisture-sensitive drug packaging. Basel-area pharmaceutical packaging developers pilot multi-layer laminated constructions.
Super Calendered Glassine Paper Market Competitive Landscape
The competitive structure tilts toward integrated forest products groups with captive pulp refining and calendering assets. Finnish and Austrian producers command supply advantages through backward integration into Nordic kraft pulp, while specialty cellulose expertise differentiates select players in medical-grade release liner segments. Two strategic archetypes dominate: integrated pulp-to-paper producers with certification depth, and specialty converters with toll-coating partnerships. Capacity expansion in barrier coating lines and direct mill-to-converter relationship building represent the dominant competitive moves.
Among Nordic integrated producers, UPM-Kymmene and Stora Enso exemplify the captive pulp refining archetype, leveraging Finnish mill assets for cost-advantaged feedstock. Sappi occupies a position bridging specialty cellulose expertise with controlled transparency in calendering operations. Mondi anchors the geographic reach vector across Central European converting corridors. Ahlstrom-Munksjö sits within the medical and industrial release liner specialization tier. These five represent distinct positioning vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| UPM-Kymmene |
| Sappi |
| Mondi |
| Ahlstrom-Munksjö |
| Stora Enso |
| Nippon Paper Industries |
| Delfortgroup |
| Lecta |
| Pudumjee Paper Products |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between silicone-coated release liners and uncoated food wrapping grades manifests in dual-track pricing ladders and supply chain configurations. Premium tiers tether to captive pulp refining in Finnish integrated mills, while commodity food-grade volumes flow through toll-coating partnerships in Central European corridors.
Pricing Analysis
Margin tightening in silicone-coated grades reflects ECHA PFAS reformulation timelines compressing supplier qualification windows to eighteen months. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—FSC chain-of-custody documentation commands premium positioning for German bakery chains, while toll-coated volumes serve price-sensitive Polish packaging clusters. Cost-down pressure on uncoated food wrapping accelerates because water-based acrylic barrier transitions displace solvent systems. Confectionery producers exhibit highest price sensitivity; medical tape manufacturers absorb premium positioning for temperature-resistant release chemistry.
Supply Chain Analysis
Retirement-driven knowledge gaps among calendering roll-handling technicians constrain output expansion in German and Austrian mill complexes. Supply concentrates in Finland, Germany, and Austria, with Nordic kraft pulp refining feeding captive production networks. Raw material flows draw from softwood kraft pulp contracts, platinum-catalyzed silicone formulations, and water-based acrylic barrier emulsions. Single-source vulnerability sits with Nordic pulp supply during cyclical tightness. Distribution runs through direct mill-to-converter relationships bypassing traditional merchant distributors for high-volume food wrapping segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Super calendered glassine paper supply is tightening around calendering operator scarcity and ECHA compliance timelines, propping pricing power for integrated producers with in-house polymer laboratories.
For Market Incumbents: Cement backward integration into captive pulp refining to secure cost-advantaged feedstock against Nordic kraft pulp volatility. Deepen FSC and PEFC certification depth to capture German bakery chain procurement consolidating toward direct mill relationships. Defend against PFAS regulatory friction by accelerating in-house silicone reformulation ahead of enforcement dates. For New Entrants and Emerging Players: Enter via toll-coating partnerships in Poland and Czech Republic packaging clusters lacking indigenous glassine supply. Target pharmaceutical blister pack liner trials in Switzerland and Belgium where moisture-sensitive drug packaging specifications remain underpenetrated. Lead with digital print compatibility pilots for short-run premium chocolate packaging in Netherlands converting corridors. For Investors and Strategic Acquirers: Re-rating potential sits with integrated pulp-to-paper producers given EU Green Deal packaging waste directive acceleration. Long-term viability over a multi-year window favors archetypes with captive softwood kraft refining and barrier coating line capacity. Monitor ECHA consultation timelines on fluorinated chemistries as inflection indicator for release chemistry supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Line Expansion | Captive water-based acrylic capacity captures EU VOC emission threshold compliance ahead of solvent system phase-out. |
| PFAS-Free Silicone Reformulation | In-house polymer laboratory validation ahead of ECHA enforcement dates secures medical tape liner specifications. |
| Direct Mill-to-Converter Relationships | FSC chain-of-custody documentation meets German bakery chain procurement mandates disintermediating distributors. |
| Central European Toll-Coating Partnerships | Polish and Czech packaging cluster access fills geographic supply gap without greenfield mill investment. |
| Digital Print Surface Engineering | Inkjet adhesion optimization enables Netherlands premium chocolate packaging pilots for variable-data short runs. |
Research Methodology
Independent corroboration across mill operations directors, converting procurement leads, silicone chemistry formulators, and regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EU ECHA consultation documents, FDA food contact guidance, FSC chain-of-custody databases, and Nordic pulp trade association statistics. Bottom-up volume triangulation against top-down spending pattern analysis calibrated segment-level outputs.
Rate-of-change decomposition across product type, application, end user industry, packaging format, and regional regulatory cluster shaped the analytical framework. CAGRs derived from slope-consistency checks against historical pulp-to-paper margin patterns and converter capacity utilization trajectories. Forecast inputs incorporated EU Green Deal implementation velocity and PFAS substitution timeline uncertainty.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA enforcement or Nordic pulp supply disruption scenarios. Projections reflect assumptions on barrier coating technology adoption curves and certification program penetration rates. Material deviation in EU packaging waste directive implementation timelines or softwood pulp contract volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.