
 GCC Stone Paper Market | 2026-2036
GCC Stone Paper Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Stone Paper Market Intelligence
The GCC stone paper supply base is pivoting between premium certified grades and commodity extrusion outputs. Shanxi Uni-Moon Lungmeng Green Paper Co. Ltd anchors its position through backward integration into calcium carbonate sourcing. Taiwan Lung Meng Technology Co. Ltd differentiates via proprietary coating formulations that sustain higher print resolution. STP STONE PAPER GmbH competes on European technical standards adapted for Gulf humidity conditions.
Stone paper consists of calcium carbonate bonded with a small proportion of high-density polyethylene resin through extrusion-based manufacturing, yielding a waterproof, tear-resistant substrate that replaces wood-pulp paper in moisture-sensitive applications. The extrusion technology segment leads production scale, while coating and laminating variants capture margin pools in food-contact packaging. Application demand clusters in packaging and stationery, with advertising-grade rolls expanding fastest among commercial print buyers seeking weatherproof display materials.
Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Ministry of Industry and Advanced Technology shape product compliance through packaging material safety protocols and recycled content disclosure rules. The Emirates Authority for Standardization and Metrology (ESMA) enforces biodegradability claims verification, tightening market access for uncertified imports. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks on polymer-content thresholds that could redefine qualifying products.
Market Dynamics
Calcium carbonate supply concentration in Shanxi Province is reshaping GCC stone paper sourcing economics, forcing Gulf converters to secure long-term offtake agreements or absorb volatile resin-carbonate spread differentials.
Growth Catalysts
- SASO quality mark mandates:Saudi Arabia's packaging material safety protocols now explicitly recognize stone paper for food-contact applications, accelerating substitution of polyethylene-coated board in Riyadh's quick-service restaurant chains.
- UAE circular economy frameworks:Dubai's 2030 waste diversion targets classify calcium carbonate-based substrates as preferred alternatives to wood-pulp imports, triggering municipal procurement preference shifts across emirate-level purchasing authorities.
- Extrusion coating advances:Proprietary surface treatment technologies enable direct thermal printing without primer layers, opening high-volume receipt and label applications previously blocked by ink-adhesion failures.
Market Restraints
- High-density polyethylene resin price volatility:Feedstock exposure to naphtha-cracker margins in Northeast Asian supply basins compresses converter margins during petrochemical upcycles.
- Single-source calcium carbonate dependence:Premium brightness grades rely on three Shanxi-based mines, creating geographic concentration risk for GCC manufacturers lacking backward integration into mining operations.
- Biodegradability claim verification:ESMA's enforcement of Gulf-standard composting protocols rejects oxo-degradable additive formulations, disqualifying legacy stone paper stocks from Abu Dhabi government tenders.
Strategic Opportunities
- Kuwait's underpenetrated retail packaging sector:Limited domestic extrusion capacity creates import substitution potential for UAE-based converters with SASO-ESMA dual certification.
- Pharmaceutical blister pack convergence:Heat-sealable stone paper laminates combining aluminum barrier layers address moisture-sensitive drug packaging in Jeddah's growing generics manufacturing cluster.
- E-commerce direct-to-merchant channels:Bypassing traditional paper distributors, stone paper suppliers now route waterproof mailer bags through Shopify-integrated fulfillment platforms serving Dubai's SME retail base.
Industry Challenges
- Extrusion technician scarcity:GCC universities lack polymer processing programs, forcing manufacturers to recruit experienced operators from Taiwan and Thailand at premium expatriate compensation packages.
- Dual certification timeline compression:SASO quality mark and ESMA biodegradability approvals require sequential 18-month validation cycles, delaying product launches for new market entrants.
- Legacy printing press incompatibility:Conventional offset units in Sharjah's commercial print clusters require $40,000-$80,000 dryer modifications to handle stone paper's lower moisture absorption and higher static charge profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Stone Paper Market |
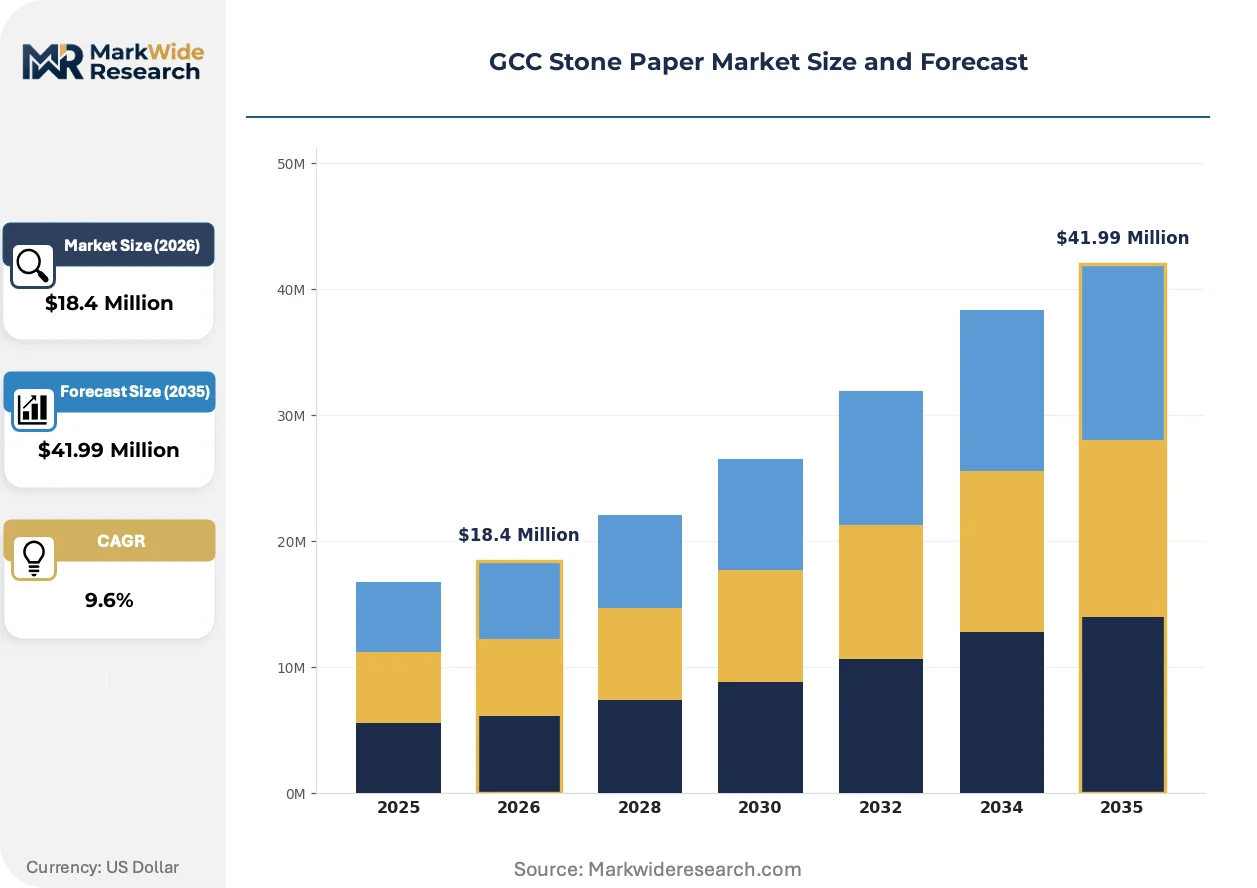
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $41.99 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Rolls, Bags, Labels Application: Packaging, Stationery, Printing, Advertising End User: Consumer Goods, Education, Healthcare, Retail Technology: Extrusion, Coating, Laminating, Converting |
| Companies Covered | Shanxi Uni-Moon Lungmeng Green Paper Co. Ltd, Taiwan Lung Meng Technology Co. Ltd, Pishgaman Sanat Sabz Company, STP STONE PAPER GmbH, Sòluz Stone Paper S.A., Azerbaijan Green Paper Company, Stone Paper Company Ltd., Sphera International, Hangzhou Gerson Paper Co. Ltd, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Stone Paper Market Strategic Shifts & Innovations
Coating formulation advances and regulatory disclosure mandates are compressing product development cycles while fragmenting buyer segments between certified premium grades and commodity extrusion outputs.
Multi-layer co-extrusion systems incorporating calcium carbonate loadings above 80% by weight are electrifying waterproof notebook and outdoor signage applications. Dubai's hospitality procurement departments now specify these substrates for poolside menus and marine-grade display materials. The technology is compressing demand for traditional synthetic papers in moisture-exposed environments across the emirate's tourism infrastructure.
SASO's recycled content disclosure rules now require polymer-source traceability for all packaging materials sold in Saudi Arabia. Industrial consequence includes mandatory blockchain-documentation of high-density polyethylene resin origins from Qatari and Kuwaiti petrochemical suppliers. Food-grade bag manufacturers in Jeddah's industrial zone are responding by segregating production lines between GCC-sourced and Asian-imported resin streams to maintain compliance eligibility.
Buying committees at UAE retail chains now mandate lifecycle assessment documentation prior to supplier onboarding, displacing price-only procurement for private-label packaging. Sustainability officers in Abu Dhabi's mall operators are consolidating vendor panels to three certified stone paper converters with verified carbon footprint data. This pattern is most visible in Dubai's luxury retail corridor, where brand-tenant lease agreements now embed packaging sustainability clauses enforceable by landlord technical compliance teams.
GCC Stone Paper Market Segmentation
Certification requirements fragment the GCC stone paper landscape into SASO-compliant and ESMA-verified tiers, with each segment carrying distinct approval timelines and polymer-content thresholds. Buyers navigate this complexity by matching substrate specifications to end-use regulatory exposure.
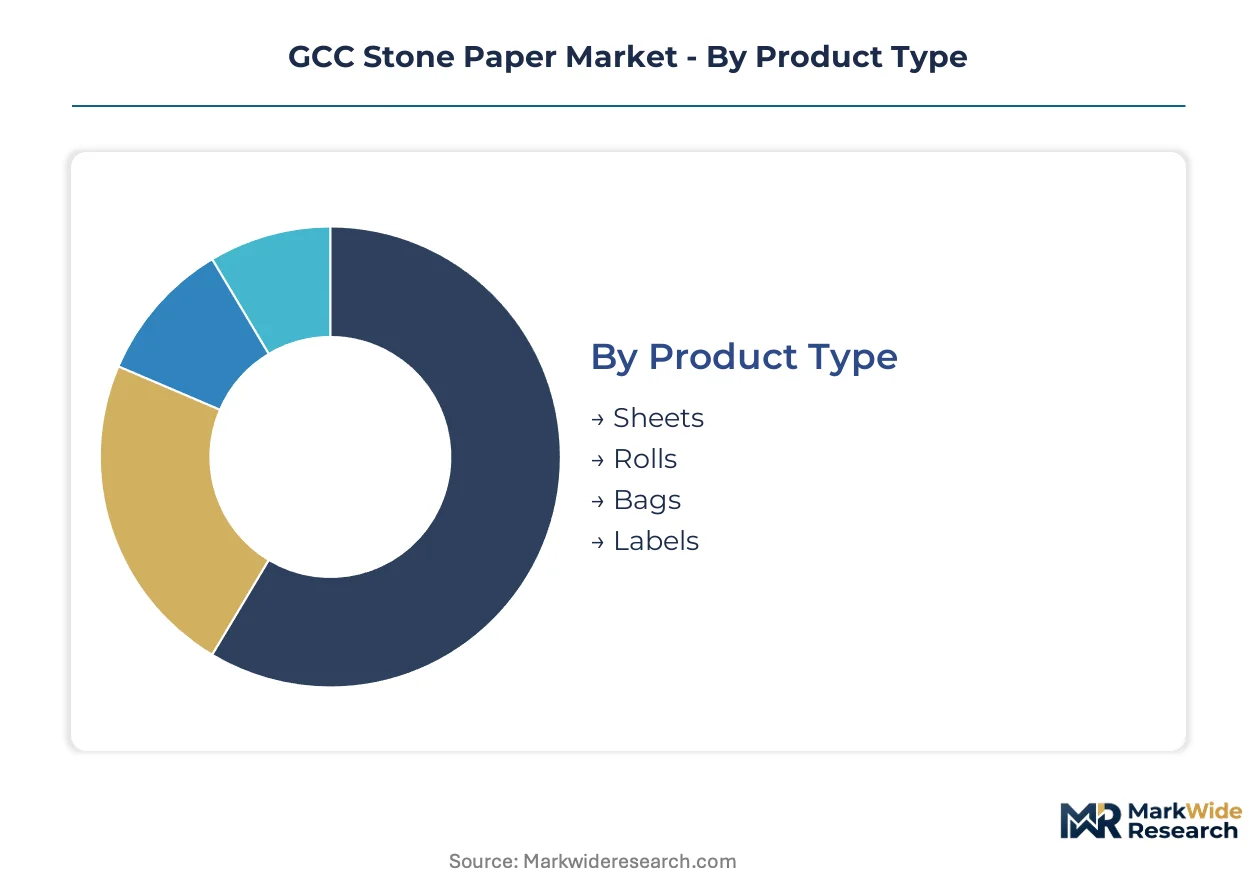
Product Type:
Sheets and rolls carry the heaviest certification burden for food-contact applications under SASO quality mark protocols, while bags and labels face stricter biodegradability verification through ESMA's composting standards.
- Sheets:Flat-cut substrates with calcium carbonate loadings above 80% serve premium stationery and menu applications. Dubai's hospitality procurement departments specify these for poolside and marine-grade environments where moisture resistance commands priority.
- Rolls:Continuous-web formats enable high-volume commercial printing. Abu Dhabi's advertising agencies favor these for weatherproof outdoor displays, though converters must absorb static-control equipment modifications.
- Bags:Food-grade variants require sequential SASO-ESMA validation cycles. Jeddah's quick-service restaurant chains substitute these for polyethylene-coated board under Saudi packaging safety protocols.
- Labels:Direct thermal printing compatibility depends on proprietary surface treatments. Receipt applications in UAE retail chains are expanding as coating advances eliminate primer-layer requirements.
Rolls sit at the top of the volume ranking, with bags climbing the fastest.
Application:
Cost tier differentiation separates moisture-sensitive packaging from commodity stationery, with print buyers absorbing premium pricing for weatherproof advertising substrates.
- Packaging:Food-contact and retail bag applications dominate procurement volumes. SASO's explicit recognition of stone paper for food-contact use accelerates substitution in Saudi quick-service chains, while Dubai's waste diversion targets classify calcium carbonate substrates as preferred alternatives to wood-pulp imports.
- Stationery:Waterproof notebooks and notebooks command margin pools in UAE education supply contracts. Multi-layer co-extrusion systems with elevated calcium carbonate loadings electrify demand across Dubai's tourism infrastructure for poolside menus.
- Printing:Commercial print buyers in Sharjah face $40,000-$80,000 dryer modifications to handle stone paper's lower moisture absorption. Offset press incompatibility constrains adoption despite substrate cost advantages.
- Advertising:Weatherproof display materials represent the steepest expansion trajectory among commercial print buyers. Outdoor signage applications in Abu Dhabi's mall operators consolidate vendor panels to certified converters with verified carbon footprint data.
Packaging captures the largest revenue share, with advertising gaining share fastest.
End User:
Customer type determines procurement sophistication, with retail chains mandating lifecycle assessment documentation and education buyers prioritizing cost per unit.
- Consumer Goods:Private-label packaging drives demand for certified grades with blockchain-documented resin origins. Brand-tenant lease agreements in Dubai's luxury retail corridor embed sustainability clauses enforceable by landlord compliance teams.
- Education:School supply contracts in Saudi Arabia and the UAE favor economy extrusion outputs. Price-sensitive procurement limits penetration of premium coated grades despite superior durability.
- Healthcare:Pharmaceutical blister pack applications require heat-sealable laminates combining aluminum barrier layers. Jeddah's generics manufacturing cluster presents convergence opportunities for moisture-sensitive drug packaging.
- Retail:UAE retail chain buying committees consolidate vendor panels to three certified converters. Sustainability officers in Abu Dhabi's mall operators now mandate verified carbon footprint data prior to supplier onboarding.
Retail leads end-user volume, with healthcare expanding most quickly.
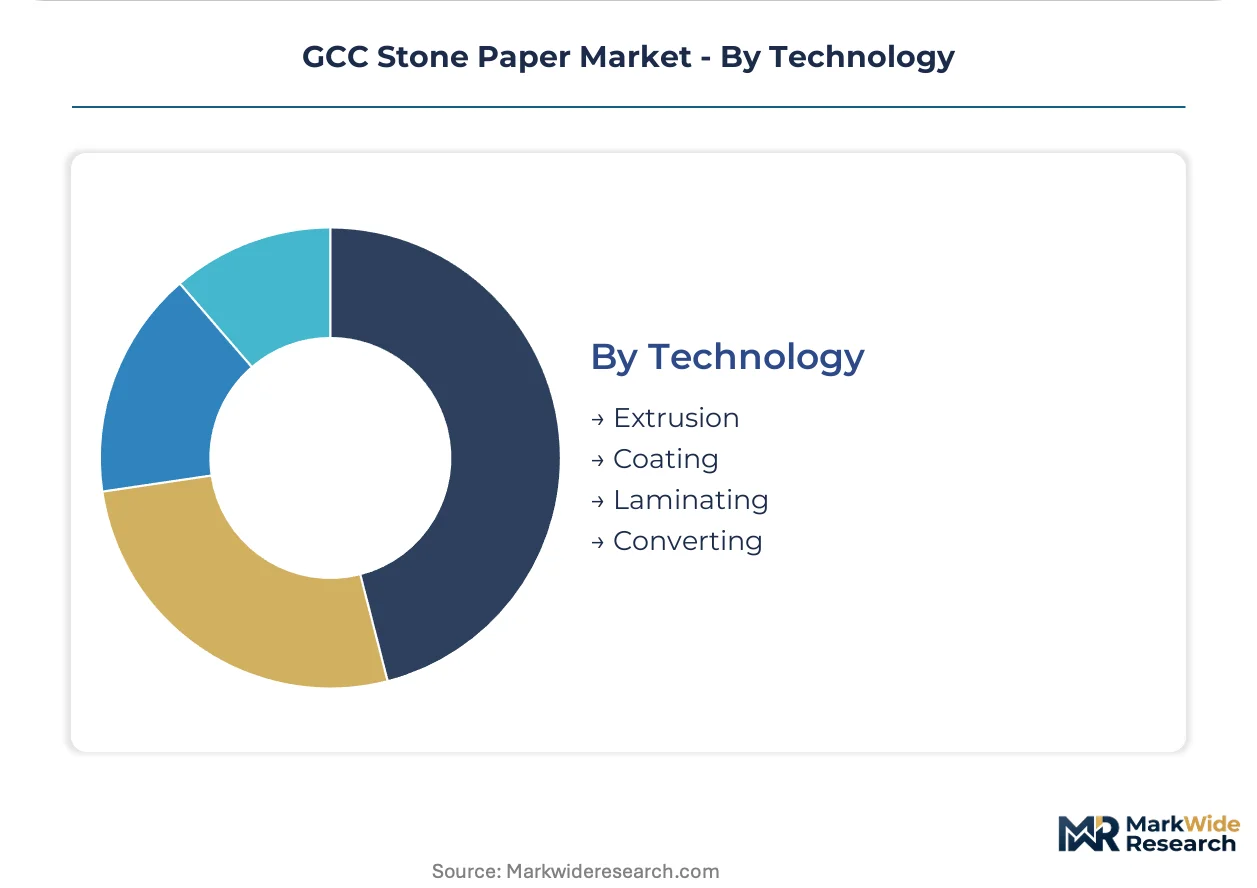
Technology:
Supply concentration in extrusion capacity shapes competitive positioning, while coating and laminating variants capture margin pools through proprietary formulation barriers.
- Extrusion:Dominant production scale bonds calcium carbonate with high-density polyethylene resin. Shanxi Province's mine concentration forces Gulf converters to secure long-term offtake agreements or absorb volatile resin-carbonate spread differentials.
- Coating:Proprietary surface treatments enable direct thermal printing without primer layers. Taiwan Lung Meng Technology Co. Ltd differentiates through formulations sustaining higher print resolution.
- Laminating:Multi-layer constructions address pharmaceutical and food-barrier applications. Heat-sealable stone paper laminates with aluminum layers target Jeddah's growing generics cluster.
- Converting:Final-stage processing into bags, labels, and finished stationery. GCC universities lack polymer processing programs, forcing manufacturers to recruit experienced operators from Taiwan and Thailand at premium expatriate compensation packages.
Extrusion dominates production volume, with coating gaining margin share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands larger procurement volumes than the UAE, yet Dubai's commercial corridors extract steeper premiums per ton for certified food-grade substrates.
Saudi Arabia
Riyadh's quick-service restaurant chains drive substitution of polyethylene-coated board with SASO-certified stone paper bags. The Saudi Standards, Metrology and Quality Organization mandates blockchain-documented resin origins for all packaging materials sold domestically. Jeddah's industrial zone manufacturers segregate production lines between GCC-sourced and Asian-imported resin streams to maintain compliance eligibility.
United Arab Emirates
Dubai's 2030 waste diversion targets classify calcium carbonate-based substrates as preferred alternatives to wood-pulp imports. The Emirates Authority for Standardization and Metrology enforces biodegradability claims verification that rejects oxo-degradable additive formulations. Abu Dhabi's mall operators consolidate vendor panels to three certified converters with verified carbon footprint data for luxury retail packaging.
Kuwait
Limited domestic extrusion capacity creates import substitution potential for UAE-based converters holding dual SASO-ESMA certification. The country's national standards body aligns packaging material safety protocols with Gulf Cooperation Council harmonization talks. Kuwait City's retail packaging sector remains underpenetrated by certified stone paper suppliers despite proximity to established Gulf converters.
Qatar
Petrochemical suppliers in Ras Laffan Industrial City provide high-density polyethylene resin streams traceable under emerging GCC polymer-content disclosure rules. The national quality infrastructure regulator participates in regional harmonization on recycled content thresholds. Doha's hospitality procurement departments specify waterproof substrates for marine-exposed display materials across tourism infrastructure.
Bahrain
Small-scale converting operations serve niche stationery demand from education sector contracts. The national standards organization adopts SASO-equivalent quality mark requirements for imported packaging materials. Manama's commercial print clusters face equipment modification barriers similar to Sharjah's offset press incompatibility challenges.
GCC Stone Paper Market Key Industry Players
Top-tier vendors anchor premium certified grades, while commodity extrusion specialists compete on volume throughput and resin-carbonate spread management. The GCC supply base fragments between Asian-origin manufacturers with backward integration into calcium carbonate mining and European converters adapting technical standards for Gulf humidity conditions. Three strategic archetypes dominate: Shanxi-based integrated miners, Taiwanese coating technology specialists, and German technical standards adapters. Competitive moves concentrate on long-term offtake agreements with Shanxi mines and sequential dual-certification timelines for SASO-ESMA compliance.
Within the integrated mining tier, Shanxi Uni-Moon Lungmeng Green Paper Co. Ltd represents upstream control over calcium carbonate sourcing. Taiwan Lung Meng Technology Co. Ltd exemplifies proprietary coating formulation specialists enabling higher print resolution applications. STP STONE PAPER GmbH occupies a position as the European technical standards adapter for Gulf humidity conditions. These three anchors illustrate how geographic origin and company structure map to distinct competitive positioning archetypes in the GCC procurement landscape.
| Leading Market Players |
|---|
| Shanxi Uni-Moon Lungmeng Green Paper Co. Ltd |
| Taiwan Lung Meng Technology Co. Ltd |
| Pishgaman Sanat Sabz Company |
| STP STONE PAPER GmbH |
| Sòluz Stone Paper S.A. |
| Azerbaijan Green Paper Company |
| Stone Paper Company Ltd. |
| Sphera International |
| Hangzhou Gerson Paper Co. Ltd |
| Others |
Cost & Logistics Intelligence
Calcium carbonate feedstock costs cascade through GCC stone paper pricing tiers from Shanxi Province mines to Jeddah converters, with resin-carbonate spread differentials compressing margins for non-integrated extrusion specialists while SASO-certified grades command premium placement in Saudi food-contact applications.
Pricing Analysis
Capacity additions in UAE extrusion facilities are reshaping price floors for standard-grade stone paper rolls. Three-tier pricing structure across premium, standard, and economy levels separates SASO-ESMA dual-certified food-grade bags from commodity stationery outputs. Pricing pressure stems from volatile high-density polyethylene resin exposure to Asian naphtha-cracker margins. Education sector buyers in Saudi Arabia exhibit highest price sensitivity, while Dubai luxury retail chains absorb premiums for blockchain-documented resin origins.
Supply Chain Analysis
Reverse-logistics flows for stone paper waste streams remain underdeveloped across GCC municipal collection systems, limiting closed-loop material recovery. Geographic concentration centers on China for calcium carbonate mining, Taiwan for coating formulation technology, and Germany for humidity-adapted technical standards. Raw material dependencies span Shanxi-mined calcium carbonate, Qatari and Kuwaiti petrochemical resin streams, and proprietary coating additives. Single-source vulnerability in premium brightness grades from three Shanxi mines creates supply risk. Distribution runs through Dubai and Jeddah commercial corridors to Kuwait and Bahrain converting operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC stone paper functions as a stable compounder where regulatory certification mandates generate recurring replacement demand across packaging and stationery applications.
For Market Incumbents: Deepen backward integration into calcium carbonate offtake agreements with Shanxi mining consortiums to defend against resin-carbonate spread volatility. Secure sequential SASO-ESMA dual certification ahead of Gulf Cooperation Council harmonization talks to lock out emerging competitors from government tender eligibility. For New Entrants and Emerging Players: Proprietary coating formulations enabling direct thermal printing without primer layers open white-space in UAE retail receipt and label applications. Kuwait's underpenetrated retail packaging sector offers lowest competitive density for SASO-ESMA certified converters. Route waterproof e-commerce mailer bags through Shopify-integrated fulfillment platforms serving Dubai's SME retail base. For Investors and Strategic Acquirers: Consolidation pressure builds where extrusion technician scarcity and 18-month dual-certification timelines create barriers to organic capacity expansion. Long-term viability favors converters with captive calcium carbonate supply or exclusive coating technology licenses. Monitor Gulf Cooperation Council polymer-content threshold harmonization talks as inflection signal for product qualification rule changes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calcium Carbonate Mining | Shanxi Province offtake agreements secure feedstock cost stability against volatile resin spreads. |
| SASO-ESMA Dual Certification Investment | Sequential 18-month validation cycles lock in government tender eligibility before harmonization shifts. |
| Proprietary Coating Technology Licensing | Taiwan-origin surface treatments sustain higher print resolution for direct thermal receipt applications. |
| E-commerce Channel Bypass | Shopify-integrated fulfillment platforms displace traditional paper distributors in Dubai SME segments. |
| Pharmaceutical Laminate Development | Heat-sealable aluminum barrier layers target Jeddah generics manufacturing moisture-sensitive packaging. |
Research Approach
Direct dialogue with extrusion plant managers, procurement leads at Saudi quick-service restaurant chains, coating technology specialists in Taiwan, and ESMA compliance officers grounded qualitative findings. Secondary validation drew from SASO quality mark documentation, UAE Ministry of Industry circular economy frameworks, customs records of calcium carbonate imports, and SEC filings of listed petrochemical suppliers. Bottom-up capacity assessments and top-down demand projections were triangulated against converter shipment data.
Segment-level outputs across product type, application, end user, and technology dimensions were generated through the analytical framework. CAGRs were derived from regression analysis of historical extrusion capacity additions against regulatory mandate implementation timelines. Forecast inputs incorporated polymer-content disclosure rule evolution and hospitality procurement specification shifts in Dubai tourism infrastructure.
The model holds under stable GCC regulatory harmonization trajectories; deviation in polymer-content threshold negotiations or Shanxi mining export restrictions would shift supply availability assumptions. Practitioners should monitor Gulf Cooperation Council technical committee proceedings and Emirates Authority for Standardization and Metrology enforcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Photographic Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Metallized Paper Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Decor Paper Market
Paper Products
Woodfree Paper Market
Paper Products
Hardwood Pulp Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Printing Paper Market
Paper Products
Paper Machine Systems Market
Paper Products
Household Paper Market
Paper Products
Veneer Sheets Market
Paper Products
Paper Machinery Market
Paper Products
Europe Coated Paper Market
Paper Products
White Line Chipboard Market