
 Global Paperboard Market | 2026-2036
Global Paperboard Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paperboard Market Analysis
Millwright and pulp-processing technician availability is collapsing across Nordic and North American mills, constraining capacity expansion timelines. International Paper sustains North American containerboard leadership through integrated fiber sourcing and mill network density. Mondi Group leverages European recycled-fiber expertise to anchor premium folding boxboard supply for FMCG brands. Smurfit Kappa dominates corrugated packaging demand across Iberian and Latin American markets through recycled-containerboard specialization.
Paperboard denotes a thick, paper-based material typically manufactured above 224 grams per square meter through multi-ply forming, calendering, and surface coating processes, engineered to provide structural rigidity, printability, and barrier protection for commercial and industrial applications. Containerboard commands the largest volume position due to e-commerce shipping demand, yet folding boxboard captures disproportionate margin pools from cosmetics and pharmaceutical blister pack applications. Virgin-material grades retain pricing premiums in food-contact segments where FDA and EFSA purity standards limit recycled-fiber substitution, while recycled-content containerboard competes aggressively on unit economics in non-food secondary packaging.
FDA food-contact regulations, EU REACH chemical compliance frameworks, and China's GB standards collectively shape product formulation, barrier coating chemistry, and cross-border market access for paperboard manufacturers. The EU Green Deal's packaging waste directives and extended producer responsibility schemes are redirecting R&D investment toward fiber-based barrier technologies that displace plastic laminates. Stakeholders must monitor fiber cost volatility, regulatory timeline convergence across the US, Europe, and China, and the pace of commercial-scale biodegradable coating deployment to align capacity decisions with evolving compliance and customer specifications.
Market Dynamics
E-commerce fulfillment packaging is compressing lead times and forcing fiber sourcing decisions closer to coastal logistics hubs across Asia-Pacific manufacturing belts.
Growth Catalysts
- EU Green Deal packaging directives:Extended producer responsibility schemes mandate recycled-content thresholds, redirecting investment toward fiber-based barrier coating R&D.
- India's industrial corridors:FMCG brand localization and pharmaceutical blister pack demand concentrate folding boxboard consumption in Gujarat and Maharashtra manufacturing zones.
- Biodegradable coating chemistry:Water-based and bio-polymer barrier technologies enable plastic-laminate substitution in food-contact segments previously locked to virgin fiber grades.
Market Restraints
- Softwood pulp cost volatility:Nordic and Canadian fiber supply disruptions transmit directly to virgin-material grade pricing, compressing margin buffers for specialty converters.
- Millwright labor scarcity:Technical workforce gaps across Sweden, Finland, and US Pacific Northwest constrain brownfield expansion timelines and maintenance scheduling flexibility.
- GB standards fragmentation:China's national food-contact purity requirements diverge from FDA and EFSA frameworks, forcing dual-certification overhead for export-oriented producers.
Strategic Opportunities
- Vietnam and Indonesia logistics hubs:Underdeveloped domestic containerboard capacity relative to e-commerce growth rates creates import substitution potential for regional recycled-fiber specialists.
- Pharmaceutical serialization mandates:EU Falsified Medicines Directive and US DSCSA track-and-trace requirements elevate demand for tamper-evident folding boxboard with integrated authentication features.
- Carbon border adjustment mechanisms:EU CBAM scope expansion toward paper products incentivizes low-carbon fiber sourcing and energy-efficient mill retrofits ahead of compliance deadlines.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and GB standard compliance stretches technical documentation and testing capacity, delaying new product commercialization.
- Legacy coating line retrofit complexity:Shifting from solvent-based to aqueous barrier systems requires capital-intensive drying infrastructure upgrades with extended commissioning periods.
- Recycled fiber contamination control:Post-consumer collection quality variability in emerging markets degrades containerboard strength specifications, forcing yield losses or virgin fiber blending.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paperboard Market |
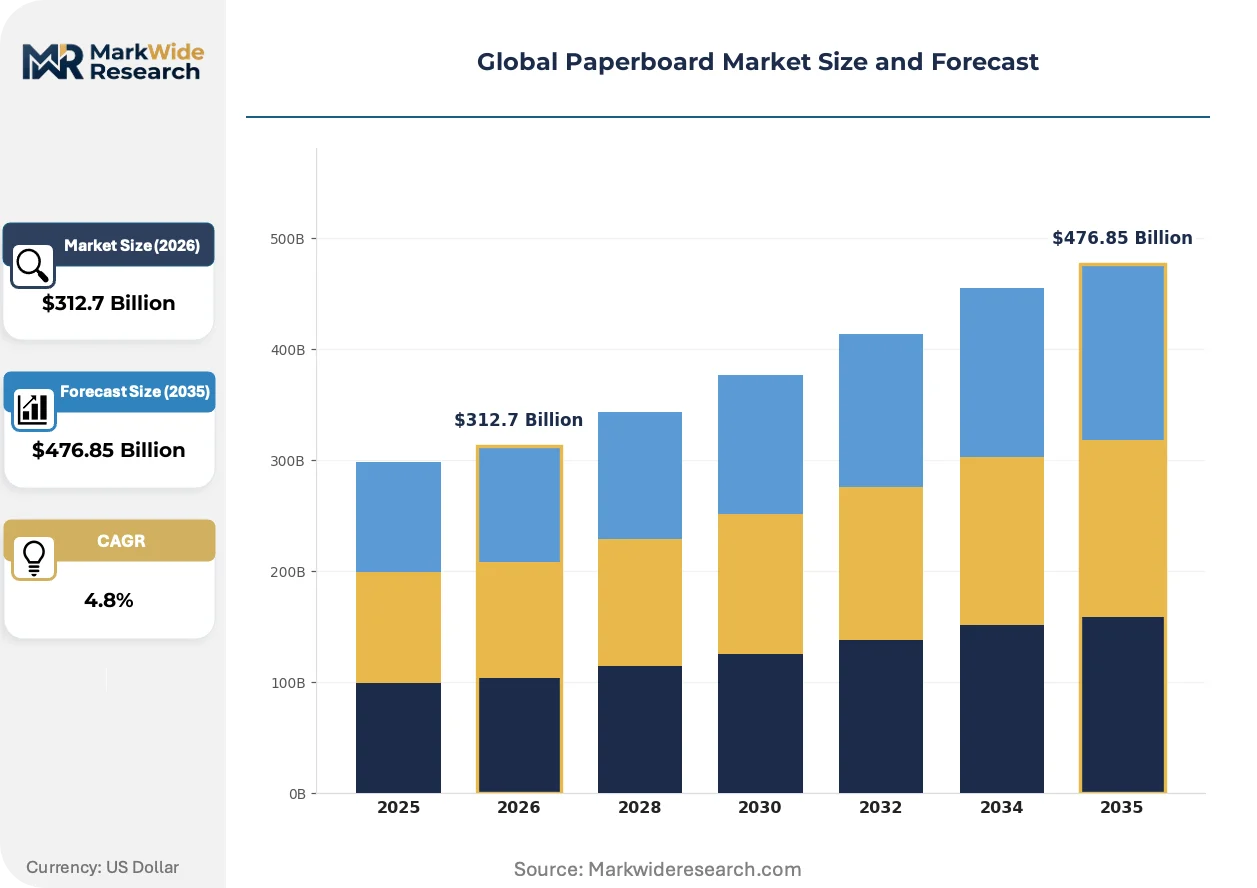
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containerboard, Folding Boxboard, Coated Paperboard, Uncoated Paperboard End Use: Packaging, Printing, Stationery, Construction Material: Recycled, Virgin, Composite, Laminated Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | WestRock Company, International Paper, Mondi Group, Stora Enso, Smurfit Kappa, Oji Holdings, Nine Dragons Paper, DS Smith, Nippon Paper Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paperboard Market Emerging Trajectories
Fiber-based barrier technologies and regulatory chemistry restrictions are actively restructuring competitive capabilities across food-contact and pharmaceutical packaging segments.
Water-based and bio-derived barrier coatings are displacing polyethylene laminates in chilled and dry food applications. Major European retail private-label programs now specify fiber-only packaging for ready-meal segments. This chemistry transition compresses pricing premiums historically captured by plastic-laminated grades while opening volume pools to recycled-content specialists with coating R&D depth.
REACH chemical compliance frameworks and EU F-Gas Regulation restrictions on fluorinated substances are eliminating per- and polyfluoroalkyl substance (PFAS) treatments from grease-resistant paperboard. Nordic mills and German converters face reformulation deadlines that compress product development cycles. Pharmaceutical blister pack producers are accelerating migration to aluminum-alternative barrier structures to preempt regulatory scope expansion.
Brand procurement teams now mandate supplier carbon disclosure through CDP and SBTi-aligned reporting as a contract qualification threshold. This behavioral shift concentrates volume with mills possessing certified chain-of-custody documentation and renewable energy sourcing. The concentration is most visible in cosmetics and premium confectionery segments where packaging sustainability claims directly influence consumer purchase intent in German and UK retail channels.
Global Paperboard Market Segmentation
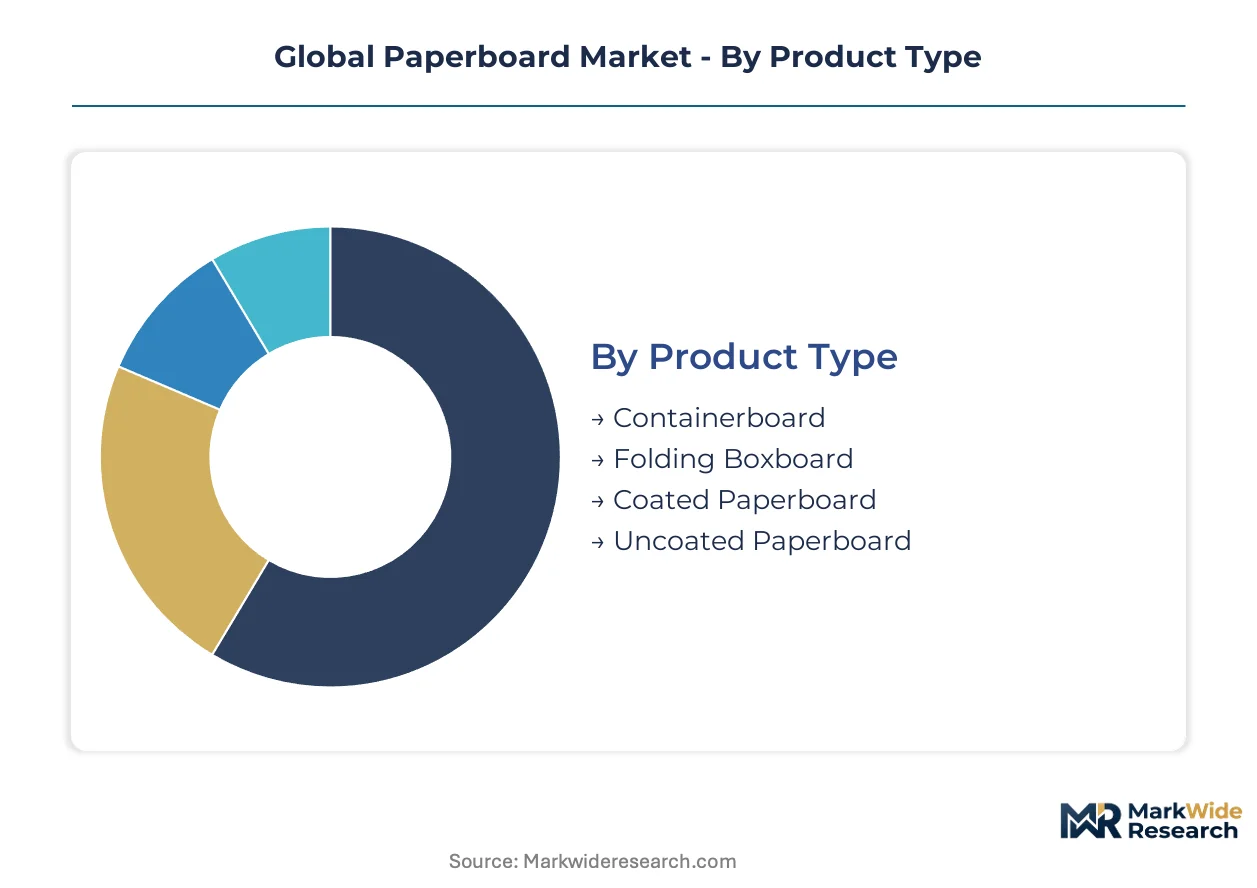
Paperboard segmentation reflects divergent cost structures, regulatory compliance burdens, and logistics requirements across end-use applications. Each dimension shapes procurement patterns, margin profiles, and geographic sourcing strategies for converters and brand owners.
Product Type:
Containerboard production concentrates in coastal China, Germany, and the US Southeast for export-oriented e-commerce fulfillment. Folding boxboard mills cluster in Sweden, Finland, and Austria to serve European pharmaceutical and cosmetics brands with short lead times.
- Containerboard:Multi-ply corrugated medium and linerboard engineered for stacking strength and moisture resistance. Demand concentrates in China's Guangdong and Zhejiang provinces where Alibaba and JD.com fulfillment centers drive specification for lightweight, high-performance grades.
- Folding Boxboard:Bleached virgin-fiber board with clay-coated surfaces for high-definition printing and structural rigidity. Pharmaceutical blister packs and premium cosmetics boxes in Germany and France sustain margin pools despite higher fiber input costs.
- Coated Paperboard:Surface-treated grades for food-contact barriers and visual appeal.
- Uncoated Paperboard:Raw-finish grades for cost-sensitive secondary packaging and industrial applications.
Containerboard commands the established base. The steepest expansion runs through folding boxboard.
End Use:
Cost tier stratification separates premium certified grades from commodity volume plays.
- Packaging:Primary and secondary containment spanning e-commerce shipping boxes, retail-ready displays, and protective dunnage. E-commerce fulfillment in Vietnam and Indonesia is climbing the fastest as domestic capacity lags demand growth.
- Printing:High-end publication covers, point-of-sale materials, and luxury packaging inserts requiring superior surface smoothness.
- Stationery:Rigid boxes, file folders, and premium notebooks where stiffness and fold precision matter.
- Construction:Temporary protective sheathing, concrete form liners, and architectural model substrates.
Packaging absorbs the dominant volume share. Printing captures the residual premium positioning.
Material:
Application requirements dictate virgin versus recycled fiber selection, with food-contact segments enforcing stricter purity standards.
- Recycled:Post-consumer fiber processed through deinking and screening for containerboard and non-food packaging. EU Green Deal recycled-content mandates are redirecting R&D investment toward contamination control technologies.
- Virgin:Fresh softwood and hardwood pulp retaining structural integrity and regulatory compliance for food-contact and pharmaceutical applications. Nordic and Canadian fiber supply disruptions transmit directly to pricing volatility.
- Composite:Blended fiber formulations balancing cost and performance.
- Laminated:Multi-material constructions with plastic or aluminum layers for barrier properties.
Virgin material retains the premium tier. Recycled fiber is gaining share fastest.
Distribution Channel:
Customer type and order scale determine channel selection, with large converters bypassing intermediaries.
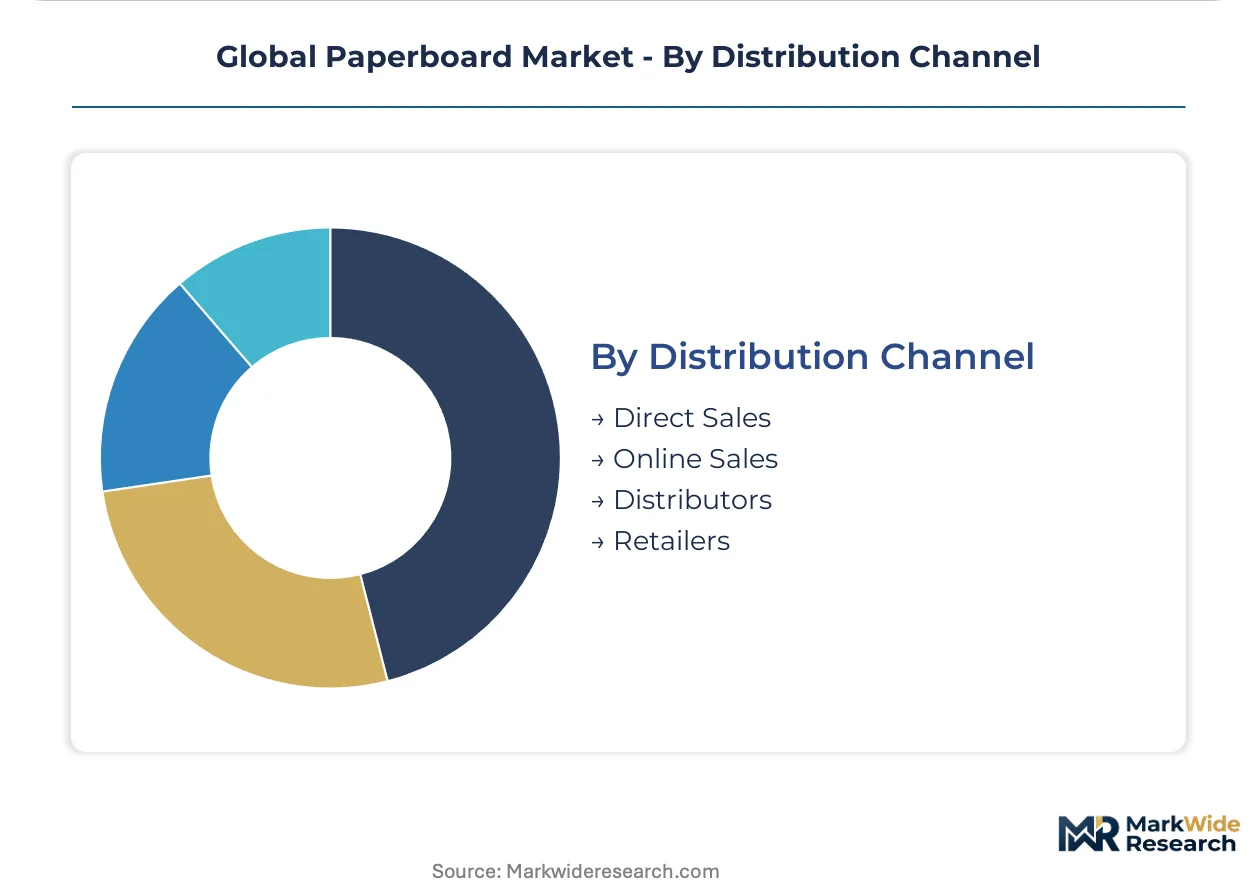
- Direct Sales:Mill-to-converter relationships for high-volume, specification-grade orders. Major corrugated producers in the US and Germany negotiate annual contracts with integrated fiber sourcing.
- Distributors:Regional inventory holders serving small-to-mid converters with fragmented demand.
- Online Sales:Digital procurement platforms for standardized grades and spot purchases.
- Retailers:Big-box and office supply chains for stationery and consumer packaging segments.
Direct sales anchor the volume foundation. Distributors are expanding most quickly into underserved regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact regulations in the United States anchor the dominant geography, with EU REACH frameworks and China's GB standards collectively reshaping cross-border formulation requirements. Mill networks and logistics hubs concentrate capacity decisions in specific national manufacturing belts.
United States
E-commerce fulfillment demand from Amazon and Walmart compresses lead times for containerboard converters. FDA purity standards for food-contact grades limit recycled-fiber substitution in specific packaging segments. The US Southeast coastal mill corridor from Georgia to Alabama hosts integrated fiber sourcing for export-oriented linerboard production.
China
Alibaba and JD.com fulfillment centers in Guangdong and Zhejiang provinces drive lightweight high-performance grade specifications. GB standards for food-contact purity diverge from FDA and EFSA frameworks, forcing dual-certification overhead. The Yangtze River Delta manufacturing belt concentrates folding boxboard consumption for pharmaceutical blister pack exports.
Germany
Premium cosmetics and pharmaceutical brands in North Rhine-Westphalia sustain folding boxboard margin pools despite higher fiber input costs. EU Green Deal packaging waste directives mandate recycled-content thresholds through extended producer responsibility schemes. The Bavarian industrial corridor anchors pharmaceutical serialization compliance for EU Falsified Medicines Directive track-and-trace requirements.
India
FMCG brand localization and pharmaceutical blister pack demand concentrate folding boxboard consumption in Gujarat and Maharashtra manufacturing zones. FSSAI food-contact regulations enforce purity standards that partially align with FDA frameworks. The Delhi-Mumbai Industrial Corridor hosts emerging containerboard capacity to serve underpenetrated domestic e-commerce logistics.
Sweden
Nordic softwood pulp supply disruptions transmit directly to virgin-material grade pricing volatility across European converters. EU F-Gas Regulation restrictions on fluorinated substances eliminate PFAS treatments from grease-resistant paperboard formulations. The Värmland and Norrland mill regions face millwright labor scarcity that constrains brownfield expansion timelines.
Global Paperboard Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with fiber sourcing control and coating R&D depth separating competitive positions. The upper tier commands annual contract relationships with major converters, while mid-scale players compete on regional logistics proximity. Two archetypes dominate: integrated fiber-to-box operators with captive pulp supply, and recycled-fiber specialists with barrier coating expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as mills retrofit legacy coating lines for aqueous barrier systems.
Within the integrated fiber-to-box tier, International Paper and WestRock Company represent North American containerboard leadership through mill network density. Among European recycled-fiber specialists, Mondi Group and Smurfit Kappa exemplify premium folding boxboard and corrugated packaging positioning respectively. Stora Enso anchors Nordic virgin-fiber expertise for pharmaceutical and cosmetics grade supply.
| Leading Market Players |
|---|
| WestRock Company |
| International Paper |
| Mondi Group |
| Stora Enso |
| Smurfit Kappa |
| Oji Holdings |
| Nine Dragons Paper |
| DS Smith |
| Nippon Paper Industries |
| Others |
Supply Flow & Price Mechanics
FDA food-contact certification and EU REACH compliance frameworks gate both mill qualification and price differentiation simultaneously, creating parallel certification cost burdens that stratify supply tiers and compress margin buffers for non-compliant converters.
Pricing Analysis
Nordic softwood pulp premiums over recycled-fiber grades have widened substantially, with virgin-material containerboard commanding sustained premiums in pharmaceutical and food-contact segments where EFSA purity standards limit substitution. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with large e-commerce converters negotiating annual offtake contracts while spot markets serve fragmented regional demand. Cost compression in recycled-content grades is intensifying because of contamination control investments and yield losses, making specialty converters the most price-sensitive buyers while premium cosmetics brands show inelastic demand for certified virgin folding boxboard.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Rotterdam port congestion have elevated landed fiber expenses for coastal Chinese mills dependent on Nordic pulp imports. Supply concentrates in Sweden, Finland, and coastal China for virgin-fiber grades, while recycled-containerboard production clusters in Germany, the US Southeast, and India's emerging industrial corridors. Raw material dependencies center on softwood pulp, OCC collection streams, and aqueous barrier coating chemicals. Single-source vulnerability runs through Nordic pulp supply disruptions. Distribution runs through mill-to-converter direct sales for volume accounts and regional distributors for fragmented demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified millwright technicians and certified barrier-coating chemists have become the constraining assets in this market, with workforce gaps now determining expansion feasibility more than capital availability.
For Market Incumbents: Secure captive fiber sourcing through long-term pulp supply agreements or backward integration into Nordic softwood holdings to insulate against price volatility. Lock in certified workforce pipelines through technical apprenticeship partnerships with Finnish and Swedish polytechnics before competitors exhaust available talent pools. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia logistics hubs where e-commerce fulfillment demand outruns domestic containerboard capacity, creating import substitution openings for regional recycled-fiber specialists with aqueous coating capabilities. Lead with pharmaceutical serialization compliance as a differentiated entry wedge against commodity corrugated producers lacking authentication-feature expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified forestry conglomerates seeking to monetize non-core paperboard assets ahead of EU CBAM scope expansion. Focus on mid-scale folding boxboard specialists with existing FDA and EFSA dual-certification infrastructure. Watch Nordic millwright labor contract renewal rates as the inflection signal for capacity constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Softwood Pulp Supply | Captive Nordic fiber sourcing insulates International Paper and Stora Enso from price volatility transmitted through global pulp exchanges. |
| Aqueous Barrier Coating Retrofit | Mondi Group and Smurfit Kappa conversion of solvent-based lines enables EU Green Deal compliance and plastic-laminate substitution in ready-meal segments. |
| Pharmaceutical Serialization Partnership | EU Falsified Medicines Directive compliance elevates folding boxboard specifications for tamper-evident authentication features in German packaging. |
| Millwright Workforce Pipeline Development | Finnish and Swedish technical institute partnerships address labor scarcity constraining brownfield expansion timelines across Nordic mill regions. |
| Carbon Border Adjustment Mechanism Preparation | Low-carbon fiber sourcing and renewable energy retrofits position EU-facing exporters ahead of CBAM scope expansion toward paper products. |
Methodological Framework
Desk research of trade association filings, customs and fiber import records, and mill capacity databases preceded structured interviews with pulp procurement directors, corrugated plant managers, pharmaceutical packaging engineers, and barrier-coating R&D leads. Primary fieldwork across Nordic mill regions, German converting corridors, and Chinese coastal manufacturing belts combined with secondary validation of technical specifications and regulatory compliance timelines. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across product grades and end-use applications.
Variance decomposition across fiber cost trajectories, regulatory timeline convergence, and coating technology adoption rates shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use application, and regional regulatory cluster. CAGRs derived from historical volume elasticities and forward-looking capacity expansion announcements. Industry-specific forecast inputs incorporated e-commerce fulfillment center buildout schedules and pharmaceutical serialization mandate implementation phases.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable Nordic pulp supply; material deviation would warrant model refresh. Forecasts reflect base-case fiber cost and regulatory compliance trajectories. Sudden shifts in China's GB standards alignment with FDA frameworks or accelerated biodegradable coating commercialization could revise demand projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Chemical Pulp Market
Paper Products
Europe Coated Paper Market
Paper Products
Global Security Paper Market
Paper Products
Recording Chart Paper Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Cheque Paper Market
Paper Products
North America Specialty Paper Market
Paper Products
Global Copier Paper Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Filtration Paper Market
Paper Products
Specialty Paper Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Pigmented Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market