
 Compressed Fiberboard Market | 2026-2036
Compressed Fiberboard Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Fiberboard Market Analysis
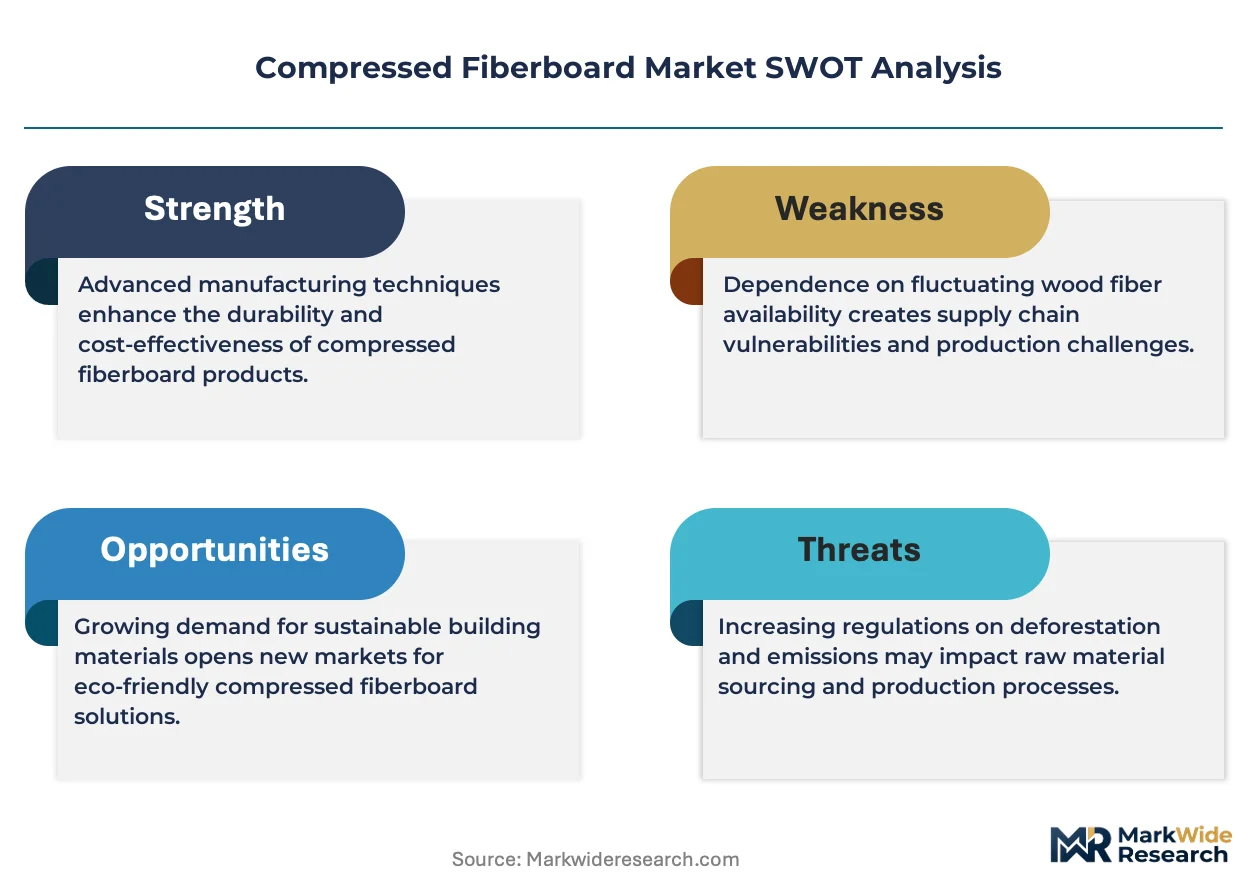
Asset-light leasing models for press equipment and finishing lines are rewriting capital requirements for mid-scale fiberboard entrants. Kronospan Limited leverages captive forestry holdings across Eastern Europe to sustain raw material cost advantages. Georgia-Pacific Wood Products LLC anchors its position through integrated resin chemistry operations in the southeastern United States. Swiss Krono Group differentiates via continuous press technology leadership and premium-grade output for German automotive interiors.
Compressed fiberboard denotes an engineered wood panel manufactured from mechanically refined lignocellulosic fibers bonded under heat and pressure with synthetic resin, typically achieving densities between 500 and 1,000 kilograms per cubic meter depending on grade specification. The material serves as a dimensionally stable substrate for furniture components, flooring underlayment, and decorative surfacing applications where solid timber proves uneconomical or structurally unsuitable. Medium Density Fiberboard commands the largest volume share due to its versatility across furniture and millwork fabrication, while Moisture Resistant grade captures expanding margin pools as commercial construction specifications tighten performance requirements. Acoustic Fiberboard represents the fastest-growing product category, driven by open-plan office retrofits and stringent building code sound transmission limits in multi-family residential towers.
The EPA regulates formaldehyde emissions from composite wood products under the Toxic Substances Control Act Title VI, compelling manufacturers to certify panel compliance through third-party testing and quality assurance protocols. REACH restricts certain phenol-formaldehyde resin constituents in European production, while the EU Timber Regulation mandates chain-of-custody documentation to exclude illegally harvested fiber inputs. Stakeholders must monitor evolving bio-based binder technologies and regional carbon accounting methodologies that will determine which production configurations retain cost-competitive access to green building specification channels.
Market Dynamics
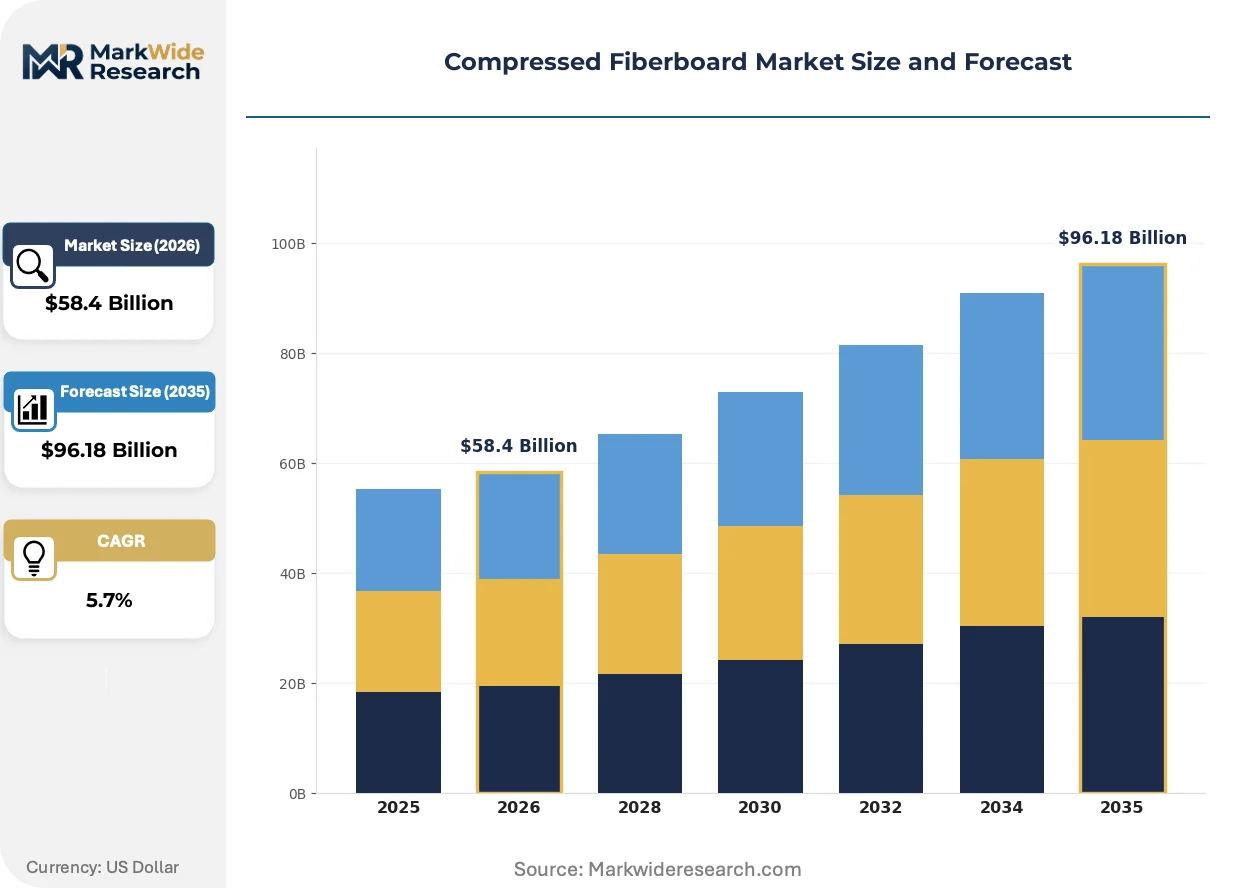
Asset-light leasing models for press equipment and finishing lines are compressing capital barriers for mid-scale entrants, while EU Timber Regulation due diligence requirements are forcing supply chain documentation investments that favor integrated producers with captive forestry holdings.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Specifiers in German and Austrian furniture manufacturing are specifying lower-carbon engineered wood substrates. Medium-density fiberboard panels with verified chain-of-custody documentation capture preference in public procurement frameworks.
- Acoustic performance mandates:Open-plan office retrofits and multi-family residential towers in Poland and the Czech Republic are specifying sound-transmission-rated panels. Building code limits on impact noise are pulling moisture-resistant and acoustic-grade fiberboard into commercial construction specifications.
- Continuous press technology diffusion:Swiss and Austrian equipment suppliers are licensing thinner-gauge, higher-speed production configurations. Premium-grade output for automotive interior applications is expanding addressable margin pools beyond traditional furniture substrates.
Market Restraints
- Formaldehyde resin input volatility:Phenol-formaldehyde and urea-formaldehyde chemistry costs fluctuate with methanol and benzene feedstock pricing. REACH restrictions on certain resin constituents in European production compound formulation complexity and compliance overhead.
- Eastern European fiber supply concentration:Captive forestry holdings in Belarus, Ukraine, and western Russia historically anchored low-cost fiber inputs. EUTR chain-of-custody documentation requirements and supply disruption risks are constraining raw material security for non-integrated processors.
- Cross-laminated timber substitution:Mass timber construction systems in commercial and mid-rise residential builds are displacing structural panel applications where fiberboard served as secondary substrate. CLT and glulam beams capture load-bearing specifications previously addressed by engineered wood panels.
Strategic Opportunities
- Bio-based binder chemistry convergence:Lignin-derived and tannin-formaldehyde resin systems are approaching cost parity with petrochemical alternatives. Producers with in-house resin operations can differentiate on embodied carbon metrics for green building certification channels.
- Equipment leasing channel innovation:Third-party financing of continuous press lines and finishing systems is enabling mid-scale entrants in Poland and Romania to achieve scale without balance-sheet intensity. Operating lease structures shift technology obsolescence risk to equipment vendors.
- Automotive interior specification expansion:German OEMs are qualifying fiberboard substrates for door panels, headliners, and trunk linings. Lightweighting mandates and interior air quality standards are pulling premium-grade, low-emission panels into vehicle platform specifications.
Industry Challenges
- Third-party certification timeline compression:EPA TSCA Title VI and CARB ATCM Phase 2 compliance requires accredited laboratory testing and quality assurance protocols. Certification delays of 4-6 months constrain new product line launches and geographic market entry.
- Resin chemistry talent scarcity:Formulation expertise in low-emission and bio-based binder systems concentrates at integrated majors. Mid-scale producers face recruitment friction for polymer chemists with composite wood product experience.
- Legacy finishing line integration:Digital printing and in-line coating systems require retrofit of existing sanding and lamination sequences. Capital allocation decisions between greenfield continuous press investments and brownfield automation upgrades create strategic tension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Fiberboard Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $96.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Density Fiberboard, High Density Fiberboard, Low Density Fiberboard, Acoustic Fiberboard Application: Furniture, Flooring, Decorative Panels, Packaging End User: Residential, Commercial, Industrial, Automotive Grade: Standard, Moisture Resistant, Fire Retardant, Others |
| Companies Covered | Kronospan Limited, Swiss Krono Group, Georgia-Pacific Wood Products LLC, ARAUCO, Daiken Corporation, Fritz EGGER GmbH & Co. OG, Timber Products Co., Roseburg Forest Products Co., Weyerhaeuser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Fiberboard Market Emerging Trajectories
Digital surface decoration and in-line quality sensing are compressing batch-to-batch variation and enabling mass-customization of decorative fiberboard panels. These technologies are redrawing the boundary between commodity substrate production and differentiated surfacing operations.
Continuous press systems with real-time density profiling and moisture sensors are rendering obsolete traditional multi-opening press configurations for premium-grade production. German automotive interior suppliers are qualifying output from these lines for just-in-sequence delivery. The technology is compressing capital recovery timelines and concentrating premium capacity among early adopters with resin integration.
REACH restrictions on formaldehyde emissions and certain phenol derivatives are tightening formulation requirements for European production. Manufacturers are accelerating migration to low-emission resins and investing in third-party certification infrastructure. The regulatory friction is most acute for mid-scale Polish and Czech producers serving export markets with divergent national standards.
Buying patterns among furniture manufacturers are consolidating toward frame contracts with volume commitments and specification lock-in. Large German and Austrian fabricators are bypassing distribution intermediaries to secure direct mill relationships with quality assurance integration. The channel compression is most visible in Central European clusters where engineered wood procurement teams co-locate with production engineering functions.
Compressed Fiberboard Market Segmentation
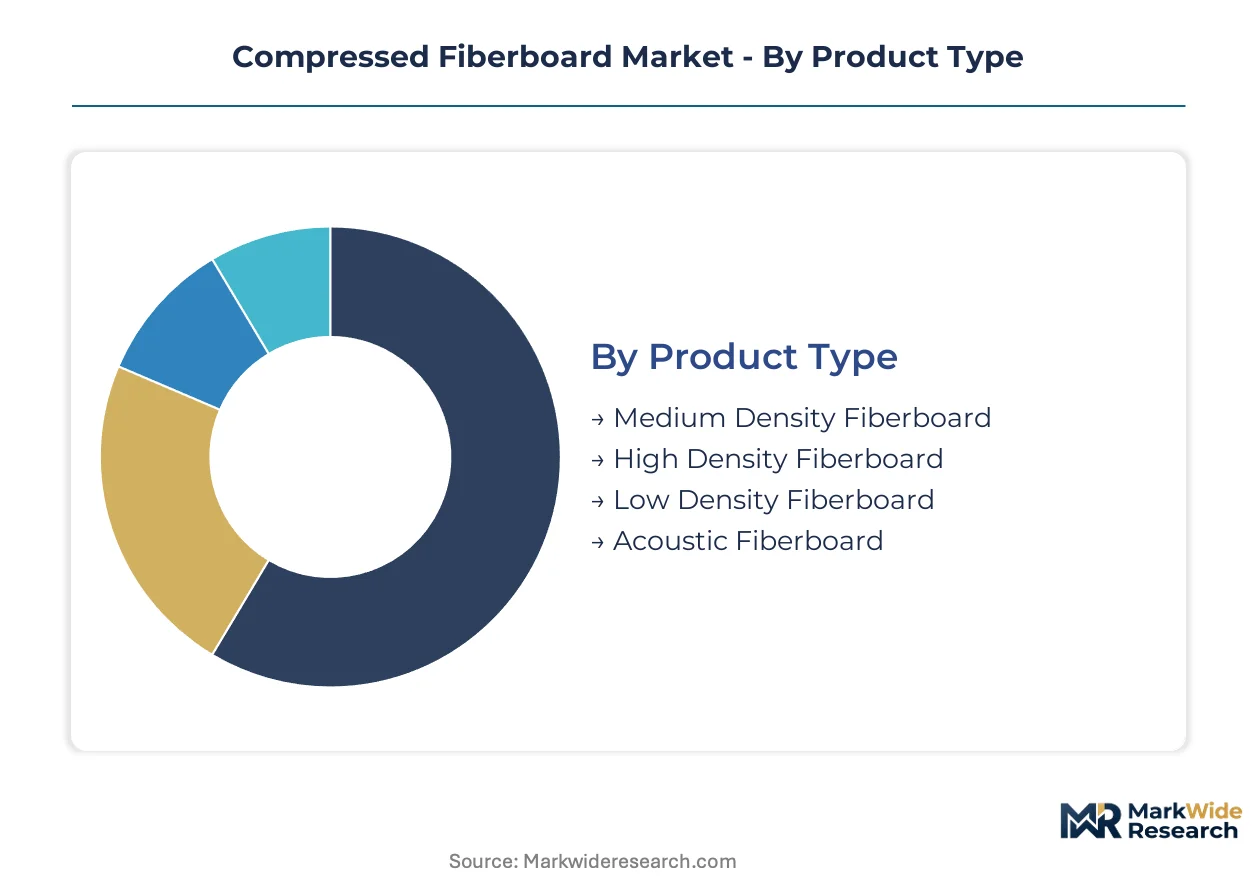
Segmentation in compressed fiberboard reveals how resin chemistry, density calibration, and surface engineering create distinct margin pools. Each category maps specific production configurations to end-use specifications that determine pricing power and certification requirements.
Product Type:
Mature density grades anchor furniture and construction substrates, while emerging acoustic formulations capture premium positioning in commercial interiors.
- Medium Density Fiberboard:Panels achieve densities between 600 and 800 kilograms per cubic meter through controlled fiber refinement and urea-formaldehyde bonding. German and Austrian furniture manufacturers specify this grade for cabinet carcasses and millwork components where dimensional stability outweighs structural load requirements. Demand concentrates in Central European clusters serving export-oriented kitchen and office furniture production.
- Acoustic Fiberboard:Engineered with perforated or porous surface structures and tuned density gradients to achieve specific sound absorption coefficients. Open-plan office retrofits in Poland and the Czech Republic are specifying NRC-rated panels to meet stringent building code limits on reverberation time and impact noise transmission.
- High Density Fiberboard:Exceeding 800 kilograms per cubic meter, these panels serve flooring underlayment and high-wear surfacing applications.
- Low Density Fiberboard:Lightweight panels below 600 kilograms per cubic meter target insulation cores and non-structural packaging applications.
Medium Density Fiberboard handles the majority of throughput; Acoustic Fiberboard is the fastest mover on share.
Application:
Volume flows through established construction and furniture channels, with packaging applications representing a cost-driven alternative substrate segment.
- Furniture:Frame contracts from large German fabricators specify certified panels with verified chain-of-custody documentation under EU Timber Regulation requirements. Direct mill relationships bypass distribution intermediaries and lock in volume commitments with quality assurance integration.
- Flooring:Underlayment specifications demand moisture-resistant grades with calibrated thickness tolerances for laminate and engineered wood floor systems. Polish and Czech construction markets are pulling certified panels into multi-family residential tower projects.
- Decorative Panels:Digital printing and in-line coating systems enable mass-customization of surface aesthetics for interior wall cladding.
- Packaging:Cost-sensitive industrial applications substitute fiberboard for corrugated and solid wood crating in non-critical transit protection.
Furniture commands the dominant volume position; Flooring is climbing the fastest as commercial construction specifications tighten.
End User:
Residential renovation cycles and commercial build-outs drive specification patterns, with automotive emerging as a qualification-intensive premium channel.
- Residential:Kitchen and wardrobe manufacturers in Germany specify low-emission panels meeting EPA TSCA Title VI and CARB ATCM Phase 2 thresholds. Home improvement retail channels stock standard grades with basic surface finishes for contractor and DIY installation.
- Automotive:German OEMs are qualifying fiberboard substrates for door panels, headliners, and trunk linings under lightweighting mandates and interior air quality standards. Premium-grade output requires continuous press technology with real-time density profiling.
- Commercial:Office fit-out and hospitality projects specify acoustic and moisture-resistant grades for performance-critical installations.
- Industrial:Manufacturing fixtures and workbench surfaces demand high-density panels with abrasion-resistant laminates.
Residential absorbs the largest volume share; Automotive is gaining share fastest through platform qualification programs.
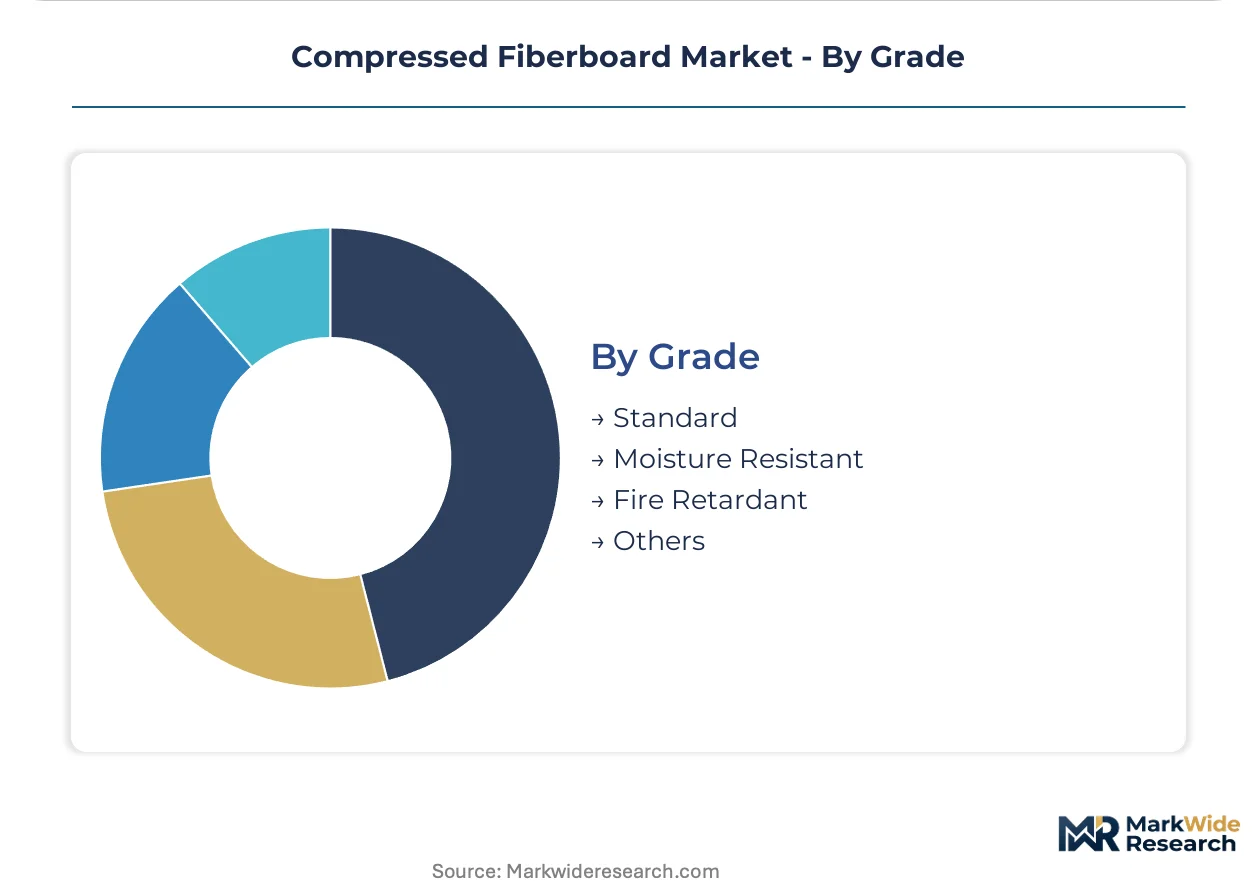
Grade:
Performance tiers separate commodity substrates from certified panels commanding green building specification premiums.
- Moisture Resistant:Modified resin formulations and wax additives achieve reduced thickness swelling under cyclic humidity exposure. Commercial construction specifications in Poland and the Czech Republic are mandating MR-grade panels for wet-area installations and concrete subfloor applications.
- Standard:Basic urea-formaldehyde bonded panels serve dry interior applications where cost minimization dominates specification criteria.
- Fire Retardant:Chemically treated or mineral-filled formulations achieve Class B or Class A surface burning ratings for code-compliant commercial installations.
- Others:Specialty grades including exterior-rated and structural composite panels address niche load-bearing and weather-exposed applications.
Standard grade moves the highest volume tonnage; Moisture Resistant is expanding most quickly as building codes tighten performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish producers capture margin premiums through EUTR-compliant documentation chains, while Belarusian fiber suppliers face exclusion from EU procurement frameworks. This asymmetry redistributes volume toward integrated Central European operators with captive forestry assets.
Germany
Furniture manufacturers in Baden-Württemberg and North Rhine-Westphalia specify low-emission MDF panels for kitchen and office systems. The EU Green Deal embodied carbon thresholds tighten procurement criteria for public infrastructure projects. Stuttgart-area automotive suppliers qualify fiberboard substrates for interior trim components under lightweighting mandates.
Poland
Engineered wood clusters around Poznań and Wrocław serve export-oriented furniture production to German and Austrian markets. EUTR due diligence requirements force documentation investments that favor integrated producers over merchant fiberboard processors. Continuous press installations in Lower Silesia achieve scale through equipment leasing structures.
Austria
Timber construction specifications in Vorarlberg and Styria drive moisture-resistant panel demand for multi-family residential towers. REACH restrictions on phenol-formaldehyde resin constituents accelerate migration to low-emission binder systems. Salzburg-region producers leverage captive Alpine forestry holdings for chain-of-custody certification.
Czech Republic
Acoustic fiberboard specifications for open-plan office retrofits concentrate demand in Prague and Brno commercial construction markets. Building code limits on impact noise transmission pull sound-rated panels into multi-family residential projects. South Moravian clusters integrate digital printing lines for mass-customized decorative surfacing.
United States
Southeastern resin-integrated producers anchor supply to residential renovation and furniture channels. EPA TSCA Title VI formaldehyde emission rules compel third-party certification through accredited laboratory testing. Georgia and Alabama mill complexes serve just-in-sequence delivery requirements for national home improvement retail distribution.
Compressed Fiberboard Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in resin chemistry and continuous press technology licensing. The vendor base concentrates among integrated forestry-product conglomerates with captive fiber supply and in-house binder operations. Three archetypes dominate: resin-integrated majors with chemical operations, equipment-leasing-enabled mid-scale entrants, and premium-grade specialists serving automotive qualification programs. Competitive moves center on backward integration into forestry assets and technology licensing partnerships for continuous press diffusion.
Within the integrated forestry-chemical tier, Kronospan Limited and Georgia-Pacific Wood Products LLC exemplify operators with captive raw material security. Swiss Krono Group occupies a position among premium-grade specialists targeting automotive interior specifications. These three anchors illustrate how resin integration, equipment technology leadership, and qualification-intensive end-use access separate margin pools in a market where documentation compliance and emission certification determine procurement eligibility.
| Leading Market Players |
|---|
| Kronospan Limited |
| Swiss Krono Group |
| Georgia-Pacific Wood Products LLC |
| ARAUCO |
| Daiken Corporation |
| Fritz EGGER GmbH & Co. OG |
| Timber Products Co. |
| Roseburg Forest Products Co. |
| Weyerhaeuser |
| Others |
Supply Flow & Price Mechanics
Overcapacity signals in Polish and Czech continuous press installations are compressing spot pricing for standard-grade fiberboard while tightening margins for non-integrated processors. This utilization imbalance rewards captive forestry holders with cost-advantaged feedstock security and forces merchant operators toward specification differentiation or equipment leasing structures.
Pricing Analysis
The customization-premium spread separates configured-to-order acoustic and automotive-grade panels from commodity furniture substrates. Contract-based long-term offtake dominates volume flows, with price differentiation hinging on certification tier and volume scale. Cost compression in standard MDF is intensifying because EUTR documentation investments raise fixed-cost thresholds for export eligibility. Large German fabricators exhibit lowest price sensitivity due to specification lock-in and quality assurance integration, while packaging applications remain most cost-driven.
Supply Chain Analysis
Upstream softwood and hardwood fiber availability concentrates in Belarus, Ukraine, and the Baltic states, though EUTR compliance constraints are redrawing sourcing patterns toward integrated Central European operators. Phenol-formaldehyde resin chemistry and wax additives constitute critical input dependencies, with formulation expertise concentrating at resin-integrated majors. Single-source vulnerability runs through Eastern European fiber supply corridors disrupted by documentation enforcement. Distribution runs through direct mill relationships for large furniture fabricators and home improvement retail channels for residential renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EUTR chain-of-custody certification and EPA TSCA Title VI compliance create switching costs that lock procurement relationships and exclude non-certified suppliers from specification channels.
For Market Incumbents: Harden captive forestry positions in Poland and Romania through leasehold expansion or long-term fiber supply agreements. Deepen backward integration into low-emission resin chemistry to defend margin position against REACH formulation restrictions. Prioritize continuous press technology upgrades for automotive qualification programs that command premium positioning.
For New Entrants and Emerging Players: Build out equipment-leased production capacity in Poland's Lower Silesia cluster where EUTR-compliant documentation infrastructure already concentrates. Target acoustic fiberboard specifications for Czech commercial construction as the most penetrable white-space segment. Pursue direct qualification relationships with Prague and Brno office fit-out contractors bypassing distribution intermediaries.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-scale Polish entrants leveraging operating lease structures for press equipment. Five-to-ten year viability favors resin-integrated operators with captive fiber supply and in-house certification infrastructure. The signal to watch is equipment vendor financing terms tightening as continuous press technology diffusion saturates Central European capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Captive fiber supply secures EUTR chain-of-custody compliance and insulates against Eastern European supply disruption. |
| Continuous Press Technology Licensing | Real-time density profiling enables automotive interior qualification and premium-grade output for just-in-sequence delivery. |
| Bio-based Binder Chemistry Development | Lignin-derived resin systems differentiate on embodied carbon metrics for EU Green Deal procurement frameworks. |
| Direct Mill Relationship Expansion | Frame contracts with German furniture fabricators bypass distribution intermediaries and lock volume commitments. |
| Third-party Certification Infrastructure Investment | EPA TSCA Title VI and CARB ATCM Phase 2 compliance accelerates geographic market entry and product line launches. |
Methodological Framework
Cross-validation between trade association production statistics and customs export filings anchors the qualitative findings. Primary interviews with plant managers at Polish and Czech fiberboard mills, procurement leads at German furniture manufacturers, and distribution channel partners in Central European clusters were synthesized with secondary validation from EU Timber Regulation implementation reports, REACH restriction dossiers, and SEC filings of resin-integrated majors. Bottom-up capacity modeling and top-down demand segmentation were reconciled across the analysis window.
Calibration against historical price spreads by grade tier and application channel informed the projection framework. The analytical model spans density grades, end-use specifications, and regional production clusters throughout the forecast period. CAGRs were derived from elasticity-adjusted volume trajectories incorporating EU Green Deal embodied carbon thresholds and acoustic performance mandate diffusion rates.
Stress conditions across formaldehyde resin input volatility, EUTR enforcement intensity, and cross-laminated timber substitution pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and technology adoption curves. Quarterly review of continuous press installation announcements and automotive platform qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Canada Honeycomb Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Sanitary Paper Products Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Synthetic Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Organic Tissue Paper Market
Paper Products
Specialty Paper Market
Paper Products
Paper Coating Materials Market
Paper Products
Paper Glass Market
Paper Products
Paper and Board Technologies Market
Paper Products
Clay Coated Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Uncoated Fine Paper Market