
 Polyester Synthetic Paper Market | 2026-2036
Polyester Synthetic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Synthetic Paper Market Analysis
Food and pharmaceutical label demand is hardening as the dominant demand vector for polyester synthetic paper, displacing traditional pulp-based stocks in moisture-exposed supply chains. Yupo Corporation leverages its biaxially oriented polypropylene heritage to anchor premium synthetic paper positioning across Asia-Pacific packaging accounts. DuPont competes through material science depth in polyester resin grades optimized for thermal transfer printability. Cosmo Films sustains manufacturing scale advantages in India, where it controls a significant share of domestic labelstock conversion capacity.
Polyester synthetic paper consists of polyethylene terephthalate (PET) resin extruded into thin, dimensionally stable sheets with surface coatings engineered for ink adhesion and print receptivity, delivering tear resistance and water immunity that wood-pulp paper cannot match. Opaque grades dominate volume consumption in shipping labels and retail tags where substrate visibility matters, while adhesive-backed configurations represent the fastest-expanding segment as linerless and pressure-sensitive label formats disperse across e-commerce fulfillment networks. Matte coatings occupy the largest share of coating type demand due to their compatibility with barcode scanning systems and thermal transfer ribbons.
FDA food-contact substance notifications govern polyester synthetic paper use in direct food labeling applications in the United States, while REACH restrictions on phthalate plasticizers and heavy metal pigments constrain formulation choices for European market access. China's GB standards for packaging material safety and Japan's JIS specifications for print durability create a fragmented compliance landscape that favors producers with multi-regional certification capabilities. Stakeholders must monitor evolving extended producer responsibility frameworks for plastic packaging, as these policies will determine whether synthetic paper gains or loses ground against fiber-based alternatives in sustainability-weighted procurement decisions.
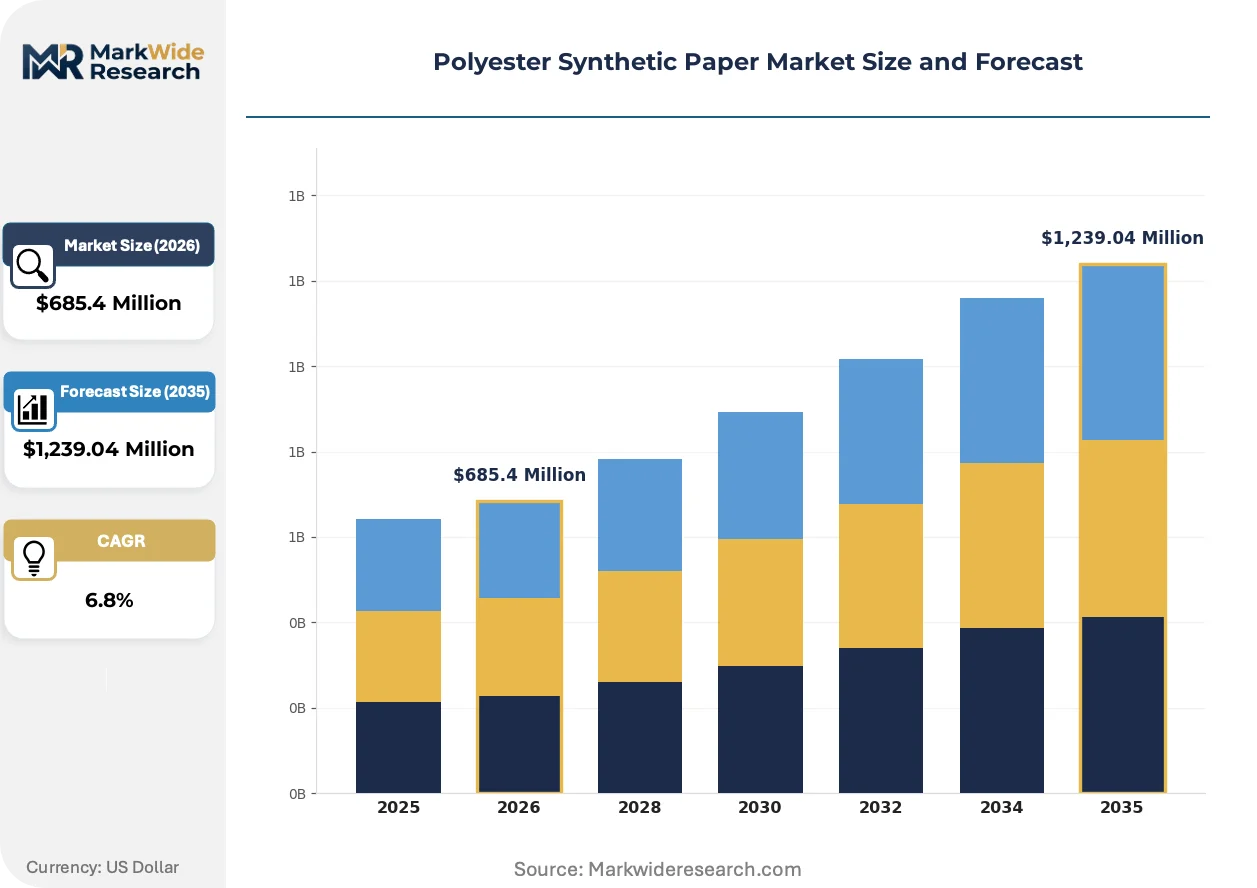
Market Dynamics
Label converters are consolidating procurement around certified synthetic substrates as pharmaceutical serialization mandates and e-commerce traceability requirements harden specification standards across moisture-exposed supply chains.
Growth Catalysts
- FDA food-contact substance notifications:Direct food labeling applications in the United States now require validated polyester substrates, pulling volume from uncoated alternatives.
- Pressure-sensitive adhesive formats:Linerless label configurations are dispersing across fulfillment networks, expanding adhesive-backed polyester sheet consumption.
- China:Packaging modernization and e-commerce label volumes are pulling significant coated polyester sheet demand as domestic converters upgrade equipment.
Market Restraints
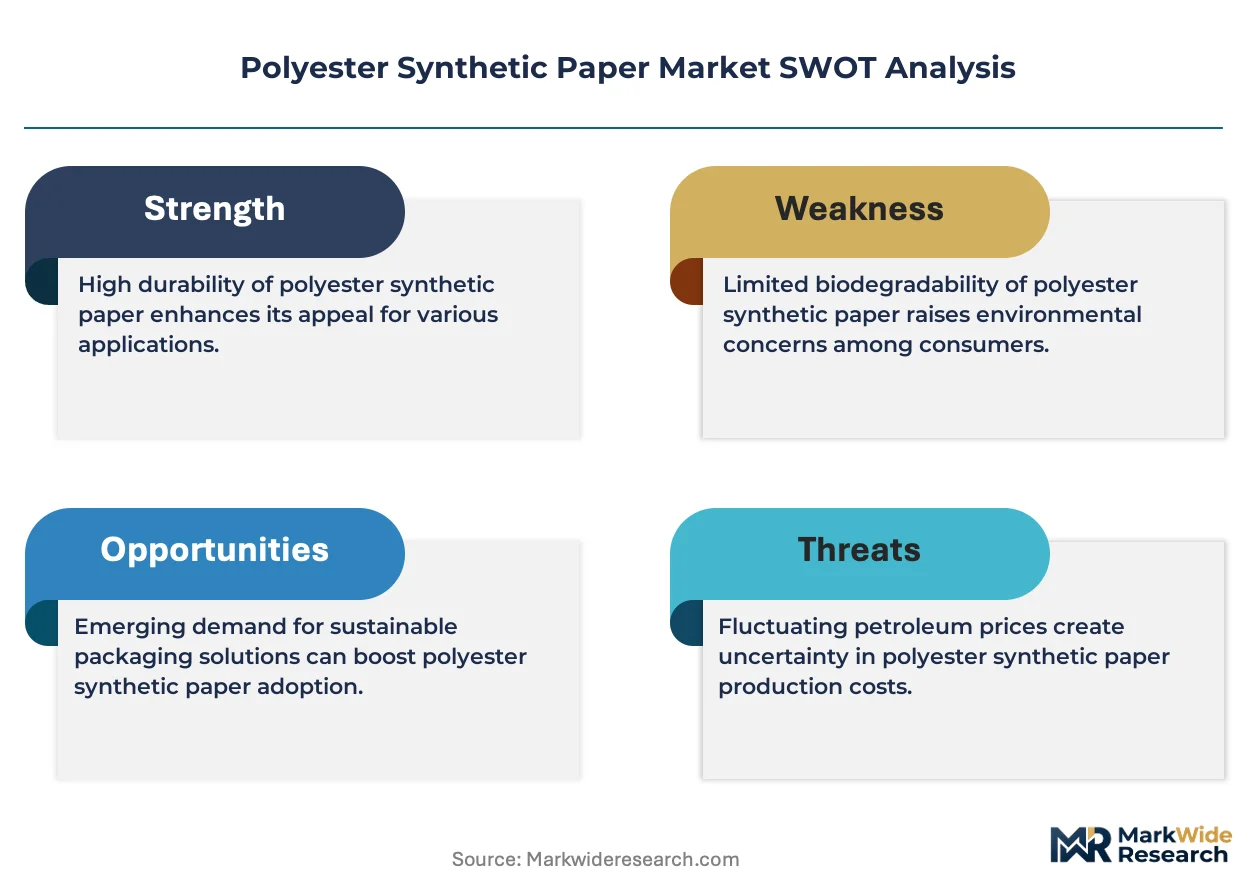
- PET resin price volatility:Crude-linked feedstock costs create margin compression for extrusion operators without captive resin supply.
- REACH phthalate restrictions:European plasticizer constraints limit formulation flexibility and extend qualification timelines for regional market entry.
- Fiber-based alternatives:Recyclable pulp substrates with barrier coatings threaten moisture-resistant applications where sustainability scores dominate procurement.
Strategic Opportunities
- India:Domestic labelstock conversion capacity remains underpenetrated by synthetic substrates, offering first-mover positioning as packaging standards tighten.
- Digital inkjet compatibility:UV-curable ink adhesion on matte polyester surfaces opens short-run variable data applications previously served by thermal transfer.
- Extended producer responsibility frameworks:Emerging plastic packaging accountability rules in the European Union may favor synthetic paper with established recycling pathways over multi-material laminates.
Industry Challenges
- Multi-regional certification capabilities:Fragmented compliance across FDA, REACH, GB standards, and JIS specifications strains quality systems and extends product launch timelines.
- Thermal transfer ribbon matching:Substrate surface energy calibration for diverse print engine specifications requires application engineering resources that mid-scale converters lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Synthetic Paper Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Opaque, Transparent, Adhesive-Backed, Embossed End Use Industry: Packaging, Labels, Stationery, Imaging Thickness: 150 Micron, 200 Micron, 300 Micron, 400 Micron Coating Type: Matte, Glossy, Satin, Others |
| Companies Covered | Yupo Corporation, PPG Industries, Cosmo Films, DuPont, Seiko Epson Corporation, Agfa-Gevaert Group, Formosa Plastics Group, Jindal Poly Films, American Profol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Synthetic Paper Market Emerging Trajectories
Surface coating chemistry and print engine compatibility are converging to redefine specification hierarchies, with converters prioritizing substrates that bridge analog and digital workflows without equipment replacement.
Matte thermal transfer coatings are consolidating position as the dominant surface treatment for barcode and variable-data applications. Pharmaceutical label converters in North America and Europe are specifying these grades for serialization compliance at accelerating rates. The technology is consolidating supply relationships around coating specialists with validated ribbon match sets, compressing spot-buy opportunities for unqualified substrates.
REACH restrictions on heavy metal pigments and phthalate plasticizers are constraining formulation choices for European market access. Producers must reformulate surface coatings and resin additives to maintain compliance, extending qualification cycles for new product introductions. Adhesive-backed configurations targeting direct food contact face the steepest reformulation burden as EFSA evaluations tighten migration limits.
Buyer concentration among e-commerce fulfillment operators is compressing specification variety and hardening price-performance thresholds. Large third-party logistics providers in China and the United States are consolidating label procurement around qualified synthetic substrates with guaranteed thermal transfer scannability. This consolidation favors producers with scale-certified coating lines and regional logistics infrastructure over specialty converters serving fragmented retail accounts.
Polyester Synthetic Paper Market Segmentation
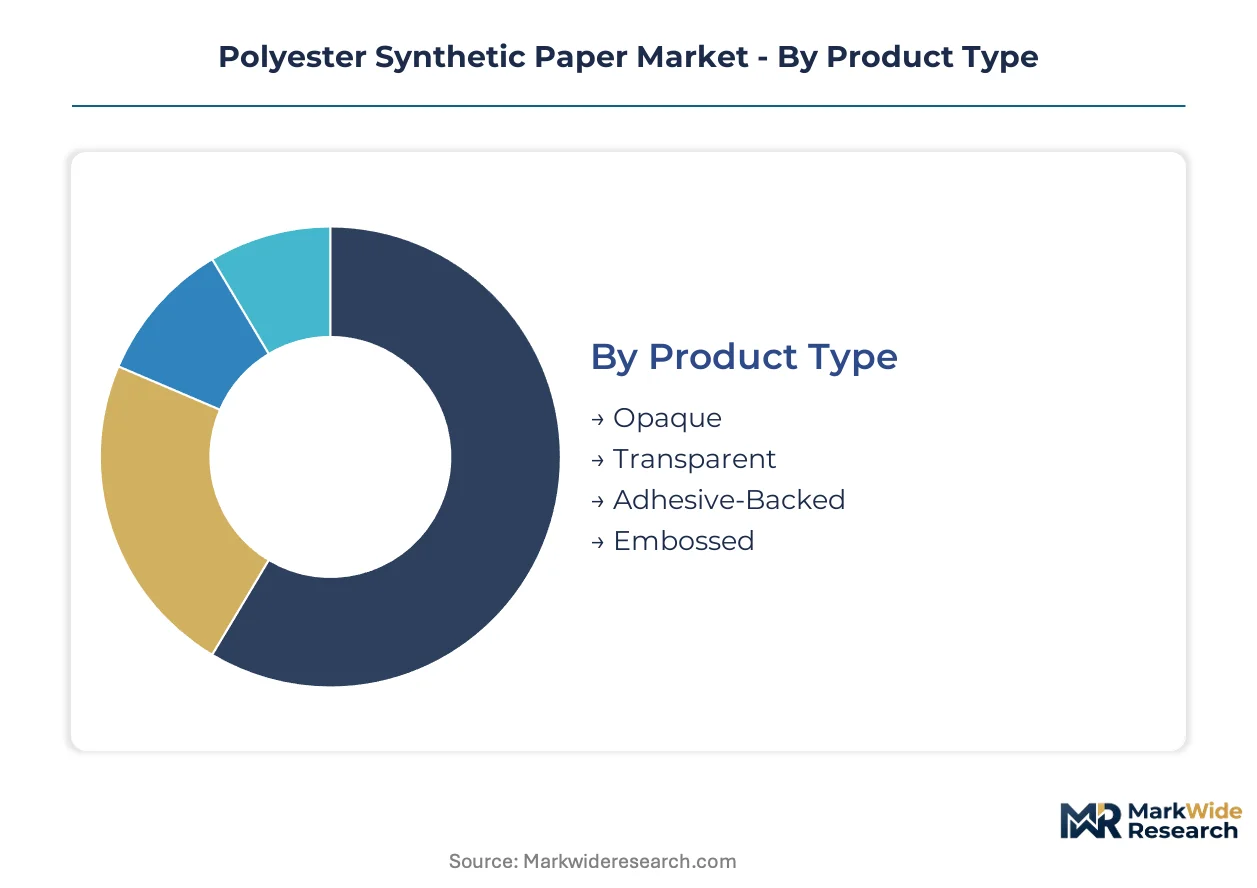
Polyester synthetic paper segments fracture along print compatibility and structural performance vectors, with coating chemistry and thickness specifications determining converter qualification cycles. Procurement consolidation around certified substrates hardens specification tiers, compressing spot-buy opportunities for unqualified grades.
Product Type:
Supply concentrates in opaque extrusions where coating line investments have already amortized across pharmaceutical and logistics label accounts.
- Opaque:PET resin extruded with mineral fillers blocks light transmission for substrate visibility in shipping labels and retail tags. Pharmaceutical serialization mandates in the United States and European Union pull volume toward certified opaque grades with validated ribbon match sets.
- Adhesive-Backed:Pressure-sensitive configurations with silicone release liners enable linerless label formats across e-commerce fulfillment networks. China's packaging modernization and domestic converter equipment upgrades concentrate demand expansion for adhesive-backed polyester sheet.
- Transparent:Unfilled PET extrusions deliver see-through properties for window graphics and overlay applications. Demand concentrates in imaging and display segments where optical clarity supersedes barcode scannability.
- Embossed:Textured surface finishes enhance tactile differentiation for premium stationery and security documents. Niche volume serves certificate and diploma applications requiring forgery resistance.
Today's leader: Opaque. Tomorrow's challenger: Adhesive-Backed.
End Use Industry:
Cost tiers separate pharmaceutical-grade certification from commercial packaging volumes, with label converters paying premiums for FDA-validated substrates.
- Labels:Thermal transfer and inkjet-compatible coatings dominate variable-data applications. Moisture-exposed supply chains in logistics and healthcare displace pulp-based stocks with tear-resistant polyester alternatives.
- Packaging:Folding cartons and flexible pouches leverage dimensional stability for high-speed filling lines. REACH-compliant formulations face reformulation burdens for European market access.
- Imaging:Photographic and wide-format printing demand glossy and satin surface treatments. UV-curable ink adhesion opens short-run digital applications previously served by analog workflows.
- Stationery:Synthetic notebooks and document covers exploit water immunity for outdoor and industrial environments. Embossed grades serve security-conscious institutional buyers.
Labels command current volume concentration. Packaging offers the steepest expansion trajectory as sustainability-weighted procurement evaluates established recycling pathways.
Thickness:
Volume clusters at mid-range calipers where print engine compatibility and material cost intersect for mainstream label converters.
- 200 Micron:Balanced rigidity and flexibility for pressure-sensitive label stocks and retail tags. Thermal transfer ribbon matching standardizes around this caliper for barcode applications.
- 150 Micron:Lightweight extrusions reduce freight costs for high-volume shipping label deployments. E-commerce fulfillment operators in China and the United States specify this grade for cost-sensitive procurement.
- 300 Micron:Heavier gauge delivers stiffness for folding cartons and display cards. Packaging modernization drives specification upgrades from pulp-based alternatives.
- 400 Micron:Maximum rigidity for reusable signage and industrial identification. Premium pricing reflects limited extrusion capacity for thick-gauge PET sheet.
200 Micron anchors current procurement. 150 Micron gains share fastest as logistics operators compress unit economics.
Coating Type:
Margin structures favor matte specialists with validated ribbon match sets, locking out commodity coating operations.
- Matte:Low-gloss surfaces optimize barcode scanning contrast and thermal transfer print receptivity. Pharmaceutical label converters in North America and Europe consolidate procurement around matte grades for serialization compliance.
- Glossy:High-sheen finishes serve imaging and promotional applications where visual impact dominates. UV inkjet compatibility constraints limit addressable market relative to matte alternatives.
- Satin:Intermediate gloss levels balance aesthetics with functional print performance. Premium stationery and certificate applications absorb limited volume.
- Others:Specialty treatments including anti-static and chemical-resistant formulations serve electronics and industrial labeling. Custom coating development extends qualification timelines.
Matte coatings defend position through equipment lock-in. Digital inkjet compatibility reshapes glossy and satin specification hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production footprints as extrusion operators migrate toward jurisdictions with streamlined compliance costs and expanding domestic label demand.
China
E-commerce fulfillment networks in Shanghai and Shenzhen are absorbing coated polyester sheet at accelerating rates as domestic converters upgrade to pressure-sensitive label lines. GB standards for packaging material safety now mandate migration testing for direct food-contact applications. The Yangtze River Delta concentration of extrusion capacity is pulling regional resin supply toward certified substrate production.
United States
Pharmaceutical serialization mandates from FDA are hardening specification standards for moisture-resistant label stocks across distribution chains. FDA food-contact substance notifications now require validated polyester substrates for direct food labeling, compressing spot-buy opportunities for unqualified imports. Chicago and Dallas logistics hubs are consolidating procurement around certified synthetic substrates with guaranteed thermal transfer scannability.
Germany
REACH restrictions on phthalate plasticizers and heavy metal pigments are constraining formulation choices for European market access, extending qualification timelines for new product introductions. EFSA evaluations tighten migration limits for adhesive-backed configurations targeting direct food contact. The Rhine-Ruhr industrial corridor maintains extrusion capacity serving pharmaceutical-grade certification requirements.
India
Domestic labelstock conversion capacity remains underpenetrated by synthetic substrates as packaging standards tighten across Maharashtra and Gujarat industrial zones. BIS certification requirements for imported packaging materials create qualification barriers that favor local extrusion investments. Mumbai-Pune logistics clusters are absorbing adhesive-backed polyester sheet as e-commerce fulfillment networks expand.
Japan
JIS specifications for print durability create technical barriers that favor established coating specialists with validated ribbon match sets. METI guidance on plastic packaging recycling is shaping procurement preferences toward substrates with established recovery pathways. The Kanto region around Tokyo maintains concentration of precision coating operations serving pharmaceutical and electronics labeling applications.
Polyester Synthetic Paper Market Vendor Landscape
Capacity expansion dominates the current landscape as extrusion operators add certified coating lines to capture pharmaceutical and e-commerce label demand. The vendor base stratifies across three tiers: integrated resin-to-sheet producers with captive PET supply, regional coating specialists with validated regulatory certifications, and commodity converters serving price-sensitive logistics accounts. Two strategic archetypes have emerged: scale-driven players leveraging amortized coating infrastructure, and compliance-focused specialists monetizing multi-regional certification capabilities. Geographic expansion and portfolio diversification represent the dominant competitive moves, with operators adding adhesive-backed configurations and digital inkjet-compatible surface treatments.
Among Asia-Pacific-based producers, Yupo Corporation and Cosmo Films occupy positions within the premium synthetic substrate tier, with the former leveraging biaxially oriented film heritage and the latter anchoring manufacturing scale advantages in South Asian markets. DuPont represents the material science archetype among North American and European players, with resin-grade optimization capabilities supporting thermal transfer printability specifications. These three companies exemplify the competitive divergence between coating-line scale and upstream resin control.
| Leading Market Players |
|---|
| Yupo Corporation |
| PPG Industries |
| Cosmo Films |
| DuPont |
| Seiko Epson Corporation |
| Agfa-Gevaert Group |
| Formosa Plastics Group |
| Jindal Poly Films |
| American Profol |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical serialization mandates and e-commerce traceability requirements are hardening specification standards, forcing extrusion operators to amortize certified coating line investments across narrower volume bases and compressing margin structures for unqualified commodity grades.
Pricing Analysis
Distributor margins for certified synthetic substrates run higher than direct-to-OEM channels due to application engineering support and ribbon match validation services. Three-tier pricing structure across FDA-validated premium, REACH-compliant standard, and uncertified economy levels separates pharmaceutical-grade certification from logistics volume. Cost compression in the economy tier is intensifying because resin price volatility and buyer consolidation among Chinese e-commerce fulfillment operators harden price-performance thresholds. Logistics procurement teams in Shanghai and Shenzhen exhibit the highest price sensitivity, while North American pharmaceutical label converters pay premiums for validated thermal transfer scannability.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and Alibaba fulfillment networks, bypassing distributor markups for adhesive-backed polyester sheet at 150-micron caliper. PET resin supply concentrates in China, South Korea, and Germany, with biaxially oriented film capacity anchoring the Yangtze River Delta and Rhine-Ruhr corridor. Surface coating chemistry draws from specialty chemical producers in Japan and the United States, creating single-source vulnerability for matte thermal transfer formulations. Distribution runs through regional labelstock converters with certified slitting and sheeting capabilities, particularly in Maharashtra and Gujarat industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyester synthetic paper production is becoming a geographic-arbitrage play as REACH compliance costs in Germany diverge from streamlined GB standard pathways in China, reshaping where extrusion operators add certified coating capacity.
For Market Incumbents: Deploy captive resin supply as the primary lever. Backward integration into PET polymerization insulates margin structures from crude-linked feedstock volatility that compresses extrusion-only operators. Add coating line capacity in India before BIS certification barriers harden, preempting emerging competition from domestic converters upgrading equipment. Fiber-based barrier-coated alternatives threaten moisture-resistant applications where sustainability scores dominate procurement decisions. For New Entrants and Emerging Players: Regional coating specialists with validated ribbon match sets represent the most penetrable channel partner type for market entry. White-space opportunity concentrates in India's underpenetrated labelstock conversion capacity across Maharashtra and Gujarat, where packaging standards are tightening but synthetic substrate adoption lags. Digital inkjet-compatible surface treatments for short-run variable data applications offer a defensible go-to-market angle against established thermal transfer incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale coating specialists holding multi-regional FDA-REACH-GB-JIS certification capabilities. Long-term viability hinges on whether extended producer responsibility frameworks favor synthetic paper with established recycling pathways over multi-material laminates. Acquisition target archetype: regional extrusion operators with amortized coating infrastructure and validated pharmaceutical-grade certifications. Watch for EFSA migration limit tightening on adhesive-backed food-contact configurations as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Captive polymerization supply shields margin compression from crude-linked feedstock volatility. |
| Multi-Regional Certification Investment | Simultaneous FDA-REACH-GB compliance unlocks pharmaceutical and food-contact premium tiers. |
| Digital Inkjet Surface Treatment Development | UV-curable adhesion chemistry opens short-run variable data applications beyond thermal transfer. |
| India Manufacturing Footprint Expansion | Domestic extrusion capacity preempts BIS import barriers and captures e-commerce label demand. |
| Recycling Pathway Certification | Established recovery protocols position synthetic paper favorably under emerging EPR frameworks. |
Methodological Framework
Bottom-up label converter demand modeling reconciled against top-down PET resin supply tracking forms the analytical core. Primary interviews with pharmaceutical serialization managers, logistics procurement leads, coating line engineers, and labelstock converters combined with secondary validation from FDA food-contact substance notifications, REACH restriction updates, GB standard filings, and customs trade data. Triangulation across these sources calibrated volume estimates and qualification timeline assumptions.
Historical consumption trendlines across pharmaceutical, logistics, packaging, and imaging end-uses established baseline growth patterns over the analysis window. Segmentation modeling incorporated product type, coating chemistry, thickness specification, and regional regulatory cluster dimensions. CAGRs derived from fitted trend extrapolation adjusted for equipment upgrade cycles in Chinese converter bases and serialization mandate phase-ins across North American and European pharmaceutical distribution chains.
Revisions become necessary when EFSA migration limits tighten, extended producer responsibility frameworks favor alternative substrates, or PET resin supply disruptions alter coating line economics. Forecasts reflect documented assumptions about certification timeline standardization and e-commerce fulfillment network expansion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Hardwood Pulp Market
Paper Products
Woodfree Paper Market
Paper Products
North America Specialty Paper Market
Paper Products
Organic Tissue Paper Market
Paper Products
Writing Paper Market
Paper Products
Europe Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Heat Transfer Paper Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Pulp Market
Paper Products
Global Kraft Paper Market
Paper Products
Drum Pulper Market
Paper Products
Europe Thermal Paper Market
Paper Products
Billing Paper Market
Paper Products
Greaseproof Paper Market