
 North America Coated Paper Market | 2026-2036
North America Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
North America Coated Paper Market Analytics
Capital-intensity divergence between integrated pulp-to-paper operators and merchant coaters is unwinding legacy margin structures in the North America coated paper sector. Stora Enso leverages its captive fiber supply and Nordic engineering heritage to sustain cost advantages across high-brightness grades. Sappi Ltd. anchors its North American position through specialized coated fine paper production for premium publishing applications. Twin Rivers Paper Company differentiates via flexible coating configurations serving short-run commercial print segments.
Coated paper consists of base paper substrate layered with mineral pigments such as kaolin clay or calcium carbonate bound with synthetic latex, engineered to achieve specified gloss levels, ink receptivity, and print resolution for commercial reproduction. The coating process applies 5–20 grams per square meter of formulated solids through blade or air-knife methods to create controlled surface porosity. Gloss coated grades dominate volume flows into magazine and catalog publishing where visual impact commands priority. Matte coated alternatives are gaining structural share in luxury packaging applications where tactile sophistication replaces reflective brilliance. E-commerce end users are redirecting demand toward silk and cast coated variants that balance unboxing aesthetics with operational printability across digital and offset platforms.
The EPA enforces recycled fiber content thresholds under Comprehensive Procurement Guidelines that constrain virgin pulp reliance in government-contracted paper supply. State-level extended producer responsibility frameworks in California and New York impose end-of-life accountability that elevates recyclable coating chemistries over plastic-laminated alternatives. OSHA maintains workplace exposure limits for titanium dioxide and formaldehyde-based coating additives that shape formulation choices at mill level. Stakeholders must monitor how FDA food-contact migration standards for mineral oil saturated hydrocarbons will tighten specifications for coated paper entering direct food packaging segments.
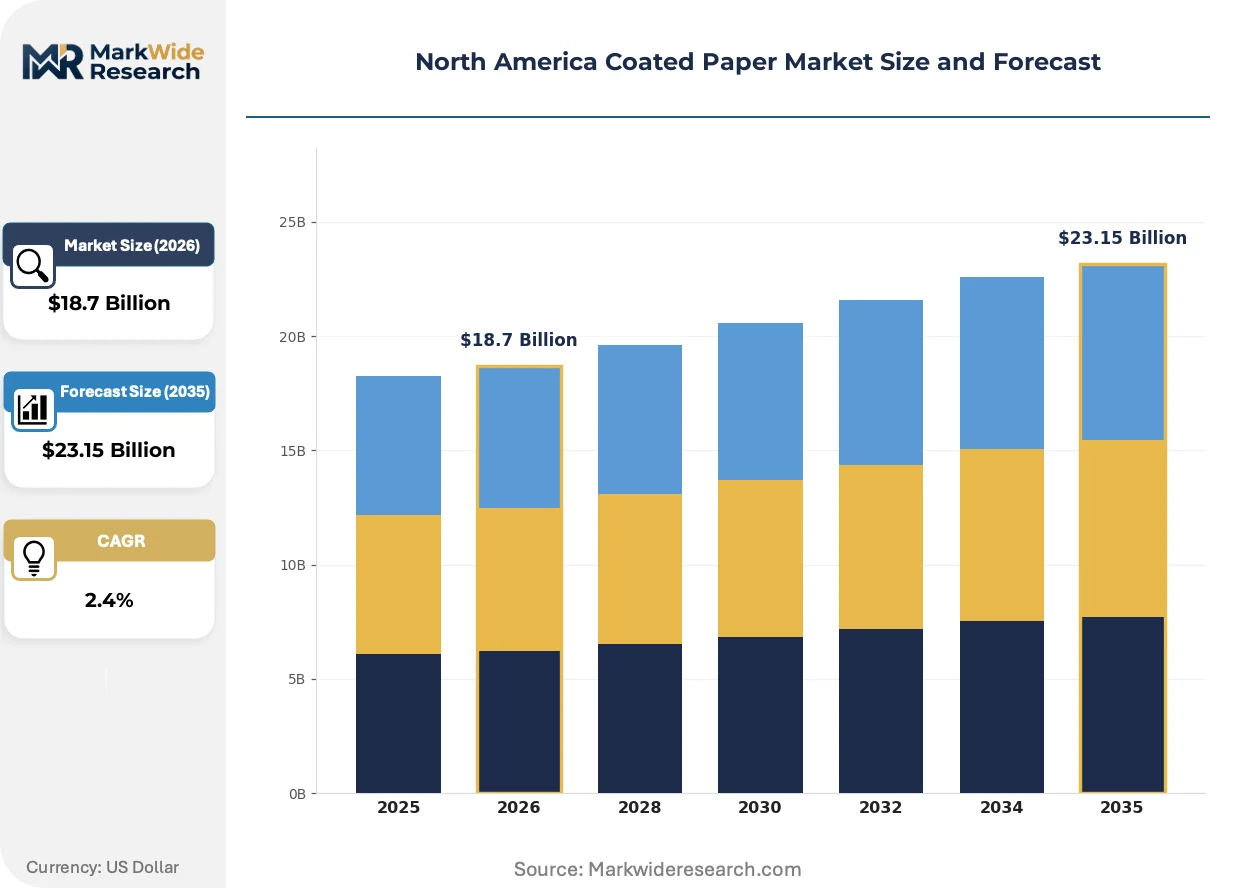
Market Dynamics
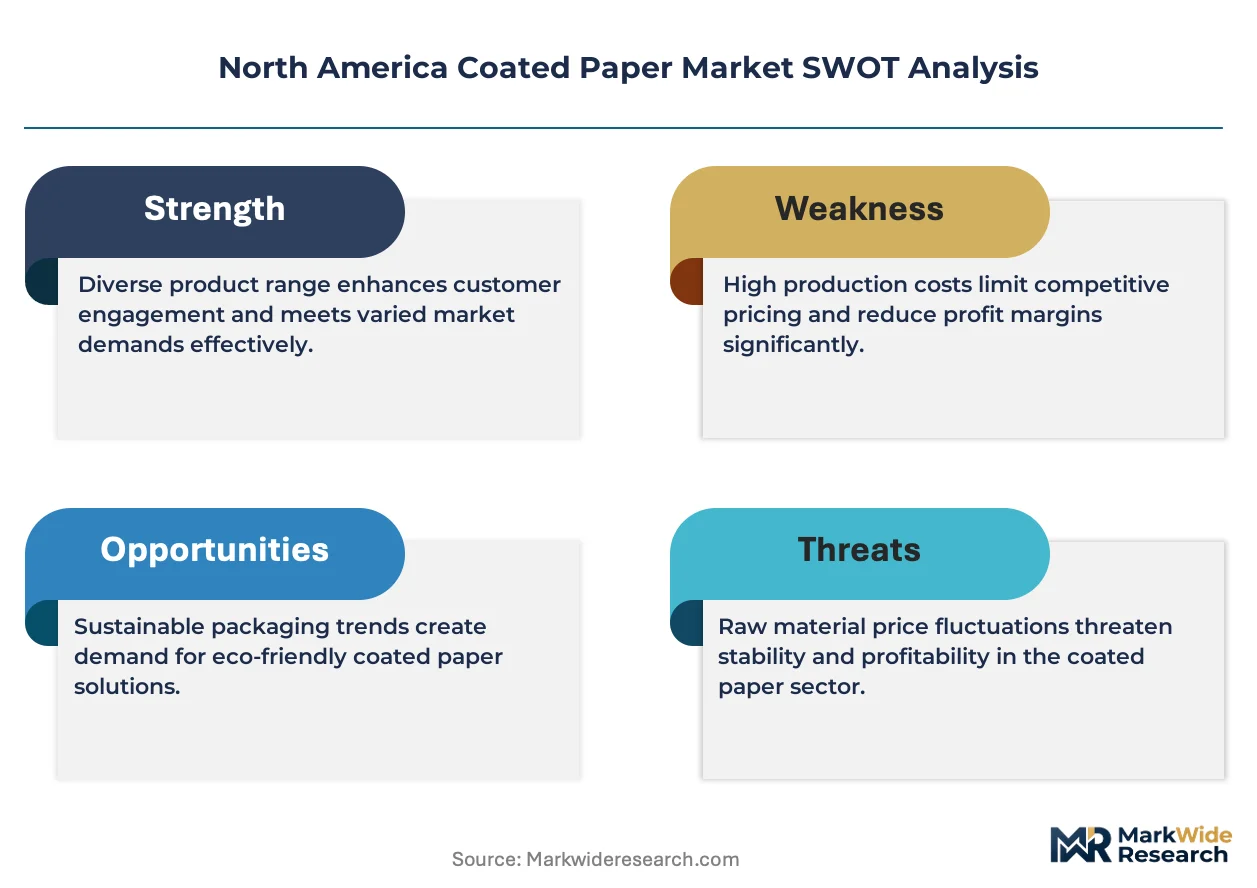
EPA recycled content mandates and California extended producer responsibility laws are compressing virgin pulp reliance while redirecting capital toward recyclable coating chemistries across the North American coated paper value chain.
Growth Catalysts
- E-commerce packaging substitution:Brands are abandoning plastic-laminated substrates for fiber-based coated papers that satisfy unboxing aesthetics and operational printability across digital and offset platforms.
- Extended Producer Responsibility frameworks:California and New York statutes impose end-of-life accountability that elevates demand for mineral-pigment coatings over petroleum-based barrier films.
- Great Lakes manufacturing corridor concentration:Wisconsin and Michigan mills benefit from integrated pulp supply, freshwater access, and established coating infrastructure that reduces logistics friction for commercial print buyers.
Market Restraints
- Titanium dioxide feedstock volatility:Coating formulation costs fluctuate with pigment commodity markets, squeezing merchant coaters lacking captive mineral supply.
- OSHA exposure limits:Workplace thresholds for formaldehyde-based coating additives constrain formulation flexibility and elevate compliance expenditure at mill level.
- Digital media substitution:Magazine and catalog publishers are compressing print volumes as advertising expenditure migrates to programmatic digital channels.
Strategic Opportunities
- Silk and cast coated variants:E-commerce fulfillment centers in Texas and Georgia are adopting these grades for premium unboxing experiences that balance tactile sophistication with operational efficiency.
- FDA food-contact specification tightening:Anticipated migration standards for mineral oil saturated hydrocarbons will create first-mover advantage for coaters with certified barrier technologies entering direct food packaging.
- Digital-press coating convergence:Short-run commercial print segments require coating configurations optimized for toner and inkjet adhesion, opening specialty production niches.
Industry Challenges
- Coating engineer talent scarcity:Formulation expertise bridging mineral pigment chemistry and synthetic latex binder systems is concentrating at integrated operators, leaving merchant coaters dependent on external technical service.
- Capex intensity for air-knife retrofit:Blade-to-air-knife coating line conversions demand substantial capital outlay that mid-scale producers struggle to finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Coated Paper Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $23.15 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloss Coated, Matte Coated, Silk Coated, Cast Coated Application: Printing, Packaging, Stationery, Art Paper End User: Publishing, Advertising, Retail, E-commerce Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Stora Enso, Sappi Ltd., UPM, Twin Rivers Paper Company, Dunn Paper Company, Billerud Americas Corporation, DS Smith, Svenska Cellulosa Aktiebolaget SCA, Lecta, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Coated Paper Market Evolving Landscape
Coating technology is pivoting toward precision application methods and bio-based binder systems that reconcile performance specifications with evolving regulatory thresholds for recyclability and workplace exposure.
Curtain coating technology is miniaturizing across North American specialty paper mills. This precision application method deposits uniform mineral-pigment layers at controlled thickness, enabling gloss-grade consistency previously achievable only through blade methods. Magazine publishers in the Midwest are adopting curtain-coated stocks for high-resolution image reproduction. The technology is miniaturizing capital requirements for entry-grade coating capacity, compressing the scale threshold for viable merchant coating operations.
EPA Comprehensive Procurement Guidelines are tightening recycled fiber thresholds for government-contracted paper supply. Federal procurement officers now require documentation of post-consumer content percentages that legacy virgin-pulp coaters struggle to satisfy without supply chain restructuring. State-level procurement offices in New York and Illinois are mirroring these standards, redirecting volume toward Great Lakes integrated operators with deinking and repulping capabilities.
Brand procurement teams are consolidating coated paper suppliers to reduce qualification overhead and secure volume-based pricing leverage. Commercial print brokers who historically sourced across fragmented merchant coaters are ceding position to direct mill relationships managed by national packaging converters. This concentration is most visible in e-commerce fulfillment networks spanning Ohio and Pennsylvania, where packaging engineers specify single-source coated board for consistency across seasonal demand spikes.
North America Coated Paper Market Segmentation
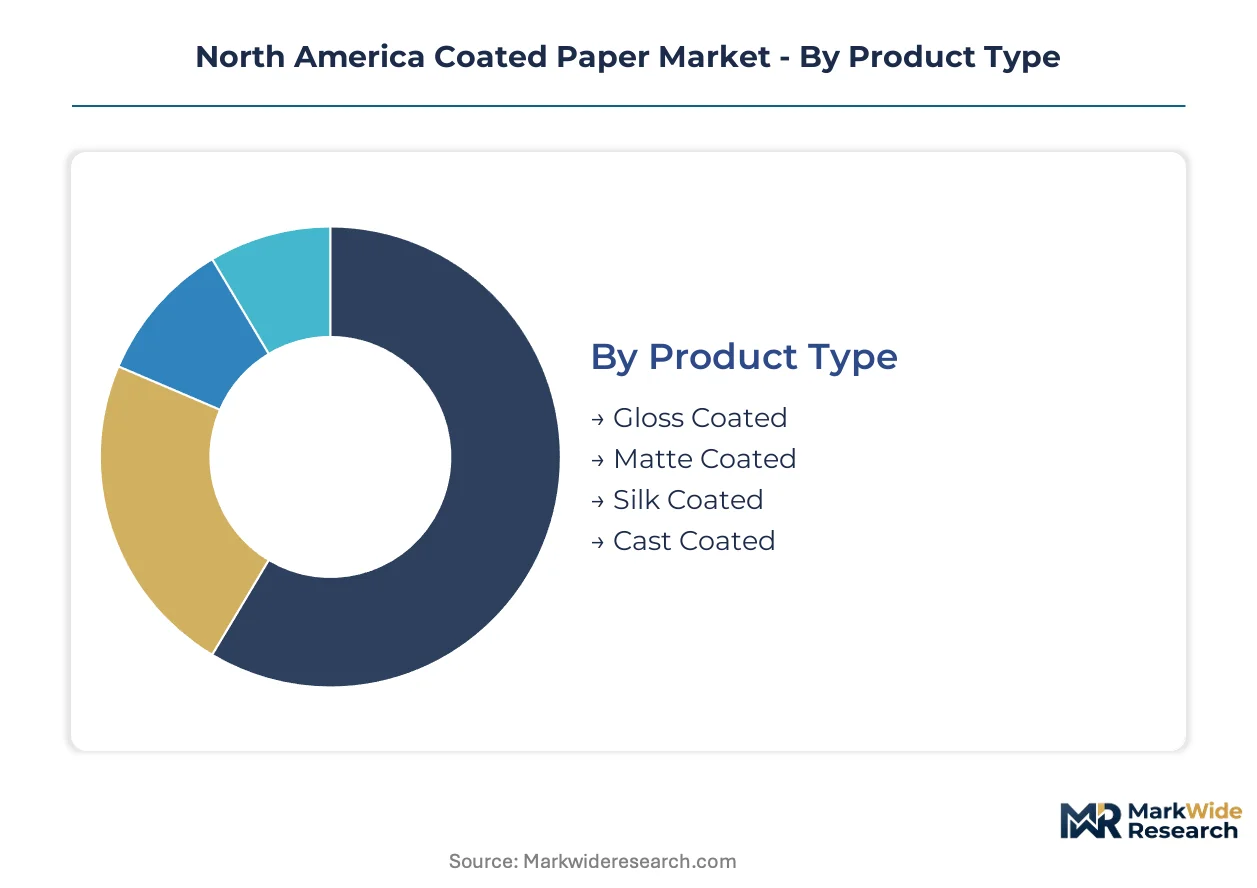
Coated paper segmentation reveals how substitution pressures from digital media and plastic alternatives are fragmenting demand across distinct performance tiers. Each segment carries divergent exposure to regulatory compliance costs and e-commerce growth vectors.
Product Type:
Gloss and matte variants face the steepest substitution threat from electronic displays and polymer films, while silk and cast grades capture fiber-based packaging migration.
- Gloss Coated:High-brightness mineral-pigment surface engineered for 75+ gloss units at 75 degrees. Magazine publishers in the Great Lakes corridor specify these grades for catalog reproduction despite compressing print volumes. EPA recycled content mandates are forcing reformulation toward deinked fiber compatibility.
- Matte Coated:Controlled surface porosity achieves 10-25 gloss units for reduced glare under retail lighting. Luxury packaging designers in California are specifying matte stocks to satisfy extended producer responsibility frameworks while delivering tactile sophistication.
- Silk Coated:Intermediate gloss positioning balances unboxing aesthetics with operational printability across digital and offset platforms.
- Cast Coated:Mirror-finish surface created through contact drying against polished drums; premium gift packaging applications dominate.
Gloss coated retains volume leadership; cast coated holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity print volumes from barrier-functional packaging commanding formulation premiums.
- Printing:Commercial reproduction spanning magazines, direct mail, and corporate collateral. Midwest commercial print brokers are consolidating supplier relationships to reduce qualification overhead across short-run digital and long-run offset workflows.
- Packaging:E-commerce fulfillment centers specify coated boards for structural integrity and printability. Ohio and Pennsylvania packaging converters are securing single-source mill relationships for seasonal demand spikes.
- Stationery:Premium writing and correspondence grades; corporate procurement teams specify certified sustainable sourcing.
- Art Paper:Archival-quality substrates for limited-edition reproductions and museum publishing.
Printing commands absolute volume; packaging climbs fastest as plastic substitution accelerates.
End User:
Customer-type concentration is shifting from fragmented commercial print brokers toward integrated packaging converters and direct brand relationships.
- Publishing:Magazine and book producers facing secular volume decline from programmatic advertising migration.
- Advertising:Direct mail and promotional print segments requiring coating configurations optimized for toner and inkjet adhesion.
- Retail:Point-of-sale and in-store display applications; seasonal demand volatility shapes inventory management.
- E-commerce:Fulfillment networks in Texas and Georgia are adopting silk and cast coated variants for premium unboxing experiences that satisfy operational efficiency requirements.
E-commerce holds the most aggressive volume trajectory; publishing retains structural scale despite compression.
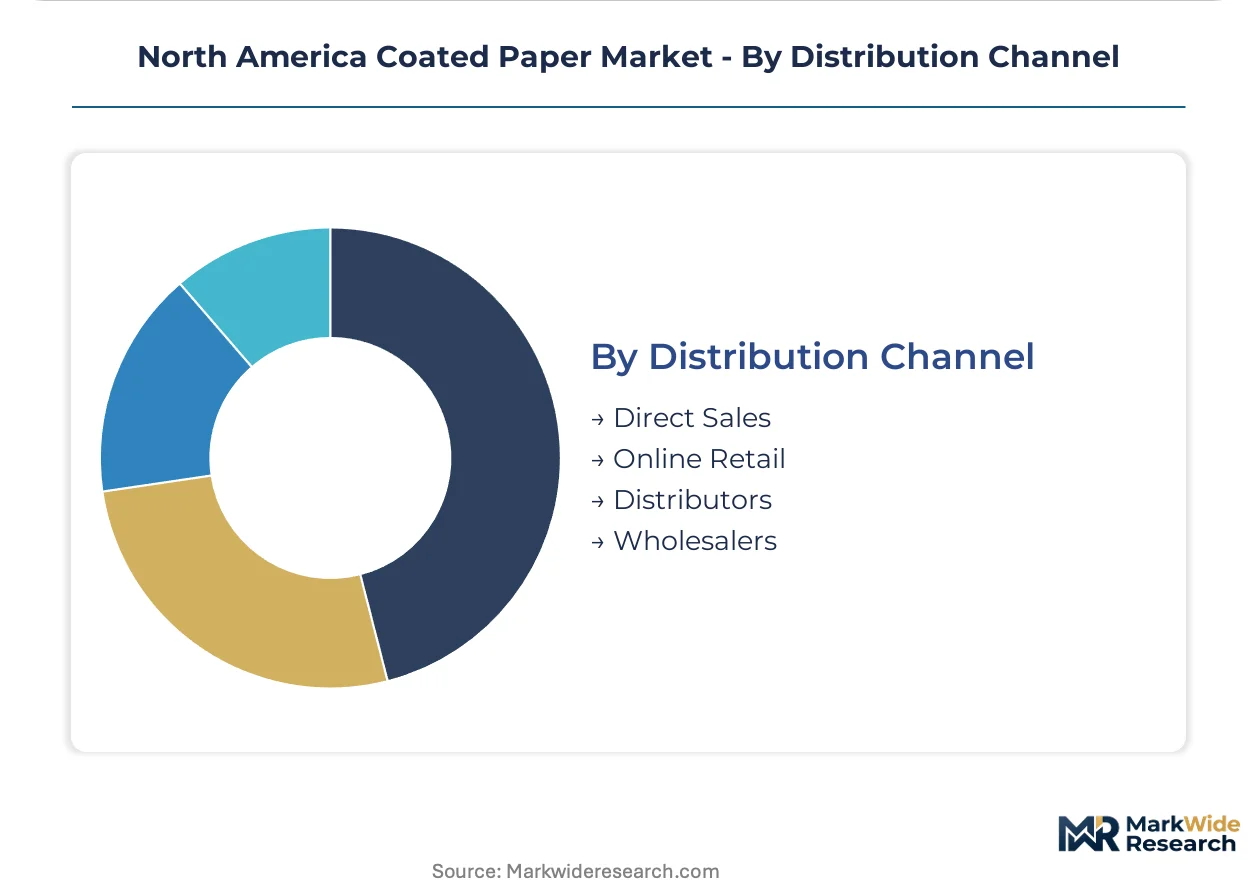
Distribution Channel:
Supply concentration favors direct mill relationships over fragmented intermediary networks, particularly for volume-account packaging converters.
- Direct Sales:National packaging converters and major publishers negotiate volume-based pricing leverage and technical service integration.
- Online Retail:Emergent channel serving small-format commercial print shops and independent designers with sample-to-roll capabilities.
- Distributors:Regional inventory positioning for just-in-time commercial print segments; warehousing costs compress margins.
- Wholesalers:Bulk consolidation for commodity grades; price transparency from integrated operators is eroding historical role.
Direct sales capture margin-rich volume; online retail expands most quickly among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial print buyers in the Great Lakes corridor exhibit the highest price elasticity, while e-commerce fulfillment centers in Texas and Georgia prioritize performance specifications over unit cost differentials.
United States
EPA recycled content mandates under Comprehensive Procurement Guidelines are redirecting federal procurement toward deinked-fiber-compatible coating formulations. Wisconsin and Michigan mills in the Great Lakes corridor leverage captive pulp supply and freshwater access to serve magazine publishers compressing print volumes. Ohio and Pennsylvania packaging converters are consolidating single-source mill relationships for seasonal e-commerce demand spikes.
Canada
Ontario and Quebec integrated operators supply barrier-functional coated boards to US cross-border e-commerce fulfillment networks. Health Canada food-contact migration standards for mineral oil saturated hydrocarbons are tightening specifications for direct food packaging applications. Quebec's established coating infrastructure serves premium publishing segments requiring archival-quality substrates.
Mexico
Nuevo León and Mexico City Metro packaging converters are adopting silk and cast coated variants for North American brand unboxing specifications. The country's environmental regulator is aligning state-level extended producer responsibility frameworks with California statutes. Bajío Region mills are expanding coating capacity to capture nearshoring demand from US retail and advertising segments.
North America Coated Paper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America coated paper sector. The upper tier commands captive fiber supply and in-house coating engineering that compresses unit economics for merchant coaters lacking upstream pulp integration. Three archetypes dominate: Nordic-engineered integrated operators with captive mineral supply, Great Lakes corridor specialists serving short-run commercial print, and European-headquartered multinationals with North American coating assets. Consolidation through strategic partnerships and air-knife coating line retrofits represent the dominant competitive vectors reshaping tier boundaries.
Among Nordic-heritage integrated operators, Stora Enso exemplifies the captive-fiber cost advantage archetype through its engineering heritage across high-brightness grades. Sappi Ltd. occupies a position within the specialized coated fine paper tier serving premium publishing applications. Twin Rivers Paper Company sits within the flexible-configuration specialist tier addressing short-run commercial print segments with adaptable coating infrastructure.
| Leading Market Players |
|---|
| Stora Enso |
| Sappi Ltd. |
| UPM |
| Twin Rivers Paper Company |
| Dunn Paper Company |
| Billerud Americas Corporation |
| DS Smith |
| Svenska Cellulosa Aktiebolaget SCA |
| Lecta |
| Others |
Value Network & Pricing Analysis
Integrated pulp-to-paper operators in the Great Lakes corridor leverage captive fiber supply and freshwater access to sustain cost advantages that compress price floors for merchant coaters lacking upstream control. This scale-driven concentration shapes pricing power across high-brightness grades while redirecting procurement toward deinked-fiber-compatible formulations under EPA mandates.
Pricing Analysis
After-sales technical service contracts and coating formulation support drive lifetime value retention across commercial print accounts. Three-tier pricing structure across premium, standard, and economy levels separates gloss coated magazine stocks from matte packaging grades and commodity uncoated alternatives. Cost compression in merchant coater margins is intensifying because titanium dioxide feedstock volatility squeezes operators without captive mineral supply. Midwest commercial print brokers exhibit highest price elasticity, while Ohio and Pennsylvania packaging converters prioritize performance specifications and single-source consistency over unit cost differentials.
Supply Chain Analysis
Just-in-time inventory preferences dominate commercial print segments, while e-commerce fulfillment centers in Texas and Georgia maintain strategic stockpiles for seasonal demand spikes. Supply concentrates in the United States, Canada, and Mexico, with Wisconsin and Michigan mills anchoring North American capacity. Raw material dependencies center on northern bleached softwood kraft pulp, kaolin clay pigments, and synthetic latex binders. Single-source vulnerability in titanium dioxide supply from offshore producers elevates formulation cost risk. Distribution runs through direct mill relationships for national packaging converters, with regional distributors serving fragmented commercial print shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce packaging substitution represents an early-cycle expansion story as brands abandon plastic-laminated substrates for fiber-based coated papers with unboxing aesthetics and operational printability.
For Market Incumbents: Secure captive deinking and repulping capabilities to satisfy EPA Comprehensive Procurement Guidelines before federal procurement officers complete supplier qualification restructuring. Defend margin position by accelerating air-knife coating line retrofits that enable curtain coating miniaturization for short-run digital press segments. Consolidate single-source relationships with Ohio and Pennsylvania packaging converters facing seasonal demand volatility. For New Entrants and Emerging Players: Technical service gaps in coating formulation support for merchant coaters dependent on external engineering resources present white-space entry points. Target Texas and Georgia e-commerce fulfillment centers adopting silk and cast coated variants for premium unboxing specifications. Pursue certified barrier technology development for anticipated FDA food-contact migration standards tightening in direct food packaging segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated operators with captive fiber supply and in-house coating engineering over fragmented merchant coaters facing talent scarcity. Long-term viability across the projection horizon rests on deinking infrastructure ownership and recyclable coating chemistry portfolios. Watch for inflection when California extended producer responsibility frameworks trigger cascading adoption across additional state jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Curtain Coating Technology Deployment | Enables gloss-grade consistency at compressed capital thresholds for merchant coaters. |
| Deinking and Repulping Capacity Expansion | Satisfies EPA recycled content mandates redirecting federal procurement volume. |
| Air-Knife Coating Line Retrofit | Delivers precision application methods for short-run digital press optimization. |
| Certified Barrier Technology Development | Positions coaters for FDA mineral oil saturated hydrocarbon migration standards. |
| Direct Mill Relationship Consolidation | Captures margin-rich volume from national packaging converters reducing supplier count. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating engineers, commercial print procurement managers, packaging converter technical directors, and e-commerce fulfillment operations heads. Secondary validation drew from EPA Comprehensive Procurement Guidelines documentation, SEC 10-K filings of listed paper companies, American Forest and Paper Association capacity reports, and customs trade data for pulp and pigment flows. Bottom-up volume estimates across product grades triangulated with top-down value projections from identified production capacity.
Across the analysis window, the forecasting framework modeled segmentation dimensions including coating finish type, application end-use, customer archetype concentration, and distribution channel structure. CAGRs were derived from production capacity utilization trends, substitution elasticity estimates, and regulatory compliance cost trajectories. Industry-specific inputs incorporated e-commerce packaging volume migration rates and digital press coating adhesion requirements.
Underlying assumptions cover sustained e-commerce fulfillment network expansion and EPA recycled content threshold enforcement, with deviation risk concentrated in titanium dioxide supply disruption and accelerated digital media substitution beyond baseline projections. Revision becomes warranted when federal procurement compliance deadlines or state-level extended producer responsibility adoption rates cross threshold acceleration points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pharma Grade Paper Market
Paper Products
Solid Bleached Board Market
Paper Products
Pigmented Paper Market
Paper Products
Paper Making Machine Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Metallized Paper Market
Paper Products
Filtration Paper Market
Paper Products
Softwood Pulp Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Printing Paper Market
Paper Products
Wood-Based Panel Market
Paper Products
Thin Printing Paper Market
Paper Products
Pulp Market
Paper Products
Chemical Pulp Market
Paper Products
Clay Coated Paper Market
Paper Products
Global Paper Chemical Market