
 Tissue Paper Market | 2026-2036
Tissue Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Paper Market Intelligence
Asset-light contract manufacturing models are reconfiguring the competitive landscape for new entrants in tissue paper production. This shift allows smaller brands to enter markets without massive capital expenditure on paper mills. Essity specializes in the health and hygiene segments, while Kimberly-Clark leverages its powerful consumer brand recognition. Georgia-Pacific sustains its position through a vast manufacturing network in North America.
Tissue paper is a lightweight, creped paper product characterized by its low basis weight, typically between 10 to 25 grams per square meter. It is engineered for high absorbency and softness for use in personal hygiene and cleaning applications. The toilet paper product type continues to command the largest market volume. Material choices, particularly between virgin pulp and recycled pulp, create distinct product tiers and influence cost structures.
Regulatory frameworks significantly shape production. The US EPA recommends recycled fiber content for government purchasing, while the EU Ecolabel sets strict criteria for environmental performance. In China, national GB standards govern product safety and composition. These rules directly impact material sourcing strategies and market access, forcing producers to navigate the trade-offs between certified virgin fiber and advanced recycled pulp processing.
Market Dynamics
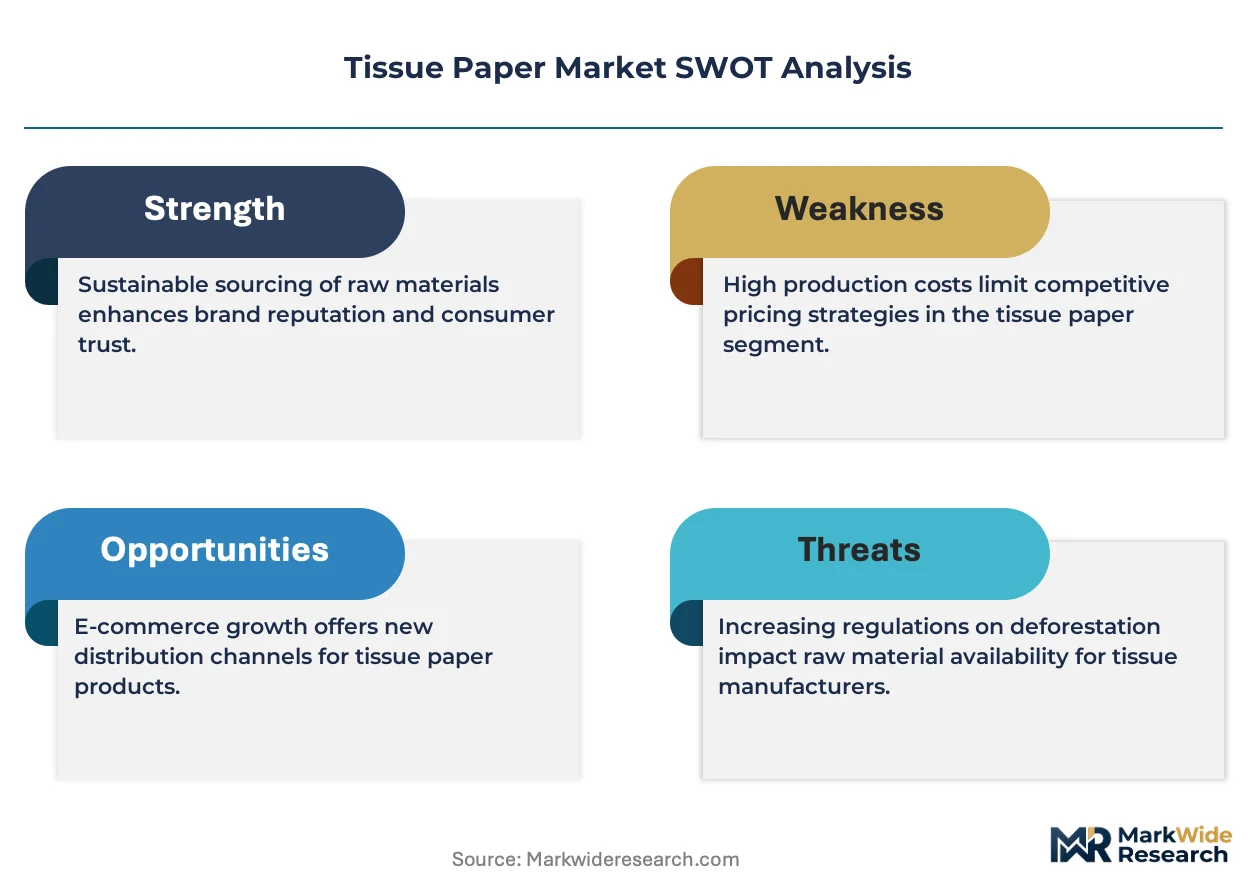
The central dynamic shaping the tissue paper market is the bifurcation of demand between sustainability and premiumization. Regulatory pressures for recycled content, exemplified by the EU Green Deal, clash with consumer preferences for the softness and quality associated with virgin pulp.
Growth Catalysts
- Hospitality Sector Expansion:Growth in tourism and business travel, particularly in the Middle East and Asia, increases demand for Away-From-Home (AFH) tissue products like hand towels and napkins in hotels and restaurants.
- Hygiene Awareness:Heightened public health consciousness in developing nations like India and Brazil is accelerating the adoption of paper towels and facial tissues for personal hygiene, moving consumption beyond just toilet paper.
- Regulatory Incentives:The US EPA's Comprehensive Procurement Guideline, which recommends recycled fiber content for government purchases, creates a stable, long-term demand floor for sustainable tissue products.
Market Restraints
- Pulp Price Volatility:Fluctuation in the global price of virgin wood pulp, driven by supply-demand imbalances in key producing regions like Canada and Brazil, creates significant cost uncertainty and margin pressure for manufacturers.
- Water Consumption:The high volume of water required for pulping and papermaking processes faces increasing scrutiny and regulatory limits, particularly in water-stressed regions, adding operational costs and risks.
- Substitution from Air Dryers:In the commercial washroom segment, high-efficiency electric hand dryers present a direct substitute for paper towels, challenging market volume with a lower total cost of ownership argument.
Strategic Opportunities
- Sustainable Premiumization:Developing advanced, processed recycled fibers that deliver softness and absorbency comparable to virgin pulp allows brands to target environmentally conscious consumers in high-income markets without sacrificing quality perception.
- Geographic Infill:Significant growth potential exists in underpenetrated rural areas of Southeast Asia and Africa, where rising incomes and improving logistics enable market entry for basic, affordable tissue products.
- Smart Dispensing Systems:For commercial clients, IoT-enabled dispensers that monitor usage data and automate reordering processes offer a compelling value proposition, locking in customers with a service-based model.
Industry Challenges
- Capital Intensity:The substantial capital investment needed to construct new, efficient paper mills or to retrofit existing plants with modern de-inking technology for recycled pulp acts as a major barrier to new capacity.
- Compliance Fragmentation:Producers face a complex web of differing national regulations, from China's GB standards on chemical composition to the EU Ecolabel's stringent environmental criteria, complicating global product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Paper Market |
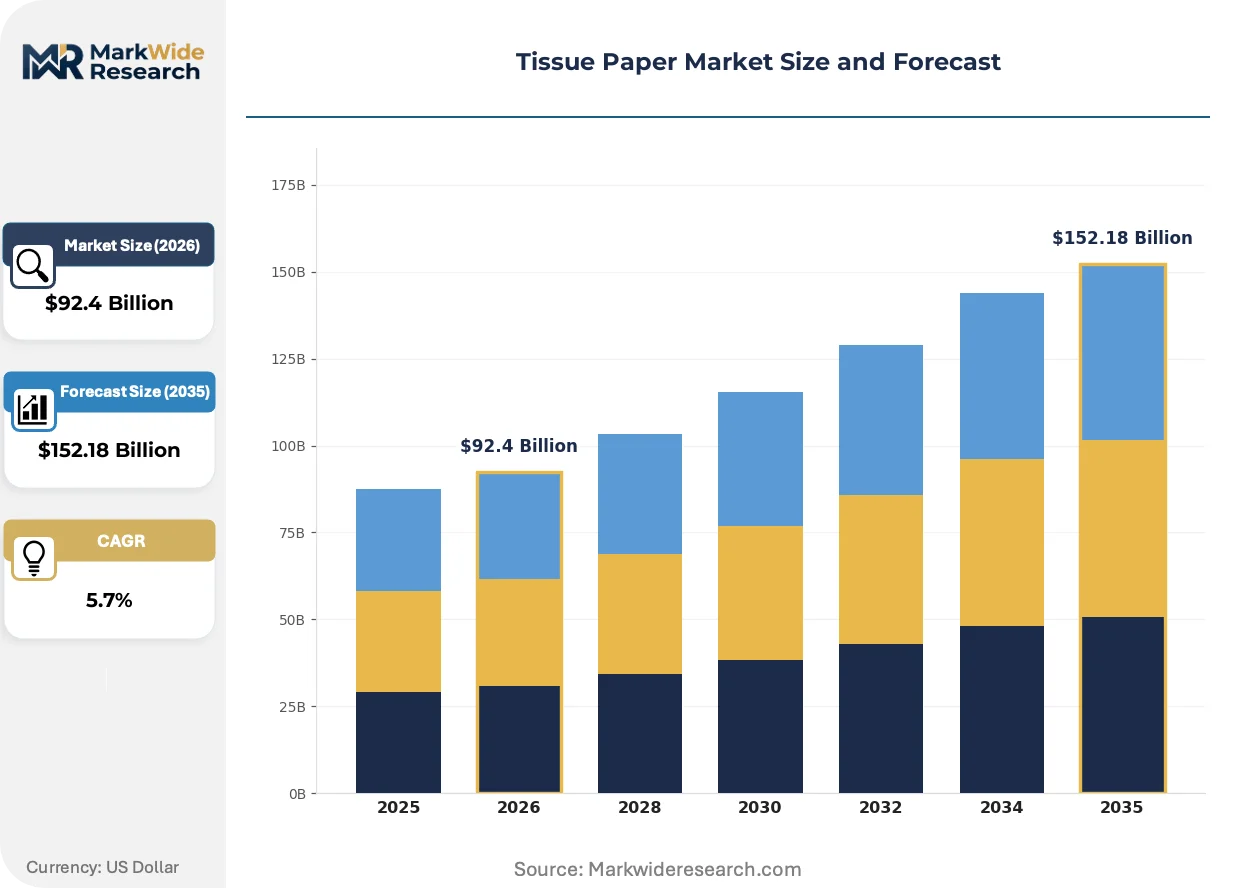
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $152.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissue, Toilet Paper, Kitchen Towel, Napkins, Handkerchiefs Application: Household, Commercial, Healthcare, Hospitality, Food Service Material: Recycled Pulp, Virgin Pulp, Bamboo Pulp, Non-Woven Fibers, Straw Pulp Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retailers, Wholesale Distributors |
| Companies Covered | Georgia-Pacific, Hengan International Group, Procter & Gamble, Cascades, CMPC, Kimberly-Clark, Asia Pulp and Paper, Sofidel Group, Essity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Paper Market Strategic Shifts & Innovations
Material science and process innovation are redefining product attributes and performance. Manufacturers are moving beyond conventional metrics to engineer products that deliver enhanced user experience with optimized fiber usage, addressing both cost and sustainability pressures simultaneously.
Advanced pulp processing methods, such as Through-Air Drying (TAD), are engineered to produce tissue with higher bulk, softness, and absorbency using less fiber. Premium and super-premium brand tiers are adopting these technologies to create tangible differentiation on the shelf. This technology is virtualizing the traditional link between basis weight and product quality, enabling the creation of lighter, more resource-efficient products that still command a premium price.
The EU Deforestation Regulation (EUDR) is imposing strict due diligence requirements on companies placing products on the European market. This policy forces tissue manufacturers to provide verifiable evidence that their raw material sourcing, particularly for virgin pulp, does not contribute to deforestation. The virgin pulp segment is most directly impacted, compelling producers to invest heavily in supply chain traceability systems to maintain market access in Europe.
A notable behavioral change is the rise of private-label premiumization among major retailers. Instead of just offering economy options, retailers are now commissioning high-quality, sustainably certified private-label tissue products that compete directly with established national brands on quality and value. This trend is most advanced in mature retail markets like Germany and the United Kingdom, where retailer brand equity is strong.
Tissue Paper Market Segmentation
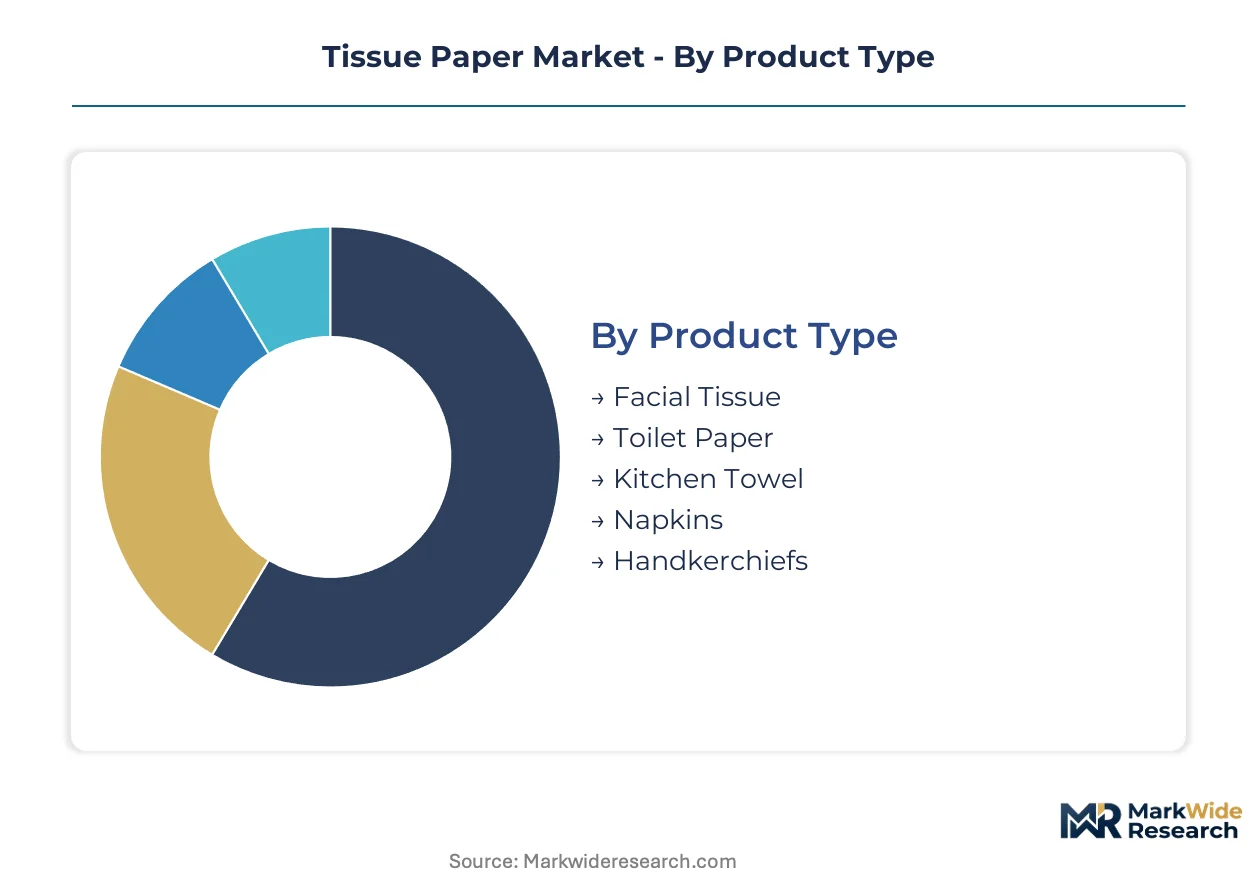
Understanding the intricate segmentation of the tissue paper market is critical for strategic positioning and resource allocation. Product types, applications, material compositions, and distribution channels each present distinct demand patterns and operational considerations for manufacturers. This granular view enables companies to tailor offerings to specific consumer needs and regulatory landscapes.
Product Type:
The tissue paper product type segmentation reflects a spectrum of maturity, ranging from established household staples to specialized hygiene items.
- Toilet Paper:This product type consists of low basis weight, multi-ply paper engineered for high absorbency and rapid disintegration in water. Demand concentrates in populous markets such as China and India, driven by rising hygiene standards and increasing urbanization.
- Kitchen Towel:Characterized by high wet strength and often embossed for enhanced scrubbing power, kitchen towels are typically multi-ply for superior absorption. Demand concentrates in mature markets like Germany and the United States due to established cleaning routines and extensive home food preparation.
- Facial Tissue:Soft, absorbent paper designed for personal hygiene, often infused with lotions or emollients, seeing increased adoption in urban centers.
- Napkins:Primarily utilized in food service and hospitality sectors, these products are characterized by various plies, sizes, and fold configurations for table settings.
- Handkerchiefs:Small, disposable paper sheets for personal use, frequently sold in compact, portable packaging for on-the-go convenience.
Toilet Paper retains volume leadership; Kitchen Towel holds the steepest expansion curve.
Application:
The application segments delineate distinct usage environments, each presenting unique performance requirements for tissue products.
- Household:Products designed for residential consumers, emphasizing softness, value, and multi-purpose utility for daily domestic use. Demand concentrates in mature markets like the United States due to established consumer habits and large household sizes.
- Hospitality:Tailored for hotels, restaurants, and tourism-related businesses, this segment prioritizes bulk purchasing, dispenser compatibility, and consistent quality for guest amenities. Demand is accelerating in the Middle East due to significant tourism infrastructure investments.
- Commercial:Encompasses office buildings, educational institutions, and public facilities, requiring durable and cost-effective solutions for high-traffic areas.
- Healthcare:Includes hospitals, clinics, and care facilities, where products must meet stringent hygiene standards and often require specific dispensing systems for infection control.
- Food Service:Covers restaurants, cafes, and catering operations, focusing on napkins, hand towels, and specialized wiping papers for food preparation and consumption.
Household applications dominate volume, while the Hospitality sector exhibits rapid expansion.
Material:
Material choices for tissue production define product performance and carry significant sustainability implications for manufacturers.
- Virgin Pulp:Derived directly from wood fibers, this material offers superior softness, strength, and brightness, often sourced from sustainably managed forests. Demand remains strong in premium segments across Europe, driven by consumer preference for quality.
- Recycled Pulp:Processed from post-consumer waste paper, this material reduces environmental impact and aligns with circular economy principles. Government procurement guidelines in the United States increasingly favor these products, creating a stable demand floor.
- Bamboo Pulp:An alternative fiber source, known for rapid renewability and natural softness, gaining traction in environmentally conscious markets.
- Non-Woven Fibers:Utilized for specialized wipes and hygiene products, offering enhanced strength and absorbency beyond traditional paper compositions.
- Straw Pulp:This material utilizes agricultural waste as a raw material, presenting a sustainable option, particularly in regions with abundant straw resources.
Virgin Pulp holds significant market share, yet Recycled Pulp is gaining traction due to regulatory support.
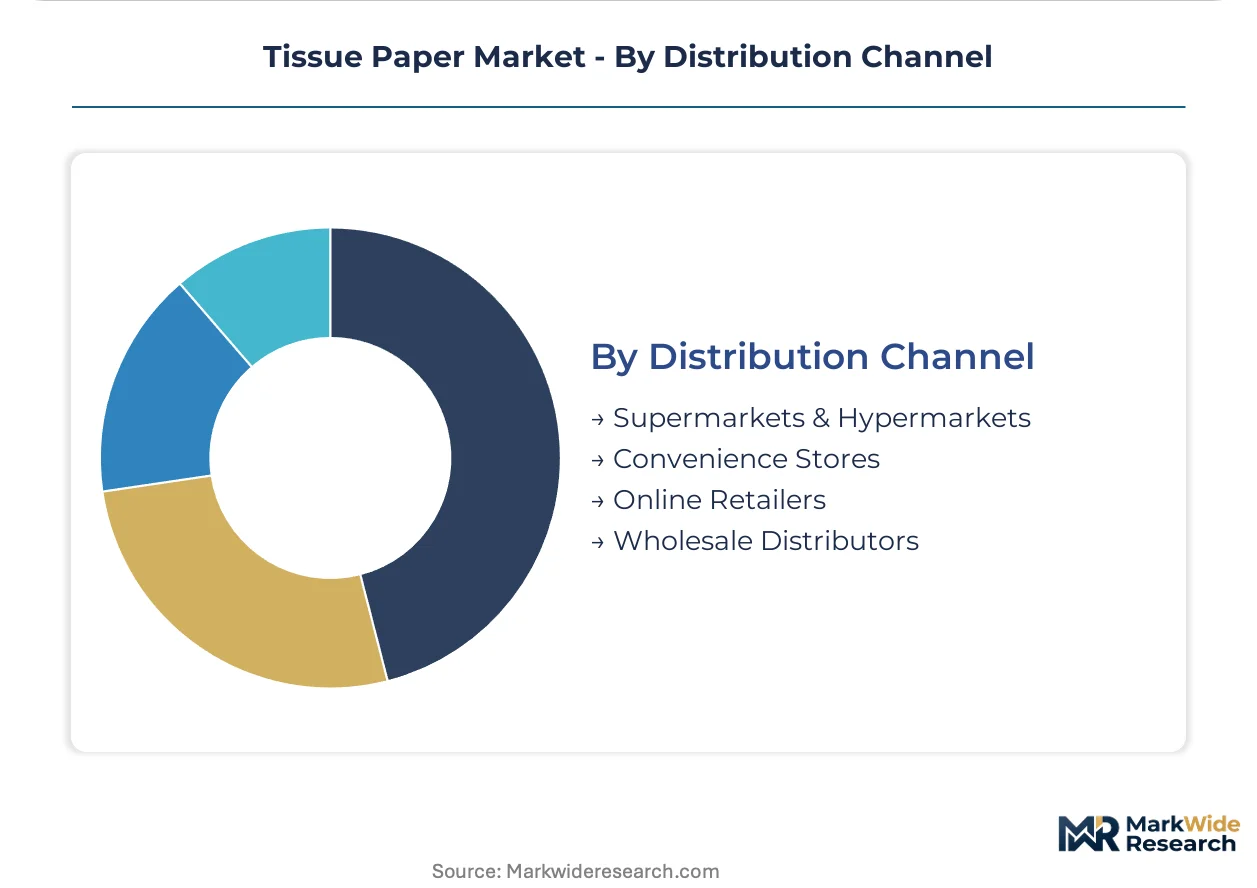
Distribution Channel:
Distribution channels dictate consumer access and influence brand visibility across diverse purchasing environments.
- Supermarkets & Hypermarkets:These large retail formats offer extensive product assortments and competitive pricing, serving as primary purchase points for household consumers. These channels dominate sales in established markets like Germany.
- Online Retailers:E-commerce platforms provide convenience and a wide selection, experiencing rapid expansion, especially for bulk purchases and subscription models. This channel is growing fastest in China due to high digital commerce penetration.
- Wholesale Distributors:These entities supply commercial, healthcare, and hospitality sectors with bulk tissue products, often managing complex logistics and inventory for businesses.
- Convenience Stores:Smaller retail outlets offering quick access for immediate needs, typically stocking a limited range of essential tissue products for impulse purchases.
Supermarkets and Hypermarkets remain critical for consumer reach, while Online Retailers demonstrate substantial growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and US EPA guidelines are influencing material choices and production strategies across the global tissue paper market. These regulatory frameworks create a stable demand floor for sustainable tissue products and incentivize advanced processing technologies. Regional dynamics reflect a mix of established consumption patterns and rapidly expanding hygiene awareness, driving varied product needs.
China
Rising hygiene standards and increasing disposable incomes drive significant demand for toilet paper and facial tissues. China's national GB standards govern product safety and composition, directly impacting material sourcing strategies. The Yangtze River Delta region, a major economic and population center, concentrates both tissue production and consumer demand.
United States
Established consumer habits and large household sizes sustain high demand for household tissue applications, particularly kitchen towels. The US EPA recommends recycled fiber content for government purchasing, creating a long-term demand for sustainable options. The Pacific Northwest, with its historical pulp and paper industry, remains a key region for raw material sourcing and manufacturing.
Germany
Mature market demand for high-quality tissue products, especially kitchen towels, is supported by established cleaning routines. The EU Ecolabel sets strict criteria for environmental performance, influencing material choices towards certified virgin and advanced recycled pulp. North Rhine-Westphalia, a densely populated and industrial state, represents a major consumer base for premium and eco-labeled tissue products.
India
Heightened public health consciousness accelerates the adoption of paper towels and facial tissues, moving consumption beyond just toilet paper. India's BIS standards ensure product quality and safety, guiding local manufacturing practices and imports. Maharashtra, a leading economic hub, experiences rapidly increasing consumption due to urbanization and improving logistics infrastructure.
United Arab Emirates
Significant tourism infrastructure investments and growth in the hospitality sector increase demand for Away-From-Home (AFH) tissue products. Local environmental regulations and sustainability initiatives encourage efficient water usage in manufacturing processes. Dubai, a global tourism and business hub, drives substantial demand for hospitality-grade hand towels and napkins.
Tissue Paper Market Key Industry Players
Channel-controlling players compete with product-specialist players in the tissue paper market, creating a tiered competitive structure. The market sees a mix of large, integrated manufacturers and asset-light contract producers. Strategic archetypes include consumer brand powerhouses, health and hygiene specialists, and private-label manufacturers. Dominant competitive moves include geographic expansion into underpenetrated markets and portfolio diversification through sustainable premiumization.
Consumer brand powerhouses like Kimberly-Clark occupy a strong position, leveraging extensive recognition to command premium pricing. Essity exemplifies specialization within the health and hygiene segments, focusing on performance-driven products for specific applications. Georgia-Pacific anchors the market with a vast manufacturing network, particularly in North America, ensuring broad product availability and scale efficiencies.
| Leading Market Players |
|---|
| Georgia-Pacific |
| Hengan International Group |
| Procter & Gamble |
| Cascades |
| CMPC |
| Kimberly-Clark |
| Asia Pulp and Paper |
| Sofidel Group |
| Essity |
| Others |
Cost & Logistics Intelligence
Overcapacity in specific regional markets, such as parts of North America, directly influences supplier behavior and pricing posture for tissue paper. This dynamic creates competitive pressure among manufacturers to maintain market share.
Pricing Analysis
Certification level, particularly for eco-labels like the EU Ecolabel, creates the primary spread in tissue paper pricing. The dominant pricing structure is a tiered premium-mid-economy differentiation, driven by material choices such as virgin versus recycled pulp. Price differentiation also stems from brand recognition, with established consumer brands commanding higher prices. Pricing softness reflects intense competition from private-label premiumization, particularly in mature retail markets like Germany. Government agencies show high price sensitivity due to procurement guidelines, while premium segment consumers prioritize softness over price.
Supply Chain Analysis
The EU Deforestation Regulation (EUDR) imposes strict due diligence requirements, limiting flows of non-compliant virgin pulp into European markets. Pulp production concentrates in Brazil, Canada, and the United States, while recycled fiber processing is more distributed. The industry draws from virgin wood pulp and recycled waste paper as primary raw materials. Commodity price volatility in virgin wood pulp presents a significant structural risk for manufacturers. Distribution runs through a dual model, with supermarkets and hypermarkets serving household consumers, and wholesale distributors supplying commercial and hospitality sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue paper market is entering a cyclical recovery, primarily driven by resurgent global tourism and business travel. This rebound boosts demand for Away-From-Home products, stabilizing industry volumes.
For Market Incumbents: Pre-empt margin erosion by investing in advanced pulp processing methods like Through-Air Drying (TAD) to optimize fiber usage. Consolidate market share through strategic acquisitions of specialized recycled pulp processors, mitigating the threat from highly price-sensitive private labels. Reinforce brand loyalty by emphasizing superior product performance and sustainability certifications. Leverage vertical integration into recycled fiber collection to secure raw material supply against future regulatory shifts like the EUDR.
For New Entrants and Emerging Players: Build out asset-light contract manufacturing models to enter underpenetrated rural areas of Southeast Asia, focusing on basic, affordable tissue products. Target the commercial washroom segment with IoT-enabled smart dispensing systems, offering a service-based model to lock in customers. Basic toilet paper in developing nations remains highly penetrable. A strong go-to-market angle involves partnering with local e-commerce platforms for direct-to-consumer delivery, bypassing traditional retail infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among commercial tissue providers offering smart dispensing systems and service contracts. The market offers long-term viability due to sustained hygiene awareness and increasing urbanization. Target asset-light contract manufacturers with strong regional distribution networks in Southeast Asia for acquisition. The signal to watch for inflection is sustained growth in advanced recycled fiber processing capacity, indicating scalable sustainable production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Recycled Pulp | Increases supply of sustainable materials, addressing EU Green Deal mandates. |
| Smart Dispensing System Integration | Locks in commercial clients with value-added service, enhancing customer retention. |
| Advanced Pulp Processing R&D | Develops softer, more absorbent tissue from recycled fibers, meeting premium demand. |
| Geographic Expansion into Rural India | Captures new volume from rising hygiene awareness and improving logistics infrastructure. |
| Private-Label Premiumization Partnership | Leverages retailer brand equity to compete with national brands in mature markets. |
Research Approach
Initial hypotheses were tested against primary input from paper mill operators, procurement managers, retail category buyers, and sustainability officers, then refined. This involved combining qualitative insights from industry stakeholders with quantitative validation from secondary sources. Secondary data included government environmental reports, trade association publications, and company financial filings. Bottom-up sizing and top-down validation ensured data triangulation.
Demand-supply balance modeling formed the core of the analytical framework across the analysis window. Segmentation dimensions included product type, application, material composition, and regional economic development. Compound annual growth rates were derived from historical trends and projected growth catalysts. Key forecast inputs included pulp price forecasts and hospitality sector expansion rates.
Stress conditions across pulp price volatility and regulatory stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect macroeconomic stability and technological advancement assumptions. Material shifts in global trade policies or significant supply chain disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Doilies Market
Paper Products
North America Specialty Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
Solar Paper Market
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
Global Paper Chemical Market
Paper Products
NCR Laser Paper Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Printing Paper Market
Paper Products
Paper Goods Market
Paper Products
Synthetic Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Sawn Wood Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
GCC Stone Paper Market