
 Global Cyber Situational Awareness Market | 2026-2036
Global Cyber Situational Awareness Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cyber Situational Awareness Market Intelligence
The sourcing model for cybersecurity capabilities is shifting from single-vendor, on-premises deployments toward multi-cloud, best-of-breed architectures. Palo Alto Networks leverages its integrated platform strategy to capture enterprise spend across network, cloud, and endpoint security domains. Microsoft Corporation integrates advanced threat intelligence directly into its Azure cloud services and extensive enterprise software portfolio. CrowdStrike Holdings Inc. specializes in cloud-native endpoint protection, offering elite threat hunting services to counter sophisticated adversaries.
Cyber situational awareness is the comprehensive perception of security data from disparate sources, creating a unified operational picture of the threat environment. These systems process high-volume telemetry from networks, endpoints, and cloud infrastructure to identify anomalous activity in real time. Threat intelligence and security analytics solutions represent the core of the market, enabling proactive threat detection. Demand from government agencies and financial services dominates the end-user landscape due to stringent security requirements.
Regulatory frameworks like the EU's GDPR and the US's HIPAA mandate comprehensive data monitoring and breach reporting, directly driving platform adoption. In China, the Cybersecurity Law imposes similar strict obligations on critical information infrastructure operators within its borders. Enterprise buyers must now focus on integrating AI-driven automation with the critical judgment of human security analysts to manage an increasingly complex threat landscape.
Market Dynamics
The convergence of sophisticated, state-sponsored cyber threats with a fragmented and increasingly stringent global regulatory environment is the central force shaping the market. This dual pressure compels organizations to move beyond siloed security tools toward integrated, data-driven awareness platforms.
Growth Catalysts
- Regulatory Mandates:Frameworks like the EU's GDPR require organizations to implement robust data monitoring and breach reporting capabilities, directly compelling the adoption of systems that provide a unified view of security events.
- Financial Services Sector Demand:Banks and financial institutions deploy situational awareness platforms to protect sensitive customer data, combat sophisticated fraud, and comply with strict industry-specific security standards from regulators.
- IoT Proliferation:The rapid expansion of Internet of Things (IoT) devices in industrial and commercial settings creates a vast new attack surface, driving demand for solutions capable of monitoring diverse and non-standard endpoints.
Market Restraints
- Implementation Complexity:The high cost of advanced platforms, combined with the technical difficulty of integrating them into heterogeneous and legacy IT environments, acts as a significant barrier to adoption for many organizations.
- Data Volume and Alert Fatigue:The immense volume of telemetry generated by networks and endpoints can overwhelm security teams, leading to alert fatigue where critical threats are missed amidst a sea of false positives.
- Talent Concentration:Elite cybersecurity expertise required to operate these systems is heavily concentrated in specific countries like the United States and Israel, creating a severe global talent shortage for security operations centers.
Strategic Opportunities
- Emerging Geographies:Rapid digitalization in regions like Southeast Asia presents a significant opportunity, as organizations seek to build their cybersecurity capabilities from a developing base to counter rising regional threats.
- Operational Technology Security:Extending situational awareness capabilities to monitor and protect Operational Technology (OT) environments in critical infrastructure, such as energy grids and water treatment facilities, is a major growth vector.
- Predictive Analytics:The convergence of artificial intelligence with threat intelligence feeds offers the opportunity to develop predictive security models that can anticipate and neutralize attacks before they are executed.
Industry Challenges
- Cybersecurity Skills Gap:A persistent global shortage of qualified security analysts and threat hunters capable of managing advanced platforms and interpreting complex threat data limits the operational effectiveness of deployed solutions.
- System Integration Hurdles:Achieving a truly unified operational picture is challenged by the difficulty of integrating and normalizing data from disparate security tools, cloud services, and on-premises infrastructure without creating performance issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cyber Situational Awareness Market |
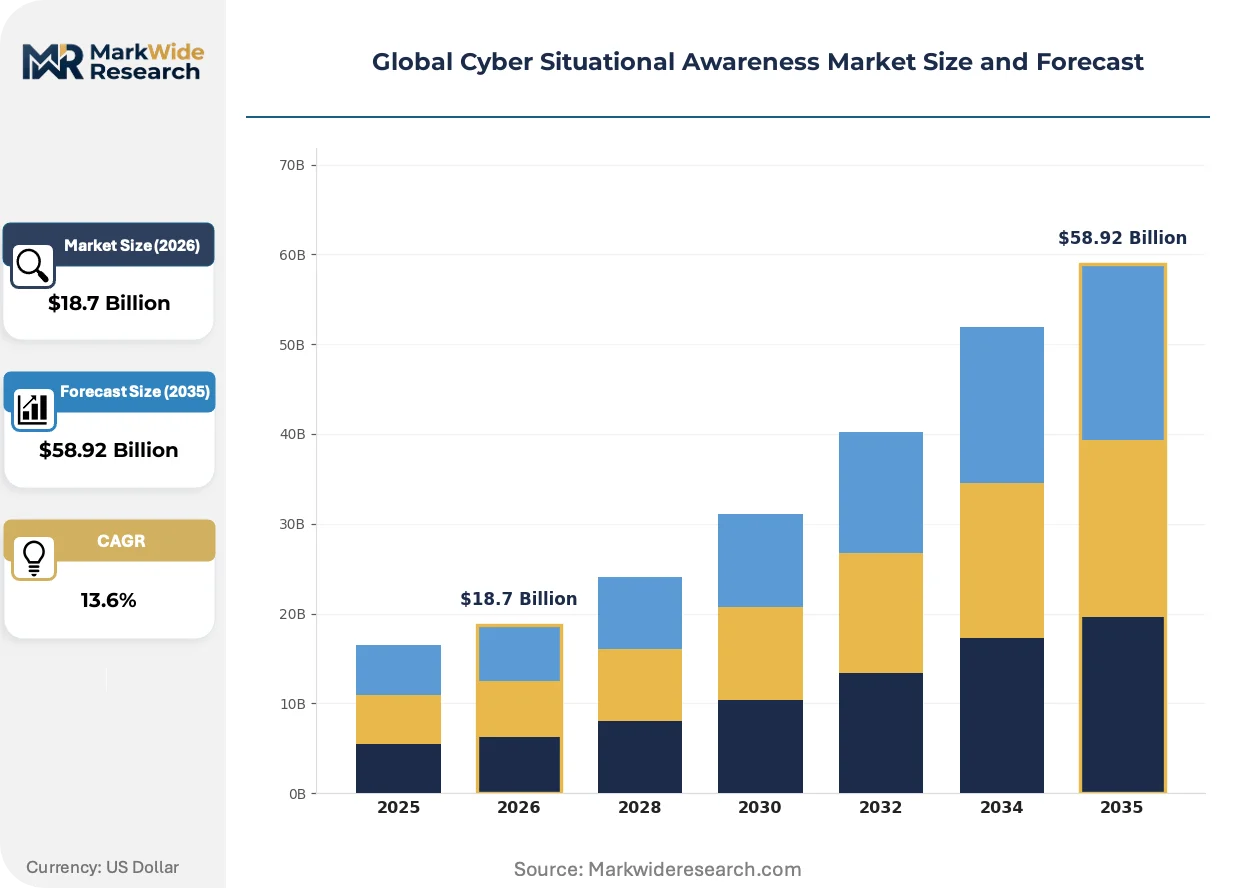
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Threat Intelligence, Security Analytics, Network Monitoring, Incident Response, Risk Management Use Case: Cyber Threat Detection, Vulnerability Assessment, Compliance Monitoring, Insider Threat Management, Forensic Analysis End User Industry: Financial Services, Telecommunications, Government Agencies, Energy Sector, Transportation |
| Companies Covered | Palo Alto Networks Inc., Check Point Software Technologies Ltd., International Business Machines Corporation, Darktrace PLC, Fortinet Inc., Microsoft Corporation, CrowdStrike Holdings Inc., Palantir Technologies Inc., Cisco Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cyber Situational Awareness Market Strategic Shifts & Innovations
Automation is becoming essential for managing the scale and velocity of modern cyber threats. Security operations are shifting toward AI-driven platforms that can correlate vast datasets, allowing human analysts to focus on high-priority incidents and strategic threat hunting.
Extended Detection and Response (XDR) platforms unify security telemetry from endpoints, cloud workloads, and network infrastructure into a single data lake. Enterprise security teams are adopting XDR to break down traditional security silos. This technology is integrating previously separate domains into a cohesive architecture, which simplifies threat investigation and accelerates response actions across the enterprise.
The US Cybersecurity and Infrastructure Security Agency (CISA) has issued directives requiring federal agencies to enhance their threat detection and response capabilities. This policy creates a powerful top-down driver for platform adoption within the public sector. Consequently, critical infrastructure entities in sectors like energy and transportation are mirroring these federal standards, upgrading their own monitoring systems.
A move away from monolithic, single-vendor security suites is gaining traction as enterprises prioritize best-of-breed capabilities. This trend favors platforms with open APIs that can ingest and analyze data from a diverse ecosystem of third-party security tools. This demand-side shift is particularly evident in the technology and financial services industries, where multi-cloud strategies are standard practice.
Global Cyber Situational Awareness Market Segmentation
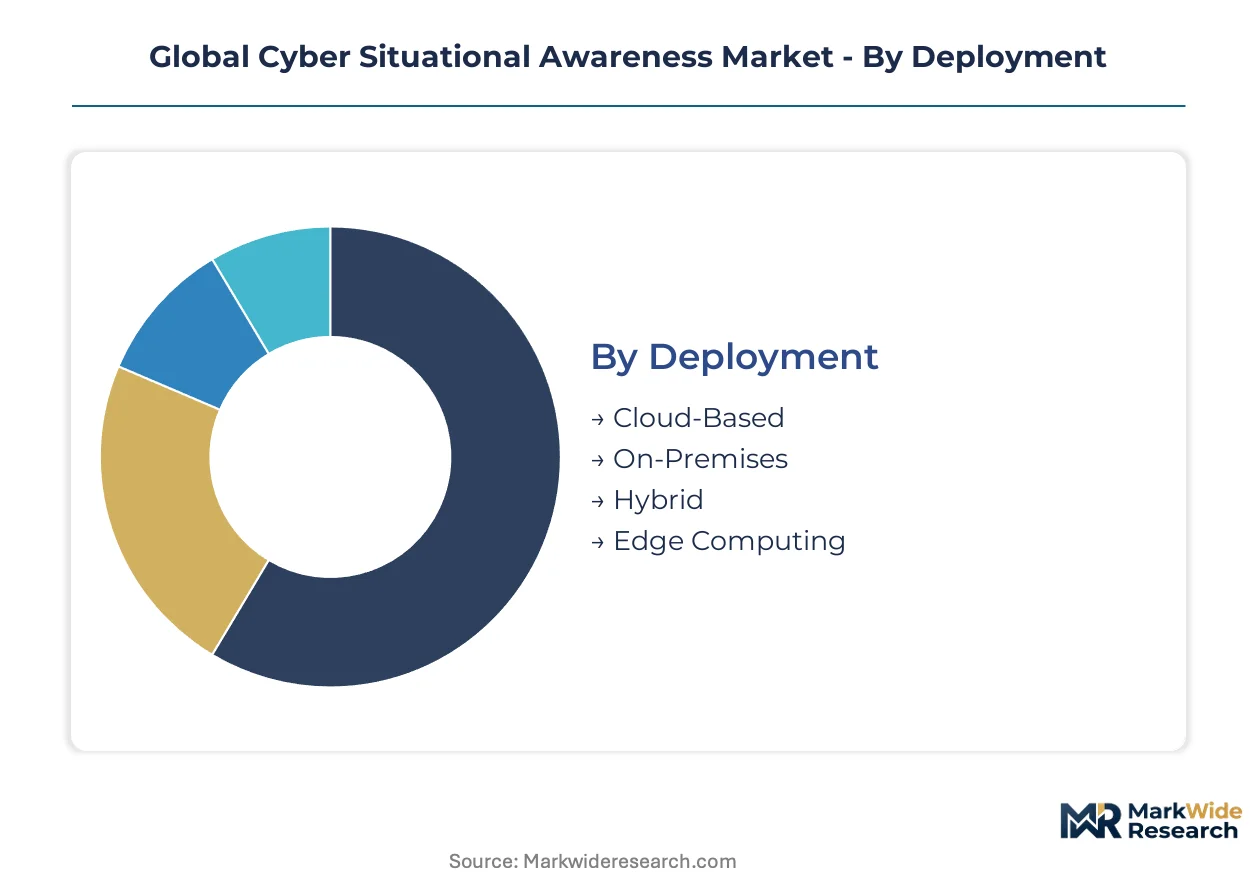
Understanding the segmentation of the global cyber situational awareness market reveals how different technological approaches, operational needs, and industry-specific requirements shape demand. This detailed breakdown highlights where investment is concentrated and how diverse organizational structures influence platform adoption.
Deployment:
The technology axis for deployment models dictates the infrastructure foundation for cyber situational awareness platforms.
- Cloud-Based:These solutions leverage public or private cloud infrastructure for hosting and processing security data, offering scalability, flexibility, and reduced on-premises hardware management. Demand concentrates in technology-forward enterprises and multi-cloud environments seeking agile security operations without large capital expenditures.
- On-Premises:Security platforms are installed and managed directly within an organization's own data centers, providing maximum control over data residency and compliance for sensitive information. Financial services and government agencies often mandate on-premises deployments due to stringent regulatory requirements and data sovereignty concerns.
- Hybrid:This model combines elements of both cloud-based and on-premises deployments, allowing organizations to manage certain workloads locally while leveraging cloud benefits for others. Hybrid deployments support phased migrations and accommodate diverse IT landscapes.
- Edge Computing:Security processing occurs closer to the data source, such as IoT devices or remote operational technology environments, reducing latency and bandwidth requirements. This segment is gaining traction in industrial control systems and smart infrastructure projects.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Solution Type:
The functional capabilities offered by cyber situational awareness solutions vary across distinct technological specializations.
- Threat Intelligence:These solutions aggregate, analyze, and disseminate information about current and emerging cyber threats, including indicators of compromise, attack methodologies, and adversary profiles. Governments and large enterprises utilize threat intelligence to proactively identify and mitigate risks from sophisticated state-sponsored actors.
- Security Analytics:Platforms that apply advanced analytical techniques, including machine learning and artificial intelligence, to vast datasets from various security tools to detect anomalous behavior and potential threats. Financial institutions rely on security analytics to identify complex fraud patterns and insider threats.
- Network Monitoring:Tools that continuously observe network traffic and activity to identify suspicious connections, data exfiltration attempts, and unauthorized access. Telecommunications providers deploy extensive network monitoring to maintain service integrity and protect customer data.
- Incident Response:Capabilities that automate and orchestrate the processes for detecting, analyzing, containing, and eradicating cyber incidents. Organizations facing frequent attacks prioritize robust incident response frameworks.
- Risk Management:Solutions designed to identify, assess, and mitigate cyber risks across an organization's assets, processes, and technologies. Compliance-driven industries integrate risk management to meet regulatory obligations.
Threat Intelligence solutions are expanding most quickly. Risk Management capabilities are also gaining significant market share.
Use Case:
Specific operational objectives drive the selection and implementation of cyber situational awareness platforms.
- Cyber Threat Detection:The primary objective of identifying malicious activities, malware, and unauthorized access attempts across an organization's digital footprint. This capability is fundamental across all end-user industries.
- Compliance Monitoring:Ensuring that an organization's security posture and data handling practices adhere to relevant regulatory frameworks and industry standards, such as GDPR or HIPAA. Financial services and healthcare organizations heavily invest in compliance monitoring capabilities.
- Vulnerability Assessment:Identifying and evaluating security weaknesses in systems, applications, and networks that could be exploited by adversaries. Regular vulnerability assessments are critical for maintaining a strong security posture.
- Insider Threat Management:Detecting and preventing malicious or negligent actions by employees, contractors, or other trusted individuals that could compromise an organization's security. Government agencies and defense contractors prioritize insider threat management.
- Forensic Analysis:Investigating cyber incidents after they occur to determine the root cause, scope of compromise, and attribution of attacks. This specialized use case supports legal proceedings and post-incident remediation efforts.
Cyber Threat Detection remains a foundational use case. Forensic Analysis is experiencing a steep expansion trajectory.
End User Industry:
Sectoral demand profiles influence the specific features and scale of cyber situational awareness deployments.
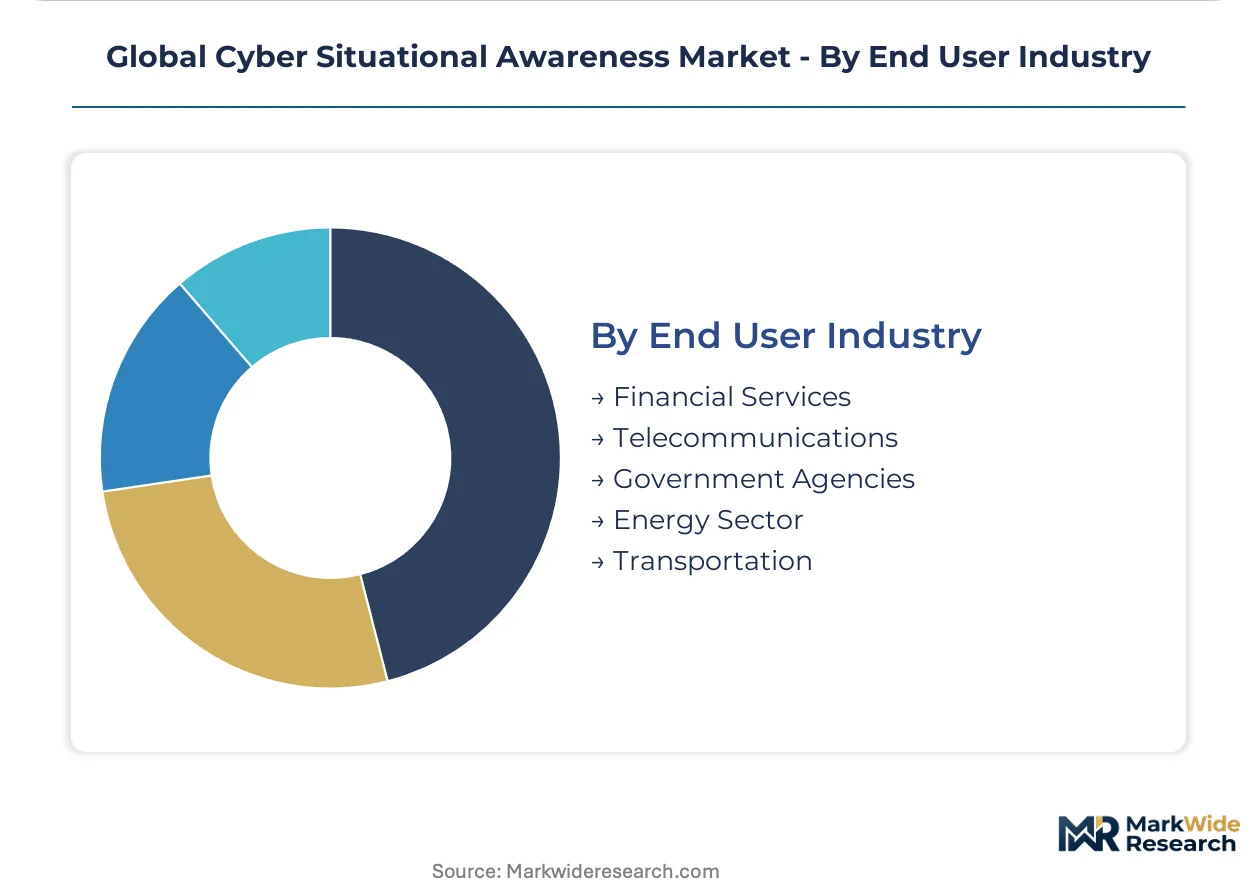
- Financial Services:Banks, investment firms, and insurance companies deploy advanced situational awareness to protect high-value customer data, prevent fraud, and comply with stringent regulations like PCI DSS and GDPR. This sector faces persistent, sophisticated attacks from financially motivated cybercriminals.
- Government Agencies:National and local government entities utilize these platforms to protect critical national infrastructure, classified information, and citizen data from state-sponsored attacks and espionage. Defense and intelligence agencies are particularly heavy users.
- Telecommunications:Providers of internet, mobile, and voice services require robust situational awareness to secure their vast network infrastructures and protect subscriber data. They also combat denial-of-service attacks and network intrusions.
- Energy Sector:Critical infrastructure operators in electricity, oil, and gas deploy solutions to monitor and protect operational technology (OT) systems and industrial control systems (ICS) from cyber-physical attacks. The US Cybersecurity and Infrastructure Security Agency (CISA) mandates enhanced security in this sector.
- Transportation:Airlines, shipping companies, and public transit systems adopt cyber situational awareness to secure operational systems, logistics networks, and passenger data. The increasing digitalization of transportation infrastructure creates new attack surfaces.
Financial Services consistently demands advanced capabilities. The Energy Sector is rapidly increasing its adoption of these platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cyber situational awareness market is significantly anchored by regions demonstrating high concentrations of both advanced technological expertise and stringent regulatory demands. Key geographic areas drive innovation in security platforms and necessitate robust defense mechanisms against evolving cyber threats.
United States
Demand for cyber situational awareness in the United States stems from critical infrastructure protection and a sophisticated financial services sector. The US Cybersecurity and Infrastructure Security Agency (CISA) directives mandate enhanced threat detection. Silicon Valley and Washington D.C. serve as hubs for cybersecurity innovation and government procurement.
Germany
Germany's industrial manufacturing base and strong privacy regulations fuel demand for advanced security analytics and threat intelligence platforms. The EU's GDPR and national cybersecurity laws compel comprehensive data monitoring. Munich and Berlin are significant centers for industrial cybersecurity research, protecting operational technology environments.
China
China's rapidly expanding digital economy and critical information infrastructure protection mandates drive substantial investment. The Cybersecurity Law imposes strict obligations on operators within its borders for data security. Beijing and Shanghai host major technology companies and government initiatives focused on national cybersecurity capabilities.
United Kingdom
The United Kingdom's robust financial services sector and government initiatives for national security are primary demand drivers. The National Cyber Security Centre (NCSC) guides organizations on threat intelligence and incident response. London's financial district and technology hubs foster significant adoption of advanced security platforms.
Israel
Israel's position as a global leader in cybersecurity innovation and its defense industry requirements generate strong demand. The National Cyber Directorate promotes a vibrant ecosystem for security technology development. Tel Aviv and Beer Sheva are central to the country's cybersecurity startup scene and research institutions.
Global Cyber Situational Awareness Market Key Industry Players
Portfolio diversification dominates the current landscape, as vendors expand capabilities to address the convergence of security domains. The market exhibits a tiered structure, with large platform providers alongside specialized solution developers. Strategic archetypes include integrated platform vendors, cloud-native specialists, and elite threat intelligence providers. Competitive moves center on technology integration, strategic partnerships, and geographic expansion to capture market share.
Within the integrated platform archetype, Palo Alto Networks Inc. exemplifies a strategy of consolidating network, cloud, and endpoint security into a unified offering. Microsoft Corporation represents another major player, leveraging its extensive enterprise software portfolio and Azure cloud services for advanced threat intelligence. CrowdStrike Holdings Inc. occupies a position as a cloud-native endpoint protection specialist, offering elite threat hunting services to sophisticated adversaries.
| Leading Market Players |
|---|
| Palo Alto Networks Inc. |
| Check Point Software Technologies Ltd. |
| International Business Machines Corporation |
| Darktrace PLC |
| Fortinet Inc. |
| Microsoft Corporation |
| CrowdStrike Holdings Inc. |
| Palantir Technologies Inc. |
| Cisco Systems Inc. |
| Others |
Cost & Logistics Intelligence
Government procurement programs and large enterprise buyers often dictate pricing models, focusing on long-term value and comprehensive service level agreements. This buyer concentration influences vendors to offer integrated platforms with bundled support, ensuring operational continuity for critical infrastructure. The emphasis shifts from transactional sales to recurring revenue models driven by ongoing threat intelligence and platform maintenance.
Pricing Analysis
Bundled service agreements, including 24/7 support and managed threat intelligence feeds, define the core pricing model for cyber situational awareness platforms. Price differentiation stems from the level of AI-driven automation and the depth of integration with existing enterprise security ecosystems. Pricing pressure emerges from the proliferation of open-source security tools and the increasing availability of cloud-native alternatives. Government agencies and financial institutions exhibit lower price sensitivity due to stringent compliance requirements, while smaller enterprises remain highly price-conscious.
Supply Chain Analysis
Single-source vulnerability sits with highly specialized threat intelligence providers and advanced AI algorithm developers, where expertise is concentrated. The supply chain for cyber situational awareness platforms primarily draws from cloud infrastructure providers in the United States and Ireland, and specialized software development talent in Israel and the United States. A structural risk involves the rapid obsolescence of threat intelligence data, requiring constant updates and investment. Distribution runs through direct enterprise sales teams and value-added resellers, particularly for complex integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cyber situational awareness market is in a technology-transition phase, with AI-driven automation rapidly displacing manual security operations. This shift compels organizations to re-evaluate their security postures and platform investments.
For Market Incumbents:To counter the threat of fragmented point solutions and specialized cloud-native entrants, incumbents must prioritize seamless integration across network, cloud, and endpoint security domains. Investing heavily in AI/ML research and development for predictive analytics capabilities will differentiate offerings. Strategic partnerships with cloud service providers can extend platform reach and enhance data ingestion capabilities, solidifying market position against evolving threats. Consolidating disparate security tools into a unified platform remains a critical defensive move.
For New Entrants and Emerging Players:Specialized AI-driven analytics platforms represent a technology-first wedge into the established cyber situational awareness market. Targeting underpenetrated segments like Operational Technology (OT) security in industrial settings offers significant white-space opportunities. A strong go-to-market angle involves offering managed detection and response (MDR) services, reducing the talent burden for end-users. Focusing on a specific industry vertical, such as mid-market healthcare, can enable rapid market penetration.
For Investors and Strategic Acquirers:Distressed-cycle entries favor acquirers seeking cutting-edge AI/ML capabilities or niche OT security expertise in regions like Israel and the United States. The long-term viability of cyber situational awareness platforms depends on their ability to integrate predictive analytics with real-time threat detection. Acquisition targets should include specialized firms with strong intellectual property in threat intelligence or security orchestration automation and response (SOAR). A key signal to watch is the increasing consolidation activity among smaller, innovative security analytics companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-driven Predictive Analytics | Enhances proactive threat neutralization before attacks fully materialize, reducing enterprise risk exposure. |
| Expand Managed Security Services | Addresses the global cybersecurity talent shortage, providing comprehensive security operations to clients. |
| Develop OT/ICS Security Modules | Protects critical infrastructure from cyber-physical threats, opening new revenue streams in industrial sectors. |
| Forge Cloud Provider Partnerships | Ensures seamless integration with multi-cloud environments, crucial for modern enterprise security architectures. |
| Acquire Niche Threat Intelligence Firms | Strengthens proprietary threat detection capabilities, offering superior insights into emerging adversary tactics. |
Research Approach
Document review covered industry reports, regulatory publications from CISA and GDPR, and vendor whitepapers, complemented by interviews with Chief Information Security Officers (CISOs), security architects, and IT procurement managers. This primary research engaged global stakeholders across financial services, government, and technology sectors. Secondary validation involved cross-referencing findings with publicly available data from cybersecurity agencies and industry consortia, employing both bottom-up and top-down triangulation.
The analytical framework cross-referenced historical market performance with expert panel input to project future trends across the analysis window. Segmentation dimensions modeled included deployment type, solution type, use case, and end-user industry, along with an industry-specific dimension for integration complexity. Compound Annual Growth Rates (CAGRs) were derived through a comprehensive analysis of market drivers, restraints, and strategic opportunities. Forecast inputs included projected cyberattack frequency and anticipated regulatory changes.
Several conditions sit outside the modeled scope, including unforeseen geopolitical cyber conflicts and rapid, disruptive technological breakthroughs like quantum computing. Forecasts reflect assumptions regarding stable economic conditions and consistent regulatory enforcement. Deviation in the pace of AI adoption or major shifts in geopolitical cyber warfare would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cyber Warfare Market
Cybersecurity
Oman Cybersecurity Market
Cybersecurity
E-Mail Security Market
Cybersecurity
Container-based Firewall Market
Cybersecurity
Mainframe Security Market
Cybersecurity
South Korea Cybersecurity Market
Cybersecurity
CDN Security Market
Cybersecurity
Cyber Security in Energy Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
Cloud Security Gateway Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
Bahrain Cybersecurity Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Asia Pacific Data Exfiltration Market