
 Cyber Warfare Market | 2026-2036
Cyber Warfare Market Size, Share, and Industry Trends Forecast 2026-2036
Cyber Warfare Market Intelligence
A shortage of cleared cybersecurity professionals with active security clearances is unwinding delivery timelines across classified program pipelines. Lockheed Martin Corporation leverages its Bethesda headquarters proximity to NSA and Cyber Command to sustain preferential access to threat intelligence contracts. BAE Systems plc anchors its UK and US operations around signals intelligence platforms that dominate Five Eyes procurement cycles. Northrop Grumman Corporation competes through Mission Systems integration that extends cyber effects into airborne and space domains.
Cyber warfare encompasses state-sponsored offensive and defensive digital operations targeting adversary networks, infrastructure, and data integrity through exploit deployment, persistent access maintenance, and kinetic-cyber effect coordination. These operations rely on zero-day vulnerability research, custom malware toolchains, and real-time command-and-control infrastructure operating below detection thresholds across commercial carrier networks. Network Security applications absorb the largest share of government spending as perimeter hardening remains foundational to critical infrastructure protection. Cloud Security represents the fastest-expanding application segment as intelligence agencies migrate classified workloads to government cloud environments and demand sovereign data residency controls. Managed Services deployment models are capturing margin pools from agencies lacking internal red-team capacity and seeking subscription-based threat hunting.
The US Cybersecurity and Infrastructure Security Agency, UK National Cyber Security Centre, and EU ENISA collectively shape procurement standards through mandatory certification regimes and incident disclosure timelines that filter vendor eligibility. NIS2 and the EU Cyber Solidarity Act are forcing European operators to retain incident response retainers and report breaches within strict windows, directly expanding addressable market for MSSP end users. Stakeholders must weigh sovereign capability investment against contractor dependency as classification barriers and citizenship requirements constrain labor mobility across allied programs.
Market Dynamics
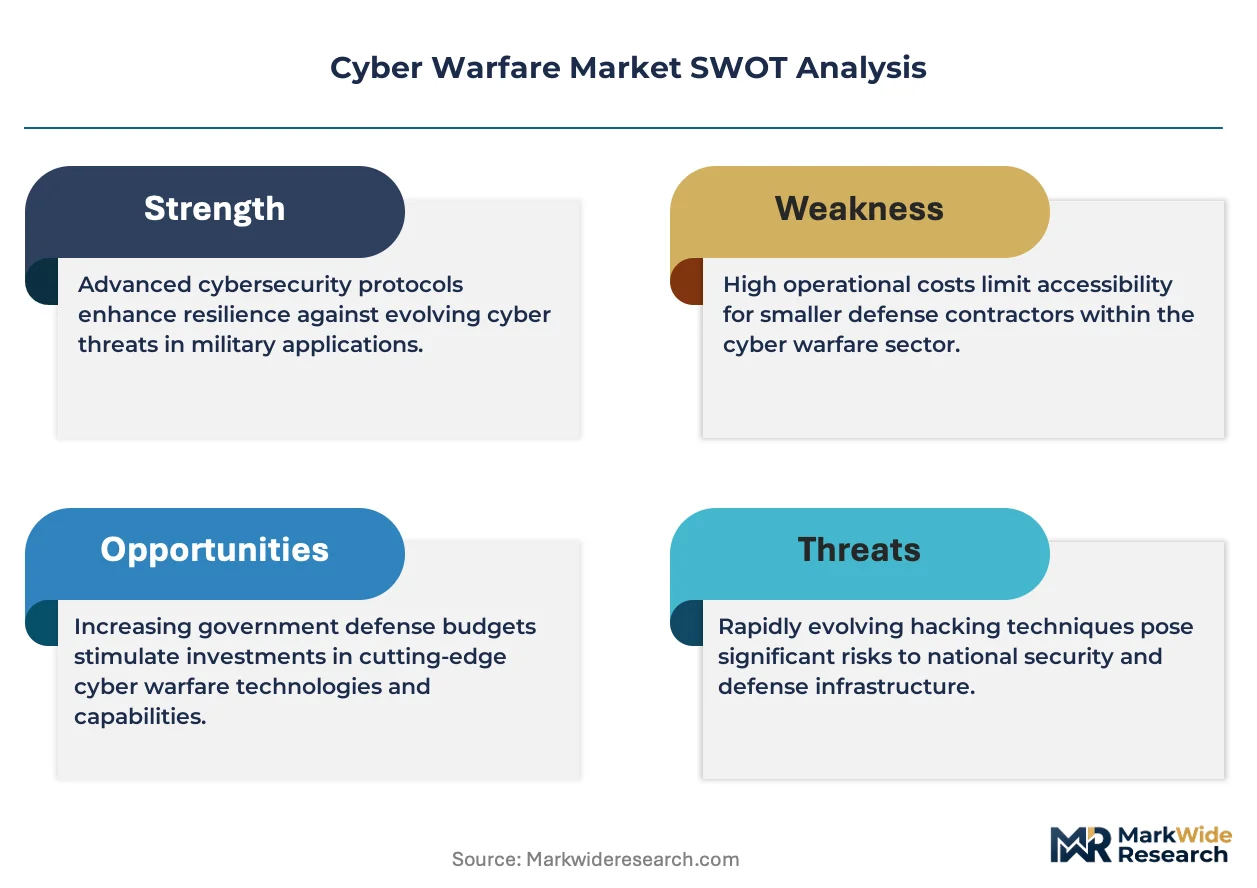
The classified program pipeline is choking on cleared-labor scarcity, forcing defense primes to bid fixed-price contracts they cannot staff while NATO members accelerate offensive cyber procurement timelines. This structural tension between demand velocity and security-cleared workforce availability defines current market mechanics.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting windows and supply chain security standards for critical infrastructure operators are expanding MSSP addressable market across European energy and transport sectors.
- Zero-day vulnerability research:State-sponsored investment in exploit discovery capabilities is accelerating procurement of custom malware toolchains and persistent access platforms by intelligence agencies.
- Five Eyes signals intelligence integration:Cross-border data sharing frameworks are standardizing procurement cycles for airborne and space-domain cyber effects platforms across allied defense ministries.
Market Restraints
- Citizenship-cleared labor scarcity:Classification barriers constrain labor mobility across US, UK, and allied programs, extending delivery timelines for classified contracts by 18-24 months.
- Sovereign data residency mandates:EU Cyber Solidarity Act and national cloud sovereignty requirements are fragmenting vendor addressable market and duplicating infrastructure investment.
- Custom toolchain development costs:Tailored malware and C2 infrastructure for below-threshold operations require sustained R&D spend that mid-tier contractors cannot amortize across programs.
Strategic Opportunities
- Cloud Security migration:Intelligence agencies moving classified workloads to government cloud environments are creating demand for sovereign data residency controls and zero-trust architecture integration.
- Managed Services subscription models:Agencies lacking internal red-team capacity are outsourcing continuous threat hunting, capturing recurring revenue pools from federal cyber budgets.
- Kinetic-cyber effect coordination:Convergence of electronic warfare and cyber operations is opening procurement channels for platforms integrating airborne, space, and network domains under unified command structures.
Industry Challenges
- Active security clearance pipeline:Defense contractors face 12-18 month adjudication delays for personnel clearances, forcing program staffing with uncleared labor and segmented work environments.
- Cross-domain integration complexity:Cyber effects platforms must interface with legacy mission systems across air, space, and maritime domains, requiring costly middleware development and extended test cycles.
- Attribution and rules-of-engagement ambiguity:Unclear legal frameworks for offensive cyber operations create procurement hesitation and contract scope limitations among risk-averse agency legal offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyber Warfare Market |
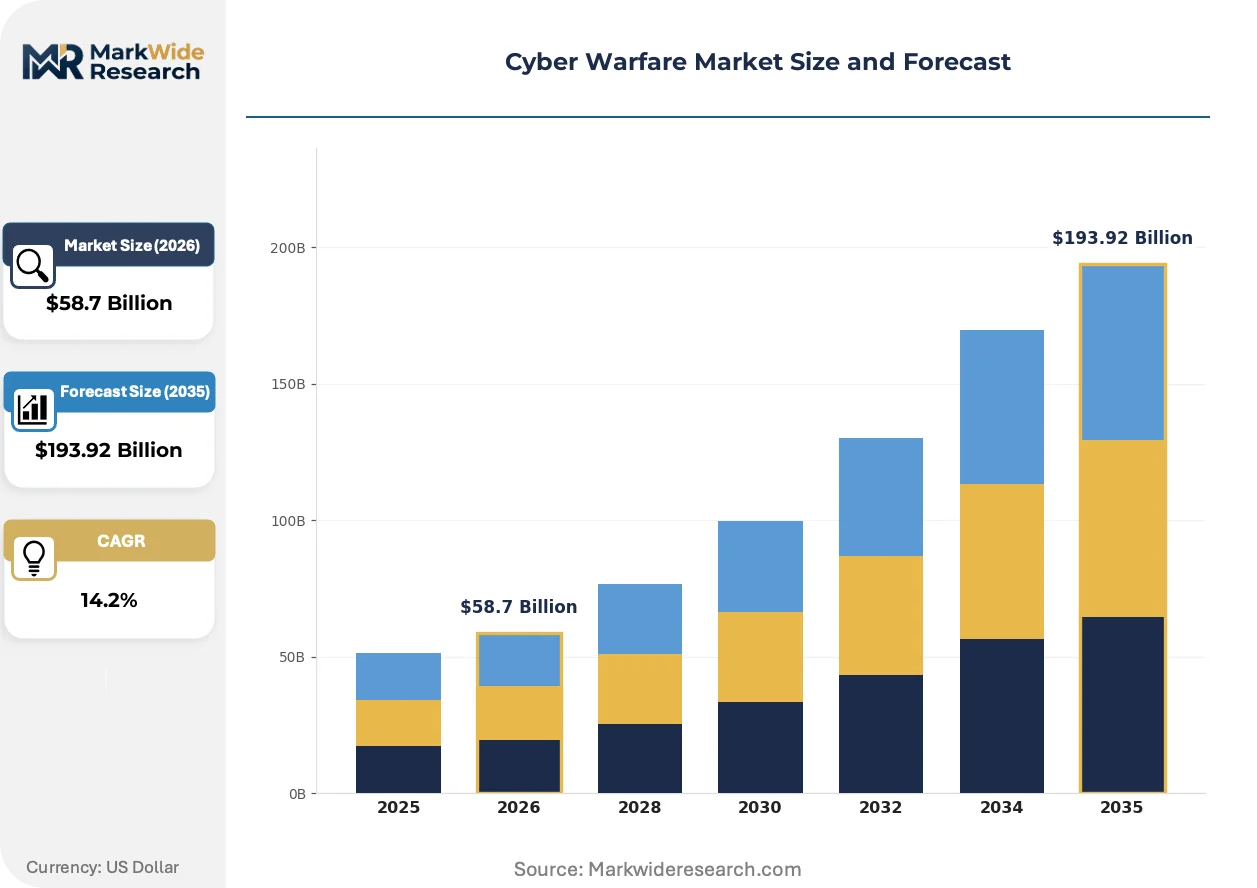
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $193.92 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Intrusion Detection Systems, Firewalls, Antivirus Software, Encryption Tools Application: Network Security, Application Security, Endpoint Security, Cloud Security Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Government Agencies, Military, Corporations, Managed Security Service Providers |
| Companies Covered | Lockheed Martin Corporation, BAE Systems plc, Northrop Grumman Corporation, Raytheon Technologies Corporation, General Dynamics Corporation, Boeing, L3Harris Technologies, Inc., Leonardo S.p.A., Booz Allen Hamilton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyber Warfare Market Strategic Shifts & Innovations
Operational technology convergence is dissolving boundaries between IT and OT security domains, while sovereign cloud mandates and AI-augmented threat detection are restructuring vendor competitive requirements. These forces are compressing procurement cycles and elevating technical certification barriers simultaneously.
Edge-deployed cyber effect platforms are miniaturizing exploit delivery and command-and-control infrastructure for installation on unmanned aerial systems and tactical vehicles. Special operations commands across NATO members are fielding these capabilities for contested environment access. This footprint reduction is miniaturizing the tradecraft threshold, enabling non-traditional defense contractors to compete for previously inaccessible programs.
The EU Cyber Solidarity Act and NIS2 Directive are mandating harmonized incident response standards and cross-border mutual assistance protocols for critical infrastructure operators. Industrial consequence includes mandatory retainer contracts with certified incident response providers and standardized breach disclosure timelines. Energy and transport operators in Germany, France, and the Netherlands are consolidating vendor relationships to meet certification complexity.
Subscription-based threat hunting is displacing traditional project-based penetration testing across federal and defense agency procurement. MSSPs with cleared personnel pools are capturing multi-year managed detection and response contracts previously awarded to boutique consultancies. This pattern is most visible in US Cyber Command and UK National Cyber Security Centre supplier base evolution, where recurring revenue models now dominate competitive evaluation criteria.
Cyber Warfare Market Segmentation
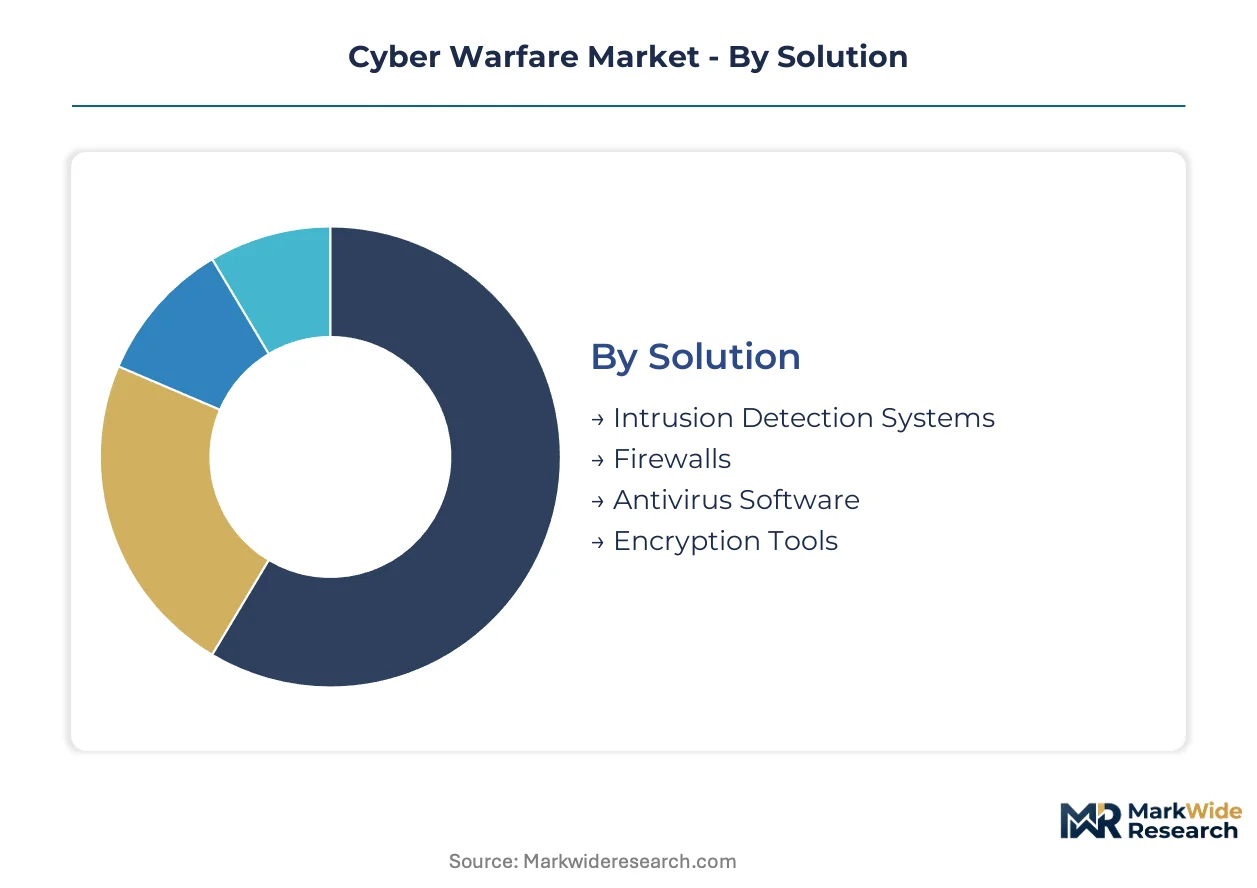
Cyber warfare procurement divides sharply across classified and unclassified channels, with regulatory certification requirements determining vendor eligibility for each segment tier. Defense primes structure product portfolios around clearance-accessible labor pools while commercial vendors compete for infrastructure-hardening contracts.
Solution:
EU NIS2 and US FedRAMP certification regimes create divergent technical requirements for perimeter defense tools across Atlantic procurement channels.
- Intrusion Detection Systems:Signature-based and behavioral analytics platforms monitor traffic patterns for persistent access indicators. US Cyber Command and UK National Cyber Security Centre procurement concentrates on systems with classified threat feed integration, constrained by cleared-analyst staffing requirements.
- Firewalls:Next-generation platforms with deep packet inspection and application-layer filtering form the perimeter foundation for critical infrastructure operators. German energy utilities and French transport operators under NIS2 mandates are consolidating vendor relationships around certified providers with EU sovereign data residency guarantees.
- Antivirus Software:Endpoint protection platforms with heuristic detection engines address commodity malware threats in commercial environments.
- Encryption Tools:Hardware security modules and quantum-resistant algorithms protect data-at-rest for classified workloads.
Firewalls handle the majority of throughput; Cloud Security is gaining share fastest as intelligence agencies migrate sensitive workloads.
Application:
Cost tiering separates foundational perimeter hardening from premium cloud-native protection requiring sovereign data controls.
- Network Security:Perimeter hardening through segmentation, access control, and traffic monitoring remains the baseline procurement category for critical infrastructure. US federal cyber budgets allocate sustained funding here, though European operators under NIS2 face compressed implementation timelines.
- Cloud Security:Zero-trust architecture and sovereign data residency controls address classified workload migration to government cloud environments. UK and Australian intelligence agencies are driving demand for platforms with Five Eyes-certified encryption key management.
- Application Security:Code scanning and runtime protection tools secure software supply chains for defense contractors.
- Endpoint Security:Device-level protection extends to operational technology networks in energy and manufacturing sectors.
Network Security absorbs the largest budget allocation; Cloud Security expands most quickly as sovereign cloud mandates proliferate.
Deployment:
Customer capability maturity determines whether agencies retain operational control or outsource to cleared personnel pools.
- Managed Services:Subscription-based threat hunting and continuous monitoring capture agencies lacking internal red-team capacity. US Cyber Command and UK NCSC supplier bases are shifting evaluation criteria toward recurring revenue models, with multi-year MDR contracts displacing project-based penetration testing.
- Cloud-Based:Scalable infrastructure without capital expenditure appeals to mid-tier defense contractors facing cleared-labor scarcity. EU Cyber Solidarity Act requirements are fragmenting vendor addressable market as data residency mandates multiply.
- On-Premises:Air-gapped systems maintain operational independence for highest-classification programs.
- Hybrid:Split architectures balance sensitive workload isolation with commercial cloud scalability.
Managed Services captures margin expansion; Cloud-Based deployment climbs the fastest as procurement velocity outstacks internal staffing capacity.
End User:
Classification barriers segment addressable market by citizenship-cleared labor availability and program access tiers.
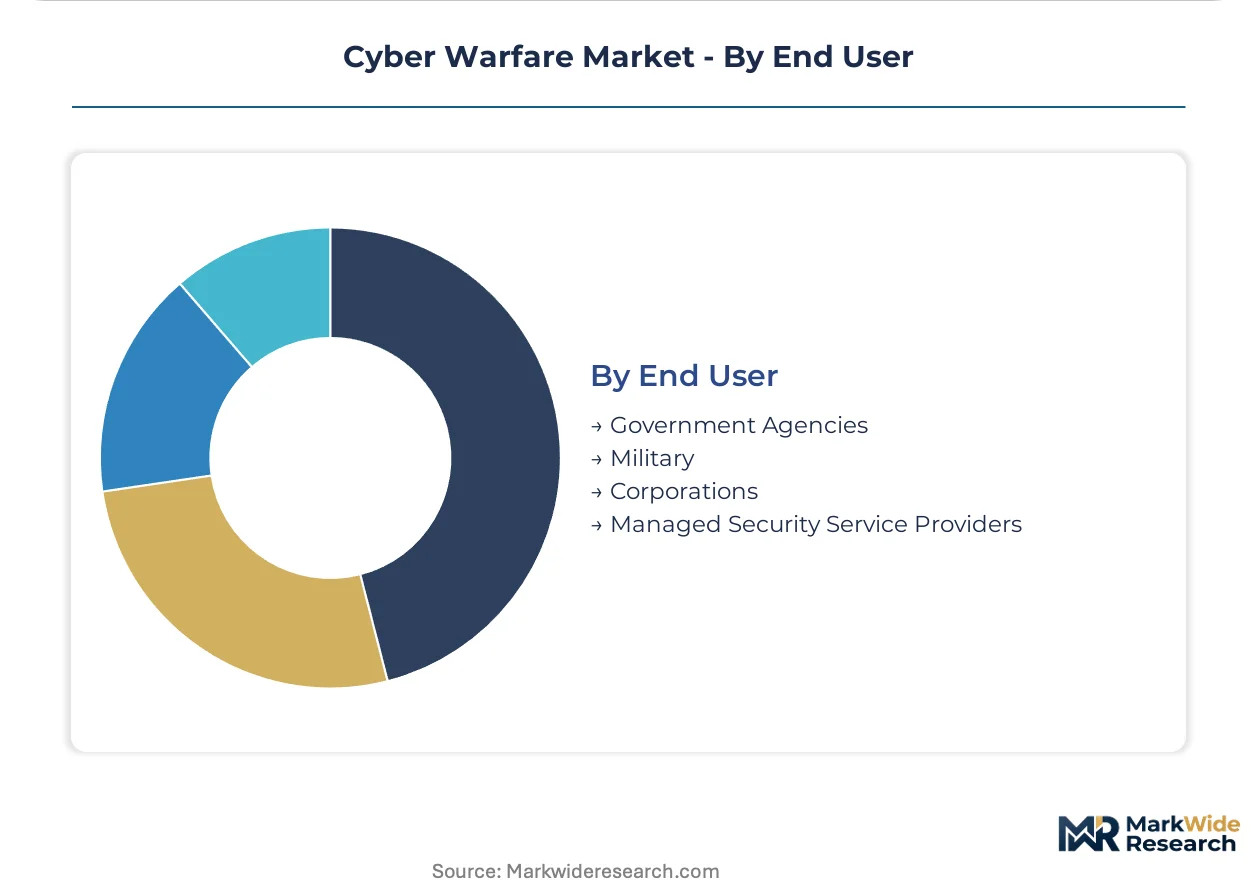
- Government Agencies:Civilian departments with critical infrastructure mandates drive standardized procurement through CISA and ENISA certification regimes. NIS2 incident reporting windows are expanding MSSP retainer contracts across German, French, and Dutch energy operators.
- Military:Offensive cyber capability procurement concentrates in US Cyber Command, UK Strategic Command, and allied special operations forces. Five Eyes integration frameworks standardize airborne and space-domain cyber effects platforms across these ministries.
- Corporations:Defense industrial base contractors face supply chain security requirements cascading from prime contractor security mandates.
- Managed Security Service Providers:Intermediary vendors with cleared personnel pools bridge capability gaps for agencies lacking internal expertise.
Government Agencies anchor procurement volume; Military programs are expanding most quickly as NATO members accelerate offensive cyber investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States agencies prioritize offensive cyber capability procurement, while European operators concentrate spending on NIS2-mandated incident response infrastructure. This divergence reflects fundamentally different consumption patterns across Atlantic defense markets.
United States
Federal cyber budgets and Silicon Valley contractor ecosystems reinforce procurement velocity for classified programs. CISA certification regimes standardize vendor eligibility for critical infrastructure contracts. The National Capital Region concentration around Fort Meade and Bethesda sustains cleared-labor pipelines for intelligence agency toolchains.
United Kingdom
UK Strategic Command and the National Cyber Security Centre drive demand for Five Eyes-integrated signals intelligence platforms. Government procurement standards filter vendor access through strict citizenship-cleared requirements. London and Cheltenham clusters anchor GCHQ-adjacent contractor ecosystems for airborne cyber effects.
Germany
Bundeswehr Cyber and Information Domain Service accelerates offensive capability investment alongside NIS2 compliance spending. The country's national cybersecurity regulator enforces mandatory incident reporting windows for energy operators. Munich and Frankfurt industrial corridors concentrate MSSP retainer contracts for critical infrastructure protection.
France
Direction du Renseignement Militaire procures sovereign cyber effect platforms for contested environment operations. ANSSI certification requirements constrain foreign vendor participation in classified procurement cycles. Paris-Saclay and Toulouse defense clusters sustain domestic prime contractor development for space-domain cyber capabilities.
Australia
Australian Signals Directorate migration to government cloud environments creates demand for sovereign data residency controls. Five Eyes integration frameworks standardize procurement with allied defense ministries. Canberra and Adelaide defense corridors concentrate cleared personnel pools for cyber effects platform integration.
Cyber Warfare Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with classification barriers determining access to revenue pools. Defense primes structure portfolios around cleared-labor availability rather than pure technology differentiation. Two strategic archetypes dominate: full-spectrum platform integrators extending cyber effects across kinetic domains, and cleared-personnel aggregators capturing managed services contracts. Competitive moves concentrate on vertical integration into classified program pipelines and geographic expansion through Five Eyes partnership structures.
Within the full-spectrum integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify platform providers leveraging proximity to Fort Meade and Cyber Command for threat intelligence contract access. BAE Systems plc occupies a position bridging UK and US operations through Five Eyes procurement standardization. These three entities represent the archetype of cleared-labor-dependent primes competing on program execution velocity rather than standalone product differentiation.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems plc |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| General Dynamics Corporation |
| Boeing |
| L3Harris Technologies, Inc. |
| Leonardo S.p.A. |
| Booz Allen Hamilton |
| Others |
Cost & Logistics Intelligence
Classified program scale economies concentrate pricing power among defense primes with cleared-labor pipelines, compressing margins for mid-tier contractors unable to amortize custom toolchain development across multiple agency customers. The feedback loop between security-cleared workforce scarcity and fixed-price contract bidding is elevating price floors for mission-critical cyber effects platforms.
Pricing Analysis
Long-term subscription contracts dominate procurement as US Cyber Command and UK NCSC shift evaluation criteria toward recurring revenue models. Three-tier pricing structure across classified, dual-use, and commercial certification levels captures margin differentiation driven by citizenship-cleared analyst requirements and sovereign data residency guarantees. Cost compression in commercial-tier perimeter hardening reflects vendor consolidation around NIS2-certified providers. Defense industrial base contractors exhibit highest price sensitivity due to cascading prime contractor security mandates.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores geographic concentration of semiconductor fabrication for tactical cyber effect platforms in Taiwan, South Korea, and the United States. Custom malware toolchain development draws from zero-day vulnerability research pipelines, quantum-resistant cryptographic libraries, and airborne platform miniaturization components. Single-source vulnerability in classified threat feed integration creates procurement risk for agencies dependent on Fort Meade-adjacent contractor ecosystems. Distribution runs through cleared-personnel aggregators bridging capability gaps for agencies lacking internal red-team capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is restructuring competitive advantage around ecosystem interoperability, as Five Eyes procurement standardization rewards vendors with cross-domain integration capabilities spanning airborne, space, and network effects.
For Market Incumbents: Compound cleared-labor pipeline advantages through captive training partnerships with NSA and Cyber Command feeder programs, while deepening upstream control over zero-day vulnerability research sources. Emerging non-traditional defense contractors with unmanned systems miniaturization expertise threaten traditional prime margins in special operations procurement channels. For New Entrants and Emerging Players: FedRAMP authorization fast-track programs unlock federal cloud security procurement channels previously sealed by incumbent certification moats. White-space concentration in EU NIS2-mandated MSSP retainer contracts for German and French energy operators offers penetrable entry points. Channel partnerships with established cleared-personnel aggregators accelerate government sales cycle velocity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed detection and response providers with multi-year US Cyber Command and UK NCSC contracts. Long-term viability rests on sovereign capability investment trajectories as classification barriers constrain cross-border labor mobility. Watch for inflection signals in airborne cyber effects platform procurement acceleration across NATO special operations commands.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Five Eyes standardization rewards vendors with unified command structures across kinetic-cyber domains. |
| Acquisition of Specialist Firm | Zero-day research boutiques with cleared personnel pools command premium valuations from primes. |
| Geographic Expansion | Canberra and Adelaide corridor presence anchors Australian Signals Directorate cloud migration capture. |
| Strategic Partnership | NSA-adjacent threat intelligence sharing agreements sustain preferential contract access for Bethesda cluster firms. |
| Product Launch | Edge-deployed cyber effect platforms for contested environments open NATO special operations procurement channels. |
Research Approach
The analysis maps intrusion detection systems, cloud security platforms, managed services deployment, and kinetic-cyber effect integration, each validated through program managers at defense primes, cleared cybersecurity contractors, agency procurement officers, and signals intelligence platform engineers. Primary interview findings triangulate against secondary sources including CISA certification databases, ENISA threat landscape reports, NATO cooperative cyber defense documentation, and federal cyber budget appropriations disclosures. Bottom-up segment sizing and top-down macro constraint checks ensure internal consistency across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including defense procurement contract announcements, MSSP revenue disclosures, and government cloud migration spending trackers. The modeling framework segments by solution type, application domain, deployment model, and end-user classification tier, with CAGRs derived from historical spending trajectories and policy-mandated procurement acceleration timelines. Intelligence agency workload migration patterns and NIS2 compliance deadline clustering inform projection sensitivity bands.
Decision-makers should treat outputs as directional under assumptions of sustained NATO offensive cyber investment and stable cleared-labor pipeline velocity; material deviation in either would warrant model refresh. Forecasts hinge on assumptions around Five Eyes integration continuity and EU sovereign cloud mandate implementation pace. Practitioners should keep alternative scenarios live as attribution framework clarity and rules-of-engagement legal evolution reshape procurement hesitation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Digital Security Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
IoT Security Market
Cybersecurity
Egypt Cybersecurity Market
Cybersecurity
Digital Immune System Market
Cybersecurity
Global Online Fraud Detection and Prevention Market
Cybersecurity
Smart Grid Cyber Security Market
Cybersecurity
SSL VPN Market
Cybersecurity
Cryptojacking Solution Market
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Global Content Disarm and Reconstruction Market
Cybersecurity
Philippines Cybersecurity Market
Cybersecurity
South Africa Cybersecurity Market
Cybersecurity
Cloud-Based Email Security Market