
 Israel ICT Market | 2026-2036
Israel ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Israel ICT Market Foresight
Silicon photonics is hardening as the preferred interconnect substrate inside Israeli data centers, displacing traditional copper backplanes at the 400G threshold and above. Mobileye leverages its autonomous-driving sensor fusion stack to dominate edge-AI silicon design. Cato Networks sustains cloud-native SD-WAN specialization across mid-market enterprise accounts. Microsoft anchors hyperscale cloud capacity through its Israel Central region datacenter investments.
Israel ICT encompasses information and communication technology systems spanning software applications, semiconductor hardware, packet-switched networking gear, and distributed cloud infrastructure, typically operating at latency thresholds below 20 milliseconds for real-time enterprise workloads. Its primary commercial purpose is to digitize organizational workflows, secure data assets, and enable algorithmic decision-making across connected device fleets. Software and cloud services together command the dominant margin pool, while cybersecurity within the technology dimension absorbs disproportionate R&D capital due to Israel's conscription-trained talent pipeline. Enterprise end users generate the largest revenue base, though healthcare adoption is accelerating as hospital networks modernize electronic record systems.
The Israeli National Cyber Directorate enforces binding cybersecurity standards for critical infrastructure operators, directly shaping procurement specifications for domestic vendors and foreign entrants. BIS-equivalent certification requirements for government cloud deployments create compliance barriers that favor locally audited service providers. ISO 27001 and IEC 62443 frameworks further constrain supply-side participation in defense-adjacent segments. Stakeholders must monitor whether proposed amendments to data localization rules will fragment cloud architecture strategies or reinforce Tel Aviv-centric infrastructure concentration.
Market Dynamics
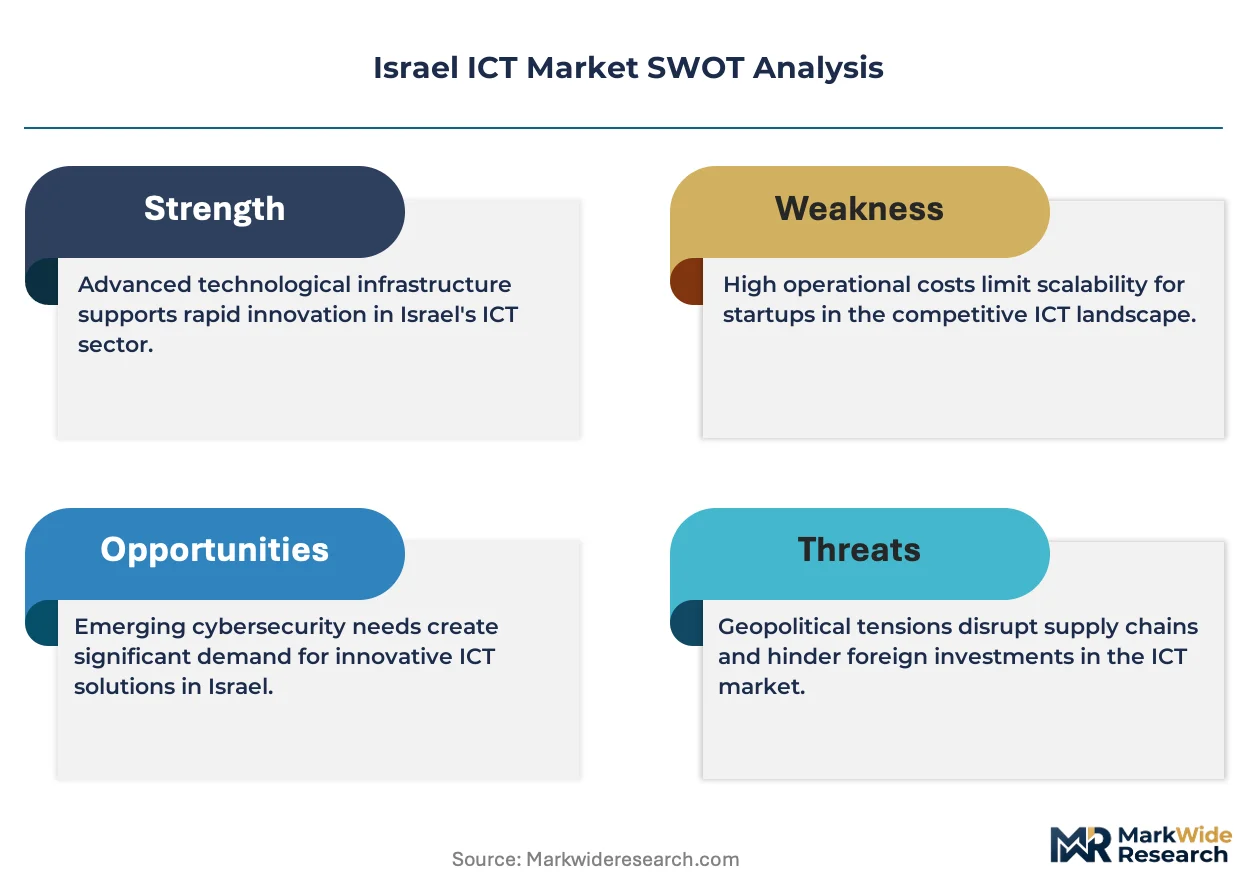
Silicon photonics is restructuring data center interconnect economics inside Israel, forcing incumbent copper-backplane suppliers to retool at the 400G threshold while defense procurement tightens data sovereignty requirements for cloud infrastructure.
Growth Catalysts
- National Cyber Directorate mandates:Binding cybersecurity standards for critical infrastructure operators are expanding procurement volumes for domestically audited cloud service providers. Defense agencies now require sovereign data residency for classified workloads.
- Tel Aviv technology corridor concentration:Venture funding flows into artificial intelligence startups, concentrating demand for high-performance compute infrastructure within a 50-kilometer radius. This density reduces latency for real-time enterprise applications.
- Silicon photonics transition:400G-and-above interconnect requirements are displacing copper backplanes in hyperscale facilities. Israeli data center operators are accelerating fiber-optic infrastructure refresh cycles.
Market Restraints
- Specialized engineering talent scarcity:Conscription-trained cybersecurity expertise concentrates in defense-adjacent roles, leaving commercial cloud architecture and edge-AI silicon design roles understaffed. Compensation inflation follows.
- BIS-equivalent certification barriers:Government cloud deployments require foreign entrants to complete lengthy domestic audit processes. This friction delays market entry by 18-24 months for non-local providers.
- Optical component supply concentration:Silicon photonics transceivers depend on concentrated Asian manufacturing for indium phosphide substrates. Geopolitical friction threatens input availability for Israeli data center expansion.
Strategic Opportunities
- Healthcare electronic record modernization:Hospital networks are accelerating digitization, creating demand for HIPAA-aligned cloud infrastructure with sub-20-millisecond latency. This vertical currently absorbs under 15 percent of domestic ICT capacity.
- Edge-AI silicon design convergence:Autonomous-driving sensor fusion architectures are migrating into industrial automation and smart city deployments. Israeli fabless design houses can capture this cross-vertical application expansion.
- SD-WAN channel innovation:Cloud-native networking solutions are penetrating mid-market enterprise accounts through managed service provider bundles. This route bypasses traditional hardware procurement cycles.
Industry Challenges
- ISO 27001 and IEC 62443 certification timelines:Defense-adjacent segments require dual-framework compliance that extends sales cycles by 9-14 months. Smaller vendors lack capital reserves to sustain pre-revenue compliance investments.
- Legacy copper infrastructure stranded assets:Data center operators face write-downs on 100G-and-below switching equipment as silicon photonics mandates 400G minimums. Migration financing constraints delay facility upgrades.
- Cross-border data flow fragmentation:Proposed amendments to data localization rules may force architectural duplication between Tel Aviv-centric infrastructure and foreign cloud regions. Engineering teams must design for regulatory uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel ICT Market |
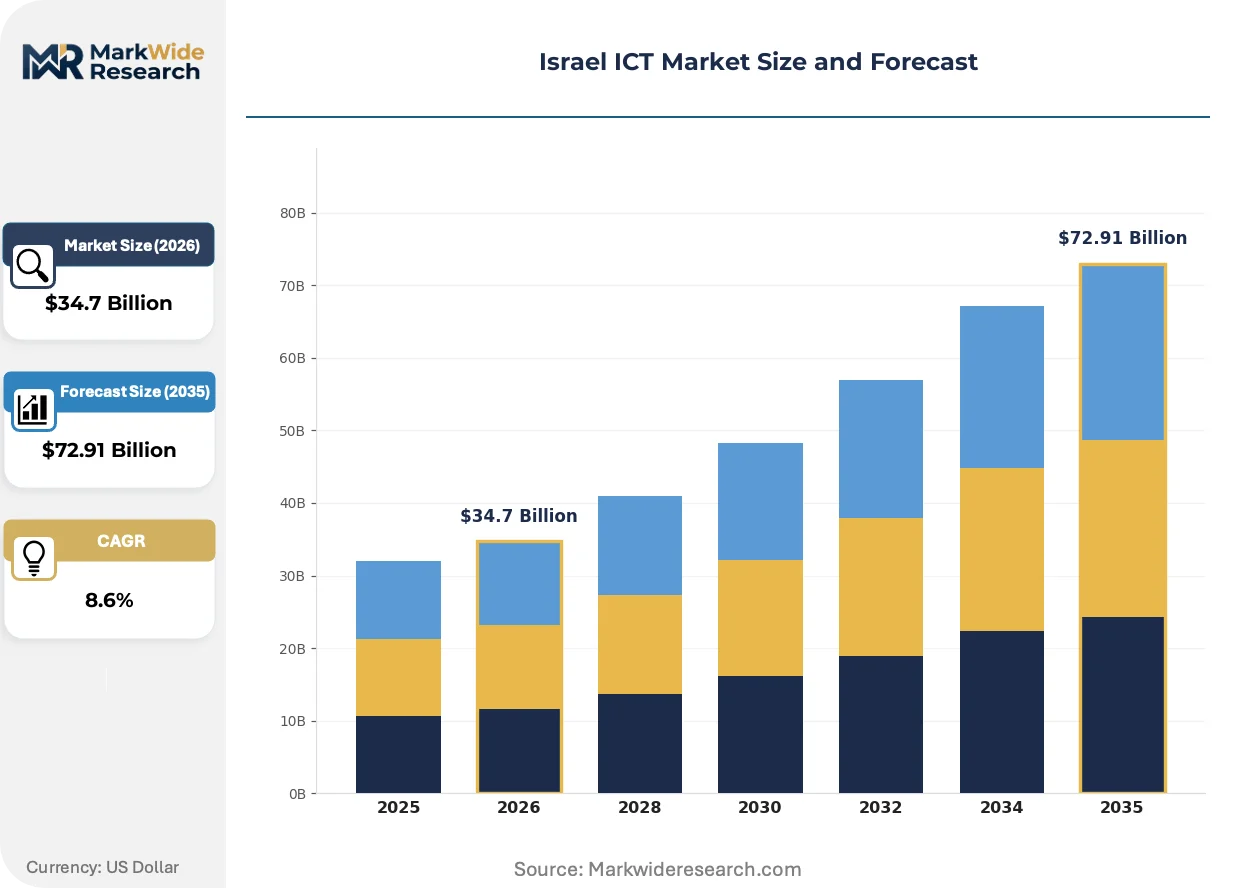
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Cloud Services End User: Government, Education, Healthcare, Enterprise Technology: AI, IoT, Blockchain, Cybersecurity Service Type: Consulting, Support, Outsourcing, Integration |
| Companies Covered | Mobileye, Riskified, Google, HiBob, Cato Networks, Microsoft, eToro, Snowflake, monday.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel ICT Market Shifts & Advancements
Active silicon photonics deployment is compressing data center power budgets while regulatory pressure on data sovereignty forces architectural redesign. Buyer behavior is simultaneously fragmenting across hyperscale, enterprise, and edge-AI deployment models.
Silicon photonics transceivers perform optical-to-electrical conversion within the package, eliminating discrete pluggable modules. Israeli hyperscale facilities are adopting these devices at 800G speeds ahead of European counterparts. This technology is integrating switching and transmission functions, collapsing traditional tiered network hierarchies into flattened fabrics.
The Israeli National Cyber Directorate has tightened binding standards for critical infrastructure data residency, extending coverage from energy and water to healthcare networks. Foreign cloud providers must establish domestically audited sovereign regions to compete for government contracts. Defense-adjacent segments are responding by consolidating procurement around locally incorporated joint ventures.
Enterprise buyers are unbundling hardware acquisition from managed service commitments, preferring consumption-based networking contracts with 12-month terms. Traditional value-added distributors are losing position to cloud-native SD-WAN specialists delivering direct subscription billing. This pattern concentrates in Tel Aviv's financial services sector, where trading floor latency requirements favor flexible capacity scaling over capital-intensive owned infrastructure.
Israel ICT Market Segmentation
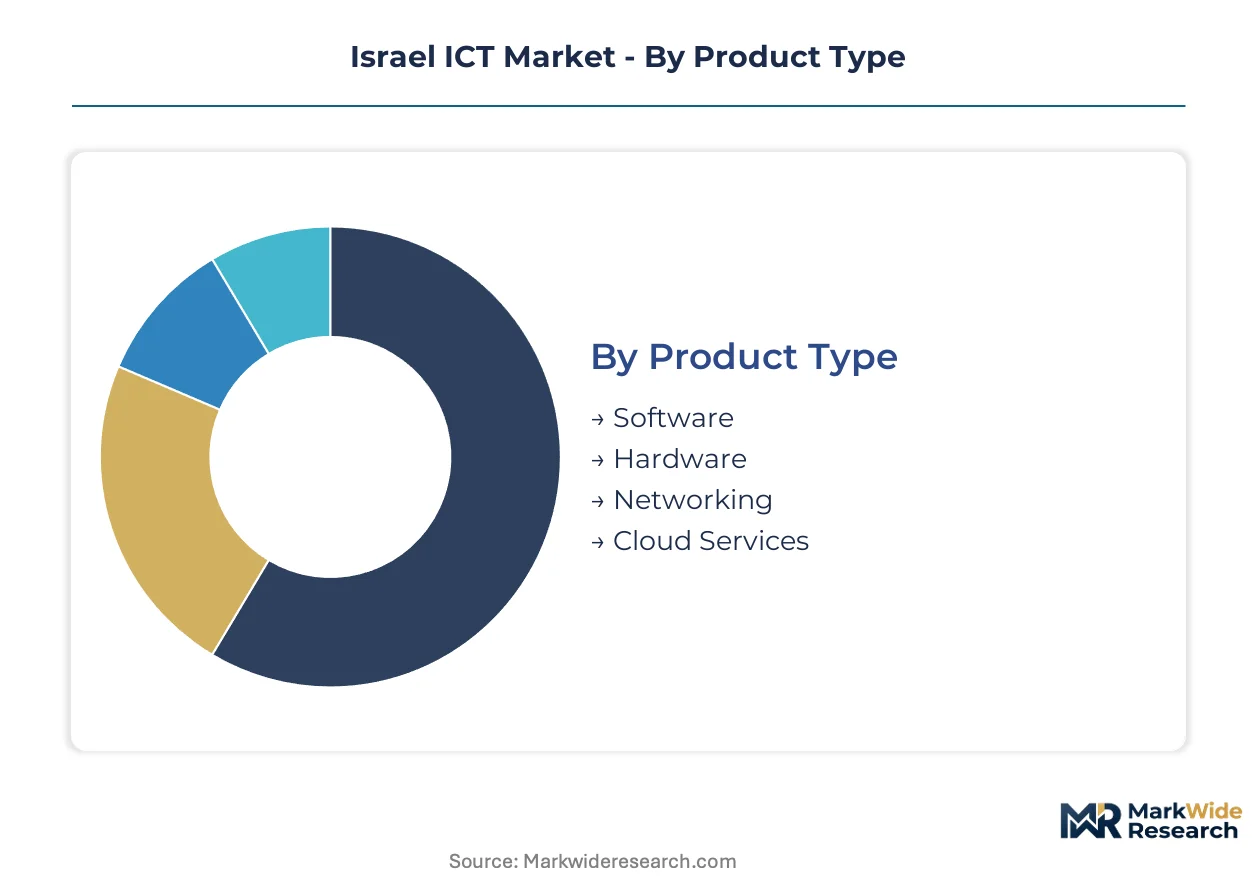
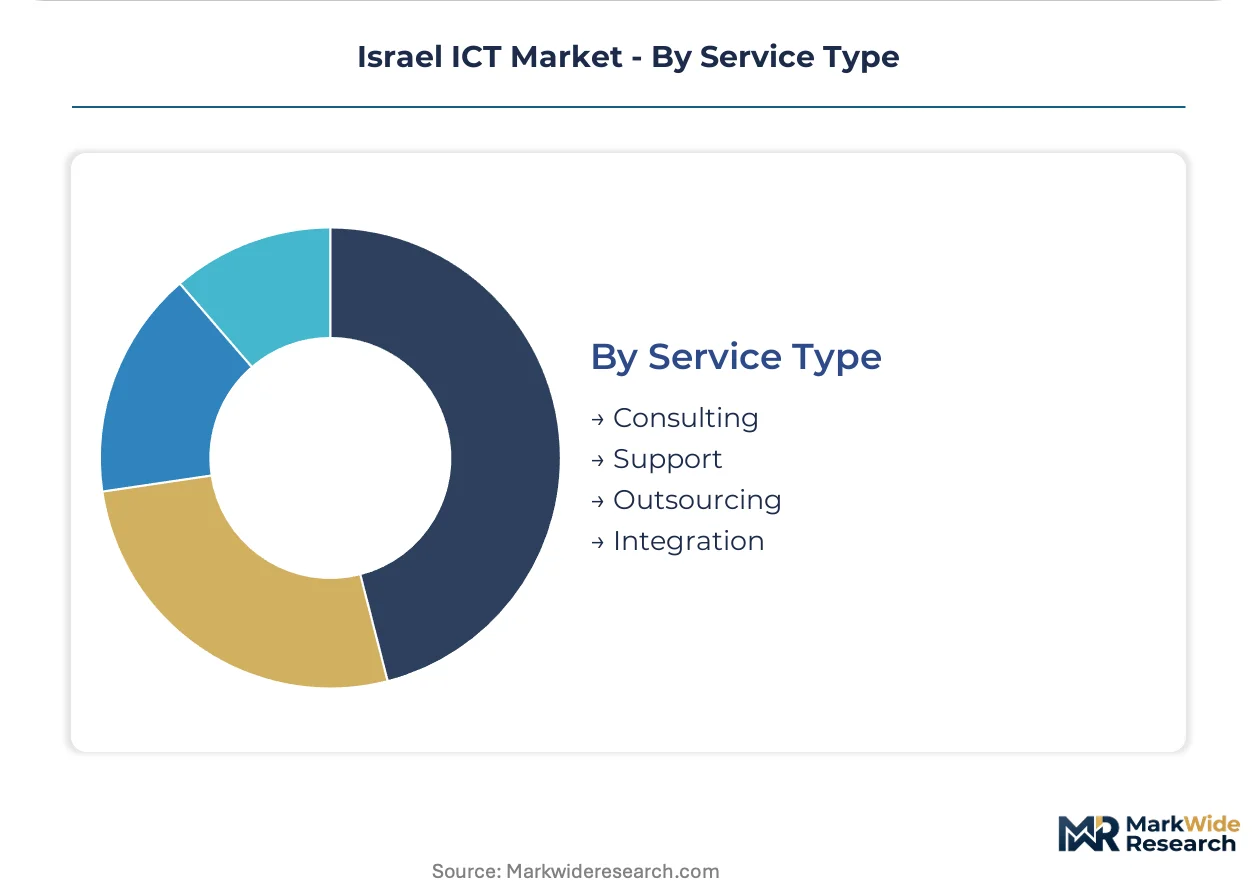
Israel's ICT market segments along four intersecting dimensions that determine procurement patterns and margin capture. Product type and technology selections concentrate in Tel Aviv's venture corridor, while end-user and service type choices diverge between defense-mandated compliance and commercial agility requirements.
Product Type:
Customization intensity varies sharply across this category, with software and cloud services offering configurable deployment models while hardware and networking demand rigid specification adherence.
- Software:Applications span enterprise resource planning, cybersecurity suites, and vertical-specific platforms. Healthcare networks in Jerusalem and Haifa drive demand for HIPAA-aligned electronic record systems with sub-20-millisecond latency requirements. The National Cyber Directorate's binding standards favor domestically audited codebases for critical infrastructure.
- Cloud Services:Hyperscale infrastructure, sovereign cloud regions, and edge computing nodes constitute this segment. Microsoft's Israel Central region anchors foreign capacity, while local providers capture defense-adjacent workloads requiring data residency. Procurement volumes expand as government agencies mandate sovereign data storage for classified operations.
- Hardware:Server infrastructure, storage arrays, and endpoint devices with silicon photonics-enabled interconnects at 400G and above.
- Networking:Packet-switched gear, SD-WAN appliances, and optical transport systems serving Tel Aviv's financial services latency requirements.
Leading the category by volume: Software. Expanding most quickly: Cloud Services.
End User:
Customer archetypes in this category range from procurement-heavy government entities with 18-24 month certification cycles to nimble enterprises seeking consumption-based contracts.
- Enterprise:Financial services, manufacturing, and technology firms constitute the largest revenue base. Tel Aviv's trading floors demand flexible capacity scaling over capital-intensive owned infrastructure. SD-WAN adoption concentrates here as buyers unbundle hardware from managed service commitments.
- Government:Defense agencies, civilian ministries, and critical infrastructure operators with stringent BIS-equivalent certification requirements. Procurement flows through locally audited joint ventures to satisfy National Cyber Directorate mandates for sovereign data residency.
- Healthcare:Hospital networks accelerating electronic record modernization with compliance to domestic cybersecurity frameworks.
- Education:Universities and research institutions driving demand for high-performance compute infrastructure and AI training clusters.
Dominating revenue: Enterprise. Steepest expansion trajectory: Healthcare.
Technology:
Application maturity separates established cybersecurity deployments from experimental blockchain implementations across this category.
- Cybersecurity:Network security, endpoint protection, and threat intelligence platforms absorbing disproportionate R&D capital. Conscription-trained talent pipelines feed defense-adjacent development, leaving commercial roles understaffed and inflating compensation. ISO 27001 and IEC 62443 dual-framework compliance extends sales cycles by 9-14 months.
- AI:Machine learning platforms, autonomous-driving sensor fusion architectures, and edge inference silicon. Mobileye's design leadership migrates into industrial automation and smart city deployments, creating cross-vertical application expansion for Israeli fabless houses.
- IoT:Connected device fleets, industrial sensors, and smart city infrastructure operating at latency thresholds below 20 milliseconds.
- Blockchain:Distributed ledger applications for supply chain traceability and financial settlement with limited production deployment.
Capturing dominant R&D investment: Cybersecurity. Gaining share fastest: AI.
Service Type:
Margin structure in this category inverts with delivery model, with integration and consulting commanding premium pricing against commoditized support.
- Integration:System architecture design, legacy modernization, and multi-cloud orchestration services. Data center operators face stranded asset write-downs on 100G-and-below switching equipment as silicon photonics mandates 400G minimums, creating demand for migration financing and technical debt restructuring.
- Consulting:Compliance advisory, cybersecurity posture assessment, and digital transformation strategy. Proposed amendments to data localization rules force architectural duplication planning between Tel Aviv-centric infrastructure and foreign cloud regions.
- Support:Break-fix maintenance, software updates, and helpdesk operations with standardized service level agreements.
- Outsourcing:Managed infrastructure, security operations centers, and application management delivered through 12-month consumption-based contracts.
Commanding premium pricing: Integration. Growing fastest: Outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's ICT demand concentrates overwhelmingly in the Tel Aviv technology corridor, where venture capital deployment and defense procurement create overlapping infrastructure requirements across a 50-kilometer radius.
Tel Aviv District
Financial services trading floors and AI startup clusters drive hyperscale cloud consumption with sub-20-millisecond latency mandates. The National Cyber Directorate enforces sovereign data residency for critical infrastructure operators. Microsoft's Israel Central region anchors foreign hyperscale capacity in this corridor.
Central District
Defense agencies and government ministries expand secure cloud procurement with BIS-equivalent certification requirements. The Israeli government mandates domestic audit processes for classified workload hosting. Locally incorporated joint ventures capture sovereign cloud contracts in this zone.
Haifa District
Industrial automation and port logistics generate edge-AI silicon demand from autonomous system deployments. The Ministry of Defense prioritizes conscription-trained cybersecurity talent for defense-adjacent roles. Haifa's technology parks concentrate hardware design activity for sensor fusion architectures.
Jerusalem District
Hospital networks accelerate electronic record modernization with HIPAA-aligned cloud infrastructure requirements. The National Cyber Directorate extends binding standards to healthcare critical infrastructure. Medical research institutions in Jerusalem drive demand for high-performance compute clusters.
Southern District
Smart city pilots and renewable energy monitoring create IoT deployment opportunities with latency-sensitive workloads. The Ministry of Energy mandates cybersecurity compliance for power grid digitization. Beersheba's cybersecurity technology park anchors defense-trained talent pipelines.
Israel ICT Market Competitive Landscape
Strategic partnerships dominate the current landscape as foreign hyperscalers align with domestic audit requirements and local specialists capture defense-adjacent procurement. The vendor base separates into three tiers: foreign cloud anchors with sovereign region investments, Israeli-born cybersecurity and AI specialists leveraging conscription-trained talent, and mid-market SD-WAN providers delivering consumption-based networking. M&A activity concentrates on AI talent acquisition, while certification-driven joint ventures address government compliance barriers.
Within the Israeli-born specialist tier, Mobileye and Cato Networks exemplify divergent archetypes: the former anchors autonomous-driving sensor fusion design migrating into industrial edge applications, while the latter occupies a position in cloud-native SD-WAN delivery for mid-market enterprise accounts. Microsoft represents the foreign hyperscale anchor, having established sovereign region infrastructure to satisfy National Cyber Directorate mandates. Riskified and monday.com sit within the SaaS application layer, though their competitive positioning diverges across fraud prevention versus work management verticals.
| Leading Market Players |
|---|
| Mobileye |
| Riskified |
| HiBob |
| Cato Networks |
| Microsoft |
| eToro |
| Snowflake |
| monday.com |
| Others |
Supply & Pricing Matrix
Captive in-house production of sovereign cloud infrastructure anchors supply positioning and pricing power for Israeli ICT vendors serving defense-adjacent segments. The National Cyber Directorate's data residency mandates force architectural choices that concentrate procurement around domestically audited joint ventures, insulating local providers from hyperscale price competition while inflating compliance-driven cost structures.
Pricing Analysis
Volume concentrates in standardized cloud subscriptions while margin pools in integration and consulting services. Three-tier pricing structure across premium, standard, and economy levels separates defense-certified sovereign deployments from commercial SaaS tiers. Price differentiation centers on ISO 27001 and IEC 62443 dual-framework compliance status. Cost compression in mid-market SD-WAN segments is intensifying because consumption-based contracts displace hardware procurement cycles. Government buyers exhibit lowest price sensitivity due to mandated sovereign requirements, while financial services trading floors prioritize latency performance over unit cost.
Supply Chain Analysis
Conscription-trained cybersecurity engineering talent scarcity in Israel concentrates development capacity in defense-adjacent roles, leaving commercial cloud architecture and edge-AI silicon design chronically understaffed. Silicon photonics transceivers draw from concentrated Asian manufacturing bases in Taiwan, Japan, and South Korea for indium phosphide substrates. Optical component sourcing rests on geopolitical friction exposure at key maritime chokepoints. Distribution runs through Tel Aviv's technology corridor venture networks and defense procurement channels, with hyperscale capacity anchored by Microsoft's Israel Central region investments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's ICT market operates as a supply-constrained environment where conscription-trained engineering talent scarcity props pricing for cybersecurity and sovereign cloud specialists. Capacity bottlenecks in certified compliance infrastructure prevent rapid supply response to defense procurement expansion.
For Market Incumbents: Extend sovereign cloud certification coverage into healthcare and energy verticals before regulatory expansion formalizes. Deepen partnerships with hyperscale anchors to secure capacity reservations for classified workload growth. ISO 27001 and IEC 62443 dual-framework pre-certification creates defensive moats against foreign entrants facing 18-24 month audit delays. For New Entrants and Emerging Players: National Cyber Directorate mandates in Israel open a window for locally incorporated joint ventures targeting government cloud procurement. Healthcare electronic record modernization represents the most penetrable vertical, absorbing under 15 percent of domestic ICT capacity with sub-20-millisecond latency requirements. Channel partnership with established managed service providers bypasses direct certification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in defense-adjacent AI talent acquisitions and sovereign cloud infrastructure rollups. Long-term viability favors fabless design houses with cross-vertical edge-AI silicon applications migrating from autonomous driving into industrial automation. Watch silicon photonics supply chain friction as the inflection indicator for data center expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | National Cyber Directorate compliance unlocks defense procurement volumes previously reserved for domestic providers. |
| Edge-AI Silicon Design Expansion | Mobileye's sensor fusion architectures migrate into industrial automation, creating cross-vertical application capture for Israeli fabless houses. |
| SD-WAN Channel Partnership | Cloud-native networking specialists bypass traditional hardware cycles through managed service provider bundles in Tel Aviv financial services. |
| Healthcare Infrastructure Modernization | Hospital networks in Jerusalem and Haifa drive HIPAA-aligned cloud demand with sub-20-millisecond latency specifications. |
| Silicon Photonics Infrastructure Refresh | 400G-and-above interconnect mandates displace copper backplanes, forcing data center operator migration financing and technical debt restructuring. |
Research Methodology
Independent corroboration across primary interviews with cloud architects, defense procurement officers, and venture capital technology investors, combined with secondary validation through National Cyber Directorate policy filings, hyperscaler capex disclosures, and ISO certification registries, underwrites the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across product type, end user, technology, and service type dimensions.
Comparable-period anchoring to historical sovereign cloud deployment cycles and silicon photonics adoption curves structures the projection horizon. The analytical framework models deployment model, organization size, vertical integration complexity, and regional adoption pattern across the analysis window. CAGRs derive from regression against infrastructure investment trajectories and regulatory mandate implementation timelines, with edge-AI silicon design convergence and healthcare digitization velocity as sector-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics at 800G speeds would alter the outlook for data center interconnect economics and copper infrastructure stranded asset exposure. Forecasts reflect assumptions regarding National Cyber Directorate mandate expansion velocity and conscription-trained talent pipeline allocation. Material deviation in Asian optical component supply availability or proposed data localization rule amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Web Analytics Market
Analytics
Text Analytics Market
Analytics
Product Analytics Market
Analytics
Load (ETL) Market
Analytics
Content Analytics Software Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Human Resource Analytics Market
Analytics
US Video Analytics Market
Analytics
Pandemic Analytics Market
Analytics
North America Speech Analytics Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
France Contact Center Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Global Data Prep Market
Analytics
Big Data Analytics Market