
 Graphical Situational Display Market | 2026-2036
Graphical Situational Display Market Size, Share, and Industry Trends Forecast 2026-2036
Graphical Situational Display Market Analytics
MicroLED substrates are displacing legacy LCD backplanes and is recalibrating unit economics across high-brightness situational displays. Honeywell International Inc. leverages captive aerospace supply chains to dominate cockpit HUD deployments. Thales Group anchors European defense contracts through sovereign manufacturing bases in France and the United Kingdom. Garmin Ltd. competes in ruggedized portable segments where military-grade durability commands premium positioning.
Graphical situational displays integrate high-resolution rendering engines with real-time data fusion to present geospatial, tactical, or operational environments to decision-makers; typical systems process refresh rates exceeding 120 Hz with luminance above 800 nits for daylight-readable performance. Monitors and HUDs capture the bulk of current procurement value in defense and aviation end-use, while LED walls are gaining share in joint operations centers requiring immersive theater-style visualization. Data visualization technology underpins command-and-control software layers, though augmented reality overlays represent the fastest-expanding capability set as military operators demand heads-up tactical symbology.
The U.S. Federal Aviation Administration and the European Union Aviation Safety Agency govern display certification for civil air traffic applications, with FAA Technical Standard Orders dictating minimum readability and failure-mode resilience. The U.S. Department of Defense MIL-STD-810 and MIL-STD-461 frameworks mandate environmental hardening and electromagnetic compatibility for field-deployable units. Stakeholders must monitor divergence between civilian certification pathways and sovereign defense procurement standards as export control regimes tighten around dual-use display technologies.
Market Dynamics
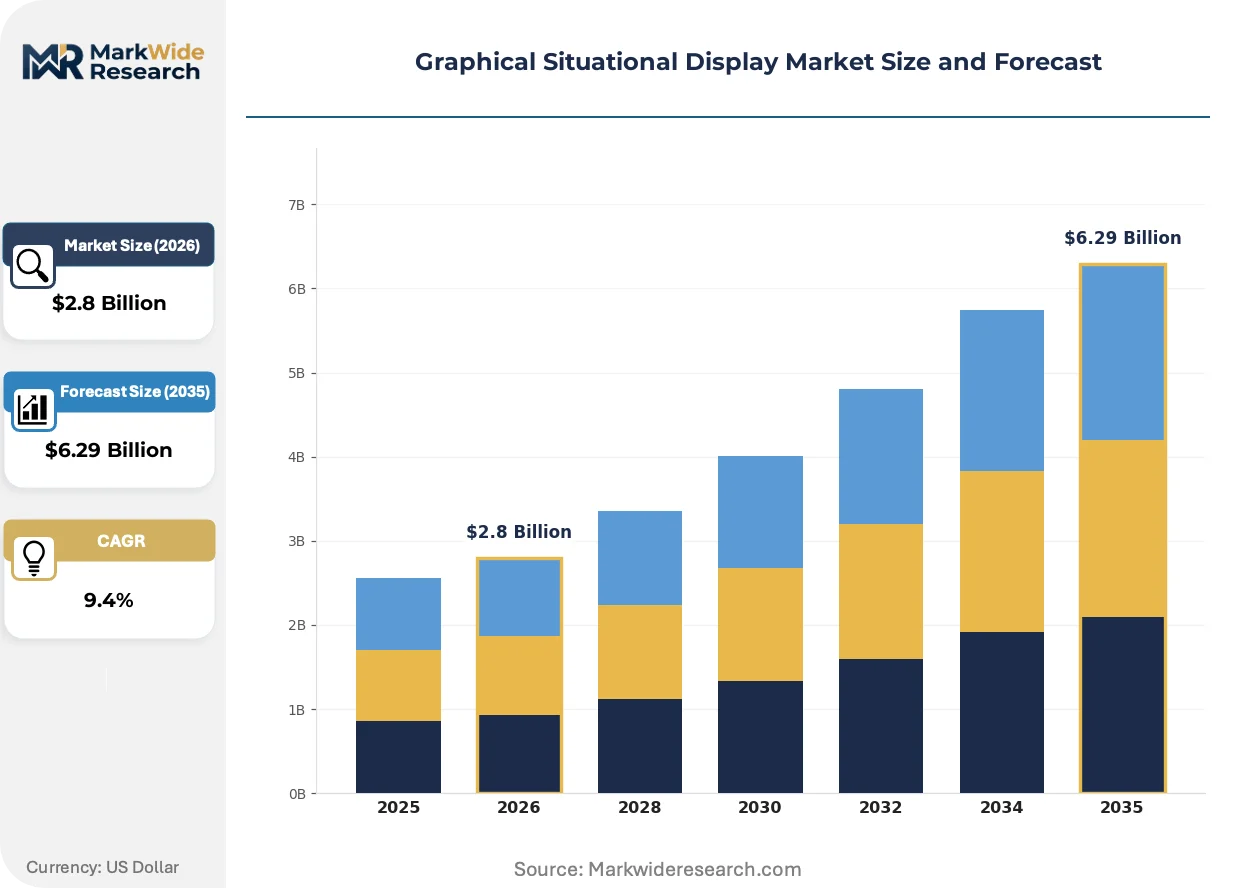
MicroLED substrate migration is compressing manufacturing cost curves while recalibrating procurement priorities across defense and aviation end-users, forcing legacy LCD supply chains into accelerated obsolescence cycles.
Growth Catalysts
- FAA NextGen Mandates:The U.S. Federal Aviation Administration's air traffic control modernization timelines are compelling wholesale display infrastructure replacement across continental radar approach facilities.
- Bundeswehr HUD Procurement:Germany's defense modernization programs are concentrating demand for helmet-mounted and cockpit-integrated graphical situational displays in European procurement pipelines.
- MicroLED Brightness Thresholds:Substrate advances enabling 800+ nits luminance at sub-100W power draw are unlocking daylight-readable deployments previously inaccessible to emissive display technologies.
Market Restraints
- Gallium Substrate Volatility:Concentrated rare earth processing in Chinese supply chains exposes MicroLED foundries to input cost fluctuations and export control friction.
- MIL-STD-810 Hardening Costs:Environmental testing for shock, vibration, and temperature extremes adds 35-50% non-recurring engineering overhead to field-deployable unit economics.
- LCD Amortization Traps:Existing defense platforms with decade-long refresh cycles delay MicroLED adoption despite performance superiority, locking procurement into legacy backplane technologies.
Strategic Opportunities
- Joint Operations LED Walls:Theater-scale immersive visualization in multi-domain command centers represents underpenetrated demand as military operators abandon projector-based briefing systems.
- AR Overlay Convergence:Integration of spatial computing engines with existing HUD architectures creates white space for mixed-reality tactical symbology in rotorcraft and armored vehicle applications.
- EU Defense Fund Alignment:European Defence Fund procurement incentives for sovereign manufacturing are redirecting display subsystem sourcing toward French and UK-based production facilities.
Industry Challenges
- EMC Certification Bottlenecks:MIL-STD-461 electromagnetic compatibility testing queues at accredited facilities extend program schedules by 8-14 months for new display entrants.
- Real-Time Rendering Talent Scarcity:Shortages of engineers proficient in 120Hz+ geospatial data fusion pipelines constrain OEM development velocity for next-generation command-and-control software layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphical Situational Display Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitors, Projectors, LED Walls, HUDs End User: Defense, Air Traffic Control, Transportation, Logistics Technology: Augmented Reality, Virtual Reality, 3D Mapping, Data Visualization Application: Simulation, Training, Real-Time Monitoring, Situational Awareness |
| Companies Covered | Honeywell International Inc., General Dynamics Mission Systems, Thales Group, Rockwell Collins, Northrop Grumman Corporation, Garmin Ltd., Curtiss-Wright Corp., Getac Technology Corp., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphical Situational Display Market Evolving Landscape
Display architectures are bifurcating between ultra-rugged field-deployable units and software-defined visualization layers, with hardware commoditization pressures forcing value migration toward data fusion and rendering engines.
MicroLED epitaxy on silicon substrates is electrifying luminance-per-watt performance curves in high-brightness applications. Defense helicopter operators are adopting the technology for wide-field-of-view helmet displays at replacement rates exceeding fixed-wing platforms. This substrate shift is compressing the cost premium against legacy OLED solutions from 4x to 1.5x across the analysis window.
The European Union Aviation Safety Agency's updated CS-25 cockpit display certification guidelines are mandating failure-mode resilience testing that exceeds prior Technical Standard Order requirements. Airframe integrators must now demonstrate independent display channel redundancy for primary flight instruments. This regulatory tightening is favoring established HUD suppliers with captive aerospace certification expertise over commercial display entrants.
Defense procurement officers are consolidating vendor relationships around integrated subsystem providers capable of delivering display hardware with embedded rendering software and sovereign maintenance infrastructure. Traditional component sourcing through fragmented distributor networks is contracting in favor of sole-source platform contracts. This concentration pattern is most visible in German and UK armored vehicle programs where Rheinmetall and BAE Systems are bundling display subsystems with vehicle electronics architectures.
Graphical Situational Display Market Segmentation
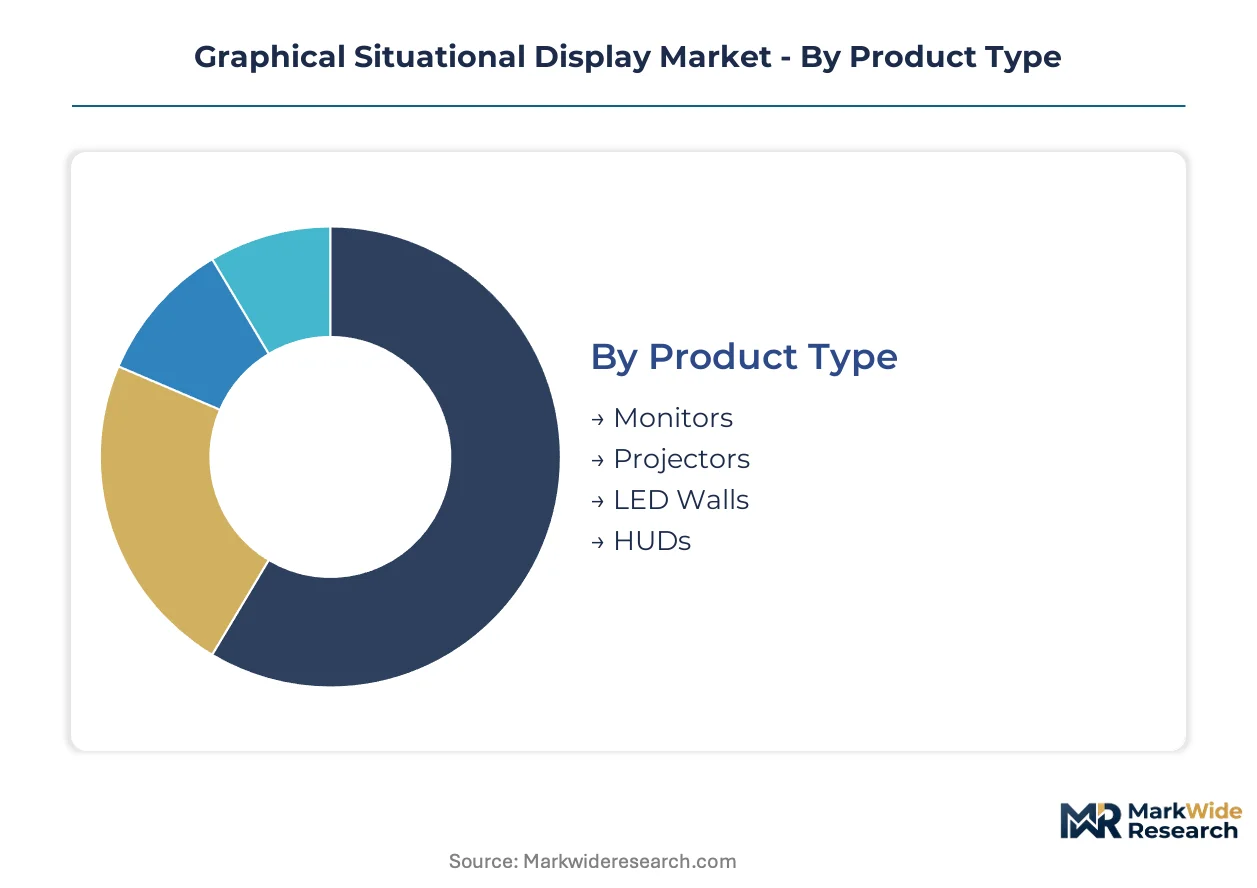
Graphical situational displays serve heterogeneous operational environments where product form factor, end-user mission profile, and rendering technology each dictate divergent procurement specifications. Segmentation reveals how defense command centers prioritize ruggedized hardware while civilian aviation operators emphasize certification compliance and refresh cycle economics.
Product Type:
Monitors and HUDs anchor procurement value in volume terms, while LED walls command premium positioning in immersive theater applications.
- Monitors:Ruggedized LCD and emerging MicroLED backplanes dominate control room installations with 120Hz+ refresh rates and 800+ nits luminance for daylight readability. Defense command centers in Germany and the United States are consolidating procurement around 24-inch to 55-inch rack-mount units with MIL-STD-810 hardening.
- HUDs:Helmet-mounted and cockpit-integrated optical systems project tactical symbology directly into operator sightlines. Bundeswehr modernization programs and FAA NextGen cockpit mandates are concentrating demand for wide-field-of-view architectures in European and North American procurement pipelines.
- LED Walls:Seamless tiled displays enable theater-scale visualization for joint operations centers.
- Projectors:Legacy briefing room installations face displacement pressure from solid-state alternatives.
Mature deployment sits with Monitors across established command-and-control facilities. Newer deployment is concentrated in LED Walls as military operators abandon lamp-based projection systems for immersive briefing environments.
End User:
Defense procurement channels absorb the majority of ruggedized display volume, while air traffic control modernization timelines are compressing replacement cycles in civilian aviation infrastructure.
- Defense:Ground vehicle crews, rotary-wing pilots, and command center operators demand environmental hardening against shock, vibration, and electromagnetic interference. MIL-STD-461 compliance adds 35-50% non-recurring engineering overhead, favoring incumbent suppliers with captive certification expertise.
- Air Traffic Control:FAA Technical Standard Orders and EASA CS-25 guidelines mandate failure-mode resilience with independent display channel redundancy for primary flight instruments. Radar approach facilities across the United States face compelled infrastructure replacement under NextGen timelines.
- Transportation:Rail and maritime operators adopt commercial-grade ruggedization for fleet dispatch centers.
- Logistics:Warehouse and distribution command posts prioritize cost-optimized visualization for inventory tracking.
Defense procurement concentrates in sole-source platform contracts bundling hardware with sovereign maintenance infrastructure. Air Traffic Control adoption is climbing fastest where regulatory mandates override legacy amortization cycles.
Technology:
Data visualization underpins current command-and-control software layers, while augmented reality overlays are gaining share as military operators demand heads-up tactical symbology.
- Data Visualization:Geospatial rendering engines fuse radar, sensor, and intelligence feeds into 2D and 3D operational pictures. Real-time data fusion pipelines processing 120Hz+ refresh rates require specialized engineering talent that constrains OEM development velocity.
- Augmented Reality:Spatial computing engines overlay tactical symbology onto physical environments through HUD and helmet-mounted architectures. Helicopter operators are adopting MicroLED-enabled wide-field-of-view systems at replacement rates exceeding fixed-wing platforms.
- 3D Mapping:Terrain and urban modeling supports mission planning and rehearsal applications.
- Virtual Reality:Fully immersive environments enable cost-effective training simulation without operational platform wear.
Data Visualization anchors procurement in established command centers with decade-long refresh cycles. Augmented Reality is expanding most quickly in rotorcraft and armored vehicle applications where heads-up operational awareness reduces cognitive load.
Application:
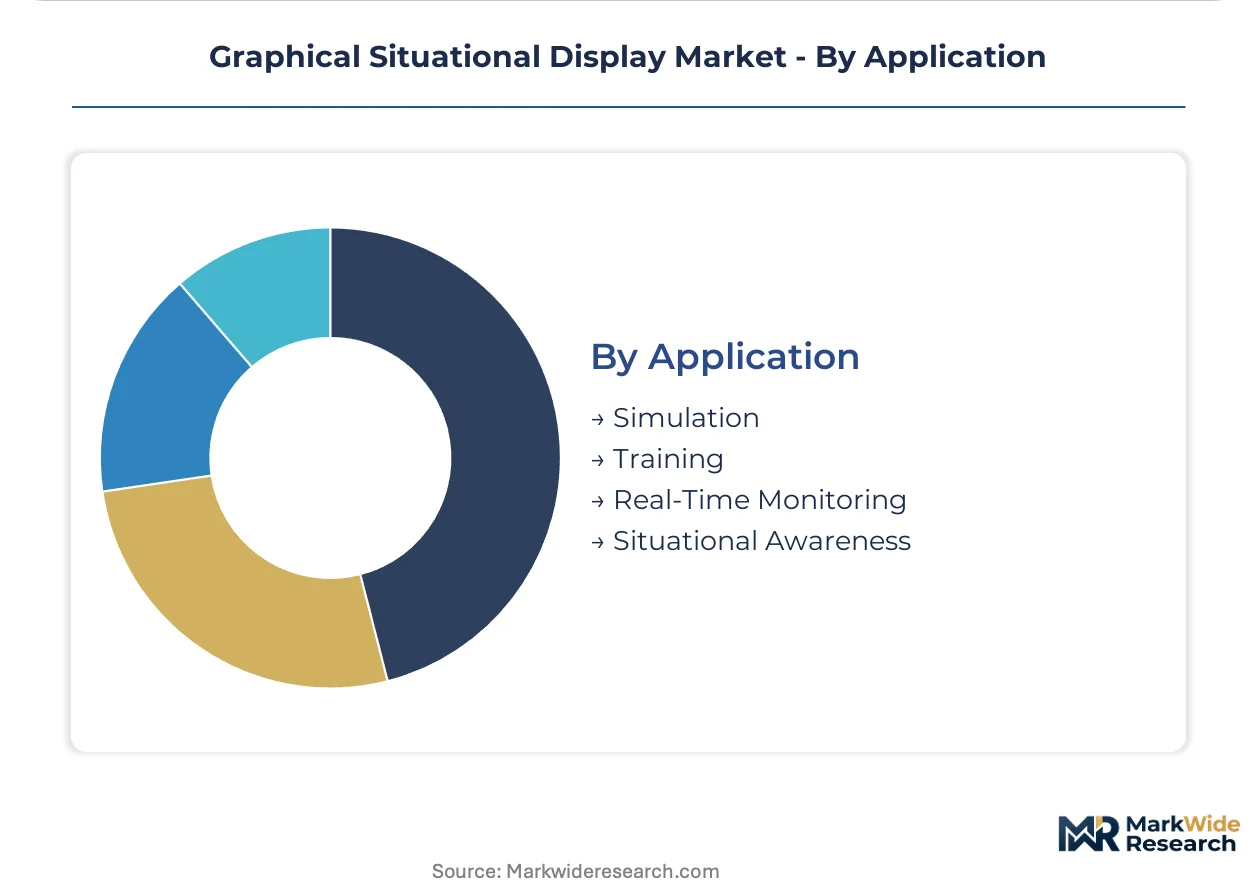
Real-time monitoring captures the majority of deployed display hours, while simulation and training applications are displacing live platform operations for cost and safety reasons.
- Real-Time Monitoring:Continuous operational picture maintenance for air defense, border surveillance, and traffic management requires 99.999% availability with hot-standby redundancy. Procurement prioritizes failure-mode resilience over incremental performance improvements.
- Simulation:Synthetic training environments replicate tactical scenarios without fuel consumption, platform wear, or personnel risk. German and UK armored vehicle programs are bundling display subsystems with vehicle electronics architectures for integrated training capability.
- Training:Classroom and field instruction applications emphasize portability and rapid deployment.
- Situational Awareness:Individual operator displays for dismounted soldiers and vehicle crews prioritize weight and power efficiency.
Real-time Monitoring dominates installed base across defense and aviation infrastructure. Simulation is gaining share fastest as procurement officers optimize total ownership costs through synthetic training substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen Special Economic Zone concentrates MicroLED substrate manufacturing capacity, drawing defense and aviation display suppliers into Guangdong Province's electronics corridor. Tax incentives for advanced semiconductor packaging accelerate foundry co-location near Hong Kong's port infrastructure.
United States
FAA NextGen mandates compel radar approach facility upgrades across continental airspace, with Technical Standard Orders dictating minimum readability standards. The Department of Defense MIL-STD-810 and MIL-STD-461 frameworks govern environmental hardening for field-deployable units. Greater Washington DC hosts defense command centers procuring augmented reality overlays for battlefield visualization.
Germany
Bundeswehr modernization programs drive helmet-mounted and cockpit-integrated display procurement through Rheinmetall-led vehicle electronics architectures. The country's national defense procurement office channels sovereign manufacturing requirements toward domestic production facilities. Bavaria anchors HUD development clusters serving European armored vehicle programs.
France
Thales Group leverages sovereign manufacturing bases to anchor European defense contracts for wide-field-of-view helmet systems. The European Defence Fund redirects display subsystem sourcing toward French and UK-based production under procurement incentives. Paris-Saclay research corridors advance spatial computing engines for tactical symbology integration.
United Kingdom
BAE Systems bundles display subsystems with armored vehicle electronics in sole-source platform contracts consolidating vendor relationships. The Ministry of Defence's procurement standards diverge from civilian certification pathways as export controls tighten. South West England clusters aerospace HUD suppliers with captive certification expertise.
Japan
METI industrial policy supports domestic display panel production for defense and aviation applications, reducing import dependency for critical subsystems. JIS standards govern commercial-grade ruggedization specifications for rail and maritime dispatch centers. Kyushu manufacturing corridors process rare earth inputs for MicroLED epitaxy operations.
Graphical Situational Display Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring integrated subsystem providers while commercial aviation channels fragment among certification-focused suppliers. The vendor base concentrates around three strategic archetypes: aerospace incumbents with captive supply chains, defense electronics integrators bundling hardware with sovereign maintenance infrastructure, and ruggedized portable specialists commanding premium positioning in military-grade durability segments. M&A activity targets rendering software capabilities as hardware commoditization pressures mount, while strategic partnerships lock in gallium substrate supply against Chinese processing concentration risks.
Among US-based aerospace and defense conglomerates, Honeywell International Inc. and Northrop Grumman Corporation exemplify the integrated subsystem archetype, occupying positions where captive certification expertise and established MIL-STD testing relationships create defensive moats. Thales Group anchors the European sovereign manufacturing tier, representing the model of defense fund alignment and national production base leverage that procurement officers increasingly mandate.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| General Dynamics Mission Systems |
| Thales Group |
| Rockwell Collins |
| Northrop Grumman Corporation |
| Garmin Ltd. |
| Curtiss-Wright Corp. |
| Getac Technology Corp. |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
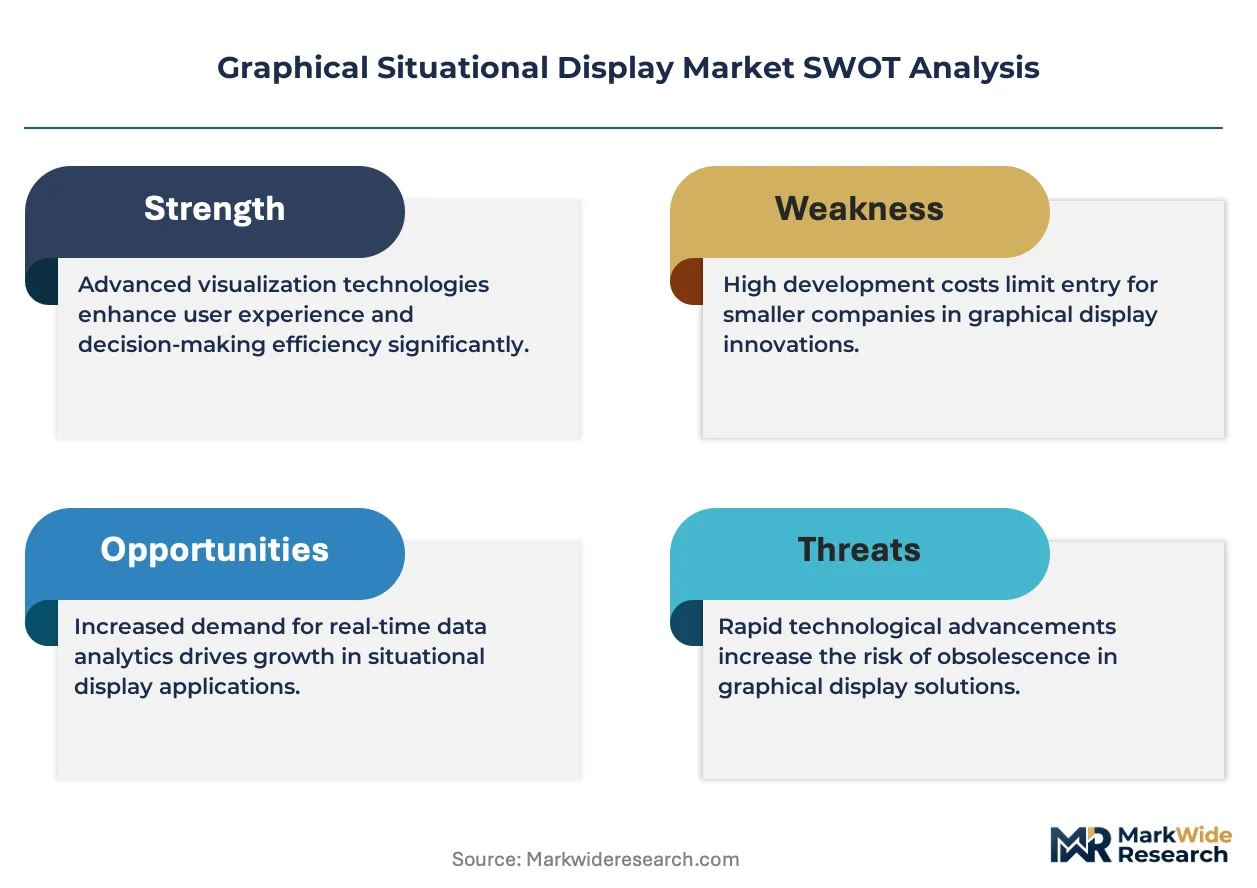
Gallium substrate spot price volatility cascades through MicroLED foundry cost structures into three-tier pricing stratification across defense-grade, aviation-certified, and commercial-rugged display tiers. Chinese rare earth processing concentration amplifies input cost uncertainty, forcing OEMs to index long-term supply agreements against commodity benchmarks while spot buyers absorb margin compression.
Pricing Analysis
Lead-time premiums compress standard delivery schedules by 40-60% for urgent MIL-STD-810 certification queues, while spot inventory of LCD backplanes trades at discount to clear obsolescence risk. Project-based contracting dominates, with price differentiation hinging on certification tier (FAA Technical Standard Order versus MIL-STD-461) and sovereign manufacturing requirements. Cost compression in commercial-rugged segments intensifies as MicroLED epitaxy scales, though defense-grade units maintain pricing power through captive certification expertise. Air traffic control procurement officers exhibit lowest price sensitivity due to regulatory mandate urgency, while logistics dispatch centers prioritize cost-optimized visualization.
Supply Chain Analysis
Freight cost spikes from Guangdong Province to European defense integrators have compressed landed cost advantages for Shenzhen-based MicroLED substrate producers. Supply concentrates in China, Germany, and the United States, with gallium nitride wafers and silicon backplanes feeding from concentrated rare earth processing corridors. Single-source vulnerability in Chinese gallium refining exposes foundries to export control friction. Distribution runs through sole-source platform contracts bundling hardware with sovereign maintenance infrastructure, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures favor integrated subsystem providers as hardware commoditization and certification bottlenecks force component specialists toward acquisition or exit. MicroLED substrate migration accelerates this Darwinian sorting.
For Market Incumbents: To counter gallium supply concentration risk, Honeywell and Thales should deepen backward integration into rare earth refining partnerships in Australia and Canada. Captive aerospace certification expertise remains the defensive moat; incumbents must harden this advantage through accelerated FAA-EASA dual certification investments before regulatory divergence widens. For New Entrants and Emerging Players: EU Defense Fund procurement incentives in France and Germany open a window for sovereign manufacturing plays in armored vehicle HUD bundling. Joint operations LED walls represent the most penetrable white space, with theater-scale immersive visualization displacing projector-based briefing systems at replacement rates exceeding other segments. Target sole-source platform contracts through vehicle electronics architecture partnerships rather than component sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor rendering software specialists with 120Hz+ geospatial data fusion capabilities in the United States and United Kingdom. Long-term viability hinges on five-to-ten year defense modernization budget trajectories rather than commercial aviation cyclicality. Watch MicroLED cost-parity milestones against legacy OLED as the inflection signal for portfolio rebalancing toward substrate-integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gallium Refining | Secures rare earth supply chains against Chinese export control volatility for MicroLED foundries. |
| FAA-EASA Dual Certification Investment | Accelerates market access across Atlantic aviation procurement pipelines under diverging regulatory timelines. |
| Rendering Software Acquisition | Captures value migration from commoditized hardware toward data fusion and spatial computing engines. |
| Sovereign Manufacturing Facility Establishment | Aligns with EU Defense Fund procurement incentives redirecting display subsystem sourcing. |
| Joint Operations LED Wall Platform Launch | Displaces projector-based briefing systems in multi-domain command centers requiring immersive theater visualization. |
Research Methodology
Independent corroboration across defense procurement officers, aviation certification engineers, and MicroLED foundry operations directors underwrites the qualitative findings. Primary interviews with HUD system architects, electromagnetic compatibility testing facility managers, and sovereign manufacturing program executives combined with secondary validation from FAA Technical Standard Order filings, EASA CS-25 certification databases, and Bundeswehr procurement disclosure records. Bottom-up unit economics triangulate against top-down defense budget appropriation analysis.
Comparable-period anchoring to historical refresh cycle data across aviation and defense infrastructure underpins the projection framework. The analysis window models segmentation across product type (monitors, HUDs, LED walls), end user (defense, air traffic control, transportation), and technology (data visualization, augmented reality). CAGRs derive from installation base replacement rates overlaid with regulatory mandate compulsion effects. MicroLED luminance-per-watt improvement curves and MIL-STD-810 hardening cost trajectories inform technology adoption pathway assumptions.
The model assumes a particular technology adoption path; alternative pathways for MicroLED substrate migration would alter the outlook if LCD amortization traps persist longer than projected. Forecasts reflect assumptions about defense modernization budget continuity and FAA NextGen timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Game Engines Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Canada ICT Market
Digital Solutions
Web Performance Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Social Computing Market
Digital Solutions
Kenya ICT Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Hyperlocal Services Market